
 Chocolate Flavors Market | 2026-2036
Chocolate Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Flavors Market Analysis
Specialty foodservice distribution is rewriting procurement patterns for chocolate flavor suppliers. Barry Callebaut leverages its integrated cocoa processing network to secure bean-to-liquid supply contracts across Europe. Puratos Group anchors its position through R&D intensity in tailored chocolate compounds for industrial bakeries. Nestlé SA competes via brand strength in premium chocolate flavor formulations for retail confectionery.
Chocolate flavors comprise concentrated cocoa-derived aromatic compounds, typically standardized at 5-15% fat content and 20-50% cocoa solids, manufactured through conching, alkalization, or enzymatic extraction to deliver consistent taste profiles across food applications. Dark chocolate formulations dominate ingredient-grade demand due to higher cocoa polyphenol content and cleaner-label positioning in health-oriented products. Liquid chocolate and chocolate coatings within the formulation segment represent the fastest-growing structural categories, driven by automation compatibility in industrial bakery and confectionery lines. Milk chocolate maintains maturity in mass-market confectionery, though margin pools increasingly shift toward ruby chocolate and single-origin dark variants targeting specialty retail channels.
FDA food additive regulations and EFSA cocoa contaminant thresholds shape permissible processing methods and residue limits for chocolate flavor imports into the United States and European Union. BIS standards in India and GB standards in China impose additional compositional requirements that segment market access for international suppliers. Stakeholders must monitor evolving clean-label enforcement trajectories and origin-certification schemes to anticipate which flavor extraction technologies will secure regulatory preference across priority export markets.
Market Dynamics
Clean-label enforcement under EFSA and FDA frameworks is compressing permissible extraction chemistries and accelerating capital redeployment toward enzymatic and supercritical CO2 processing infrastructure across supplier networks.
Growth Catalysts
- EFSA Contaminant Thresholds:Stricter cadmium and lead limits in cocoa derivatives are filtering out artisanal processors and consolidating volume with industrial-scale alkalization and conching operators capable of certifiable traceability.
- Specialty Foodservice Expansion:Artisanal bakeries and third-wave coffee chains in Belgium, Switzerland, and France are contracting for single-origin liquid chocolate compounds with defined polyphenol retention specifications.
- Enzymatic Extraction:Cell-wall degrading enzyme protocols are recovering aromatic fractions at lower thermal load, preserving volatile pyrazines and esters that conventional roasting destroys.
Market Restraints
- Cocoa Butter Price Volatility:Butter futures on ICE and NYMEX expose compound manufacturers to margin compression when fat content specifications lock in contract terms ahead of harvest cycles.
- West African Supply Concentration:Ivory Coast and Ghana processing clusters concentrate bean sourcing, creating political risk exposure and freight cost spikes during regional instability.
- Alkalization Residue Limits:FDA Title 21 restrictions on potassium carbonate carryover constrain Dutch-process flavor intensity in US-bound ingredient shipments.
Strategic Opportunities
- Indian Industrial Bakery Segment:FSSAI harmonization with CODEX standards is opening formulation partnerships for tailored milk chocolate compounds in packaged biscuit and ice cream applications.
- Ruby Chocolate Positioning:Barry Callebaut's proprietary cultivar delivers fruit-forward profiles without added flavorants, creating premium positioning in confectionery and frozen dessert lines.
- Direct-to-Manufacturer Digital Platforms:B2B procurement portals are disintermediating traditional flavor distributors and enabling volume-customized compound orders with 72-hour fulfillment windows.
Industry Challenges
- Flavor Chemist Talent Scarcity:Retention of specialists capable of bridging cocoa biochemistry and industrial scale-up is tightening as food science programs pivot toward plant protein and alternative fat research.
- Legacy ERP Integration:Batch traceability requirements for EUDR deforestation compliance are forcing mid-tier processors to replace decade-old MRP systems with cloud-native platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Flavors Market |
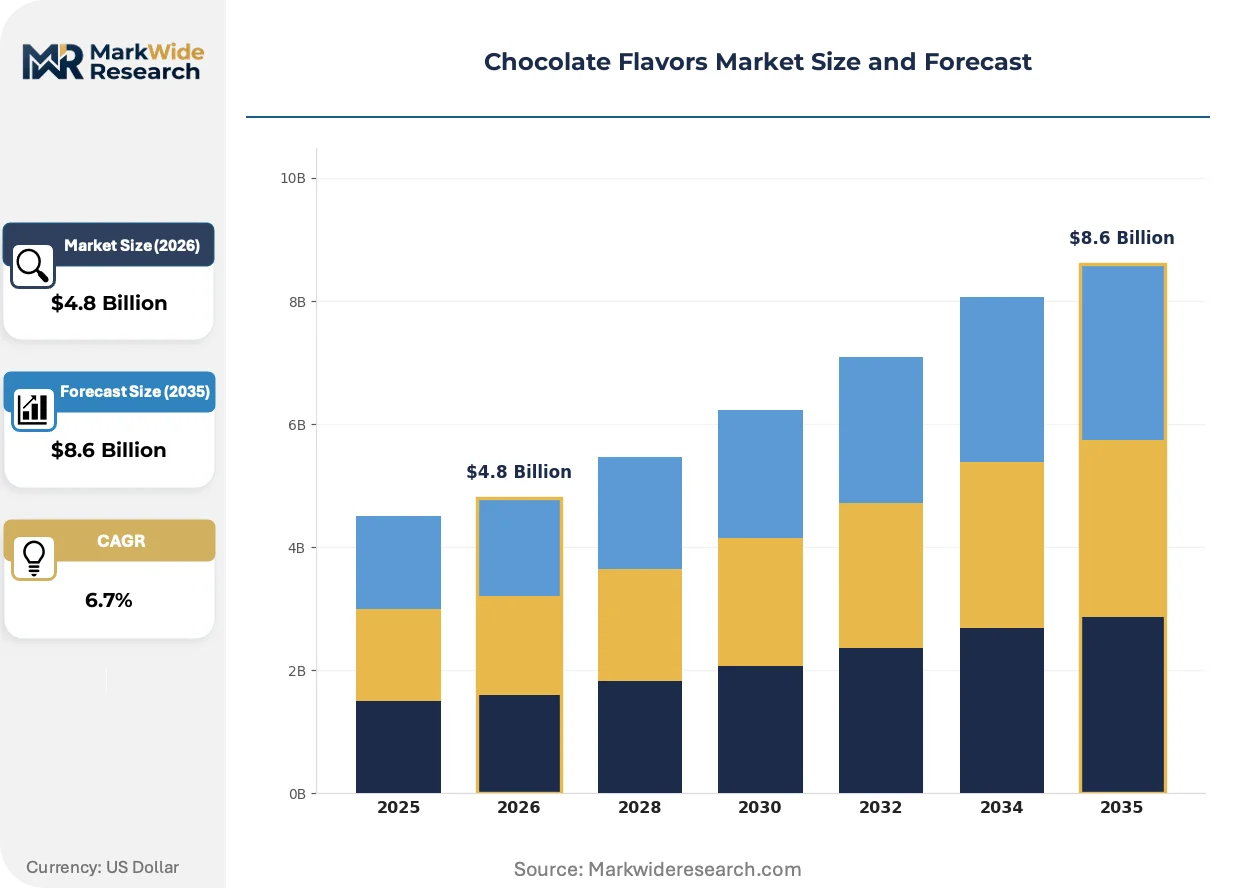
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Formulation: Chocolate Bars, Liquid Chocolate, Chocolate Coatings, Chocolate Chips Use Case: Baking, Confectionery, Food Services, Ingredient Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Foodservice |
| Companies Covered | Mondelēz International, Lindt & Sprüngli, Barry Callebaut, Fuji Oil Holdings Inc., Puratos Group, Nestlé SA, Ferrero Group, Godiva Chocolatier, Mars, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Flavors Market Emerging Trajectories
Digital twin modeling of conching parameters and blockchain-anchored origin documentation are compressing development cycles and reconfiguring buyer qualification protocols across ingredient procurement functions.
Supercritical CO2 extraction is virtualizing traditional solvent-based aromatic recovery by decoupling flavor concentration from thermal degradation pathways. Industrial chocolate compound manufacturers in Switzerland and Belgium are piloting these systems for high-value single-origin lines. The technology is virtualizing capital allocation toward modular processing units that retrofit existing alkalization infrastructure rather than greenfield construction.
EFSA's evolving guidance on novel food definitions for enzymatically modified cocoa extracts is forcing reformulation roadmaps across European suppliers. The regulatory friction is accelerating R&D partnerships between flavor houses and enzyme technology providers to secure pre-market safety dossiers. Dark chocolate ingredient categories face the steepest compliance burden given their positioning in functional food applications where polyphenol content claims trigger additional scrutiny.
Buyer consolidation among multinational confectionery and bakery groups is compressing supplier qualification timelines and unbundling technical service from compound pricing. Procurement functions now separate base chocolate supply from application-specific formulation support, awarding latter contracts to specialized R&D service providers. This bifurcation is most advanced in Germany and the Netherlands where industrial bakery automation rates exceed regional averages and line integration demands precise viscosity and tempering specifications.
Chocolate Flavors Market Segmentation
Chocolate flavor procurement patterns diverge sharply across formulation types and end-use channels. Industrial buyers prioritize viscosity stability and automation compatibility over aromatic complexity, while specialty foodservice operators negotiate for single-origin traceability and defined polyphenol specifications.
Flavor Type:
Dark chocolate and milk chocolate formulations turn inventory fastest in industrial bakery contracts with 90-day procurement cycles, while ruby chocolate and single-origin dark variants sit in longer development pipelines with 12-18 month qualification timelines.
- Dark Chocolate:Higher cocoa polyphenol content delivers cleaner-label positioning for health-oriented applications. Demand concentrates in Belgian and Swiss heritage processing clusters where EFSA contaminant thresholds favor alkalization operators with certifiable traceability systems.
- Milk Chocolate:Standardized at 5-15% fat content with 20-50% cocoa solids for consistent mass-market performance. Volume concentrates in packaged biscuit and ice cream applications across India as FSSAI harmonization with CODEX standards opens formulation partnerships.
- White Chocolate:Cocoa butter base without cocoa solids requires precise tempering specifications for coating applications. European industrial bakeries specify this grade for visual contrast in filled products.
- Ruby Chocolate:Barry Callebaut's proprietary cultivar delivers fruit-forward profiles through natural precursors. Premium positioning in confectionery and frozen dessert lines commands extended payment terms and exclusive territory arrangements.
Milk chocolate dominates installed base across mass-market confectionery. Dark chocolate and ruby variants are where expansion concentrates in specialty retail and functional food positioning.
Formulation:
Cost tier stratification separates commodity-grade chocolate bars from precision-engineered liquid compounds, with coating formulations occupying the mid-tier where automation compatibility drives specification intensity.
- Liquid Chocolate:Pumpable viscosity profiles engineered for continuous depositing lines in industrial bakery automation. Demand concentrates in Germany and the Netherlands where line integration demands precise tempering specifications and 72-hour fulfillment windows.
- Chocolate Coatings:Fat bloom-resistant formulations for enrobing operations with defined snap and mouthfeel parameters. Belgian and Swiss specialty cafes contract for single-origin variants with defined aromatic retention.
- Chocolate Bars:Standard solid formats for retail confectionery and ingredient breaking. Mass-market positioning faces margin compression from cocoa butter futures volatility on ICE and NYMEX.
- Chocolate Chips:Dimensional stability specifications for baking applications requiring heat resistance without excessive spread. North American cookie and muffin manufacturers specify this grade in volume contracts.
Chocolate bars dominate installed base in retail confectionery. Liquid chocolate and coatings are where expansion concentrates as foodservice automation accelerates.
Use Case:
Application-driven specification intensity separates commodity ingredient buyers from technical service-dependent formulators, with foodservice operators demanding the most intensive application support.
- Confectionery:Precision tempering and fat bloom control for molded and enrobed products. EFSA novel food definitions for enzymatically modified extracts trigger additional scrutiny for functional positioning claims.
- Baking:Heat-stable formulations with defined pH tolerance for chemical leavening systems. Industrial biscuit manufacturers in India specify tailored milk chocolate compounds under evolving BIS compositional requirements.
- Food Services:Artisanal bakeries and third-wave coffee chains in Belgium, Switzerland, and France contract for single-origin liquid compounds with defined polyphenol retention. Procurement separates base supply from application-specific formulation support.
- Ingredient:Standardized cocoa-derived aromatic compounds for downstream processing. FDA Title 21 restrictions on potassium carbonate carryover constrain Dutch-process flavor intensity in US-bound shipments.
Confectionery dominates installed base in value terms. Food services are where expansion concentrates as specialty channel procurement professionalizes.
Distribution Channel:
Customer-type concentration separates high-volume supermarket contracts from relationship-intensive specialty store placements, with digital platforms disintermediating traditional flavor distributors.
- Foodservice:Direct-to-manufacturer digital platforms enable volume-customized compound orders with compressed fulfillment windows. Procurement functions unbundle technical service from compound pricing in Germany and the Netherlands.
- Specialty Stores:Curated single-origin and ruby chocolate positioning for premium retail. Belgian and Swiss heritage clusters sustain innovation pipelines through direct relationships with processing operators.
- Supermarkets:Mass-market milk chocolate and standard dark formulations for retail confectionery. Volume contracts lock in fat content specifications ahead of harvest cycles, exposing margins to cocoa butter price volatility.
- Online Retail:Direct-to-consumer channels for premium and gift-positioned chocolate flavors. Ruby chocolate and single-origin dark variants target specialty buyers through platform-specific merchandising.
Supermarkets dominate installed base in volume throughput. Foodservice and online retail are where expansion concentrates as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian and Swiss processors command 40-60% pricing premiums over Indian and Brazilian suppliers for comparable cocoa solids specifications, reflecting heritage processing infrastructure and EFSA-aligned traceability systems that lower buyer compliance costs.
Belgium
Artisanal bakeries in Brussels and Antwerp contract for single-origin liquid compounds with defined polyphenol retention specifications. EFSA cadmium and lead thresholds for cocoa derivatives favor industrial-scale alkalization operators with certifiable bean-to-bar traceability. The Flanders chocolate processing cluster sustains innovation pipelines through direct relationships between heritage manufacturers and third-wave coffee chains.
Switzerland
Specialty cafes in Zurich and Geneva source ruby chocolate and single-origin dark variants with exclusive territory arrangements. Swissmedic-aligned quality frameworks exceed baseline CODEX standards, creating regulatory preference for domestic processors in premium confectionery procurement. The Lake Geneva corridor anchors R&D intensity in tailored chocolate compounds for industrial automation compatibility.
Germany
Industrial bakery automation in Bavaria and North Rhine-Westphalia demands precise viscosity and tempering specifications for continuous depositing lines. KBA-adjacent food safety enforcement harmonizes with EU-wide EUDR deforestation compliance requirements, forcing cloud-native ERP upgrades among mid-tier processors. The Cologne-Düsseldorf corridor concentrates procurement digitization with 72-hour fulfillment windows for volume-customized compounds.
India
Packaged biscuit and ice cream manufacturers in Maharashtra and Gujarat specify tailored milk chocolate compounds under evolving FSSAI harmonization with CODEX standards. BIS compositional requirements segment market access for international suppliers lacking localized formulation partnerships. The Mumbai-Pune industrial corridor attracts joint ventures between European flavor houses and domestic dairy processors.
United States
North American cookie and muffin manufacturers specify chocolate chips with dimensional stability for heat resistance without excessive spread. FDA Title 21 restrictions on potassium carbonate carryover constrain Dutch-process flavor intensity in US-bound ingredient shipments. The Chicago-Milwaukee processing belt concentrates compound manufacturing for retail confectionery volume contracts.
Chocolate Flavors Market Vendor Landscape
Integrated cocoa processors and specialized flavor houses split the market between bean-to-liquid supply security and application-specific formulation agility. The vendor base concentrates around heritage European clusters with captive bean sourcing and Asian-Pacific compound manufacturers serving cost-sensitive industrial bakery segments. Two strategic archetypes dominate: vertically integrated grinders with African bean origination networks, and R&D-intensive formulators with patented extraction technologies. Competitive moves center on enzymatic processing infrastructure deployment and direct-to-manufacturer digital platform development.
Among Swiss- and Belgian-based heritage processors, Barry Callebaut and Lindt & Sprüngli exemplify the integrated grinding archetype with bean origination networks concentrated in West African supply clusters. Puratos Group occupies a position within the specialized formulation tier, anchoring R&D service capabilities for industrial bakery automation requirements. Nestlé SA represents the multinational brand-owner archetype, leveraging retail confectionery channel strength to secure preferred supplier status for premium flavor formulations. These three companies collectively illustrate the strategic segmentation between upstream supply security and downstream application support.
| Leading Market Players |
|---|
| Mondelēz International |
| Lindt & Sprüngli |
| Barry Callebaut |
| Fuji Oil Holdings Inc. |
| Puratos Group |
| Nestlé SA |
| Ferrero Group |
| Godiva Chocolatier |
| Mars, Incorporated |
| Others |
Supply Flow & Price Mechanics
West African bean origination in Ivory Coast and Ghana anchors upstream supply concentration, concentrating margin pools with European alkalization operators capable of certifiable traceability under EFSA contaminant thresholds. Belgian and Swiss processors command substantial premiums over Indian and Brazilian competitors for comparable cocoa solids specifications, reflecting heritage infrastructure and compliance systems that lower buyer qualification costs.
Pricing Analysis
Configured-to-order pricing for single-origin liquid compounds with defined polyphenol retention commands substantial premiums over standard milk chocolate formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and automation compatibility, with ruby chocolate and enzymatically extracted variants occupying the premium tier. Pricing pressure stems from cocoa butter futures volatility on ICE and NYMEX, which exposes compound manufacturers to margin compression when fat content specifications lock in ahead of harvest cycles. Industrial bakery buyers in Germany and the Netherlands exhibit highest price sensitivity due to volume procurement and unbundled technical service contracts, while specialty foodservice operators in Belgium and Switzerland prioritize traceability over unit cost.
Supply Chain Analysis
EU deforestation regulation and EUDR traceability requirements function as de facto export controls, filtering market access for processors lacking blockchain-anchored origin documentation. Geographic supply concentration centers on Ivory Coast and Ghana for bean sourcing, Switzerland and Belgium for alkalization and conching, and India for cost-compound manufacturing. Raw material dependencies include cocoa butter, cocoa liquor, and enzymatic processing agents. Single-source vulnerability runs through West African political risk exposure and freight cost spikes during regional instability. Distribution runs through direct-to-manufacturer digital platforms that disintermediate traditional flavor distributors and enable volume-customized compound orders with compressed fulfillment windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-manufacturer digital platforms are reconfiguring procurement economics around platform intermediation, with B2B portals unbundling technical service from compound pricing and compressing supplier qualification timelines.
For Market Incumbents: Harden bean-to-liquid supply security through backward integration into West African origination networks, securing certifiable traceability systems ahead of EUDR compliance deadlines. Consolidate enzymatic processing infrastructure deployment to defend against specialty competitors capturing premium positioning in single-origin and ruby chocolate segments. Prioritize cloud-native ERP upgrades to maintain batch traceability credentials under evolving EFSA contaminant thresholds. For New Entrants and Emerging Players: India's industrial bakery segment offers the most penetrable white-space target, where FSSAI harmonization with CODEX standards is opening formulation partnerships for tailored milk chocolate compounds in packaged biscuit and ice cream applications. Target precision viscosity specifications for automation-compatible liquid chocolate as the entry wedge, leveraging 72-hour fulfillment windows to differentiate from heritage processors with longer lead times. Deploy direct-to-manufacturer digital platforms as the primary go-to-market angle to bypass established distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier compound manufacturers possessing enzymatic extraction capabilities but lacking integrated origination networks. Long-term viability in this market hinges on regulatory compliance infrastructure and R&D service bundling rather than commodity scale alone. Watch EFSA novel food guidance on enzymatically modified cocoa extracts as the critical inflection signal, with pre-market safety dossier approvals determining which processing technologies secure premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Infrastructure Deployment | Cell-wall degrading enzyme protocols recover aromatic fractions at lower thermal load, preserving volatile pyrazines for premium positioning. |
| Backward Integration into West African Origination | Captive bean sourcing secures certifiable traceability systems required under EUDR deforestation compliance and EFSA contaminant thresholds. |
| Direct-to-Manufacturer Digital Platform Launch | B2B procurement portals disintermediate traditional distributors and enable volume-customized compound orders with compressed fulfillment windows. |
| Cloud-Native ERP System Implementation | Batch traceability requirements for EUDR compliance force replacement of legacy MRP systems among mid-tier processors. |
| Ruby Chocolate Production Scale-Up | Barry Callebaut's proprietary cultivar delivers fruit-forward profiles without added flavorants, creating premium positioning in confectionery lines. |
Methodological Framework
Desk research of customs and trade data, EFSA and FDA regulatory filings, and cocoa futures market records preceded structured interviews with flavor chemists, industrial bakery procurement managers, specialty foodservice operators, and enzymatic processing technology providers. Primary fieldwork combined telephone and video interviews with supply chain executives at heritage European processors and emerging Indian compound manufacturers. Secondary validation drew from BIS compositional standards, FSSAI harmonization documents, and SEC filings of publicly traded confectionery groups. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Assumptions held fixed include EFSA contaminant thresholds and FDA Title 21 alkalization residue limits, while cocoa butter price volatility and West African supply disruption scenarios were stress-tested. The analytical framework modeled flavor type, formulation structure, end-use application, and distribution channel as primary segmentation dimensions. CAGRs were derived from regression analysis of historical procurement patterns and projected automation adoption curves in industrial bakery segments. Forecast inputs included enzymatic extraction technology penetration rates and digital platform adoption timelines among mid-tier processors.
Macroeconomic conditions sit as an overlay; deviation in cocoa commodity prices, freight rates, or currency exchange volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and clean-label preference evolution. Material shifts in EFSA novel food definitions for enzymatically modified extracts or EUDR traceability implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Bean-To-Bar Chocolate Market
Confectionery
South America Confectionery Market
Confectionery
South Korea Chocolate Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Licorice Candy Market
Confectionery
Asia-Pacific Confectionery Market
Confectionery
South America Chocolate Market
Confectionery
Low-Fat Sweets Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
North America Dark Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
White Chocolate Market
Confectionery
Asia-Pacific Sugar Free Chewing Gum Market
Confectionery
Sugar-Free Sweets Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
Global Industrial Chocolate Market