
 Europe Prepaid Card Market | 2026-2036
Europe Prepaid Card Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Prepaid Card Market Insights
A shortage of embedded-finance engineers and compliance technologists is unwinding product rollout timelines for several European issuers. Revolut Ltd. leverages its banking license stack to anchor multi-currency prepaid offerings across the continent. Edenred SA sustains dominance in corporate meal and fleet segments through closed-loop network density. Paysafe Ltd. competes in digital entertainment and gaming verticals with specialized virtual card infrastructure.
Prepaid cards are non-credit payment instruments funded in advance through direct deposit, cash load, or bank transfer, typically bearing 16-digit PAN credentials and operating on major scheme networks for authorization and settlement. Their primary commercial purpose is to enable controlled spending, payroll disbursement, and financial access for users without traditional banking relationships. Open loop products lead transaction volume across retail and online channels, while virtual cards represent the fastest-growing feature set as contactless and mobile integration demand accelerates among digitally native end users. Corporate end users generate the deepest margin pools through recurring B2B program fees and foreign exchange markups.
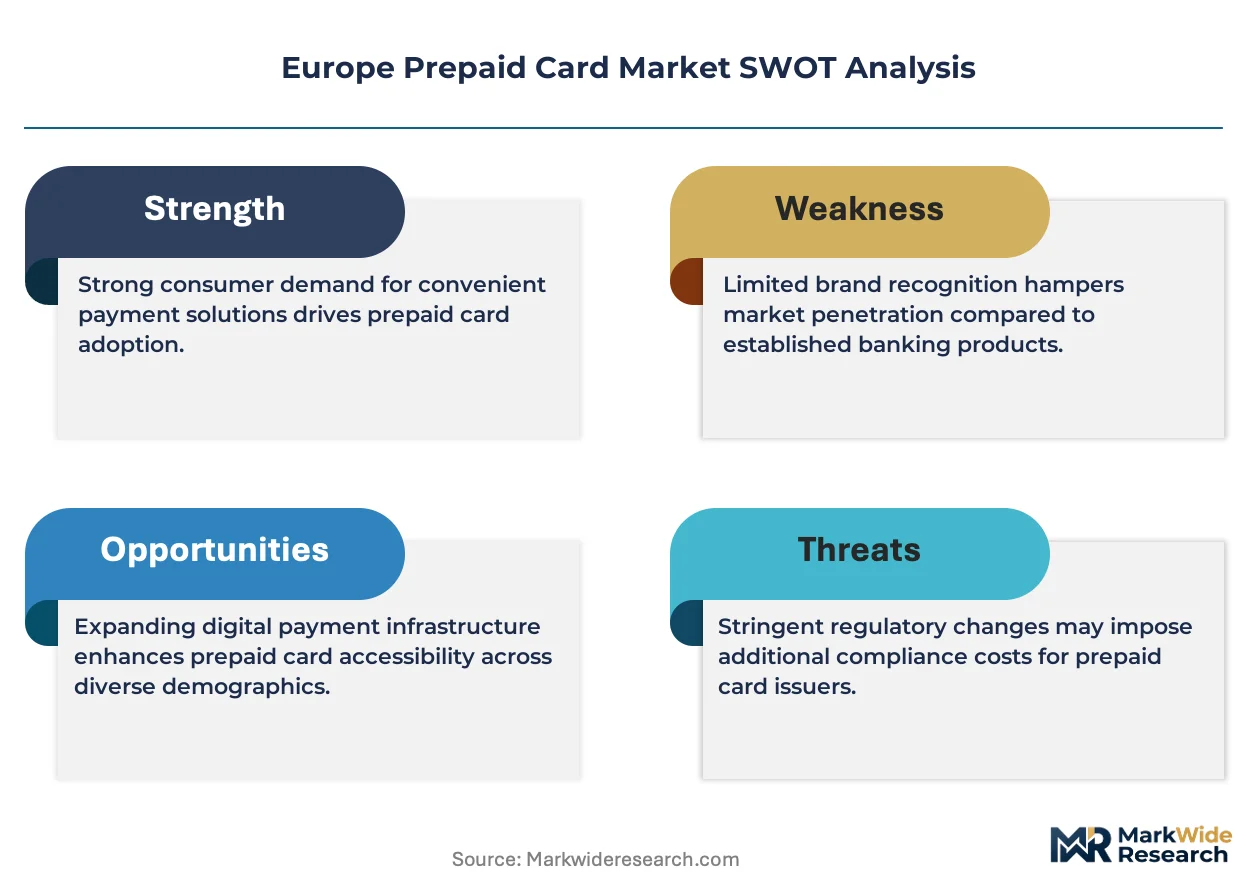
PSD2 and the EU's Digital Operational Resilience Act (DORA) impose strict authentication and IT risk standards on payment service providers, directly elevating compliance costs for prepaid program managers. The European Banking Authority (EBA) guidelines on anti-money laundering further shape customer onboarding workflows and transaction monitoring thresholds. E-money licensing requirements under national regulators such as BaFin in Germany and the Financial Conduct Authority in the United Kingdom create fragmented market access barriers that favor established players with multi-jurisdictional authorization. Stakeholders must monitor how the EU's instant payment regulation and proposed digital euro initiative reshape funding rail economics and issuer interoperability requirements.
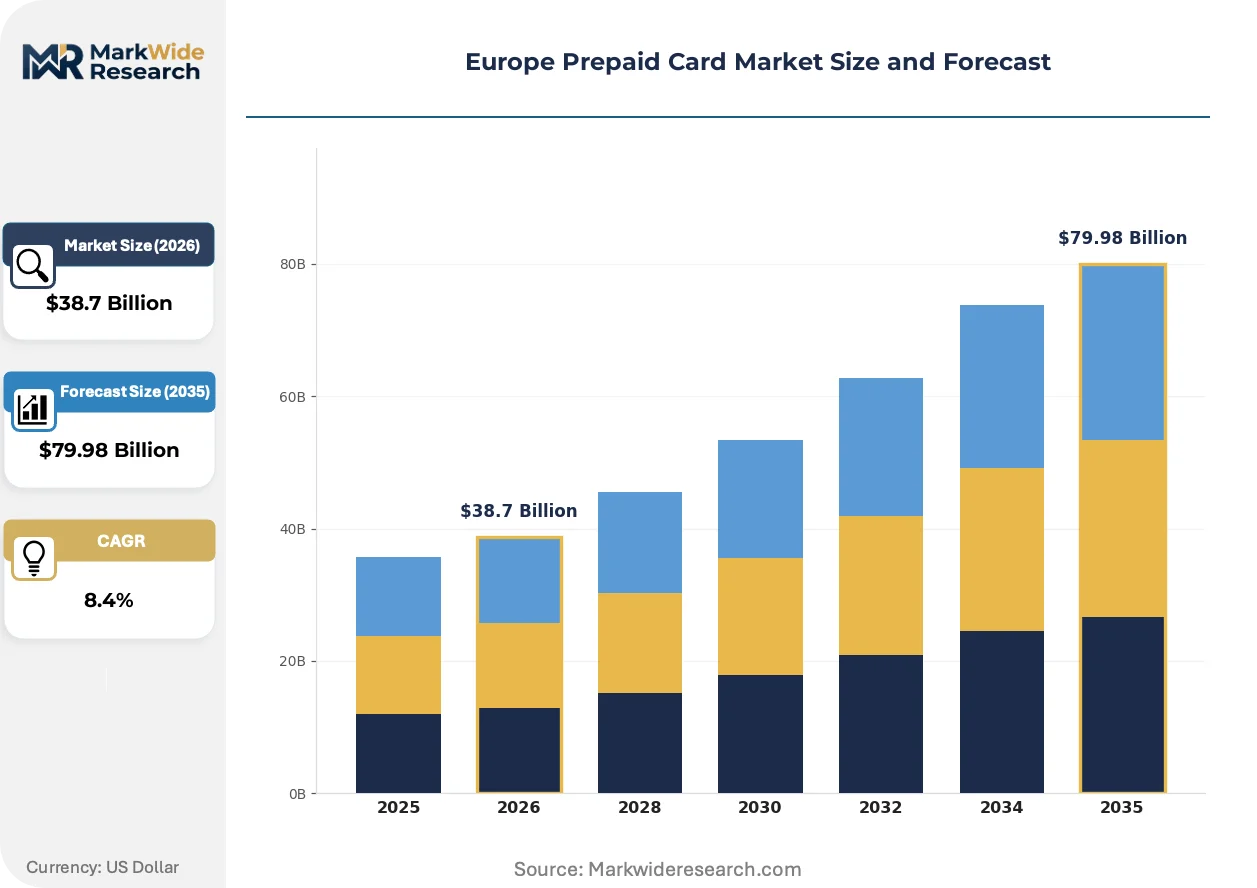
Market Dynamics
PSD2's open banking mandates are fragmenting issuer-processor relationships across Europe, forcing prepaid program managers to rebuild API architectures around real-time account access and Strong Customer Authentication workflows.
Growth Catalysts
- Corporate travel digitization:Germany's BaFin-regulated e-money frameworks enable automated expense reconciliation for fleet and per diem programs, accelerating B2B card issuance.
- PSD2 Strong Customer Authentication:The EU directive mandates biometric and two-factor verification, creating standardized security infrastructure that reduces fraud costs for prepaid issuers.
- France's meal voucher modernization:Edenred's closed-loop network density supports regulatory migration from paper to digital meal benefits, expanding reloadable card penetration.
Market Restraints
- E-money licensing fragmentation:Separate authorizations from the FCA, BaFin, and ACPR create multi-jurisdictional compliance costs that favor established players with existing banking licenses.
- Embedded-finance talent scarcity:A shortage of API developers and compliance technologists extends product rollout timelines for digital-first prepaid offerings.
- Legacy core banking substitution:Cloud-native card management platforms threaten traditional processor relationships, creating migration friction for incumbent issuers.
Strategic Opportunities
- Poland's unbanked corridor:Regulatory financial inclusion initiatives target underbanked populations with basic payment accounts, opening prepaid distribution through retail networks.
- Instant Payment Regulation convergence:The EU's SEPA Instant mandate creates 24/7 funding rails that enable real-time prepaid top-ups, differentiating against traditional ACH delays.
- Gaming vertical API integration:Paysafe's specialized virtual card infrastructure demonstrates how embedded finance partnerships with digital entertainment platforms unlock recurring transaction volumes.
Industry Challenges
- DORA compliance timelines:The EU's Digital Operational Resilience Act imposes strict IT risk management and incident reporting standards that require significant infrastructure investment before January 2025 deadlines.
- EBA AML workflow complexity:Evolving European Banking Authority guidelines on transaction monitoring thresholds force continuous recalibration of customer onboarding and suspicious activity detection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Prepaid Card Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Loop, Closed Loop, Virtual, Reloadable End User: Individuals, Corporations, Government, Non-profits Distribution Channel: Retail, Online, Banks, ATMs Feature: Cashback, Rewards, Contactless, Mobile Integration |
| Companies Covered | Visa, Mastercard, PayPal Holdings Inc., American Express Company, Green Dot Corporation, Revolut Ltd., Edenred SA, Paysafe Ltd., N26 AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Prepaid Card Market Trends and Innovations
Virtual card issuance is compressing physical plastic production cycles while open banking APIs are displacing traditional processor dominance in program management workflows.
Tokenized mobile wallet provisioning is displacing contactless plastic as the primary prepaid delivery mechanism. Digital-native users in the United Kingdom and Nordic markets now expect instant virtual card generation through banking apps. This shift is displacing legacy emboss-and-mail fulfillment economics, forcing issuers to renegotiate processor contracts around API-based credential delivery.
The EU's Digital Operational Resilience Act (DORA) mandates granular IT risk governance for all payment service providers. Prepaid program managers must implement comprehensive incident reporting and third-party risk monitoring by early 2025. Small and mid-sized issuers in Spain and Italy face particular pressure to consolidate technology stacks or exit the market.
Corporate procurement departments are consolidating travel and expense programs around unified prepaid platforms. Finance teams in France and Germany now demand real-time spend visibility and automated VAT recovery, displacing fragmented reimbursement processes. This concentration favors issuers with integrated accounting software partnerships and multi-currency hedging capabilities.
Europe Prepaid Card Market Segmentation
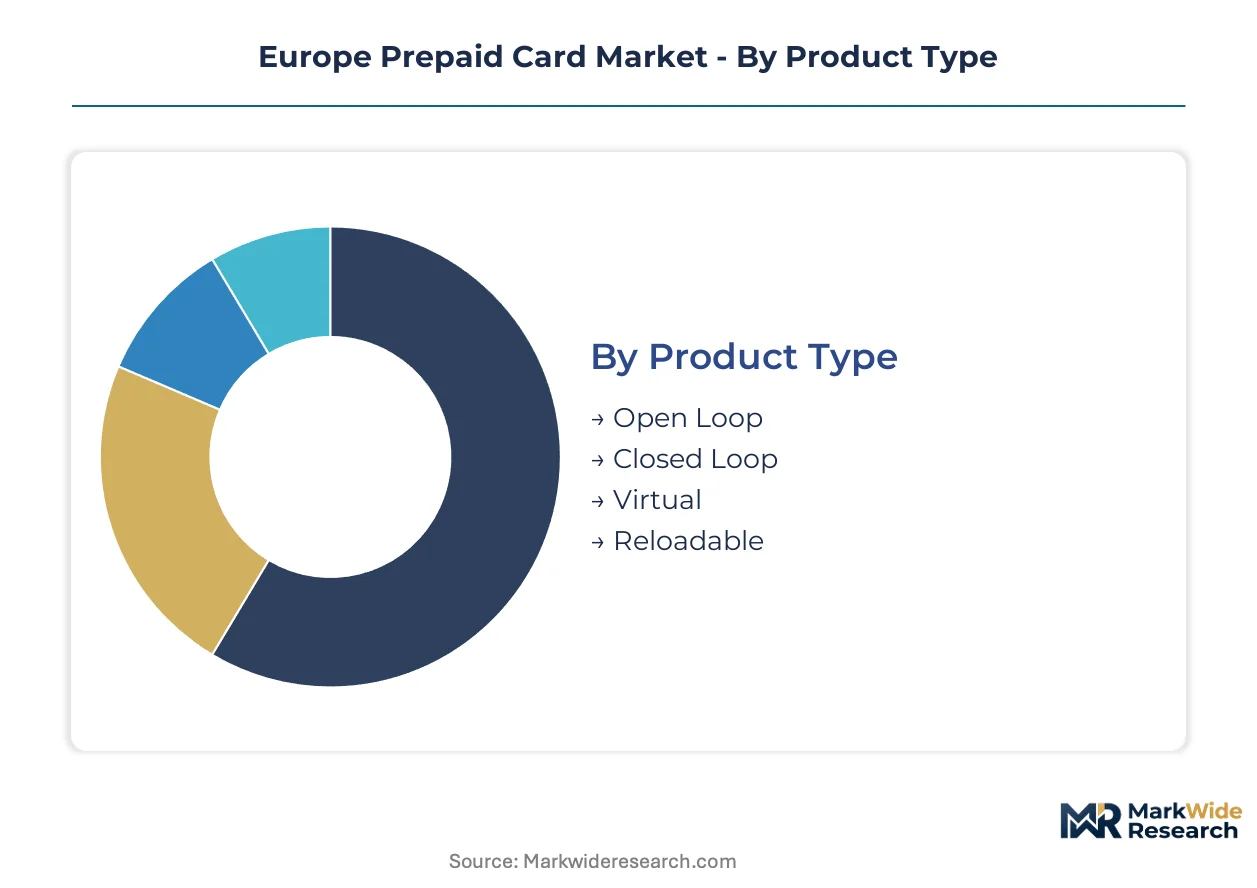
Prepaid card segmentation across Europe reveals distinct margin architectures. Product type determines scheme network economics, while end-user concentration shapes program management fee structures and foreign exchange revenue depth.
Product Type:
Margin pools concentrate in network-branded instruments that capture interchange and cross-border transaction flows.
- Open Loop:These instruments carry Visa or Mastercard credentials and settle across scheme networks, enabling universal merchant acceptance. Corporate travel programs in Germany and the United Kingdom drive issuance volume, with automated expense reconciliation reducing administrative overhead for fleet and per diem disbursement.
- Virtual:Digital-only credentials generated through API provisioning eliminate plastic production and emboss-and-mail fulfillment costs. Gaming platforms and digital entertainment merchants in the United Kingdom and Nordic markets absorb these instruments fastest, with instant issuance matching consumer expectations for mobile-first payment experiences.
- Closed Loop:Restricted acceptance networks limit merchant interoperability but capture higher breakage rates on unspent balances. Edenred's meal voucher infrastructure exemplifies this model across France and Belgium.
- Reloadable:Persistent funding capabilities extend customer lifetime value through recurring top-up behavior. Financial inclusion initiatives in Poland and Romania distribute these products through retail agent networks.
Open Loop holds installed capacity. Virtual is rotating up the share rankings.
End User:
Application context determines pricing power and program stickiness across the customer base.
- Corporations:B2B disbursement programs generate the deepest margin pools through recurring platform fees, foreign exchange markups, and integrated accounting software partnerships. Finance teams in France and Germany demand real-time spend visibility and automated VAT recovery, consolidating previously fragmented reimbursement processes.
- Individuals:Unbanked and underbanked populations access basic payment functionality without traditional banking relationships. Poland's regulatory financial inclusion initiatives target this segment through retail distribution networks.
- Government:Social benefit disbursement programs require compliant procurement frameworks and audit trail capabilities. National regulators impose strict authentication standards on public sector deployments.
- Non-profits:Humanitarian aid distribution leverages prepaid instruments for beneficiary identification and fund traceability. Cross-border remittance corridors favor virtual credential delivery.
Corporations anchor current revenue concentration. Individuals are expanding most quickly through financial inclusion mandates.
Distribution Channel:
Channel economics fragment across physical and digital touchpoints with divergent customer acquisition costs.
- Online:Direct-to-consumer digital onboarding eliminates intermediary margins and enables instant virtual card provisioning. Mobile-first users in the United Kingdom expect seamless app-based credential generation.
- Retail:Physical point-of-sale activation captures cash-preferred customers and unbanked segments. Agent networks in Eastern European markets sustain reload infrastructure.
- Banks:Established financial institutions leverage existing customer relationships for cross-sold prepaid products. PSD2 open banking APIs reshape issuer-processor partnerships.
- ATMs:Cash loading infrastructure extends network utility for reloadable instruments. SEPA Instant funding rails enable real-time balance updates.
Online captures the steepest expansion trajectory. Retail maintains physical presence density.
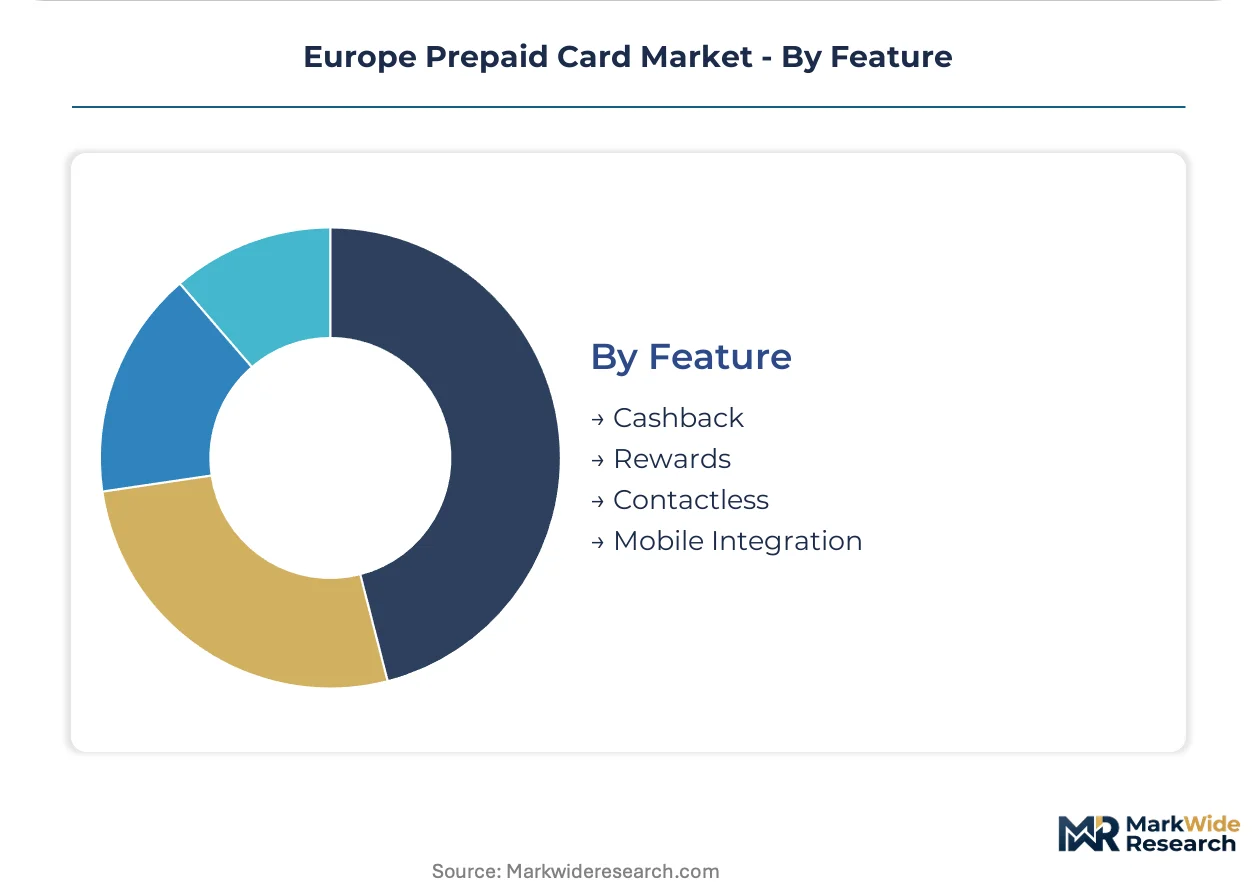
Feature:
Capability differentiation increasingly determines customer selection and retention outcomes.
- Contactless:Near-field communication enablement matches European consumer preference for tap-to-pay convenience. Tokenized mobile wallet provisioning displaces plastic dependency.
- Mobile Integration:Native banking app embedding and instant push provisioning align with digitally native user expectations. API architectures support real-time credential delivery.
- Cashback:Merchant-funded reward programs subsidize issuer acquisition costs. Retail network partnerships determine program attractiveness.
- Rewards:Points-based loyalty structures extend engagement for recurring-use instruments. Corporate programs integrate with expense management platforms.
Contactless holds mature deployment scale. Mobile Integration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys prepaid instruments predominantly for corporate fleet and per diem automation, while France channels volume through regulated meal benefit digitization. The United Kingdom diverges toward mobile-native virtual issuance for gaming and entertainment platforms.
Germany
BaFin's e-money licensing frameworks enable automated expense reconciliation for B2B disbursement programs. The Digital Operational Resilience Act imposes strict IT risk governance on payment service providers operating national infrastructure. Berlin and Frankfurt host concentrated fintech development clusters where cloud-native card management platforms are displacing legacy processor relationships.
United Kingdom
Financial Conduct Authority authorization requirements create fragmented market access barriers favoring established multi-jurisdictional players. The FCA's Strong Customer Authentication mandates reshape API architectures around biometric verification workflows. London's digital banking corridor drives instant virtual card generation through native mobile app embedding.
France
Edenred's closed-loop network density supports regulatory migration from paper meal vouchers to reloadable digital instruments. The Autorité de Contrôle Prudentiel et de Résolution supervises e-money issuance with strict anti-money laundering calibration requirements. Paris anchors corporate procurement consolidation around unified prepaid platforms with real-time spend visibility.
Poland
Regulatory financial inclusion initiatives target underbanked populations with basic payment account access through retail agent networks. The country's national banking regulator imposes compliant procurement frameworks on social benefit disbursement programs. Warsaw and Krakow sustain reload infrastructure for cash-preferred customer segments.
Netherlands
Randstad metropolitan concentration drives demand for multi-currency corporate travel instruments with integrated accounting software partnerships. De Nederlandsche Bank oversees payment service provider licensing with granular third-party risk monitoring requirements. Amsterdam's fintech ecosystem specializes in API-based credential delivery for digital-native user bases.
Europe Prepaid Card Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with banking-license holders commanding premium positioning in multi-currency and B2B segments. The middle tier fragments across closed-loop benefit networks and virtual card infrastructure specialists. Two strategic archetypes dominate: scheme-anchored global networks leveraging universal acceptance, and license-stacked fintechs exploiting regulatory authorization for rapid product iteration. Competitive moves concentrate on API-based processor substitution and embedded-finance partnership expansion.
Within the license-stacked tier, Revolut Ltd. and N26 AG exemplify the banking-authorization advantage for continental scale, while Edenred SA occupies a position representing closed-loop density specialization. Visa and Mastercard anchor the scheme-network archetype with interchange economics that underpin issuer business models. Paysafe Ltd. sits within the vertical-specialist category, demonstrating how gaming-focused virtual infrastructure unlocks recurring transaction volumes through platform embedding.
| Leading Market Players |
|---|
| Visa |
| Mastercard |
| PayPal Holdings Inc. |
| American Express Company |
| Green Dot Corporation |
| Revolut Ltd. |
| Edenred SA |
| Paysafe Ltd. |
| N26 AG |
| Others |
Pricing and Supply Chain Analysis
Scheme network scale economies in Visa and Mastercard credentialing concentrate pricing power among issuers with multi-jurisdictional banking licenses, compressing margin floors for program managers lacking direct scheme relationships. BaFin and FCA authorization density in Germany and the United Kingdom reinforces this bifurcation, as licensed players capture interchange economics while smaller issuers absorb processor markups.
Pricing Analysis
Contract structures in corporate B2B programs favor long-term offtake arrangements with recurring platform fees and foreign exchange markups, while individual consumer segments absorb spot-priced transactional models with higher per-unit variability. Price differentiation rests on scheme network tier and API provisioning sophistication, with virtual card infrastructure commanding premium positioning over physical plastic fulfillment. Cost compression in basic reloadable products intensifies as SEPA Instant rails commoditize funding velocity. Government disbursement programs exhibit lowest price sensitivity due to compliance procurement mandates, whereas individual unbanked segments drive volume through retail agent networks at compressed unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for plastic card production and chip personalization equipment, though virtual credential delivery increasingly displaces physical fulfillment. Manufacturing concentration clusters in Germany, the Netherlands, and Estonia for card personalization services, while Taiwan and South Korea anchor semiconductor supply for secure element chips. Single-source vulnerability in EMV chip provisioning poses structural risk to emboss-and-mail fulfillment timelines. Distribution runs through scheme-certified processor networks with API-based credential delivery displacing traditional mail fulfillment for digitally native user bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe prepaid card market exhibits cyclical recovery characteristics as corporate travel normalization and PSD2 compliance investment cycles converge, with BaFin and FCA authorization backlogs creating temporary supply constraints that favor prepared incumbents.
For Market Incumbents: Shield core B2B program relationships through exclusive API integration with accounting software platforms, as cloud-native processor substitution threatens traditional scheme-processor contracts. Deepen vertical integration into virtual card infrastructure to capture gaming and entertainment verticals before specialized fintechs consolidate embedded-finance partnerships.
For New Entrants and Emerging Players: Corporate treasury under-service in mid-market Polish and Romanian enterprises presents white-space opportunity, as established players concentrate on large multinational accounts in Germany and France. Target regulatory financial inclusion mandates through retail agent network partnerships rather than direct digital onboarding, leveraging cash-preferred customer segments that incumbent neobanks overlook.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors license-stacked fintechs with multi-jurisdictional authorization, as DORA compliance timelines force consolidation among sub-scale issuers. Long-term viability hinges on instant payment rail integration and virtual card API scalability. Watch SEPA Instant adoption rates across Eastern European markets as inflection indicator for funding rail economics disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Banking License Stack Expansion | Multi-jurisdictional BaFin and FCA authorization enables direct scheme relationships and interchange capture. |
| Virtual Card Infrastructure Buildout | API-based credential delivery displaces plastic fulfillment for gaming and entertainment platform embedding. |
| Corporate Accounting Software Integration | Real-time expense reconciliation partnerships with SAP and Oracle consolidate B2B program stickiness. |
| SEPA Instant Rail Integration | 24/7 funding capability differentiates against ACH-delayed competitors in reloadable product segments. |
| DORA Compliance Infrastructure Investment | Granular IT risk governance satisfies EBA incident reporting mandates before regulatory deadlines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECB payment statistics, EBA regulatory guidelines, and scheme network disclosure filings, combining structured interviews with prepaid program managers, corporate treasury officers, and compliance technologists with bottom-up and top-down triangulation across national regulator authorization databases.
Segmentation dimensions modeled include product type architecture, end-user application context, distribution channel economics, and feature capability differentiation across the projection horizon. CAGRs derive from trend extrapolation of issuance volumes, transaction velocity, and foreign exchange revenue pools, with scheme network interchange schedules and SEPA Instant adoption curves as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU PSD2, DORA, and national e-money licensing regimes; material policy shifts such as digital euro issuance mandates or instant payment fee caps would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
APAC Mobile Payments Market
Payments
France POS Terminal Market
Payments
Blockchain Payments Software Market
Payments
GCC Payment Gateway Market
Payments
Electronic Payment Processing Software Market
Payments
Vietnam E-Wallet Market
Payments
India Gift Card and Incentive Card Market
Payments
China Payment Gateway Market
Payments
Credit Card Payments Market
Payments
Bulgaria POS Terminals Market
Payments
Proximity Mobile Payment Market
Payments
Third Party Payment Market
Payments
Asia-Pacific Digital Remittance Market
Payments
Gift Card and Incentive Card Market
Payments
EMV Card Market
Payments
China Payments Market