
 Window Covering Market | 2026-2036
Window Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Window Covering Market Analysis
Premium thermal performance tiers is collapsing the gap between commodity blinds and engineered facade systems as building codes tighten across major construction markets. Hunter Douglas N.V. leverages its vertical manufacturing footprint to control raw material conversion from polymer extrusion to finished shade assembly. Springs Window Fashions LLC anchors its position through captive distribution relationships with national home improvement retailers. Somfy S.A. specializes in motorization and home automation protocols, extending its influence beyond hardware into control system architecture.
Window coverings comprise operable and fixed treatments—blinds, shades, drapes, and shutters—fabricated from wood, fabric, vinyl, or aluminum, designed to modulate light transmission, thermal transfer, and visual privacy through manual or automated actuation. Blinds and shades command the largest installed base due to retrofit compatibility and cost scalability across residential and commercial envelopes. Fabric and wood materials carry premium positioning in hospitality and high-end residential applications where acoustic dampening and aesthetic warmth justify higher specification. The distribution channel structure is fragmenting as online retail captures standard-size volume while specialty shops retain complex commercial and custom residential projects requiring measurement and installation services.
FDA oversight of cord safety standards and CPSC recall protocols directly shapes product design requirements for corded window coverings in the United States, while REACH chemical restrictions in Europe limit certain flame retardants and plasticizers used in vinyl slat production. EPA ENERGY STAR certification for attachment products and California Title 24 building efficiency standards are elevating thermal performance testing as a prerequisite for market access in key states. Stakeholders must monitor evolving smart home interoperability standards and decarbonization mandates that will determine which material platforms and motorization architectures secure specification preference in the next construction cycle.
Market Dynamics
Building envelope efficiency mandates are compressing specification cycles for fenestration products as thermal performance becomes a code-mandated purchase criterion rather than a discretionary upgrade. Motorization integration and smart home protocol standardization are simultaneously elevating technical barriers for component suppliers while opening new revenue pools for systems architects.
Growth Catalysts
- EU Green Deal building renovation wave:Mandatory energy performance certificates for existing structures are accelerating retrofit specifications across Germany, France, and the Netherlands. Member states must renovate worst-performing building stock at measurable annual rates.
- Smart home protocol convergence:Matter and Thread standardization is reducing motorization integration friction. Residential developers now specify automated shade packages as standard in premium multifamily construction.
- Acoustic performance specification:Hospitality and healthcare verticals are specifying fabric cellular shades for sound dampening. Open-plan office retrofits are absorbing dual-function thermal-acoustic solutions at elevated price points.
Market Restraints
- Aluminum and polymer input volatility:Slat and headrail fabrication depends on extruded aluminum and PVC compounds. Energy-intensive smelting and petrochemical feedstock costs transmit directly to finished product margins.
- Cord safety compliance burden:CPSC mandatory standards for corded window coverings require extensive redesign and testing. Small fabricators lack capital to absorb retooling costs, consolidating supply toward scaled manufacturers.
- Installation labor scarcity:Custom measurement and mounting services require skilled trades. Residential retrofit project delays extend revenue recognition cycles and elevate customer acquisition costs.
Strategic Opportunities
- Decarbonization-linked financing instruments:Green mortgage products and property-assessed clean energy bonds are covering window covering upgrades. Lenders in Germany and California are bundling efficiency improvements into renovation loans.
- Commercial building automation integration:BACnet and KNX protocol compatibility positions motorized shades as demand-response assets. Facility managers in large-format offices are procuring shading as part of integrated energy management systems.
- Direct-to-installer digital platforms:Configurator tools with augmented reality measurement are compressing sales cycles. Specialized distributors are bypassing retail markup to capture commercial specification flow.
Industry Challenges
- Multi-protocol motor engineering:Shade OEMs must support Zigbee, Z-Wave, Wi-Fi, and proprietary home automation ecosystems simultaneously. Firmware development teams face persistent talent competition from consumer electronics sectors.
- Certification timeline compression:ENERGY STAR and NFRC attachment product ratings require third-party thermal testing. Test queue backlogs delay new product launches by multiple quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Window Covering Market |
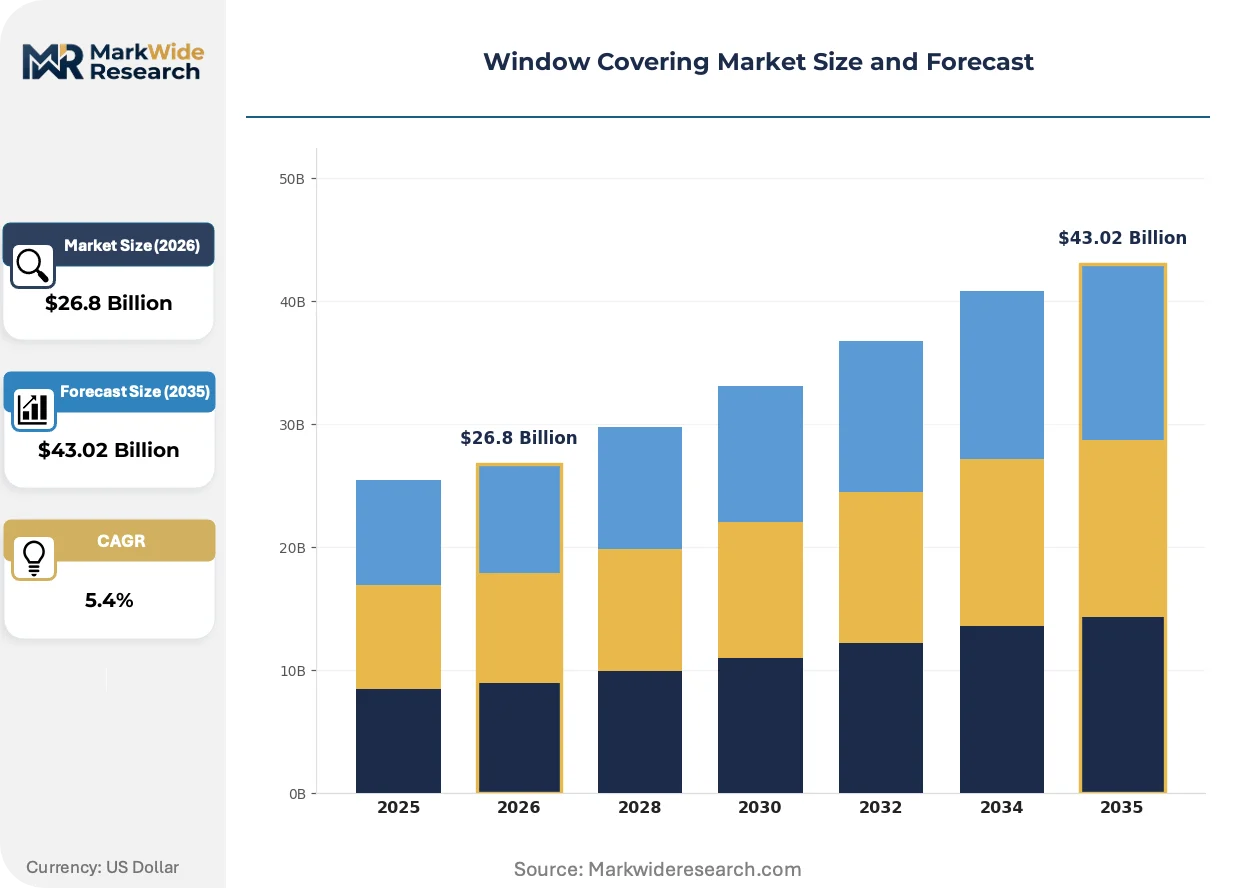
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blinds, Shades, Drapes, Shutters Material: Wood, Fabric, Vinyl, Aluminum Application: Residential, Commercial, Hospitality, Automotive Distribution Channel: Online Retail, Home Improvement Stores, Specialty Shops, Distributors |
| Companies Covered | Hunter Douglas N.V., Springs Window Fashions LLC, Somfy S.A., Lutron Electronics Co., Inc., Nien Made Enterprise Co., Ltd., MechoShade Systems, LLC, Insolroll Window Shading Systems, Lafayette Interior Fashions, Comfortex Window Fashions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Window Covering Market Emerging Trajectories
Material science advances and control system architecture evolution are redefining competitive boundaries between commodity shade assemblers and engineered facade specialists. Technical differentiation now concentrates at the intersection of thermal performance, motorization reliability, and interoperability compliance.
Photovoltaic-integrated shading systems are bifurcating the commercial specification market. Building-integrated photovoltaics embedded in exterior louvers and brise-soleil generate on-site power while managing solar heat gain. Large-format office developers in California and Germany are specifying these systems for net-zero certification compliance. The technology is compressing traditional HVAC load calculations and shifting capital allocation toward envelope-first design.
REACH chemical restrictions are forcing material platform transitions across European supply chains. ECHA substance of very high concern listings have eliminated certain phthalate plasticizers and halogenated flame retardants from vinyl slat formulations. Compounders are validating bio-based plasticizers and mineral flame retardants through accelerated aging protocols. German fabricators are absorbing reformulation costs to maintain CE marking access, while non-compliant imports face customs detention at Rotterdam and Hamburg.
Buyer concentration among national home improvement retailers is reshaping procurement leverage structures. Category managers at Lowe's and Home Depot are demanding exclusive SKUs, dedicated inventory positions, and vendor-managed replenishment. Private-label shade programs now capture substantial North American volume. Domestic suppliers are responding with captive offshore assembly to meet price targets while preserving margin through material specification control.
Window Covering Market Segmentation
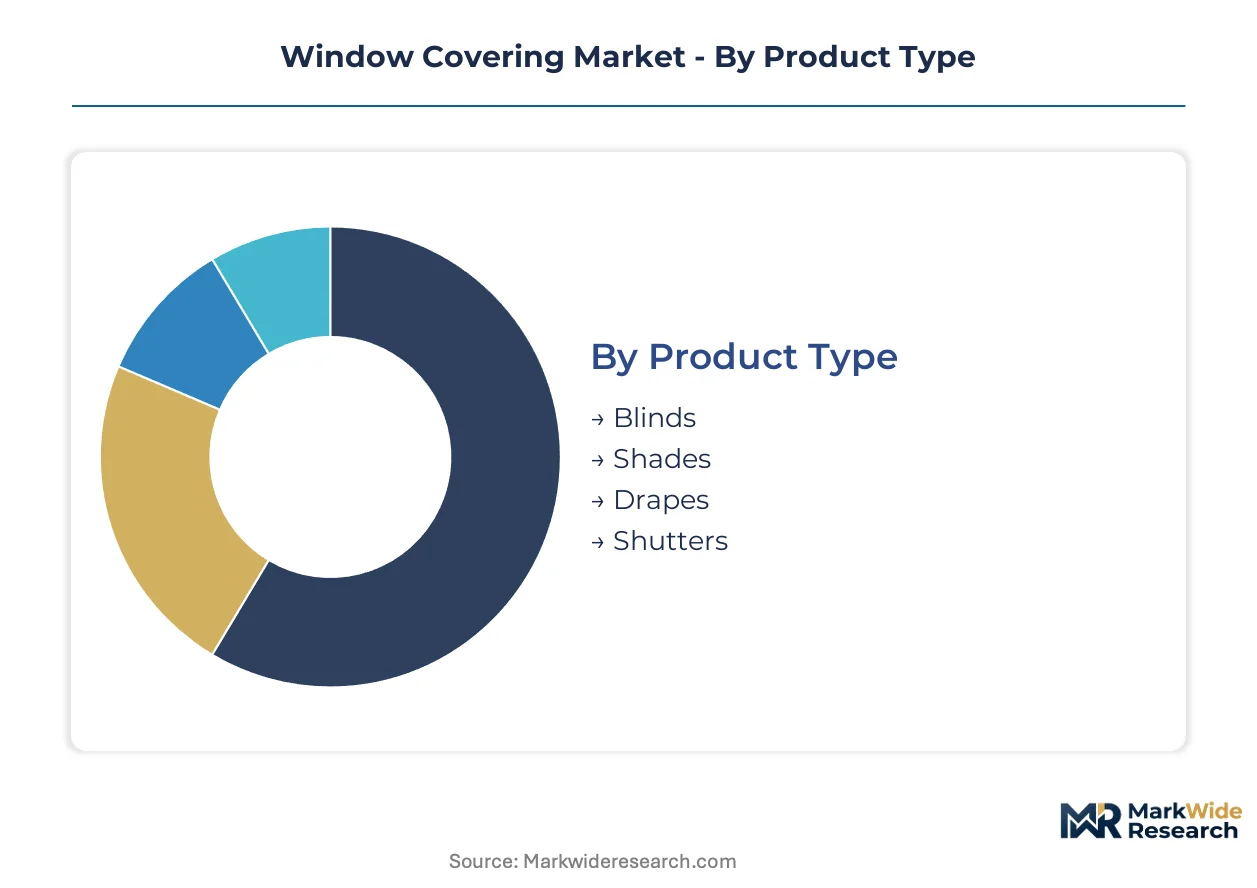
Window covering procurement patterns diverge sharply across residential retrofits, commercial new construction, and hospitality fit-outs. Specification requirements for thermal performance, motorization integration, and acoustic dampening create distinct margin architectures within each segment category.
Product Type:
Margin pools concentrate in motorized and thermal-rated systems where building codes have eliminated commodity alternatives.
- Blinds:Horizontal and vertical slat systems fabricated from aluminum, vinyl, or wood dominate residential retrofit volume. California Title 24 and EU Green Deal efficiency mandates are accelerating specification of cellular and thermal-rated variants in Germany and the Netherlands.
- Shades:Roller, Roman, and cellular fabric systems command premium positioning through motorization integration and acoustic performance. Hospitality developers in Dubai and Singapore specify dual-function thermal-acoustic cellular shades for open-plan atriums and guest room retrofits.
- Drapes:Heavy fabric panels with manual or motorized track systems retain specification in luxury residential and theatrical applications where aesthetic warmth outweighs technical performance metrics.
- Shutters:Plantation and colonial-style louvered panels fabricated from wood or composite materials concentrate in Southern US residential markets and Mediterranean climate zones for storm protection and architectural consistency.
The dominant share belongs to Blinds, while Shades is closing the gap fastest through smart home integration and thermal code compliance.
Material:
Raw material selection directly determines thermal performance certification eligibility and REACH chemical compliance access.
- Wood:Solid hardwood and engineered composite slats carry premium positioning in high-end residential and hospitality applications. FSC chain-of-custody certification is becoming mandatory for EU public procurement and LEED-compliant commercial projects in Chicago and San Francisco.
- Fabric:Woven polyester, linen, and blackout-coated textiles enable cellular construction for thermal-acoustic dual function. German fabricators are absorbing reformulation costs to eliminate SVHC-listed flame retardants under ECHA restrictions.
- Vinyl:Extruded PVC slats and vanes offer cost scalability across mass-market residential channels. Phthalate-free plasticizer transitions are compressing margins for European suppliers while opening specification barriers for compliant imports.
- Aluminum:Roll-formed and extruded slat systems deliver durability and recyclability for commercial high-cycle applications. Energy-intensive smelting costs transmit directly to finished product margins, favoring suppliers with captive extrusion capabilities.
Fabric and Wood together capture the premium tier, though Aluminum is expanding most quickly in commercial automation-integrated specifications.
Application:
End-use concentration shapes technical requirements for motorization protocols, fire safety ratings, and installation service intensity.
- Residential:Single-family and multifamily retrofits absorb standard and custom-sized treatments through home improvement retail and direct-to-installer digital platforms. Matter and Thread protocol standardization is embedding motorized shades as standard in premium multifamily developments in Austin and Miami.
- Commercial:Office, healthcare, and educational facilities specify BACnet and KNX-compatible motorized systems as demand-response assets. Facility managers in Frankfurt and Los Angeles procure shading through integrated energy management contracts rather than discrete capital purchases.
- Hospitality:Hotels and resorts prioritize acoustic dampening, blackout performance, and brand-consistent aesthetics through custom fabric programs. Procurement runs through specialized FF&E specification firms with captive installation networks.
- Automotive:Sun visors, rear window shades, and panoramic roof systems integrate into OEM tier-1 supply chains with stringent vibration and temperature cycling requirements.
Residential maintains volume leadership, but Commercial is gaining share fastest through building automation integration and efficiency-linked financing instruments.
Distribution Channel:
Channel structure is fragmenting as measurement and installation service requirements separate simple from complex transactions.
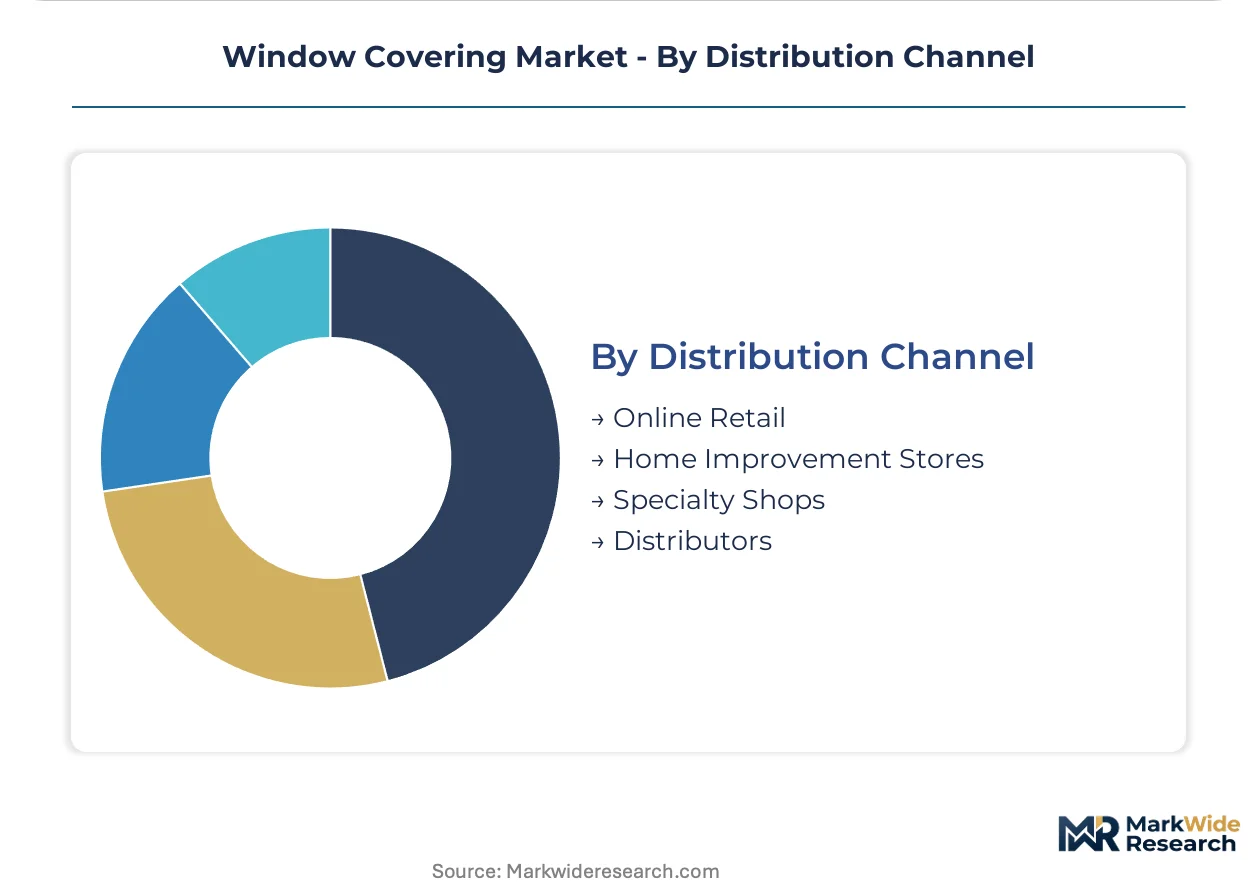
- Online Retail:Direct-to-consumer platforms capture standard-size volume in blinds and shades through augmented reality measurement tools and compressed delivery cycles. Returns complexity limits category penetration for custom dimensions.
- Home Improvement Stores:Lowe's and Home Depot category managers demand exclusive SKUs and vendor-managed replenishment, consolidating procurement leverage toward scaled manufacturers with captive offshore assembly.
- Specialty Shops:Independent dealers retain complex commercial and custom residential projects requiring field measurement, professional installation, and post-sale service. Technical consultation justifies margin premiums over mass retail.
- Distributors:Two-step and specialty distributors serve commercial specification flow with project-based quoting, staging, and installation coordination. Digital configurators are compressing sales cycles and bypassing retail markup capture.
Home Improvement Stores hold the largest transaction volume, while Online Retail is climbing the fastest through AR-enabled measurement and next-day fulfillment capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in window coverings track construction activity and regulatory stringency. Germany and the Netherlands export specification-grade systems to EU renovation markets. The United States imports motorization components while maintaining domestic assembly for custom residential channels.
Germany
Building envelope codes under the EU Green Deal mandate thermal-rated retrofits at measurable annual rates. ECHA REACH restrictions on phthalate plasticizers force vinyl compound reformulation across domestic extrusion plants. The Rhine-Ruhr industrial corridor concentrates fabric finishing and motor assembly operations serving Benelux and French specification markets.
United States
California Title 24 and EPA ENERGY STAR certification elevate thermal performance testing to market access prerequisites. CPSC cord safety standards drive redesign costs that consolidate supply toward scaled manufacturers. The Dallas-Fort Worth metroplex anchors national distribution infrastructure for home improvement retail channels.
China
Dual carbon goals and GB standards for building efficiency accelerate specification of automated shading in premium commercial developments. MIIT industrial policy supports motorization component manufacturing for export markets. The Yangtze River Delta clusters aluminum extrusion and fabric weaving capacity serving North American and European OEM supply chains.
Netherlands
EU Green Deal renovation wave targets worst-performing residential stock with mandatory energy performance certificates. CE marking compliance for attachment products requires third-party thermal testing through accredited Rotterdam laboratories. The Randstad conurbation hosts specification firms coordinating cross-border commercial projects into Germany and Belgium.
Japan
METI building efficiency standards and JIS certification protocols shape product development for high-cycle commercial applications. Aging residential stock drives retrofit specifications for motorized shades with Matter protocol compatibility. The Kanto region around Tokyo concentrates distribution infrastructure for hospitality and healthcare verticals.
Window Covering Market Vendor Landscape
Concentration sits with vertically integrated fabricators controlling raw material conversion through finished assembly. The vendor base spans multinational window treatment specialists, motorization technology providers, and regional custom manufacturers. Two strategic archetypes dominate: captive distribution players leveraging home improvement retail relationships, and automation specialists extending from hardware into control system architecture. Competitive moves center on exclusive SKU procurement arrangements and smart home protocol certification investments.
Among motorization and control system architects, Somfy S.A. and Lutron Electronics Co., Inc. occupy positions defining interoperability standards for automated shading. Hunter Douglas N.V. exemplifies the vertically integrated archetype through polymer extrusion-to-assembly control. These three anchors represent the competitive tension between hardware fabrication expertise and systems integration capability that shapes procurement leverage in commercial and premium residential channels.
| Leading Market Players |
|---|
| Hunter Douglas N.V. |
| Springs Window Fashions LLC |
| Somfy S.A. |
| Lutron Electronics Co., Inc. |
| Nien Made Enterprise Co., Ltd. |
| MechoShade Systems, LLC |
| Insolroll Window Shading Systems |
| Lafayette Interior Fashions |
| Comfortex Window Fashions |
| Others |
Supply Flow & Price Mechanics
Captive extrusion capacity at scale manufacturers in Germany and China compresses unit costs for aluminum slat systems while elevating price floors for smaller fabricators lacking backward integration into polymer compounding. This scale asymmetry concentrates margin pools with vertically integrated producers capable of absorbing REACH reformulation costs and CPSC retooling investments without passing full burden to buyers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by thermal certification tier and motorization protocol compatibility. Price compression runs through mass-market vinyl blinds as home improvement retailers extract vendor-managed replenishment concessions. Residential retrofit channels exhibit highest price sensitivity due to discretionary purchase framing, while commercial building automation procurement shows lowest sensitivity given efficiency-linked financing instruments.
Supply Chain Analysis
China and Germany anchor raw material conversion, with the Yangtze River Delta clustering aluminum extrusion and fabric weaving capacity and the Rhine-Ruhr corridor concentrating motor assembly and polymer compounding. Finished production draws from extruded aluminum, PVC compounds, and woven polyester textiles. Single-source vulnerability concentrates in semiconductor components for motor controllers. Distribution runs through home improvement retail consolidation in North America and specialty distributor networks in European commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation and measurement services represent a faster-expanding recurring layer than hardware margins, as skilled labor scarcity extends revenue recognition cycles and elevates customer lifetime value for service-captive providers.
For Market Incumbents: Fortify captive distribution control through exclusive SKU arrangements with Lowe's and Home Depot while deepening backward integration into polymer extrusion to absorb REACH plasticizer reformulation costs. Smart home protocol certification investments defend against motorization specialists encroaching on specification-grade commercial projects. For New Entrants and Emerging Players: Differentiate on direct-to-installer digital platforms with augmented reality measurement tools, targeting commercial retrofit channels where facility managers procure shading through integrated energy management contracts rather than discrete capital purchases. White space concentrates in BACnet and KNX-compatible systems for demand-response building automation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors motorization and control system architects over commodity shade assemblers, as Matter and Thread standardization embeds automated shades as standard in premium multifamily developments. Acquisition targets should demonstrate firmware development teams with multi-protocol engineering capabilities. The signal to watch is ENERGY STAR test queue compression indicating new product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Protocol Certification | Matter and Thread compatibility secures specification preference in Austin and Miami multifamily developments. |
| Backward Integration into Polymer Extrusion | Captive PVC compounding absorbs ECHA REACH reformulation costs while maintaining CE marking access. |
| Direct-to-Installer Digital Platform Launch | AR-enabled measurement tools compress sales cycles and bypass home improvement retail markup capture. |
| Commercial Building Automation Integration | KNX and BACnet compatibility positions motorized shades as demand-response assets in Frankfurt and Los Angeles. |
| Green Financing Instrument Alignment | Property-assessed clean energy bond eligibility in California and Germany bundles window covering upgrades into renovation loans. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with shade OEM product managers, motorization engineering directors, home improvement retail category buyers, and commercial facility management procurement leads; and secondary validation against EPA ENERGY STAR certification databases, CPSC recall filings, ECHA SVHC substance listings, and customs trade records for aluminum extrusion and fabric imports. Bottom-up channel volume estimates triangulated against top-down construction spending allocations across residential retrofit and commercial new construction verticals.
Across the analysis window, the forecasting framework modeled demand by product type, material platform, application vertical, and distribution channel, with CAGRs derived from building code adoption curves and smart home protocol penetration rates. Motorization attach rate assumptions and thermal performance certification timelines served as key sensitivity inputs for premium segment projections.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal renovation enforcement or aluminum smelting cost stability would require recalibration. Forecasts reflect documented assumptions regarding Matter protocol adoption velocity and cord safety compliance implementation pace. Recalibration cycles align with material shifts in building efficiency code adoption and smart home interoperability standard ratification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
Wall Clock Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
Flush Door Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Europe Commercial Blinds and Shades Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
Hearth Market