
 Christmas Tree Market | 2026-2036
Christmas Tree Market Size, Share, and Industry Trends Forecast 2026-2036
Christmas Tree Market Analysis
Multi-source procurement from Asian manufacturing clusters is expanding as brands diversify beyond single-country supply dependence. Balsam Hill leverages direct-to-consumer digital channels to control pricing and customer data across North American households. National Tree Company anchors its competitiveness through vertical manufacturing ownership in China and Mexico. Puleo International differentiates via specialized lighting engineering and patented quick-assembly hinge systems.
A Christmas tree is a coniferous or synthetic decorative structure, typically constructed from PVC or PE needles on hinged steel frames, designed for seasonal residential and commercial display. Its primary commercial purpose centers on holiday retail anchoring, where tree purchases drive coordinated ornament, lighting, and decor spending. Artificial and pre-lit tree types command the widest margin pools due to repeat-purchase cycles and accessory attachment rates. The 5-7 foot height band dominates unit volumes in suburban single-family dwellings, while above-10 foot specimens concentrate in hospitality and municipal applications. Online sales channels are capturing share from farm stands and supermarkets, particularly for artificial variants requiring no freshness verification.
The U.S. Department of Agriculture's Animal and Plant Health Inspection Service enforces phytosanitary certification on imported fresh-cut specimens, elevating compliance costs for European and Canadian suppliers. The EPA's evolving standards on flame-retardant chemical formulations directly affect PVC needle production for artificial trees manufactured in China. California's Proposition 65 labeling mandates create a de facto national compliance threshold for lead and phthalate disclosure. Stakeholders must monitor whether biobased needle alternatives can achieve cost parity with conventional petroleum-derived materials before the next full product development cycle.
Market Dynamics
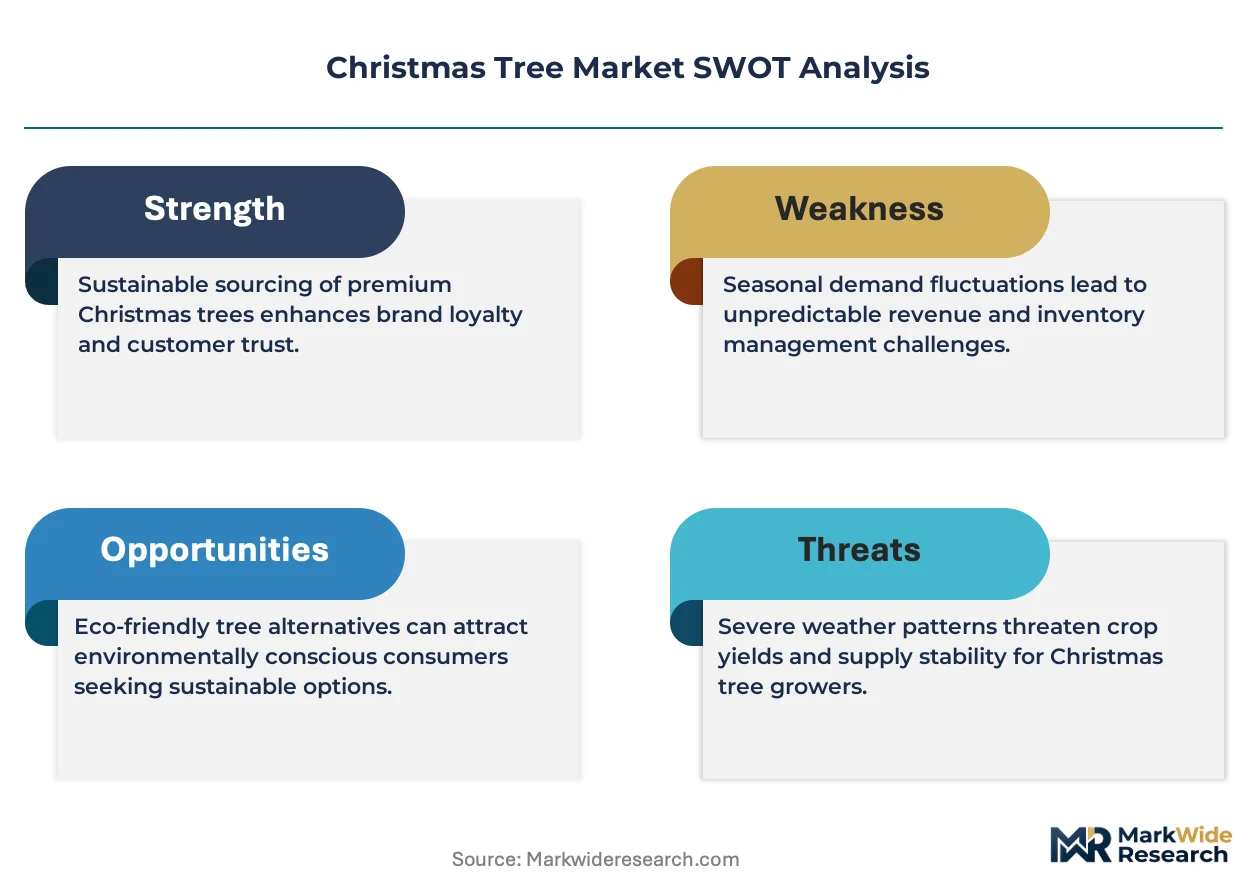
The Christmas Tree Market is experiencing structural pressure from phytosanitary compliance requirements on fresh-cut imports, which is compressing margins for traditional farm-stand channels while accelerating artificial tree adoption through digital direct-to-consumer platforms.
Growth Catalysts
- Pre-lit LED integration:Energy-efficient lighting systems reduce consumer assembly friction and drive repeat purchases in suburban residential segments. The technology lowers total cost of ownership across multi-season use cycles.
- Germany's seasonal retail anchoring:Concentrated December purchasing patterns in German metropolitan centers establish demand benchmarks that influence European inventory planning and product mix decisions.
- USDA APHIS phytosanitary enforcement:Certification requirements on imported fresh-cut specimens elevate artificial tree competitiveness by adding compliance friction to natural alternatives.
Market Restraints
- Petroleum-derived PVC input volatility:Crude oil price fluctuations directly compress manufacturing margins for needle production in Asian manufacturing clusters.
- Single-origin supply concentration:Heavy reliance on Chinese manufacturing for steel frame and PVC needle assembly creates geopolitical exposure and tariff vulnerability.
- California Proposition 65 disclosure mandates:Lead and phthalate labeling requirements impose uniform compliance costs that disproportionately burden smaller artificial tree importers.
Strategic Opportunities
- Biobased needle alternatives:Plant-derived polymer research offers path to petroleum substitution if production scale achieves cost parity within current development cycles.
- Municipal and hospitality procurement:Above-10-foot commercial specimens face limited specialized competition and command premium pricing in public space decoration contracts.
- Online channel capture:Artificial variants requiring no freshness verification migrate from farm stands and supermarkets to digital platforms, enabling direct customer data ownership.
Industry Challenges
- Flame-retardant formulation adaptation:EPA evolving standards on chemical treatments force PVC needle producers to reformulate coatings without performance degradation.
- Quick-assembly hinge engineering:Patent-protected connection systems create licensing complexity for brands seeking to match established setup-time benchmarks.
- Seasonal demand compression:Six-week concentrated selling windows require precise inventory positioning and working capital intensity that strains smaller distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Christmas Tree Market |
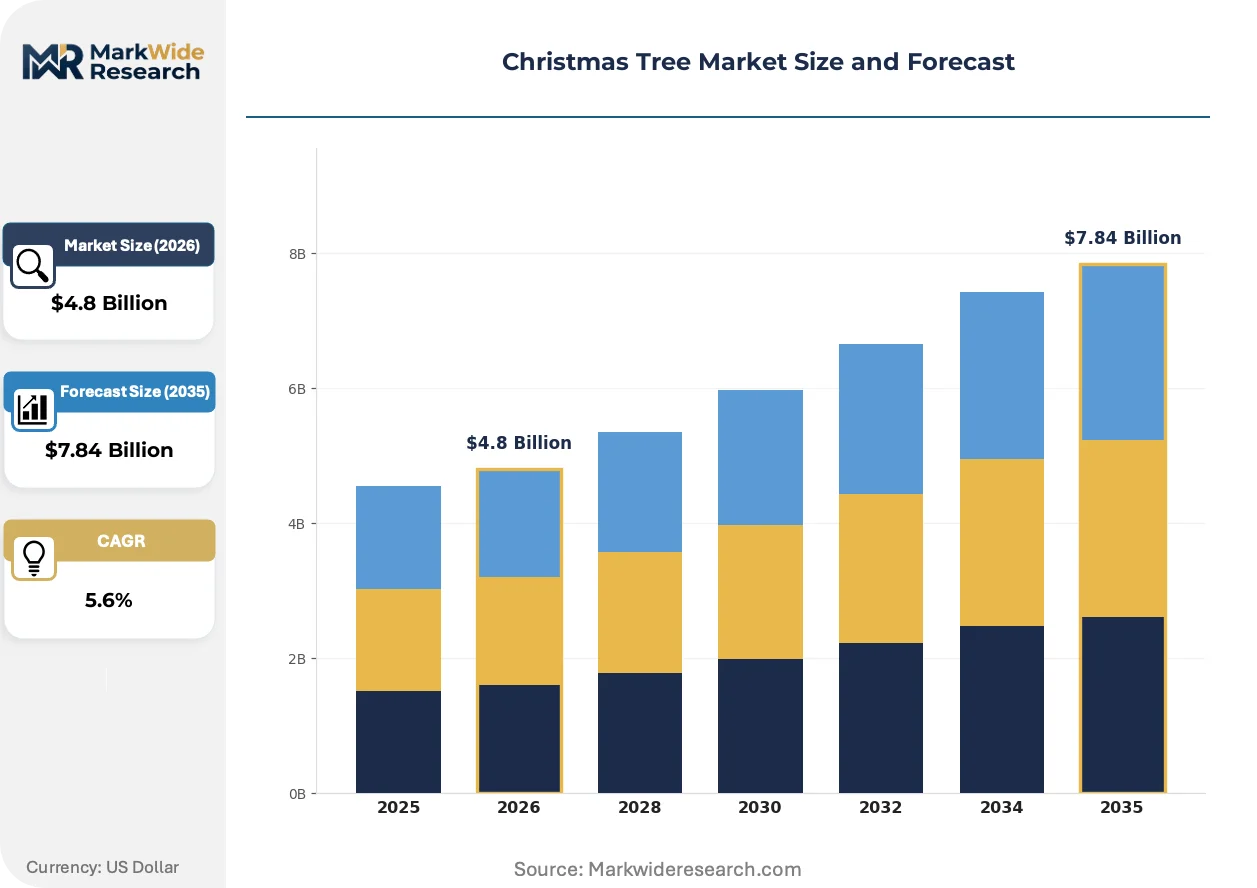
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tree Type: Artificial, Fresh Cut, Potted, Pre-lit Market Segment: Retail, Wholesale, Online Sales, Commercial Distribution Channel: Supermarkets, Specialty Stores, E-commerce, Farm Stands Height: 2-4 feet, 5-7 feet, 8-10 feet, Above 10 feet |
| Companies Covered | Balsam Hill, National Tree Company, Puleo International, Vickerman, King of Christmas, Treetopia, Hallmark, Gordon Companies, Christmastrees.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Christmas Tree Market Emerging Trajectories
Active transformation in the Christmas Tree Market centers on material science advancement, regulatory chemistry evolution, and channel migration away from physical retail verification toward digital convenience.
Polyethylene needle technology is modularizing product architecture in artificial tree manufacturing. PE materials replicate natural needle texture and light reflection more convincingly than conventional PVC. Residential consumers in North American suburban markets are adopting PE-dominant specimens at accelerating rates. The technology is modularizing supply chains by enabling componentized frame and needle sourcing from discrete specialized producers rather than integrated single-facility manufacturing.
REACH chemical registration requirements in the European Union are tightening flame-retardant substance restrictions on imported artificial decorations. Industrial consequence falls heaviest on Chinese exporters serving German and French retail channels, forcing reformulation of PVC needle coatings and steel frame treatments. Affected suppliers are responding by accelerating biobased alternative testing and shifting some assembly to Mexican facilities to access USMCA tariff preferences.
Direct-to-consumer platform purchasing is displacing farm-stand and supermarket verification for artificial tree acquisition. Digital channels eliminate the tactile freshness assessment that natural specimens require, collapsing the traditional retail advantage of physical inspection. This behavioral shift concentrates most visibly in United States suburban households where two-day delivery expectations and hassle-free return policies override in-person selection preferences.
Christmas Tree Market Segmentation
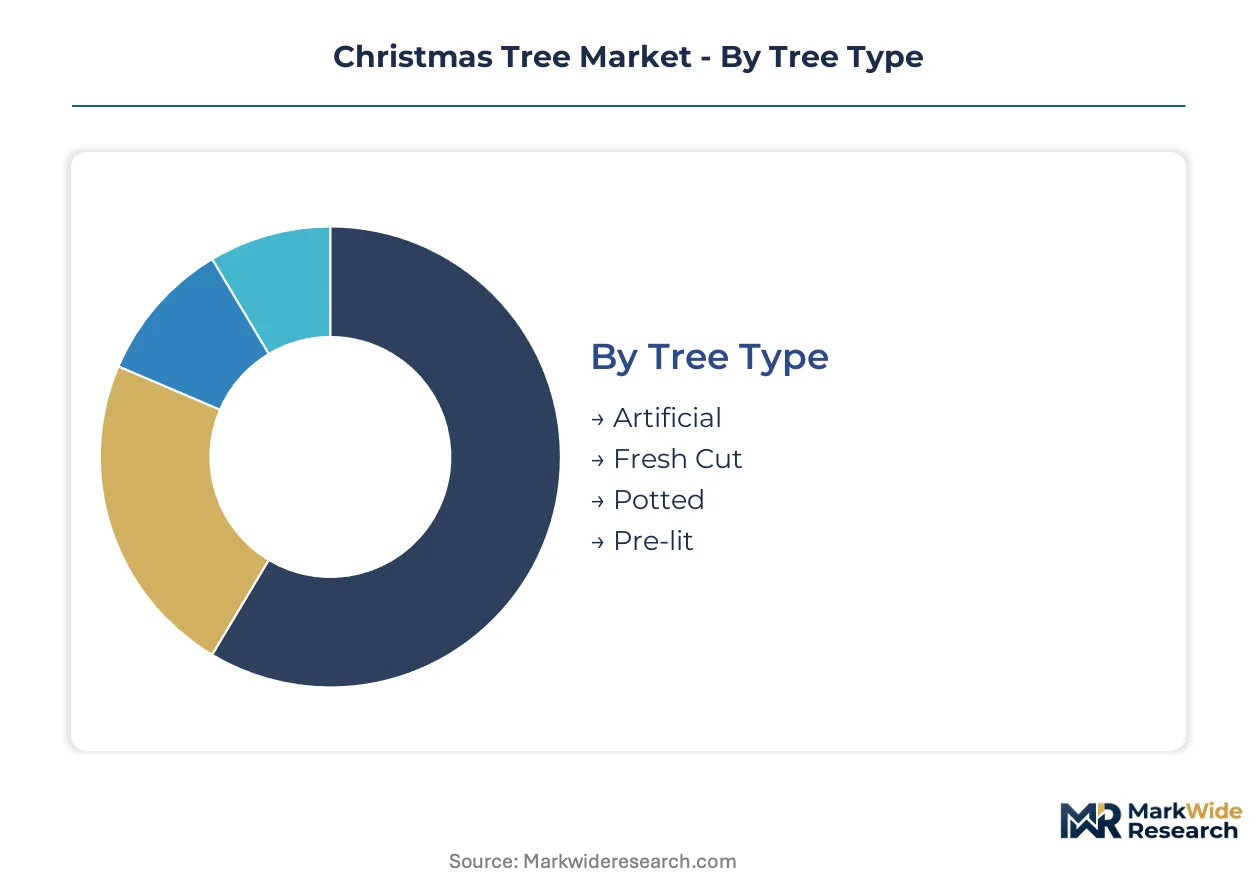
Christmas tree purchasing patterns fragment sharply across use-case durability, channel convenience, and spatial constraints. Upgrade cycles and replacement timing differ fundamentally between artificial inventory investments and annual fresh-cut rituals. Manufacturers and retailers calibrate production, pricing, and merchandising around these divergent behavioral segments.
Tree Type:
Replacement-cycle timing separates artificial purchasers on 7-10 year horizons from fresh-cut buyers locked into annual December rituals. Pre-lit variants compress the upgrade decision by bundling lighting technology obsolescence with tree replacement.
- Artificial:PVC and PE needle constructions on hinged steel frames deliver multi-season durability. Suburban United States households concentrate demand here, driven by convenience preferences and avoidance of USDA APHIS phytosanitary friction on imported fresh specimens.
- Pre-lit:Integrated LED lighting systems eliminate consumer assembly labor and reduce return rates. Germany's concentrated December purchasing patterns anchor European adoption, where energy efficiency regulations accelerate LED substitution.
- Fresh Cut:Balsam fir, Fraser fir, and Nordmann fir specimens require annual replacement and freshness verification. Farm-stand and supermarket channels retain residual share despite digital migration.
- Potted:Living root-ball specimens enable post-holiday replanting or outdoor transition. Limited volume concentrates in environmentally conscious urban households with balcony or garden access.
Artificial sits at the top of the volume ranking, with Pre-lit climbing the fastest as LED technology costs decline and assembly friction becomes a decisive purchase factor.
Market Segment:
Cost-tier differentiation separates high-frequency, low-margin retail transactions from negotiated commercial contracts spanning multiple holiday seasons. Wholesale intermediation is thinning as direct sourcing penetrates mid-scale buyers.
- Retail:Individual household transactions through branded storefronts or digital platforms. United States big-box and specialty channels dominate, with pricing stratifying across premium, standard, and economy tiers based on needle material and lighting integration.
- Commercial:Hospitality, municipal, and corporate procurement of above-10-foot specimens for public space decoration. German city centers and United States hotel chains anchor demand, with multi-year service contracts reducing annual re-sourcing costs.
- Online Sales:Direct-to-consumer platforms bypass physical freshness verification requirements. Artificial variants migrate here fastest where two-day delivery expectations override tactile inspection preferences.
- Wholesale:Bulk aggregation for downstream retail redistribution. Concentrating in Chinese manufacturing clusters for artificial trees and Pacific Northwest distribution hubs for fresh-cut North American supply.
Retail commands absolute volume leadership, while Online Sales gains share fastest as suburban United States households abandon farm-stand verification rituals.
Distribution Channel:
Channel selection correlates directly with tree type verification requirements and consumer time-cost tradeoffs. E-commerce penetration rises where physical inspection delivers no marginal value.
- E-commerce:Digital platforms with return logistics and customer data ownership. Balsam Hill and similar direct-to-consumer operators exploit this channel for artificial and pre-lit variants requiring no freshness assessment.
- Specialty Stores:Curated assortments with assembly service and design consultation. Premium artificial specimens and high-grade fresh cuts concentrate here in German metropolitan retail corridors.
- Supermarkets:Mass-market fresh-cut lots with price-competitive commodity positioning. Seasonal parking-lot installations in United States suburban locations capture convenience-driven December traffic.
- Farm Stands:Direct-from-grower freshness verification and variety selection. USDA APHIS compliance costs compress margins and accelerate share loss to artificial alternatives.
E-commerce leads expansion velocity, though Supermarkets retain the largest transaction volume through seasonal convenience positioning.
Height:
Spatial constraints and use-case formality dictate height selection, with residential ceiling clearance and commercial visual impact operating as distinct demand drivers.
- 5-7 feet:Standard residential ceiling accommodation for single-family suburban dwellings. This band captures the dominant share of United States and German household purchases across both artificial and fresh-cut formats.
- Above 10 feet:Commercial and municipal applications requiring specialized logistics and installation. Limited competition and premium pricing characterize this segment in hospitality and public space contracts.
- 8-10 feet:Large residential or small commercial installations. Demand concentrates in United States households with vaulted ceilings and boutique hospitality properties.
- 2-4 feet:Apartment, tabletop, and secondary space decoration. Compact artificial specimens dominate with minimal fresh-cut penetration due to handling economics.
5-7 feet dominates absolute volume, with Above 10 feet expanding most quickly as commercial property managers professionalize holiday decoration procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters in Guangdong and Zhejiang provinces anchor global artificial tree production, supplying hinged steel frames and PVC needle assemblies to distributors across North America and Europe. Farm-stand channels in the Pacific Northwest and seasonal retail corridors in German metropolitan centers shape complementary demand patterns for fresh-cut specimens.
United States
Suburban households in Texas and Florida drive artificial tree volumes through direct-to-consumer platforms, bypassing traditional farm-stand freshness verification. USDA APHIS phytosanitary certification requirements on imported fresh-cut specimens elevate compliance costs for Canadian and European suppliers. California's Proposition 65 labeling mandates on lead and phthalate disclosure create de facto national compliance thresholds that burden smaller artificial tree importers.
Germany
Concentrated December purchasing patterns in Berlin and Munich metropolitan centers establish European demand benchmarks for pre-lit LED varieties. REACH chemical registration requirements tighten flame-retardant substance restrictions on imported artificial decorations, forcing Chinese exporters to reformulate PVC needle coatings. The Black Forest region retains residual fresh-cut cultivation despite margin compression from phytosanitary compliance.
China
Yiwu commodity markets and Dongguan manufacturing zones supply the majority of global artificial tree components, from steel hinge systems to molded PE needle branches. The Ministry of Ecology and Environment enforces evolving standards on industrial chemical emissions from PVC processing facilities. Guangdong province is accelerating biobased polymer testing to anticipate European regulatory shifts away from petroleum-derived materials.
Canada
Balsam fir and Fraser fir exports from Nova Scotia and Quebec face heightened USDA APHIS inspection protocols at United States border crossings, lengthening delivery windows during critical November inventory positioning. Health Canada and the Pest Management Regulatory Agency coordinate phytosanitary certification reciprocity with United States counterparts. British Columbia's Pacific coastal valleys concentrate domestic fresh-cut cultivation for westward United States distribution.
Mexico
Assembly operations in Tijuana and Monterrey are capturing artificial tree production migrating from Chinese facilities seeking USMCA tariff preferences and reduced shipping distances to United States consumers. The Secretariat of Economy monitors compliance with North American product safety standards for re-export qualification. Baja California manufacturing parks are specializing in quick-assembly hinge system integration for premium artificial specimens.
Christmas Tree Market Vendor Landscape
Global majors compete with regional champions across digital channel control and manufacturing scale. The vendor base clusters around three strategic archetypes: vertically integrated Asian fabricators owning captive steel and polymer production, direct-to-consumer digital specialists capturing customer data and pricing power, and lighting engineering specialists patenting assembly-reduction technologies. Dominant competitive moves include backward integration into hinge system manufacturing and strategic partnerships with biobased material research consortia.
Within the direct-to-consumer archetype, Balsam Hill exemplifies pricing control through owned digital channels and customer data accumulation across North American suburban households. National Tree Company anchors the vertically integrated tier with manufacturing ownership spanning China and Mexico. Puleo International occupies the engineering-specialist position through patented quick-assembly hinge systems and concentrated lighting technology development.
| Leading Market Players |
|---|
| Balsam Hill |
| National Tree Company |
| Puleo International |
| Vickerman |
| King of Christmas |
| Treetopia |
| Hallmark |
| Gordon Companies |
| Christmastrees.com |
| Others |
Supply Flow & Price Mechanics
Crude oil price volatility cascades through PVC needle production costs in Guangdong manufacturing clusters, compressing margins for economy-tier artificial trees while premium PE-dominant specimens absorb input swings through brand pricing power. This cost pass-through dynamic stratifies the market into three distinct tiers where petroleum-derived material exposure determines competitive positioning.
Pricing Analysis
Input-cost pass-through from petroleum-derived PVC resin governs pricing dynamics across artificial tree tiers. Three-tier pricing structure across premium, standard, and economy levels separates PE-dominant specimens with natural needle replication from basic PVC constructions. Price differentiation hinges on lighting integration depth and hinge system patent licensing costs. Cost compression in economy tiers is intensifying because of crude oil volatility and Chinese environmental compliance upgrades. Suburban United States households in Texas and Florida exhibit lowest price sensitivity for pre-lit convenience, while supermarket fresh-cut purchasers demonstrate highest elasticity to seasonal discounting.
Supply Chain Analysis
Steel frame and PVC needle supply rests on Chinese manufacturing ownership in Guangdong and Zhejiang provinces, with secondary assembly migration to Tijuana and Monterrey facilities seeking USMCA tariff preferences. Raw material feeds from petroleum-derived polymer processors, specialty steel coil producers, and LED lighting component fabricators. Single-origin concentration in Chinese coastal manufacturing zones creates tariff exposure and geopolitical vulnerability. Distribution runs through direct-to-consumer platforms for artificial variants, bypassing traditional farm-stand freshness verification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Christmas Tree Market functions as a stable compounder anchored by seven-to-ten year replacement cycles for artificial inventory investments. Residential convenience preferences in suburban North American households generate predictable recurring demand.
For Market Incumbents: To counter digital-native entrants capturing customer data through owned e-commerce platforms, National Tree Company and vertically integrated peers should deepen in-house production of patented hinge systems while establishing captive PE needle fabrication in Mexican assembly parks. Certification investment in California Proposition 65 compliance creates defensive moats against smaller importers burdened by uniform disclosure costs. For New Entrants and Emerging Players: Direct-to-consumer platform routes offer lowest customer acquisition friction for artificial and pre-lit variants requiring no tactile freshness assessment. Municipal and hospitality procurement of above-10-foot commercial specimens presents the most penetrable white-space target, given limited specialized competition and premium pricing power. A go-to-market angle centered on quick-assembly engineering and multi-year service contracts displaces incumbent annual re-sourcing relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with biobased material specialists achieving cost parity with petroleum-derived PVC before the next full product development cycle. The five-to-ten year viability window favors acquisition targets with lighting engineering patents and established direct-to-consumer data infrastructure. Watch for EPA flame-retardant formulation rulings as inflection indicators that would force accelerated reformulation investment across Chinese exporter supply bases.| Strategic Initiative | Industry Significance |
|---|---|
| Biobased Polymer Scale-Up | Plant-derived needle alternatives from Guangdong testing facilities anticipate European REACH regulatory shifts away from petroleum materials. |
| Direct-to-Consumer Channel Expansion | Owned digital platforms bypass farm-stand verification rituals and capture customer data across United States suburban households. |
| Quick-Assembly Patent Licensing | Protected hinge systems from Puleo International and similar engineering specialists create setup-time benchmarks competitors must license or match. |
| USMCA Manufacturing Migration | Tijuana and Monterrey assembly operations reduce tariff exposure and shipping distances to Texas and Florida demand centers. |
| Pre-lit LED Integration | Energy-efficient lighting systems lower total cost of ownership and drive repeat purchases in Germany's concentrated December purchasing patterns. |
Methodological Framework
Coverage spans United States, Germany, China, Canada, and Mexico, with primary inputs from each market cluster combining structured interviews with supply chain directors at artificial tree manufacturers, category buyers at United States big-box retailers, and regulatory affairs specialists at phytosanitary certification bodies. Secondary validation drew from USDA APHIS enforcement records, EPA chemical formulation standards, REACH registration databases, and customs trade flow documentation. Bottom-up unit volume modeling triangulated against top-down value estimates across tree type and height segmentation dimensions.
Granularity-level modeling operated at country-by-tree-type-by-height band resolution, with separate projections for artificial PVC, artificial PE, pre-lit LED, fresh-cut, and potted specimens. CAGRs were derived from replacement-cycle timing analysis and channel migration velocity across the projection horizon. Industry-specific forecast inputs included petroleum price trajectory assumptions and biobased polymer cost-parity timelines.
The model assumes a particular technology adoption path for PE needle substitution; alternative pathways for biobased material commercialization would alter the outlook for petroleum-dependent PVC producers. Forecasts reflect assumptions regarding regulatory enforcement continuity at USDA APHIS and EPA. A small set of named triggers warrants ongoing watch: crude oil price spikes, REACH flame-retardant restriction tightening, and USMCA tariff preference modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Smart Curtain Market
Homecare and Decor
Bulletin Board Market
Homecare and Decor
Asia-Pacific Wall Covering Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Pillow Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
Home Decor Market