
 China Camping Tent Market | 2026-2036
China Camping Tent Market Size, Share, and Industry Trends Forecast 2026-2036
China Camping Tent Market Insights
The capital-intensity gap between mass-market assemblers and technical fabric developers is collapsing as waterproof-breathable membrane costs decline. Ningbo Naturehike leverages direct-to-consumer digital channels to sustain margin control across mid-tier backpacking lines. Zhejiang Mobi anchors its position through in-house production of aluminum alloy poles and ripstop nylon. Guangzhou Fastup Tent Manufacturing competes on rapid OEM turnaround for festival and event rental operators.
China camping tents are portable shelter structures engineered with hydrostatic-head-rated fabrics, seam-taped construction, and geodesic or tunnel pole architectures designed to withstand wind loads and precipitation in outdoor environments. Polyester and ripstop fabric dominate material selection for recreational applications, while PU-coated fabric variants command premium positioning in expedition-grade products where waterproofing thresholds exceed standard leisure specifications. Dome tent configurations lead volume sales through leisure camping channels, whereas backpacking tent demand accelerates fastest among lightweight-focused outdoor enthusiasts seeking sub-two-kilogram packed weights. Tunnel tent and cabin tent categories occupy stable niches in family and basecamp segments where interior volume priorities override portability constraints.
SAMR enforces mandatory GB standards for textile flammability and structural stability in camping equipment sold domestically, while provincial environmental bureaus under MEE monitor VOC emissions from PU coating processes in Zhejiang manufacturing zones. BIS-equivalent conformity assessments for export-bound tents add compliance layers for producers serving Indian or Middle Eastern markets through third-party logistics hubs. Stakeholders must monitor how China's dual carbon goals reshape energy-intensive fabric treatment operations and whether coastal province carbon quotas force production relocation inland.
Market Dynamics
China's dual carbon goals are forcing fabric treatment facilities to relocate from coastal Zhejiang and Guangdong provinces to inland energy zones, restructuring where waterproof-breathable membrane production can operate profitably.
Growth Catalysts
- Adventure tourism policy support:Provincial tourism bureaus in Sichuan and Yunnan are subsidizing outdoor recreation infrastructure, directly expanding addressable demand for technical shelter products.
- SAMR safety standard updates:Mandatory GB standards for textile flammability and structural stability are accelerating replacement cycles among domestic recreational users.
- Lightweight fabric innovation:Ripstop nylon with improved tear strength-to-weight ratios is enabling sub-two-kilogram backpacking tent categories that command premium positioning.
Market Restraints
- PU coating input volatility:Petroleum-derived polyurethane resin prices fluctuate with crude oil benchmarks, compressing margin predictability for waterproof fabric specialists.
- Aluminum alloy pole concentration:Domestic supply of 7000-series aluminum for tent poles concentrates among three Jiangsu smelters, creating single-source vulnerability.
- Silicone fabric substitution threat:Silicone-coated nylon variants from Taiwanese suppliers are displacing PU-coated alternatives in expedition-grade segments due to superior UV resistance.
Strategic Opportunities
- Inland province manufacturing migration:Sichuan and Chongqing offer carbon quota headroom and lower energy costs for fabric treatment operations facing coastal restrictions.
- Rental operator channel expansion:Festival and glamping site operators represent an underpenetrated B2B segment seeking durable, rapid-deployment shelter fleets.
- Cross-border e-commerce integration:Direct-to-consumer platforms are collapsing traditional export distributor margins for technical backpacking lines.
Industry Challenges
- Seam-taping technician shortage:Skilled operators for hot-tape waterproof seam sealing are scarce in inland relocation zones, constraining quality throughput.
- BIS-equivalent certification timelines:Export-bound producers serving Indian markets face extended third-party conformity assessment periods that delay revenue recognition.
- Legacy dye house integration:Coastal fabric finishers lack capital to replicate VOC-compliant coating lines in new inland facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Camping Tent Market |
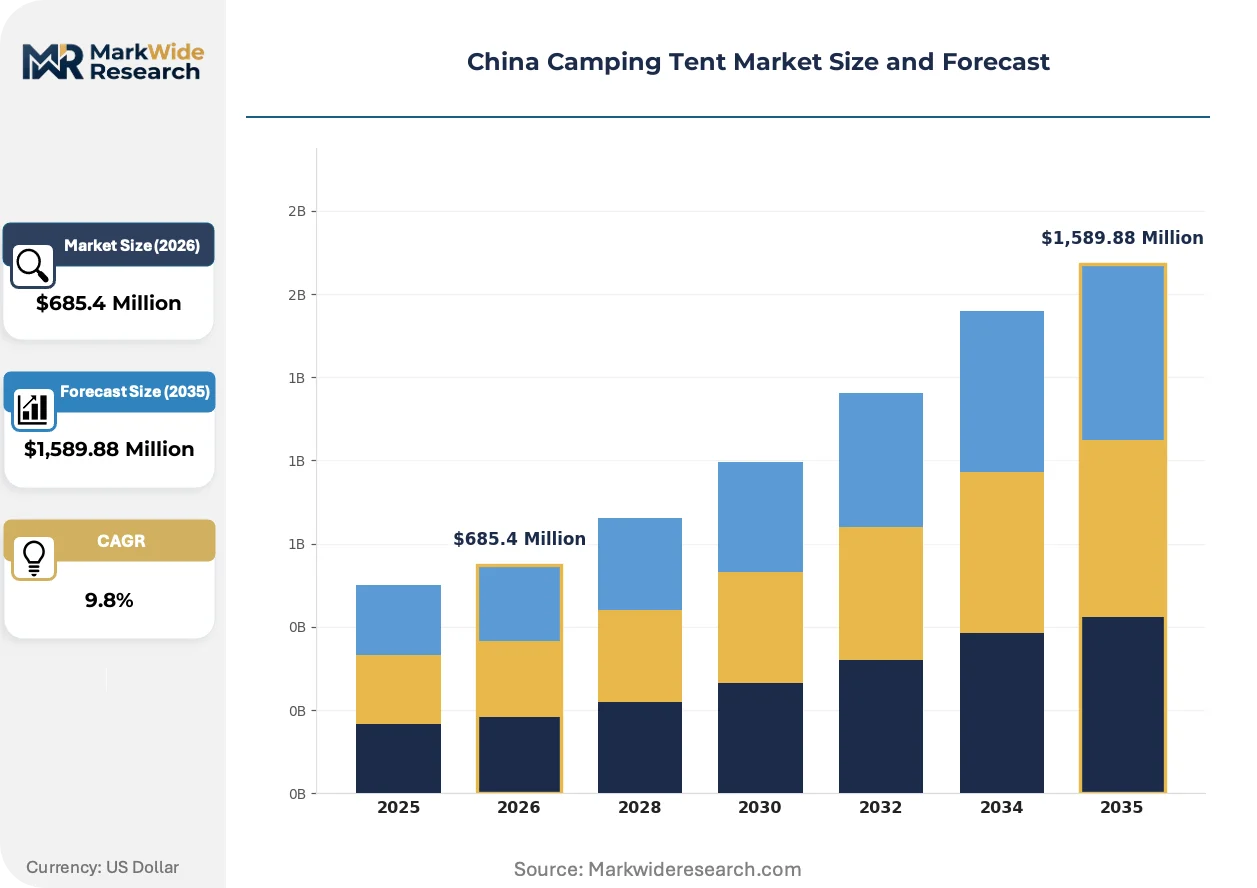
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,589.88 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Tent, Cabin Tent, Tunnel Tent, Pop-up Tent, Backpacking Tent Material: Polyester, Nylon, Canvas, Ripstop Fabric, PU-Coated Fabric, PVC Application: Leisure Camping, Expedition Camping, Adventure Touring, Festival Camping, Wildlife Observation End User: Outdoor Enthusiasts, Scouts, Travel Agencies, Sports Clubs, Educational Institutes, Military Units |
| Companies Covered | Liri Architecture Technology (Guangdong), Guangzhou Fastup Tent Manufacturing Co., Ltd., Ningbo Naturehike, Wild Land, Superb Tent Co., Ltd., Hangzhou Everich Outdoor, Changzhou Expo Tent Co., Ltd. (ExpoTent), ENJOIN, Zhejiang Mobi (Mobi Garden), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Camping Tent Market Trends and Innovations
Waterproof-breathable membrane technology is compressing the performance gap between mass-market and expedition-grade shelter products, while regulatory pressure on coating emissions accelerates process innovation.
Silicone-impregnated fabric is miniaturizing the weight penalty for hydrostatic-head ratings above 3000mm. Backpacking enthusiasts are adopting silicone-coated nylon at triple the rate of conventional PU alternatives. This material shift is miniaturizing the distinction between recreational and technical product tiers, forcing mid-market brands to reposition on features rather than fabric grade alone.
SAMR's updated GB standards for camping equipment flammability are mandating flame-retardant additive integration in polyester and nylon substrates. Domestic manufacturers serving the China market must reformulate fabric treatments or exit recreational segments. Zhejiang coating houses are responding by importing halogen-free FR chemistries from German specialty suppliers, adding 15-20% to input costs.
Direct-to-consumer digital channels are displacing traditional outdoor retail distributors for technical tent sales. Young urban outdoor enthusiasts in Shanghai and Chengdu research specifications through social platforms and purchase through brand-flagship stores, bypassing multi-brand retailers. This channel rotation is most pronounced in the 25-35 age demographic, where brand-owned content drives preference formation before physical product handling.
China Camping Tent Market Segmentation
Segmentation in China's camping tent market reveals how material substitution and application specialization are fragmenting what was once a uniform recreational goods category. Distinct buyer requirements across leisure, expedition, and institutional channels reward manufacturers who configure product architectures around specific stress factors rather than generic portability.
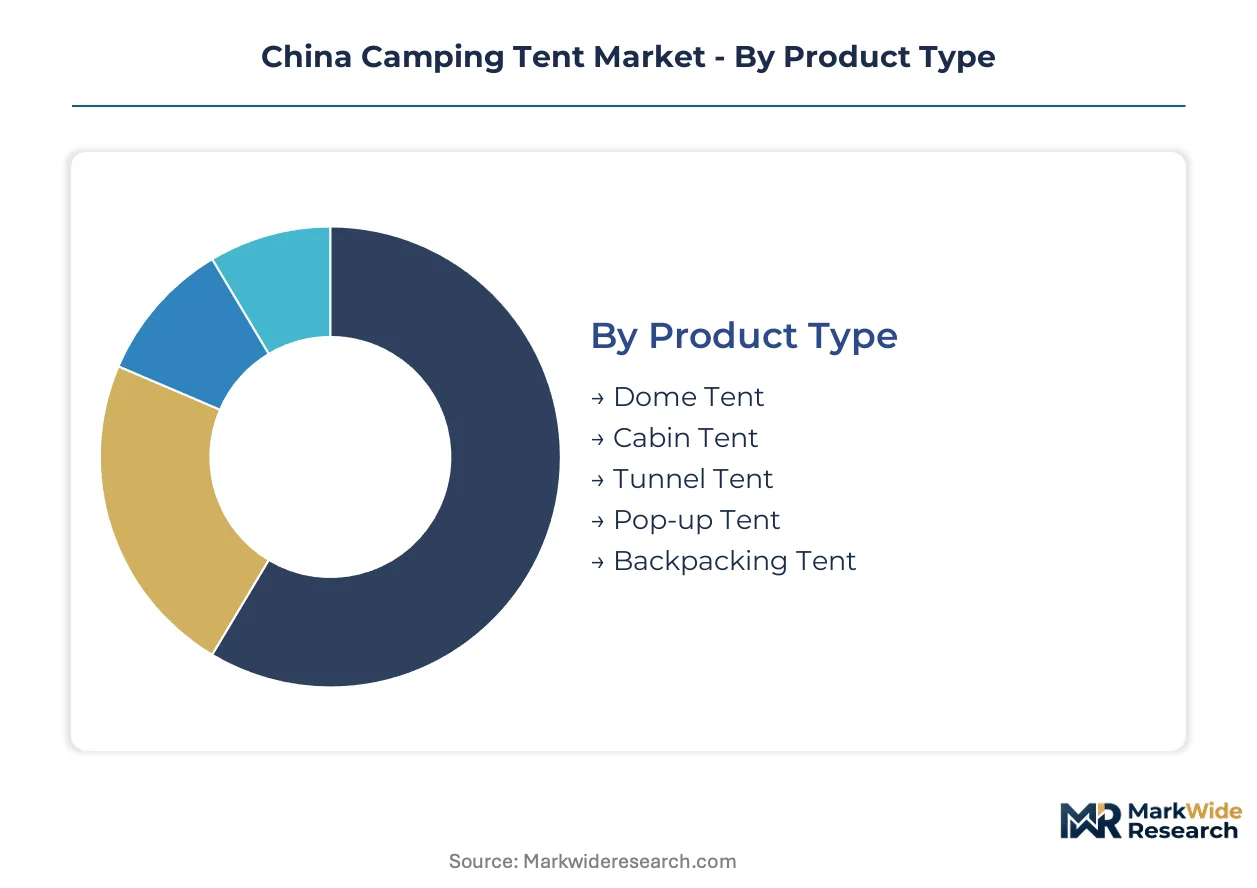
Product Type:
Silicone-coated nylon variants from Taiwanese suppliers are displacing traditional dome and cabin configurations in technical segments, reshaping which structural formats can command sustained margin premiums.
- Dome Tent:Geodesic pole architecture distributes wind loads across multiple intersection points, enabling freestanding stability without guy-out tension. Demand concentrates in Zhejiang and Guangdong family leisure channels where SAMR's updated flammability standards accelerate replacement purchases from domestic recreational users. Dome Tent retains volume leadership; Backpacking Tent holds the steepest expansion curve.
- Backpacking Tent:Sub-two-kilogram packed weights require silicone-impregnated ripstop nylon and truncated pole segments. Sichuan and Yunnan adventure tourism infrastructure subsidies are expanding addressable demand among young urban outdoor enthusiasts in Chengdu who research specifications through social platforms.
- Cabin Tent:Vertical wall geometry maximizes interior headroom for extended basecamp occupancy. Guangzhou Fastup Tent Manufacturing serves festival rental operators with rapid-deployment configurations.
- Tunnel Tent:Extended vestibule volumes accommodate gear storage and cooking operations in exposed conditions. Stable niche in family segments where interior volume priorities override portability constraints.
- Pop-up Tent:Pre-tensioned spring-pole mechanisms enable sub-minute assembly for casual recreational users. Mass-market assemblers compete on OEM turnaround speed for seasonal retail cycles.
Dome Tent retains volume leadership; Backpacking Tent holds the steepest expansion curve.
Material:
Cost tier stratification separates petroleum-dependent coating processes from emerging silicone-impregnated alternatives that sidestep MEE VOC monitoring requirements.
- PU-Coated Fabric:Polyurethane resin treatments deliver hydrostatic-head ratings for standard recreational waterproofing. Jiangsu smelter concentration in 7000-series aluminum pole supply creates complementary vulnerability for complete shelter systems. PU-Coated Fabric retains volume leadership; Silicone-impregnated alternatives gain share fastest.
- Ripstop Fabric:Reinforced weave patterns interrupt tear propagation through interwoven thicker yarns. Ningbo Naturehike leverages direct-to-consumer digital channels to sustain margin control across mid-tier backpacking lines utilizing this substrate.
- Silicone-Coated Nylon:UV-resistant surface chemistry extends fabric lifespan in high-altitude exposure conditions. Taiwanese suppliers are displacing PU alternatives in expedition-grade segments.
- Polyester:Hydrophobic fiber structure resists moisture absorption and sagging in humid environments. Dominates material selection for recreational applications.
- Nylon:Superior tear strength-to-weight ratio enables lightweight architectural configurations. Zhejiang Mobi anchors position through in-house production integration.
- Canvas:Heavy cotton duck construction provides breathable durability for glamping and basecamp applications. Higher packed weight limits mobility-focused adoption.
- PVC:Thermoplastic sheeting for temporary shelter and event rental applications where packed bulk is secondary to cost minimization.
PU-Coated Fabric retains volume leadership; Silicone-impregnated alternatives gain share fastest.
Application:
Customer type divergence separates institutional procurement cycles from impulse-driven recreational purchases, with distinct channel requirements for each.
- Leisure Camping:Weekend recreational use in designated campgrounds with vehicle access and established facilities. Zhejiang and Guangdong e-commerce fulfillment infrastructure concentrates demand.
- Expedition Camping:Multi-day unsupported journeys in remote terrain requiring weather resilience and repairability. Sichuan and Yunnan provincial tourism bureau subsidies expand technical shelter demand.
- Adventure Touring:Motorcycle and bicycle-mounted mobility requiring compact packed dimensions and rapid pitch sequences. Fastest-expanding buyer segment as domestic adventure tourism gains traction.
- Festival Camping:Temporary occupancy for music and cultural events prioritizing aesthetic differentiation and social media visibility. Rental operator channel expansion represents underpenetrated B2B opportunity.
- Wildlife Observation:Concealed positioning and extended stationary occupancy for nature photography and research. Specialized requirements limit mass-market penetration.
Leisure Camping retains volume leadership; Adventure Touring holds the steepest expansion curve.
End User:
Supply concentration in coastal manufacturing clusters dictates procurement patterns for institutional buyers versus dispersed individual purchasing through digital channels.
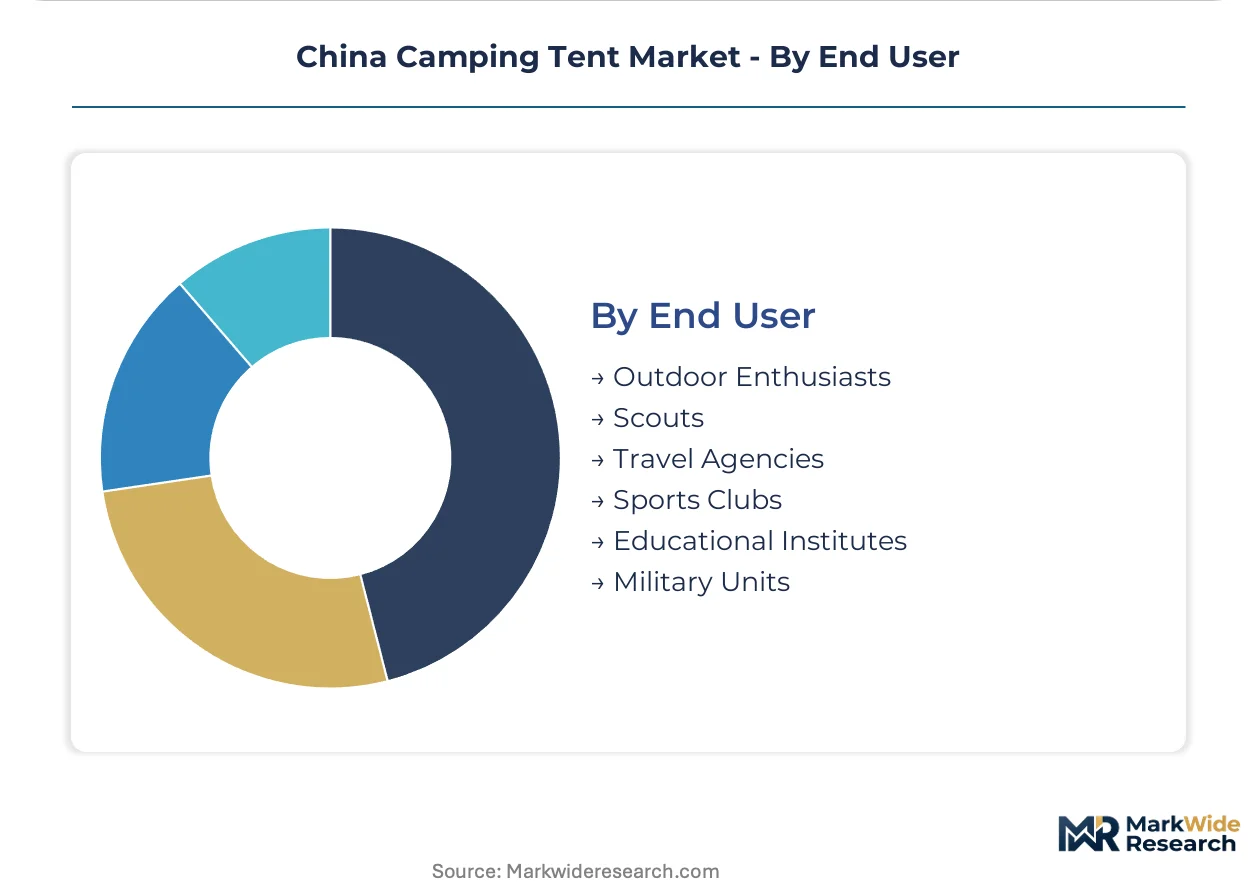
- Outdoor Enthusiasts:Self-directed recreational consumers researching technical specifications through brand-owned content. Shanghai and Chengdu 25-35 demographic bypasses multi-brand retailers for direct-to-consumer platforms.
- Travel Agencies:Packaged tour operators sourcing standardized fleet configurations for group deployment. Procurement concentrates through Guangdong OEM channels.
- Scouts:Youth organization durability requirements and institutional procurement cycles. Volume pricing negotiations favor established supplier relationships.
- Sports Clubs:Team-based outdoor activity coordination with seasonal equipment turnover. Replacement cycles align with SAMR safety standard update timelines.
- Educational Institutes:Curricular outdoor education programs requiring institutional durability certifications. Budget constraints favor economy-tier configurations.
- Military Units:Tactical shelter specifications with camouflage and signature management requirements. Specialized procurement outside commercial market channels.
Outdoor Enthusiasts retain volume leadership; Travel Agencies hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adventure tourism subsidies in Sichuan and Yunnan attract price-insensitive technical buyers, while mass-market leisure purchasers in coastal provinces remain highly elastic to promotional pricing.
Yangtze River Delta
Zhejiang province hosts the densest concentration of tent fabricators, with Ningbo and Hangzhou anchoring ripstop nylon production and aluminum pole fabrication. SAMR's updated GB flammability standards are accelerating equipment replacement cycles among domestic recreational users. E-commerce fulfillment infrastructure in Yiwu and Shaoxing enables same-day delivery to Shanghai and Hangzhou consumers.
Pearl River Delta
Guangdong's festival economy and glamping site expansion drive demand for rapid-deployment cabin configurations. Provincial environmental bureaus under MEE monitor VOC emissions from PU coating processes in Dongguan and Foshan manufacturing zones. Guangzhou-based OEM channels serve travel agency procurement for standardized fleet deployment.
Sichuan-Chongqing
Provincial tourism bureau subsidies for outdoor recreation infrastructure are expanding addressable demand among young urban enthusiasts in Chengdu. Dual carbon goals are forcing fabric treatment facilities to relocate from coastal provinces to inland energy zones with available carbon quota headroom. Chongqing's lower industrial electricity rates attract waterproof-breathable membrane producers facing Zhejiang restrictions.
Beijing-Tianjin-Hebei
Capital region consumers exhibit strong preference for direct-to-consumer digital channels when researching technical specifications. SAMR enforces mandatory GB standards for textile flammability and structural stability across camping equipment sold through Beijing and Tianjin retail networks. Hebei's manufacturing base supplies economy-tier polyester configurations for educational institute procurement.
Shandong Peninsula
Qingdao and Yantai port infrastructure supports export-bound production serving Indian markets through third-party logistics hubs. BIS-equivalent conformity assessments add compliance layers for producers targeting South Asian distribution channels. Coastal fabric finishers face capital constraints when replicating VOC-compliant coating lines inland.
China Camping Tent Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-market assemblers competing on OEM turnaround speed. The structure rewards backward integration into aluminum pole production and ripstop nylon weaving. Three archetypes dominate: coastal fabric treatment specialists with VOC compliance capabilities, inland relocators leveraging carbon quota headroom, and direct-to-consumer digital natives. Competitive moves center on inland manufacturing migration and cross-border e-commerce platform integration.
Within the integrated leader tier, Zhejiang Mobi and Ningbo Naturehike exemplify divergent strategic positions. Guangzhou Fastup Tent Manufacturing Co., Ltd. occupies a distinct niche serving festival rental operators with rapid-deployment configurations. These three entities represent the spectrum from in-house production integration to digital-native channel control.
| Leading Market Players |
|---|
| Liri Architecture Technology (Guangdong) |
| Guangzhou Fastup Tent Manufacturing Co., Ltd. |
| Ningbo Naturehike |
| Wild Land |
| Superb Tent Co., Ltd. |
| Hangzhou Everich Outdoor |
| Changzhou Expo Tent Co., Ltd. (ExpoTent) |
| ENJOIN |
| Zhejiang Mobi (Mobi Garden) |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Zhejiang coating houses sits above eighty percent during peak seasonal cycles, compressing margin buffers for mid-tier assemblers while concentrating pricing power among integrated producers with captive fabric treatment lines. This scale asymmetry forces smaller OEMs to accept thinner margins or exit technical segments entirely.
Pricing Analysis
After-sales service revenue from pole replacement kits and seam-tape repair patches drives lifetime value for established brands. Three-tier pricing structure across premium silicone-impregnated, standard PU-coated, and economy polyester configurations dominates transactional sales. Pricing pressure stems from Taiwanese silicone-coated nylon imports displacing domestic PU alternatives in expedition-grade segments. Individual outdoor enthusiasts in Chengdu and Shanghai exhibit lowest price sensitivity, while educational institute procurement teams negotiate aggressively on volume tenders.
Supply Chain Analysis
China and Taiwan anchor global supply for waterproof-breathable membranes and silicone-impregnated ripstop nylon, with South Korea supplying specialized 7000-series aluminum alloys for tent pole fabrication. Domestic production draws from petroleum-derived polyurethane resins, Jiangsu-sourced aluminum extrusions, and German-imported halogen-free flame retardant chemistries. Single-source vulnerability concentrates in Jiangsu smelter supply for 7000-series aluminum. Distribution runs through Yiwu and Shaoxing e-commerce fulfillment hubs serving direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as adventure tourism subsidies fragment demand across technical backpacking, festival rental, and glamping site operator segments. Channel specialization rewards players who configure operations around specific buyer archetypes rather than generic recreational positioning.
For Market Incumbents: Compound defensive positioning through backward integration into aluminum pole production and captive ripstop nylon weaving. SAMR flammability standard updates threaten non-compliant coastal finishers; incumbents should accelerate inland facility relocation to Sichuan energy zones with available carbon quota headroom. Certification investment in BIS-equivalent conformity assessments protects Indian export revenue streams against extended third-party assessment timelines. For New Entrants and Emerging Players: Anchor in festival and glamping site operator procurement as the most penetrable B2B white space. Sichuan-Chongqing manufacturing migration offers carbon quota advantages for fabric treatment entrants. Direct-to-consumer digital platforms provide go-to-market angle bypassing entrenched distributor relationships in coastal provinces. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated producers with inland carbon quota access and VOC-compliant coating capabilities. Long-term viability hinges on fabric treatment technology transitions and channel control architecture. Acquisition target archetype: coastal fabric finishers with capital-constrained inland relocation capability. Signal to watch: MEE enforcement intensity in Dongguan and Foshan manufacturing zones as indicator of forced migration timeline.| Strategic Initiative | Industry Significance |
|---|---|
| Inland Manufacturing Migration | Sichuan and Chongqing carbon quota headroom attracts waterproof-breathable membrane producers facing Zhejiang restrictions. |
| Direct-to-Consumer Platform Integration | Brand-flagship stores bypass multi-brand retailers for Shanghai and Chengdu 25-35 demographic. |
| Silicone-Coated Fabric Transition | Taiwanese silicone-impregnated nylon displaces PU alternatives in expedition-grade segments. |
| Flame Retardant Certification Investment | SAMR GB standard compliance requires German-imported halogen-free chemistries adding input cost. |
| Rental Operator Channel Expansion | Festival and glamping site operators represent underpenetrated B2B segment seeking rapid-deployment fleets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAMR regulatory filings, MEE environmental compliance records, and provincial tourism bureau subsidy disclosures. Primary interviews engaged product development directors at integrated tent manufacturers, procurement managers at festival rental operators, coating house technical supervisors in Zhejiang, and e-commerce platform category buyers. Secondary validation drew from customs export data, SEC filings of listed outdoor equipment companies, and China Tourism Academy adventure tourism statistics. Bottom-up demand modeling triangulates against top-down production capacity assessments.
Segmentation dimensions modeled include product architecture type, fabric substrate chemistry, end-use application, and buyer channel across the projection horizon. CAGRs derive from trend extrapolation of lightweight fabric adoption rates and adventure tourism infrastructure deployment. Industry-specific forecast inputs incorporate MEE carbon quota allocation trajectories and SAMR standard implementation timelines.
Decision-makers should treat outputs as directional under assumptions of continued dual carbon policy enforcement and stable petroleum-derived input pricing; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
New Zealand Camping Equipment Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Camping Cooler Market
Outdoor Gear
Germany Camping Equipment Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Rooftop Tent Market