
 Global People and HR Analytics Software Market | 2026-2036
Global People and HR Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global People and HR Analytics Software Market Foresight
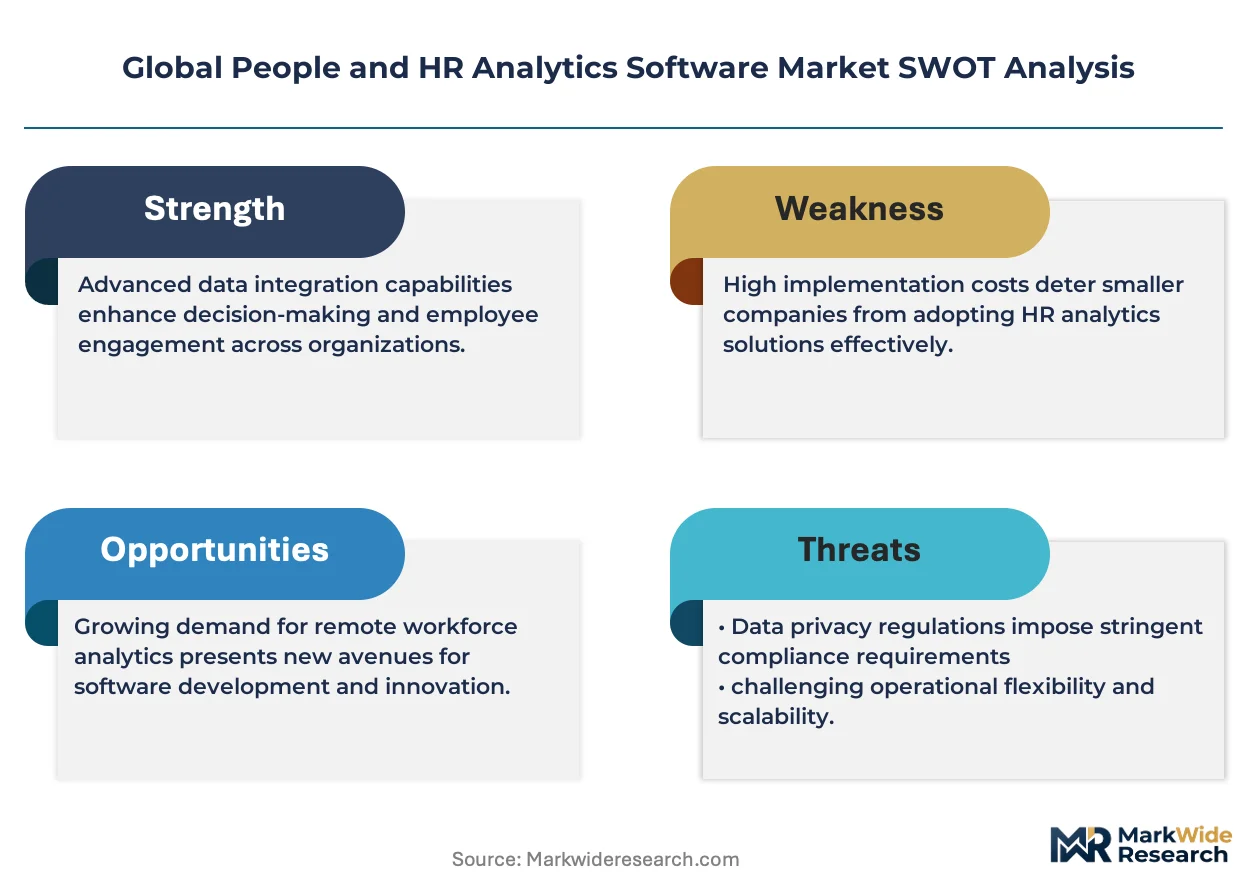
Subscription-based delivery of software-defined workforce intelligence is hardening into the dominant commercial model for HR analytics vendors. Workday leverages its native cloud architecture to anchor large-enterprise deployments across North America and Europe. SAP sustains competitive pressure through deep ERP integration that captures workforce data at the source of financial and operational systems. Oracle differentiates by extending its database-layer dominance into predictive talent analytics, controlling the infrastructure stack beneath application logic.
People and HR analytics software comprises algorithmic platforms that ingest structured and unstructured employee data—demographics, performance ratings, engagement surveys, compensation history, and digital collaboration metadata—to generate predictive models and prescriptive workforce recommendations. These systems employ machine learning pipelines, natural language processing for sentiment extraction, and statistical forecasting engines to reduce attrition, optimize compensation allocation, and identify succession risks. Cloud-based deployment leads absolute spending as multi-tenant architectures reduce implementation friction and accelerate time-to-value for mid-market buyers. Talent acquisition analytics represents the fastest-expanding solution type as labor market volatility intensifies demand for predictive hiring quality metrics. Workforce planning analytics occupies concentrated margin pools among vendors serving regulated industries with complex compliance reporting obligations.
The EU AI Act imposes mandatory risk classification and human oversight requirements on automated employment decision systems, directly shaping product roadmaps for vendors serving European corporate HR departments. In the United States, the EEOC enforces disparate impact standards that constrain algorithmic scoring in hiring and promotion workflows, while state-level biometric privacy laws in Illinois and California restrict facial analysis and emotional inference tools. The SEC's emerging human capital disclosure mandates for public companies are expanding board-level demand for standardized workforce metrics. Stakeholders must monitor the divergence between European algorithmic accountability frameworks and the fragmented U.S. federal-state regulatory patchwork when architecting product compliance strategies and geographic market prioritization.
Market Dynamics
Cloud-native workforce intelligence platforms are compressing implementation timelines from quarters to weeks, eroding the competitive moat of legacy on-premise HR systems and forcing incumbent vendors to rearchitect delivery models around multi-tenant SaaS infrastructure.
Growth Catalysts
- EU AI Act compliance mandates:European employers must deploy auditable algorithmic hiring systems with human oversight, creating immediate replacement demand for opaque legacy tools.
- Financial services talent risk management:Banks and insurers face Basel and Solvency II workforce disclosure pressures, accelerating procurement of predictive attrition and succession analytics.
- Natural language processing pipelines:Sentiment extraction from employee communications and engagement surveys now operates at scale, enabling real-time organizational health monitoring.
Market Restraints
- Cross-border data localization requirements:China's PIPL and Russia's data sovereignty rules fragment cloud architectures, forcing vendors to maintain region-locked infrastructure that duplicates engineering overhead.
- Algorithmic bias litigation exposure:EEOC disparate impact enforcement and Illinois BIPA biometric claims create liability uncertainty that extends enterprise sales cycles.
- Skills-based hiring substitution:Employers bypass traditional credential analytics by adopting direct assessment platforms, reducing dependency on historical workforce data models.
Strategic Opportunities
- India's digital HR transformation:PLI scheme incentives and RBI workforce reporting mandates for financial institutions create a high-growth entry market for cloud analytics vendors.
- Frontline worker analytics:Hourly workforce segments in retail and logistics remain underserved by existing platforms optimized for salaried knowledge workers.
- ISO 30414 human capital reporting:Standardized workforce disclosure frameworks enable vendors to sell pre-configured compliance dashboards to multinational issuers.
Industry Challenges
- Machine learning engineering scarcity:Vendors compete for talent capable of building production-grade fairness auditing and explainability systems.
- ERP integration complexity:Fragmented customer tech stacks spanning Workday, SAP, Oracle, and niche payroll systems demand costly custom connector development.
- Consent management at scale:Employee data rights under GDPR and emerging US state privacy laws require continuous re-permissioning infrastructure that degrades model training data freshness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global People and HR Analytics Software Market |
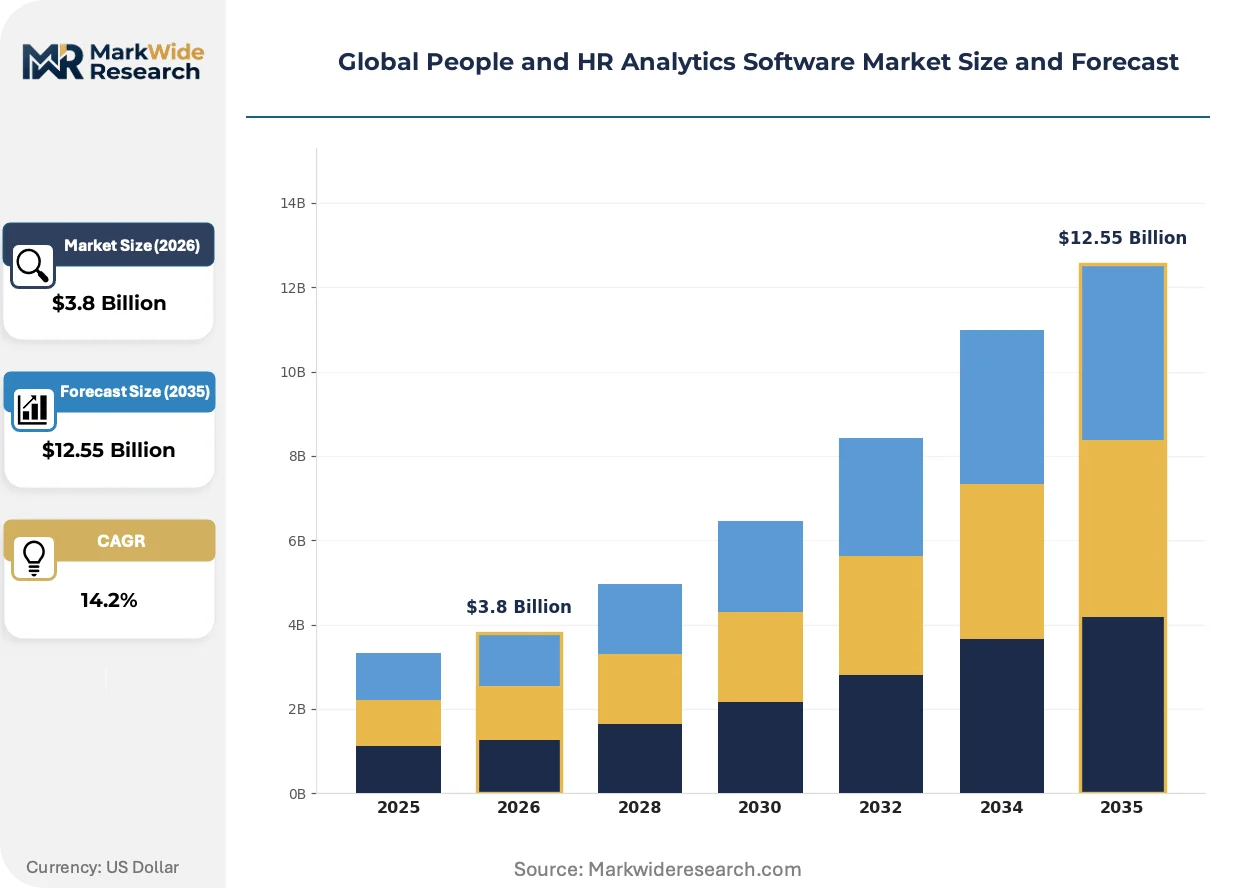
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Private Cloud Solution Type: Talent Acquisition Analytics, Employee Engagement Analytics, Performance Management Analytics, Workforce Planning Analytics, Learning & Development Analytics Use Case: Attrition Prediction, Skill Gap Analysis, Diversity & Inclusion Metrics, Succession Planning, Compensation Analysis End User: Human Capital Management Firms, Recruitment Agencies, Corporate HR Departments, Talent Management Consultancies |
| Companies Covered | Workday, SAP, Oracle, IBM, Visier, UKG, Tableau, Infor, ADP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global People and HR Analytics Software Market Shifts & Advancements
Generative AI capabilities are embedding into workforce analytics workflows, compressing the interpretive gap between raw data outputs and actionable managerial recommendations. This shift demands new governance frameworks for synthetic content in employment decisions.
Graph neural networks for organizational network analysis are converging with traditional HR information systems. Large enterprises in technology and professional services deploy these tools to map informal influence structures and identify hidden succession candidates. The technology is converging with existing talent management suites, forcing point-solution vendors to embed network analytics or face displacement by platform consolidation.
The EU AI Act's risk classification system for automated employment decision tools imposes conformity assessment obligations on vendors serving European corporate buyers. High-risk systems require human-in-the-loop documentation and bias monitoring protocols that reshape product roadmaps. Vendors are responding by building audit trails and explanation interfaces that satisfy French CNIL and German DPA enforcement expectations.
Subscription pricing for workforce analytics is displacing perpetual license models across mid-market buyers. Chief Financial Officers prefer operational expenditure treatment and demand usage-based tiers tied to employee headcount. This pattern is most visible in United States technology and healthcare sectors, where finance teams scrutinize HR tech procurement through zero-based budgeting lenses.
Global People and HR Analytics Software Market Segmentation
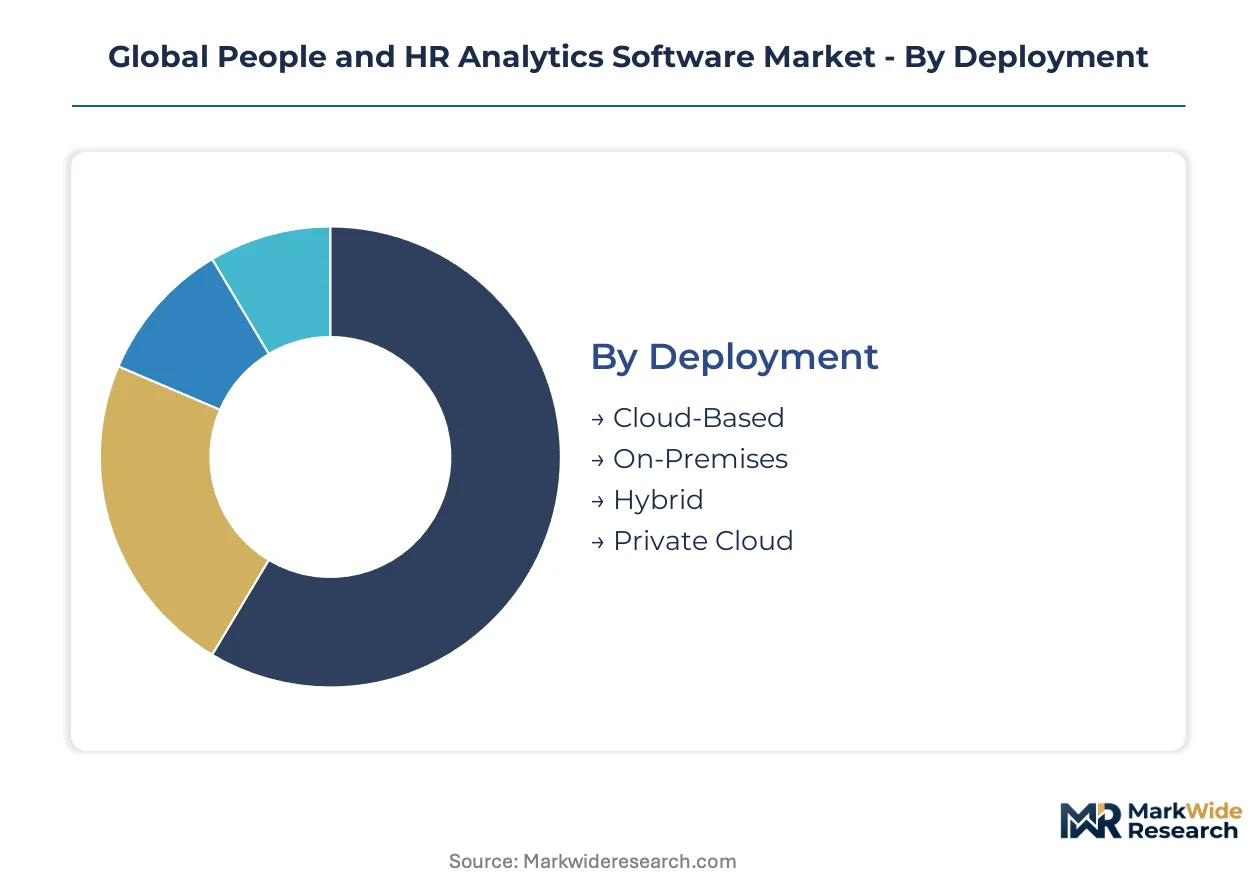
Workforce intelligence platforms fragment across deployment architectures, solution specializations, and functional use cases that determine procurement priorities. Each segmentation axis reveals distinct competitive dynamics: cloud-native delivery accelerates time-to-value while specialized analytics modules command premium pricing in regulated industries. Buyers align segment selection with existing HR technology investments and compliance obligations.
Deployment:
Upgrade cycles from legacy on-premise systems to elastic cloud infrastructure are compressing from multi-year migrations to phased SaaS transitions. Organizations prioritize deployment models that balance data sovereignty requirements against operational agility.
- Cloud-Based:Multi-tenant architectures deliver workforce analytics through browser-accessible dashboards with automatic feature updates. Demand concentrates among mid-market enterprises in the United States seeking to eliminate server maintenance overhead and accelerate implementation timelines.
- On-Premises:Installed software running on customer-managed servers retains favor where data residency mandates or air-gapped security requirements override cloud economics. Financial institutions in Germany and Switzerland maintain on-premise deployments to satisfy national banking regulator documentation standards.
- Hybrid:Split architectures process sensitive employee records locally while pushing anonymized analytics workloads to public cloud infrastructure. Organizations with mixed legacy-modern tech stacks adopt this model to preserve existing ERP connector investments.
- Private Cloud:Dedicated single-tenant cloud instances hosted by vendors or managed service providers deliver isolation without full capital expenditure burden. Healthcare systems and government agencies in Canada specify private cloud to align with Health Canada data protection guidance.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Hybrid.
Solution Type:
Functional specialization within HR analytics reflects diverging buyer maturity: transactional efficiency tools saturate while predictive workforce planning commands expanding budgets. Cost tier differentiation separates point solutions from integrated platform suites.
- Talent Acquisition Analytics:Algorithmic platforms score candidate quality, forecast time-to-fill, and optimize sourcing channel mix using historical hiring outcome data. High-volume employers in technology and retail sectors deploy these tools to reduce cost-per-hire amid labor market volatility.
- Workforce Planning Analytics:Scenario modeling engines project headcount requirements, skills inventories, and location strategies against business growth trajectories. Regulated industries with complex compliance reporting obligations generate concentrated margin pools for vendors serving European corporate HR departments under EU AI Act mandates.
- Employee Engagement Analytics:Pulse survey aggregation and natural language processing of internal communications measure organizational health indicators.
- Performance Management Analytics:Continuous feedback systems and goal-alignment tracking replace annual review cycles.
- Learning & Development Analytics:Skills ontology mapping and training effectiveness measurement connect capability building to business outcomes.
Revenue concentration sits with Workforce Planning Analytics; Talent Acquisition Analytics is gaining share fastest.
Use Case:
Application-specific analytics modules address identifiable pain points that justify procurement against competing HR technology priorities. Customer type segmentation separates enterprise buyers with dedicated data science teams from mid-market purchasers requiring pre-configured workflows.
- Attrition Prediction:Machine learning models identify flight-risk employees using engagement scores, compensation benchmarks, and network centrality metrics. Corporate HR departments in the United States deploy these systems to reduce voluntary turnover costs in competitive talent markets.
- Diversity & Inclusion Metrics:Demographic pipeline analysis and pay equity auditing satisfy SEC human capital disclosure mandates and stakeholder reporting requirements. Public companies facing shareholder pressure prioritize this use case for board-level workforce transparency.
- Skill Gap Analysis:Competency inventory assessment against future role requirements identifies reskilling priorities.
- Succession Planning:Leadership pipeline visualization and readiness scoring reduce key-person dependency risks.
- Compensation Analysis:External market benchmarking and internal equity analytics optimize total rewards spend.
Deployment scale favors Attrition Prediction; Diversity & Inclusion Metrics shows the steepest expansion trajectory.
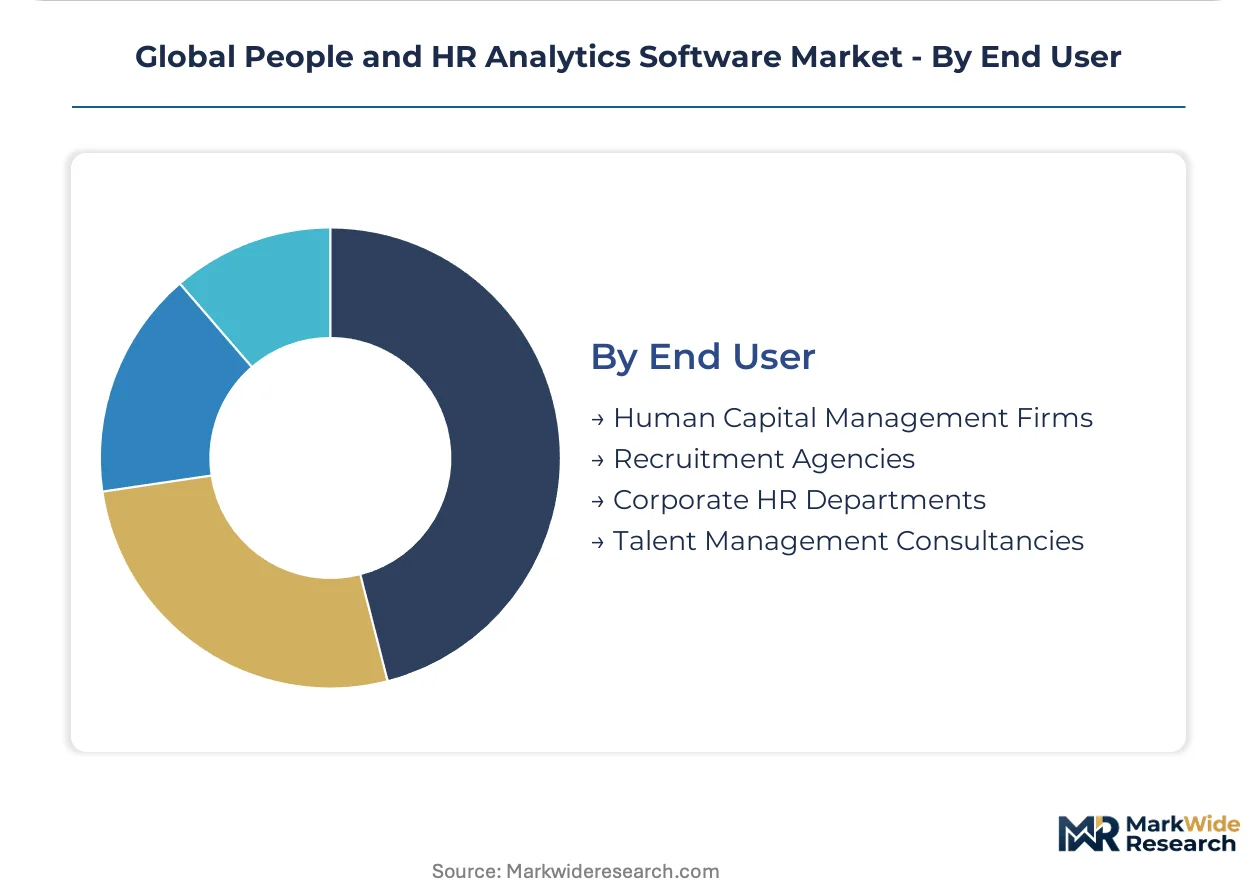
End User:
Channel structure and buyer sophistication shape solution packaging: direct enterprise sales carry higher margins while agency and consultancy intermediaries demand white-label flexibility. Maturity differences separate buyers with internal analytics capabilities from those requiring full-service implementation.
- Corporate HR Departments:In-house people analytics teams within large enterprises purchase platform licenses for direct workforce intelligence operations. Technology and financial services firms in the United States build dedicated analytics functions that demand API access and custom model development environments.
- Talent Management Consultancies:Advisory firms bundle analytics software with change management and strategy services for transformation engagements. McKinsey, Deloitte, and Accenture deploy white-labeled or co-developed platforms to differentiate workforce transformation offerings.
- Human Capital Management Firms:Outsourced HR providers embed analytics into managed service delivery for client workforces.
- Recruitment Agencies:Staffing firms leverage talent acquisition analytics to improve candidate matching and client retention.
Contract value concentrates with Corporate HR Departments; Talent Management Consultancies are expanding procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States and India while enterprise consumption spreads across Western Europe and East Asia. Cloud infrastructure investments follow data residency requirements rather than labor cost arbitrage alone. Regulatory fragmentation shapes vendor localization strategies more than feature differentiation.
United States
Enterprise HR tech stacks are undergoing wholesale cloud migration as CFOs apply zero-based budgeting to workforce technology procurement. The SEC's emerging human capital disclosure mandates expand board-level demand for standardized workforce metrics. Technology and financial services firms in Silicon Valley and New York Metro build dedicated people analytics functions requiring API access and custom model development environments.
Germany
Industrial conglomerates and automotive manufacturers deploy predictive workforce planning to manage engineering talent pipelines through energy transition restructuring. The EU AI Act imposes mandatory risk classification and human oversight requirements on automated employment decision systems. Banking regulators in Frankfurt and manufacturing clusters in Bavaria maintain strict data residency standards that favor hybrid cloud deployments.
United Kingdom
Financial services firms in the City of London expand adoption of predictive workforce analytics to manage regulatory compliance and talent risk post-Brexit. The Information Commissioner's Office enforces GDPR-derived accountability standards for algorithmic processing of employee data. Professional services clusters in London and emerging tech hubs in Manchester drive procurement of sentiment analysis and organizational network tools.
India
PLI scheme incentives and RBI workforce reporting mandates for financial institutions create a high-growth entry market for cloud analytics vendors. The Digital Personal Data Protection Act establishes consent frameworks for employee data processing that vendors must architect around. Technology parks in Bengaluru and Hyderabad host delivery centers for global HR platforms while domestic enterprises in Mumbai accelerate SaaS adoption.
Japan
Large manufacturers facing demographic contraction deploy succession planning analytics to identify leadership pipelines amid retiring baby-boomer executives. METI guidelines on human capital disclosure push listed companies toward standardized workforce reporting. Corporate headquarters in Tokyo and Osaka industrial zones concentrate procurement of integrated talent management suites over point solutions.
Global People and HR Analytics Software Market Competitive Landscape
Capital-heavy platform builders compete with asset-light analytics specialists across the HR technology stack. The vendor landscape organizes into three tiers: integrated cloud suites with native workforce intelligence, ERP-anchored systems capturing data at financial system sources, and independent analytics platforms offering cross-system aggregation. Consolidation pressure intensifies as customers prefer unified data layers over fragmented point solutions. Strategic moves center on API ecosystem expansion and pre-configured compliance modules for regulated industries.
Within the integrated suite tier, Workday leverages its native cloud architecture to anchor large-enterprise deployments across North America and Europe. SAP sustains competitive pressure through deep ERP integration that captures workforce data at the source of financial and operational systems. Oracle differentiates by extending its database-layer dominance into predictive talent analytics, controlling the infrastructure stack beneath application logic. These three exemplify divergent paths to workforce intelligence market position.
| Leading Market Players |
|---|
| Workday |
| SAP |
| Oracle |
| IBM |
| Visier |
| UKG |
| Tableau |
| Infor |
| ADP |
| Others |
Supply & Pricing Matrix
Vertical integration into cloud infrastructure anchors both supply position and pricing power for workforce analytics vendors, as proprietary data center investments in the United States and India insulate platform providers from third-party hosting cost volatility while enabling tiered subscription premiums.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects CFO-mandated zero-based budgeting scrutiny across United States technology and healthcare sectors. Pricing stratifies across enterprise, professional, and essentials tiers, with differentiation driven by API access depth and EU AI Act compliance module inclusion. Cost-down pressure on essentials tiers accelerates because freemium entrants from adjacent HR tech categories commoditize basic workforce reporting. Corporate HR departments with dedicated analytics functions show lowest price sensitivity; mid-market buyers without internal data science teams exhibit highest.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Singapore concentrate cloud workload delivery for workforce analytics platforms serving regulated industries. Engineering talent pipelines draw from Bengaluru, Hyderabad, and Warsaw development hubs. Single-source vulnerability concentrates in GPU provisioning for generative AI model training. Distribution runs through direct enterprise sales teams and talent management consultancy partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning engineering scarcity props pricing power for vendors capable of delivering production-grade fairness auditing, constraining supply expansion faster than demand growth across the analysis window.
For Market Incumbents: Extend API ecosystem coverage to neutralize point-solution disintermediation threats from specialized network analytics vendors. Deepen vertical integration into consent management infrastructure to preempt GDPR and emerging United States state privacy law compliance fragmentation. Prioritize certification investment in ISO 30414 human capital reporting standards to capture multinational issuer procurement mandates. For New Entrants and Emerging Players: Enter via frontline worker analytics segments in United States retail and logistics, where hourly workforce optimization remains underserved by knowledge-worker-optimized incumbents. Target India's domestic enterprise market under PLI scheme acceleration and RBI workforce reporting mandates. Deploy white-label partnerships with talent management consultancies as primary go-to-market channel. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated cloud suites seeking cross-system aggregation capabilities. Long-term viability favors vendors with explainable AI architectures that satisfy divergent European algorithmic accountability and United States disparate impact enforcement frameworks. Watch EEOC litigation volume against algorithmic hiring tools as inflection indicator for liability-adjusted valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates fragmented ERP connectors into unified data layers for Workday, SAP, and Oracle environments. |
| Acquisition of Specialist Firm | Adds organizational network analysis capabilities to counter graph neural network displacement threats. |
| Geographic Expansion | Establishes region-locked infrastructure in Germany and Switzerland to satisfy banking regulator data residency mandates. |
| Strategic Partnership | Aligns with McKinsey, Deloitte, or Accenture workforce transformation practices for white-label distribution. |
| Product Launch | Introduces pre-configured EU AI Act compliance dashboards capturing high-risk system audit trail requirements. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents formed the secondary backbone, supplemented by primary interviews with CTOs, HR technology procurement officers, platform engineers, and integration specialists. Bottom-up deployment estimates across cloud-native, on-premises, hybrid, and private cloud architectures were triangulated against top-down vendor revenue aggregations.
Historical trendline analysis of subscription revenue trajectories informed CAGR derivation across the projection horizon, with segmentation modeling spanning deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. Forecast inputs incorporated EU AI Act implementation timelines and SEC human capital disclosure mandate adoption curves.
Revisions become necessary when regulatory divergence between European algorithmic accountability frameworks and United States federal-state enforcement patterns materializes, or when generative AI governance standards crystallize. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Document Analytics Market
Analytics
Europe Retail Analytics Market
Analytics
AI Performance Marketing Market
Analytics
APAC Data Wrangling Market
Analytics
Europe Mobile Analytics Market
Analytics
Mobile Business Intelligence Market
Analytics
Spain Geospatial Analytics Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
North America Location Analytics Market
Analytics
Datacenter Analytics Market
Analytics
Augmented Analytics in BFSI Market
Analytics
Content Analytics and Discovery Software Market
Analytics
Global Enterprise Performance Management Market
Analytics
Personal Analytics Market
Analytics
UAE Geospatial Analytics Market
Analytics
Global Data Analysis Software Market