
 Global High Performance Data Analytics (HPDA) Market | 2026-2036
Global High Performance Data Analytics (HPDA) Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Performance Data Analytics (HPDA) Market Foresight
Enterprise manufacturing buyers is collapsing as the dominant procurement archetype while government agencies and academic institutions gain share in HPDA platform selection. Hewlett Packard Enterprise leverages its supercomputing heritage to anchor federal and research contracts. NVIDIA Corporation dominates GPU-accelerated analytics infrastructure for defense and energy applications. IBM sustains its position through quantum-classical hybrid analytics development and sovereign cloud partnerships.
High Performance Data Analytics (HPDA) refers to the application of high-performance computing architectures, including parallel processing clusters, in-memory computing grids, and GPU-accelerated nodes, to execute complex analytical workloads on petabyte-scale datasets with sub-second latency requirements. Its primary purpose is to enable real-time decision intelligence across computationally intensive domains such as genomic sequencing, financial risk modeling, and autonomous systems validation. Cloud-based deployment is capturing the fastest expansion as hyperscalers invest in elastic HPC instances, while on-premise installations retain primacy in classified environments where data sovereignty mandates strict physical control. Predictive analytics and machine learning platforms represent the deepest margin pools, particularly when bundled with industry-specific model governance and MLOps tooling.
The EU AI Act imposes conformity assessment requirements on high-risk AI systems, directly shaping HPDA product roadmaps for European deployments, while FDA guidelines on AI-enabled medical devices influence validation protocols for healthcare analytics pipelines in the United States. ISO/IEC 27001 and NIST cybersecurity frameworks further constrain infrastructure design for cross-border data flows. Stakeholders must weigh sovereign compute requirements against cloud economics when architecting multi-jurisdiction HPDA deployments.
Market Dynamics
GPU-accelerated computing clusters are compressing analytical latency from minutes to milliseconds, forcing infrastructure buyers to reevaluate rack density and thermal design power constraints across every deployment category.
Growth Catalysts
- EU AI Act Conformity Mandates:High-risk AI system classification is accelerating procurement of auditable HPDA platforms with embedded model governance tooling across European financial and healthcare sectors.
- Defense Simulation Workloads:Aerospace contractors in the United States, Germany, and Japan are expanding classified supercomputing contracts for hypersonic vehicle modeling and electronic warfare validation.
- In-Memory Computing Maturation:Persistent memory architectures are eliminating storage bottlenecks for real-time fraud detection and genomic variant calling in commercial banking and precision medicine.
Market Restraints
- Advanced Packaging Capacity Constraints:CoWoS and HBM3 supply from TSMC and SK Hynix is creating 12-18 month lead times for GPU-accelerated nodes, freezing procurement cycles.
- Data Sovereignty Fragmentation:Divergent localization requirements across Germany, France, and India are forcing redundant infrastructure builds that erode cloud economics.
- Power Density Physics:Liquid cooling retrofits for existing data centers now consume 15-25% of total HPDA project capex, compressing ROI timelines.
Strategic Opportunities
- Quantum-Classical Hybrid Pipelines:IBM and research consortia in Switzerland and Canada are prototyping variational quantum eigensolvers for molecular simulation workloads that exceed classical limits.
- Sovereign Cloud Architectures:Gaia-X compliant federated data spaces in Germany and the Netherlands are creating procurement channels outside hyperscaler dominance.
- Edge-HPDA Convergence:Autonomous systems manufacturers in South Korea and Sweden are deploying containerized analytics nodes for real-time sensor fusion on factory floors and naval vessels.
Industry Challenges
- Parallel Programming Talent Scarcity:CUDA and MPI expertise concentrated in national laboratories and elite universities is failing to scale with commercial deployment velocity.
- Model Validation Protocols:FDA 21 CFR Part 11 and EMA GxP requirements for AI-enabled medical devices are extending HPDA pipeline certification timelines by 18-36 months.
- Interoperability Debt:Legacy SAS and MATLAB analytics stacks in financial services are resisting containerization, forcing expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Performance Data Analytics (HPDA) Market |
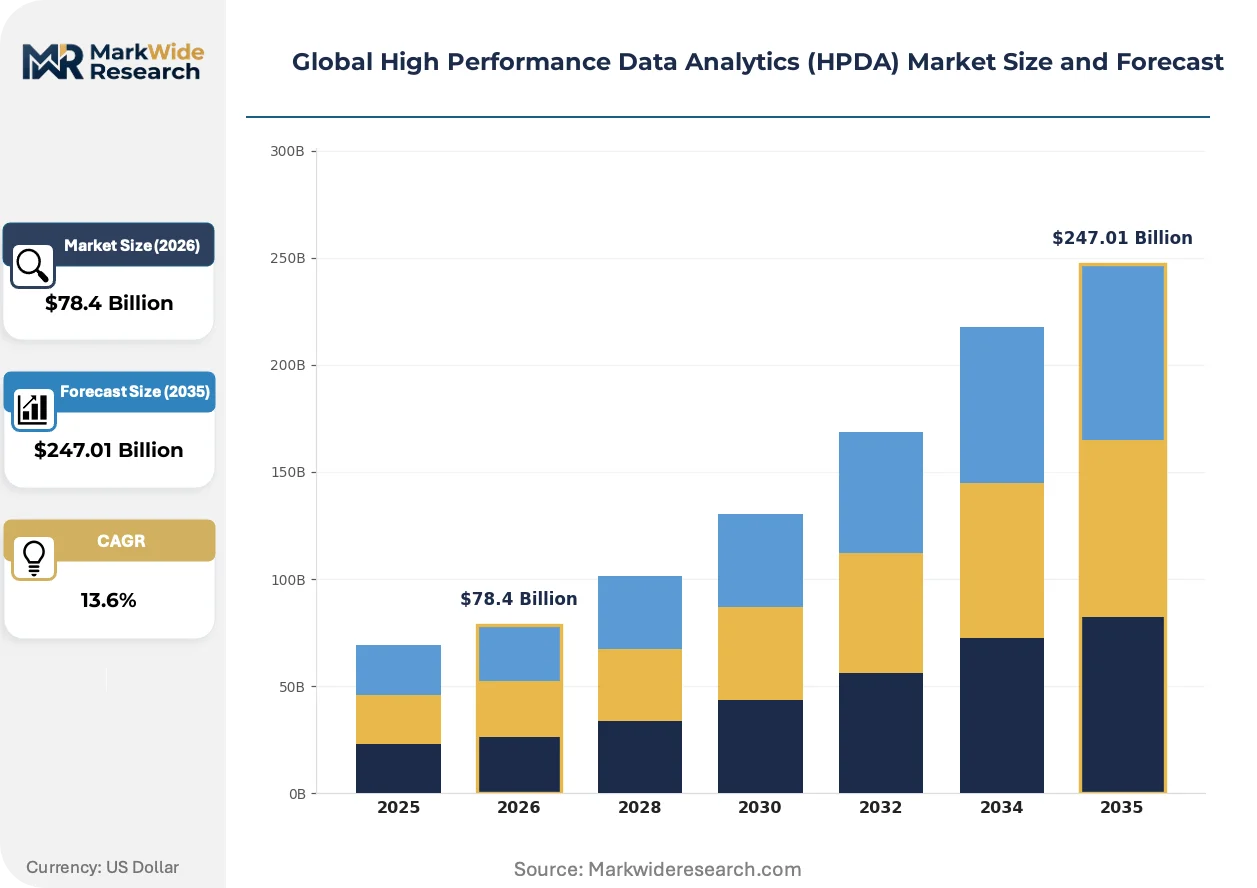
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Offering: Data Mining, Predictive Analytics, Real-Time Analytics, Machine Learning Platforms, Data Visualization Application: Fraud Detection, Customer Insights, Risk Management, Supply Chain Optimization, Scientific Research End User: Telecommunications, Aerospace & Defense, Energy Production, Government Agencies, Academic Institutions |
| Companies Covered | Hewlett Packard Enterprise, IBM, Amazon Web Services, SAS Institute, Oracle Corporation, Microsoft Corporation, NVIDIA Corporation, Intel Corporation, Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Performance Data Analytics (HPDA) Market Shifts & Advancements
Silicon photonics and CXL memory fabrics are dissolving the boundaries between storage, compute, and networking layers, enabling new disaggregated architectures that challenge traditional server-centric procurement models.
Optical interconnects between GPU clusters and memory pools are supplanting copper backplanes in training-scale deployments. Hyperscalers in Oregon and Singapore are deploying 51.2 Tbps photonic switch fabrics to sustain thousand-node synchronization. This photonic layer is compressing the physical footprint of exascale systems by 40% while tripling energy efficiency per FLOP.
The EU AI Act's conformity assessment framework is mandating technical documentation and risk management systems for high-risk AI deployments. European HPDA vendors are embedding automated model cards and lineage tracking into platform stacks. Healthcare and public sector buyers in France and Germany are now disqualifying solutions lacking built-in audit trails.
Consumption-based pricing for HPC cycles is displacing perpetual licensing in enterprise procurement. Automotive and semiconductor firms in Japan and Michigan are negotiating reserved instance contracts with burst capacity guarantees. This shift is concentrating buyer power among firms with predictable workload patterns while marginalizing episodic users.
Global High Performance Data Analytics (HPDA) Market Segmentation
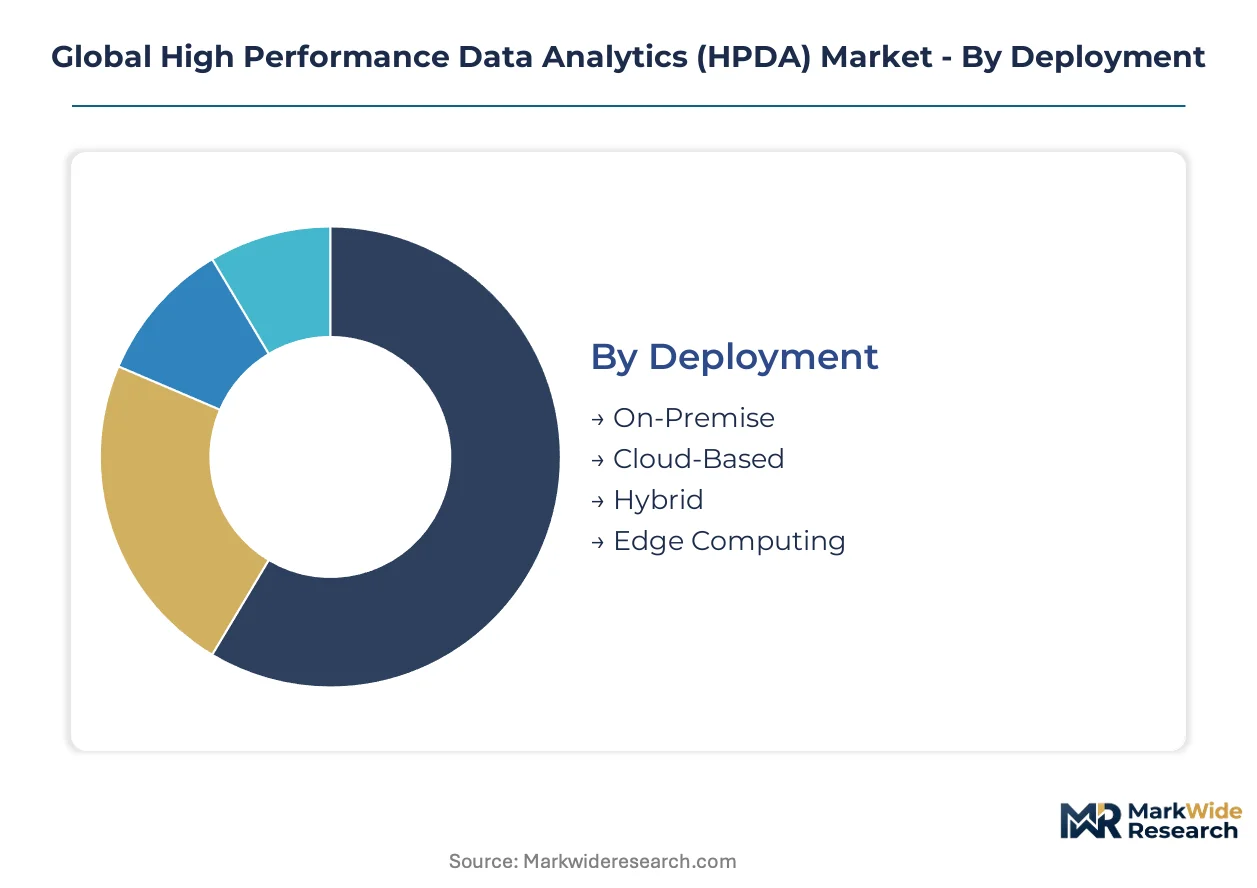
HPDA procurement patterns diverge sharply across deployment architectures and end-user governance requirements. Buyers weigh latency constraints against data sovereignty mandates when selecting platform configurations.
Deployment:
Cloud-based instances face substitution pressure from sovereign edge architectures as data localization requirements harden across European and Asian jurisdictions.
- On-Premise:Dedicated HPC clusters with liquid-cooled GPU racks serve classified defense simulations and genomic research facilities. Procurement concentrates in German Fraunhofer institutes and U.S. national laboratories where physical data control is non-negotiable under ITAR and GDPR Article 48 restrictions.
- Cloud-Based:Elastic HPC instances from hyperscalers offer burst capacity for automotive crash modeling and financial stress testing. Demand clusters in Singapore and Oregon where photonic interconnects minimize latency for distributed training workloads.
- Hybrid:Federated architectures partition sensitive training data on-premise while offloading inference to sovereign cloud zones. German automotive OEMs and Swiss pharmaceutical firms deploy these configurations to satisfy EMA GxP and EU AI Act conformity mandates.
- Edge Computing:Containerized analytics nodes process sensor fusion aboard naval vessels and factory floors. South Korean shipbuilders and Swedish autonomous systems manufacturers drive procurement for real-time decisioning outside datacenter footprints.
On-premise installations anchor the volume base while edge computing gains share at the steepest rate.
Solution Offering:
Application-specific tooling creates distinct margin tiers based on embedded governance and MLOps sophistication.
- Data Mining:Pattern extraction algorithms for unstructured telemetry and transaction logs. Financial services in Frankfurt and Mumbai deploy these for anti-money laundering pipelines.
- Predictive Analytics:Statistical forecasting engines for demand planning and equipment failure prediction. Energy utilities in Texas and Denmark leverage these for grid stability optimization.
- Real-Time Analytics:Sub-millisecond stream processing for fraud detection and algorithmic trading. Investment banks in London and Tokyo require dedicated FPGA acceleration to meet latency budgets.
- Machine Learning Platforms:End-to-end MLOps stacks with automated model lineage and audit trails. Healthcare systems in France and Germany mandate these for EU AI Act high-risk system conformity.
- Data Visualization:Interactive rendering engines for exascale simulation outputs. Aerospace contractors in Munich and Huntsville use these for hypersonic vehicle design review.
Machine learning platforms command premium pricing while real-time analytics expands most quickly in financial services procurement.
Application:
Use-case maturity determines whether buyers prioritize throughput optimization or governance tooling.
- Fraud Detection:Real-time transaction scoring with behavioral biometrics. Commercial banks in Singapore and São Paulo deploy these for cross-border payment monitoring.
- Customer Insights:Segmentation engines for personalization and churn prediction. Telecommunications carriers in Jakarta and Lagos use these for subscriber retention.
- Risk Management:Monte Carlo simulation frameworks for credit and market risk quantification. Insurance groups in Zurich and Sydney require these for Solvency II and APRA compliance.
- Supply Chain Optimization:Multi-echelon inventory and logistics solvers. Semiconductor firms in Hsinchu and Dresden deploy these for fab-to-assembly coordination.
- Scientific Research:Climate modeling, molecular dynamics, and astrophysical simulation. Research councils in Canada and Australia fund these through national supercomputing allocations.
Risk management applications dominate enterprise spending while scientific research climbs fastest in public sector procurement.
End User:
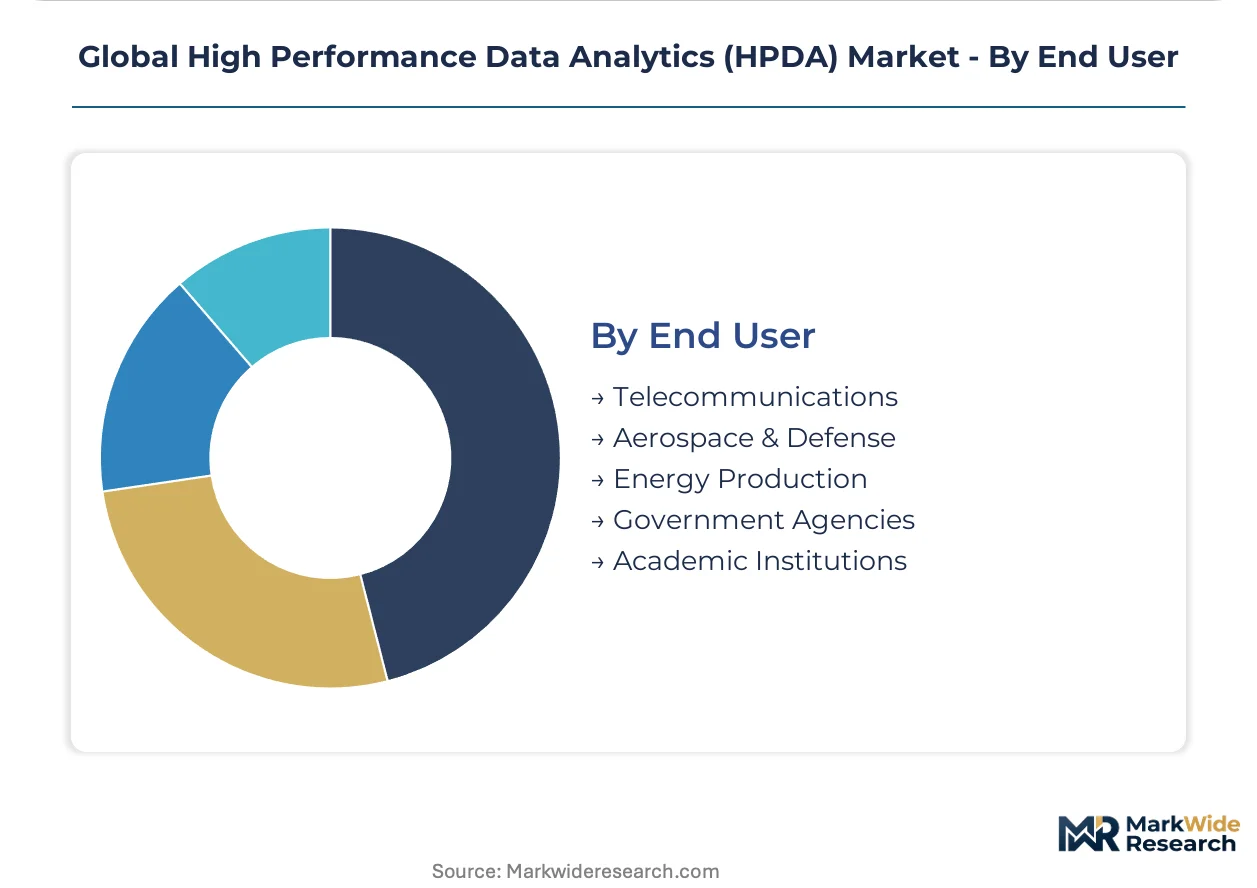
Procurement authority is migrating from enterprise IT departments to specialized research and defense agencies with dedicated HPC budgets.
- Telecommunications:Network optimization and predictive maintenance for 5G infrastructure. Operators in Finland and South Korea deploy these for RAN automation.
- Aerospace & Defense:Classified supercomputing for electronic warfare and hypersonic modeling. Contractors in the United States, Germany, and Japan secure multi-year contracts with national laboratories.
- Energy Production:Reservoir simulation and renewable intermittency forecasting. Oil majors in Norway and UAE national oil companies drive demand for subsurface analytics.
- Government Agencies:Sovereign data processing for census, tax, and intelligence analytics. India's UIDAI and Brazil's Receita Federal deploy these for population-scale data integration.
- Academic Institutions:Open-science HPC for particle physics and genomics. Universities in Switzerland, the Netherlands, and California compete for limited allocation hours on shared national facilities.
Aerospace and defense anchors the revenue base while government agencies are expanding procurement fastest under sovereign compute mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The DE-CIX internet exchange in Frankfurt anchors Europe's data gravity, while submarine cable landings in Singapore and Oregon sustain trans-Pacific analytics workloads. These infrastructure assets determine where HPDA clusters concentrate and how sovereignty requirements reshape deployment patterns.
United States
Defense contractors in Huntsville and aerospace clusters in Southern California drive classified supercomputing procurement for hypersonic modeling. The FDA's 21 CFR Part 11 framework governs validation protocols for AI-enabled medical devices in healthcare analytics. National laboratories in Oak Ridge and Lawrence Livermore anchor federal HPC allocations for nuclear stockpile stewardship.
Germany
Fraunhofer institutes and automotive OEMs in Stuttgart and Munich deploy sovereign HPDA architectures for crash simulation and battery cell modeling. The EU AI Act's conformity assessment mandates shape platform selection for high-risk industrial AI systems. Gaia-X compliant federated data spaces in the Rhine-Ruhr corridor create procurement channels outside hyperscaler dominance.
Japan
Automotive manufacturers in Toyota City and semiconductor equipment firms in Tokyo prefecture negotiate reserved HPC instance contracts with burst capacity guarantees. METI's digital infrastructure investments accelerate domestic GPU cluster deployment for materials science. Research consortia in Tsukuba prototype quantum-classical hybrid pipelines for molecular simulation.
Singapore
Financial institutions in the central business district deploy sub-millisecond real-time analytics for cross-border payment monitoring and algorithmic trading. The Monetary Authority of Singapore's technology risk management guidelines constrain infrastructure design for cloud-based deployments. Photonic interconnects at Tuas data center campuses compress latency for distributed training workloads across Southeast Asian markets.
India
The Unique Identification Authority of India deploys population-scale data integration pipelines for biometric authentication and welfare distribution. RBI's data localization directives force on-premise installations for commercial banking fraud detection systems. IT services clusters in Bengaluru and Hyderabad build sovereign analytics capacity for government and enterprise clients.
Global High Performance Data Analytics (HPDA) Market Competitive Landscape
Concentration sits with diversified technology conglomerates and specialized infrastructure vendors. The vendor base spans three tiers: hyperscale cloud operators with elastic HPC instances, legacy enterprise systems providers with supercomputing heritage, and GPU-accelerated hardware specialists. Strategic moves center on sovereign cloud partnerships and quantum-classical hybrid development pipelines.
Among diversified technology conglomerates, Hewlett Packard Enterprise and IBM occupy positions anchored in federal and research contracting relationships. NVIDIA Corporation exemplifies the GPU-accelerated infrastructure archetype for defense and energy applications. These three entities represent distinct competitive vectors: sovereign compute partnerships, quantum-classical hybrid analytics, and parallel processing hardware dominance.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| IBM |
| Amazon Web Services |
| SAS Institute |
| Oracle Corporation |
| Microsoft Corporation |
| NVIDIA Corporation |
| Intel Corporation |
| Google LLC |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-month lead times for GPU-accelerated nodes reshape pricing power across deployment tiers, concentrating margin capture with foundries and memory suppliers while forcing infrastructure buyers into multi-year reservation contracts. This supply bottleneck elevates sovereign cloud premiums above hyperscaler spot rates and accelerates consumption-based pricing displacement of perpetual licensing.
Pricing Analysis
Volume-discount tiering structures stratify across reserved instance commitments, burst capacity guarantees, and pay-per-FLOP consumption models. Pricing separates sovereign cloud deployments in Germany and Singapore from standard hyperscaler tiers through Gaia-X compliance and data localization certification. Cost compression in cloud-based instances intensifies as hyperscalers compete for automotive and semiconductor reserved contracts, while on-premise installations retain pricing resilience under ITAR and GDPR Article 48 mandates. Government agencies and classified defense contractors exhibit lowest price sensitivity; episodic commercial users face marginalization under predictable workload preference.
Supply Chain Analysis
Taiwan and South Korea anchor advanced packaging capacity for CoWoS and HBM3 production, with TSMC and SK Hynix controlling critical GPU node supply. The supply chain draws from specialized silicon photonics foundries in Oregon and Singapore for optical interconnect fabrics, alongside persistent memory wafer output from Japanese and American facilities. Single-source vulnerability concentrates in TSMC's CoWoS capacity allocation decisions. Distribution runs through direct federal contracting channels for classified deployments, hyperscaler reserved instance marketplaces for elastic demand, and systems integrator partnerships for hybrid sovereign architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among government agencies and academic institutions with dedicated HPC budgets, fragmenting procurement authority away from enterprise IT departments. This shift rewards vendors with federal contracting heritage and sovereign cloud compliance capabilities.
For Market Incumbents: Shield federal research relationships through quantum-classical hybrid R&D investment and Gaia-X certification acceleration. Liquid cooling infrastructure partnerships and in-house CoWoS allocation negotiations reduce GPU node lead-time exposure. Sovereign cloud compliance tooling defends against emerging European specialists. For New Entrants and Emerging Players: MLOps governance gaps in mid-market healthcare and financial services create entry points where IBM and SAS Institute over-serve. Target German automotive OEMs and Swiss pharmaceutical firms with EU AI Act-ready model lineage platforms. Go-to-market leverage rests on pre-certified compliance bundles rather than raw compute performance. For Investors and Strategic Acquirers: Carve-out targets emerge from hyperscaler edge computing divisions and national laboratory technology transfer offices. Long-term viability centers on sovereign compute mandates hardening across European and Asian jurisdictions. Watch for EU AI Act enforcement intensity as inflection signal for compliance-tooling valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Gaia-X compliance in Germany and Netherlands unlocks procurement outside hyperscaler dominance. |
| Quantum-Classical Hybrid Development | IBM and Swiss research consortia prototype variational eigensolvers exceeding classical simulation limits. |
| Liquid Cooling Infrastructure Investment | Retrofit partnerships address 15-25% capex burden compressing on-premise ROI timelines. |
| GPU Allocation Contracting | Multi-year TSMC CoWoS reservations secure supply certainty for defense and energy supercomputing. |
| MLOps Platform Integration | Automated model lineage embedding satisfies FDA 21 CFR Part 11 and EU AI Act audit mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with HPC procurement officers at German Fraunhofer institutes, GPU platform engineers at hyperscalers, and sovereign cloud architects at European automotive OEMs. Secondary validation drew from SEC hyperscaler capex disclosures, EU AI Act implementation guidance, national supercomputing facility allocation reports, and photonic interconnect patent filings. Bottom-up deployment volume estimates triangulated against top-down infrastructure spending projections across defense, healthcare, and energy verticals.
Across the analysis window, the forecasting framework modeled deployment architecture splits, solution offering margin tiers, and end-user procurement authority migration. Segmentation dimensions included on-premise versus cloud versus edge topology, machine learning platform versus real-time analytics solution type, and aerospace defense versus government agency versus academic institution buyer archetype. CAGRs were derived from elasticity-adjusted infrastructure investment curves and workload pattern evolution assumptions.
Underlying assumptions cover sovereign data localization requirement permanence and GPU packaging capacity expansion trajectories, with deviation risk concentrated in EU AI Act enforcement timing and TSMC CoWoS allocation policy shifts. Recalibration cycles align with material shifts in defense simulation procurement volumes and photonic interconnect commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Statistical Analytics Market
Analytics
Complex Event Processing Market
Analytics
Automated Analytics Market
Analytics
Content Analytics and Discovery Software Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
APAC Data Wrangling Market
Analytics
Patent Analytics Market
Analytics
Europe Edge Analytics Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
Global Sentiment Analytics Software Market
Analytics
Service Analytics Market
Analytics
China Contact Center Analytics Market
Analytics
Business Value Dashboard Market
Analytics
Global User and Entity Behavior Analytics Market
Analytics
Emotion Analytics Market
Analytics
Big Data Analytics in BFSI Market