
 Application Analytics Market | 2026-2036
Application Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Application Analytics Market Analysis
Enterprise buyer concentration is expanding as mid-market retailers and healthcare networks consolidate analytics procurement under centralized IT governance. Adobe sustains product specialization through creative-cloud integration with analytics workflows. Microsoft dominates enterprise distribution via Azure-embedded deployment channels. Amplitude differentiates through product-led growth tooling tailored to subscription business models.
Application analytics encompasses software platforms that capture, process, and visualize user interaction data across mobile and web environments, typically ingesting event streams exceeding thousands of events per second to generate behavioral cohorts and funnel analyses. Cloud-based deployment leads product-type adoption due to elastic scaling and reduced infrastructure overhead, while predictive analytics within the solution category captures expanding margin pools as organizations automate churn forecasting and personalization. Self-service analytics matures as a baseline expectation, with data visualization representing the fastest-growing capability segment as business users demand interactive dashboards without engineering dependencies.
GDPR enforcement by European data protection authorities and the EU AI Act's risk-classification framework constrain cross-border data processing architectures, compelling vendors to engineer region-specific instance isolation. The US Federal Trade Commission scrutinizes dark-pattern detection and consumer data practices, shaping consent-management feature roadmaps. FDA guidance on software-as-medical-device for diagnostic applications influences healthcare analytics validation protocols. Stakeholders must weigh sovereign data requirements against unified platform economics when architecting multi-tenant deployments.
Market Dynamics
Real-time behavioral data ingestion is electrifying platform architectures as retail and healthcare enterprises mandate sub-second latency for user journey mapping. Cloud-native event streaming now dominates procurement specifications.
Growth Catalysts
- GDPR Article 30 compliance mandates:European enterprises must maintain records of processing activities, forcing platform upgrades to automated audit trails and consent orchestration.
- Edge computing deployment:Mobile network operators in India and Germany are co-locating analytics nodes at 5G base stations to reduce data transit costs for real-time personalization.
- Healthcare diagnostic workflows:FDA software-as-medical-device guidance is validating predictive patient engagement models, opening reimbursement pathways for clinical analytics.
Market Restraints
- Cross-border data localization:The EU AI Act's risk-classification framework fragments multi-tenant architectures, compelling vendors to provision isolated regional instances.
- Specialized talent scarcity:Event-stream processing engineers command premium compensation in the United States and Germany, inflating implementation costs for mid-market buyers.
- Legacy warehouse inertia:On-premise Hadoop clusters at established retailers resist migration despite elastic cloud economics, delaying platform refresh cycles.
Strategic Opportunities
- India digital commerce infrastructure:Unified Payments Interface transaction volumes are generating unprecedented event data streams, creating greenfield demand for behavioral analytics.
- Generative AI convergence:Large language models are automating natural language query interfaces, reducing dashboard development dependencies for business users.
- CSRD sustainability reporting:The EU Corporate Sustainability Reporting Directive mandates granular operational disclosures, extending analytics procurement into ESG data lineage.
Industry Challenges
- Event schema governance:Product teams struggle to maintain consistent taxonomies across mobile, web, and connected device streams, corrupting funnel accuracy.
- Third-party cookie deprecation:Google's Privacy Sandbox transition is forcing identity resolution rebuilds, compressing measurement continuity for attribution models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Analytics Market |
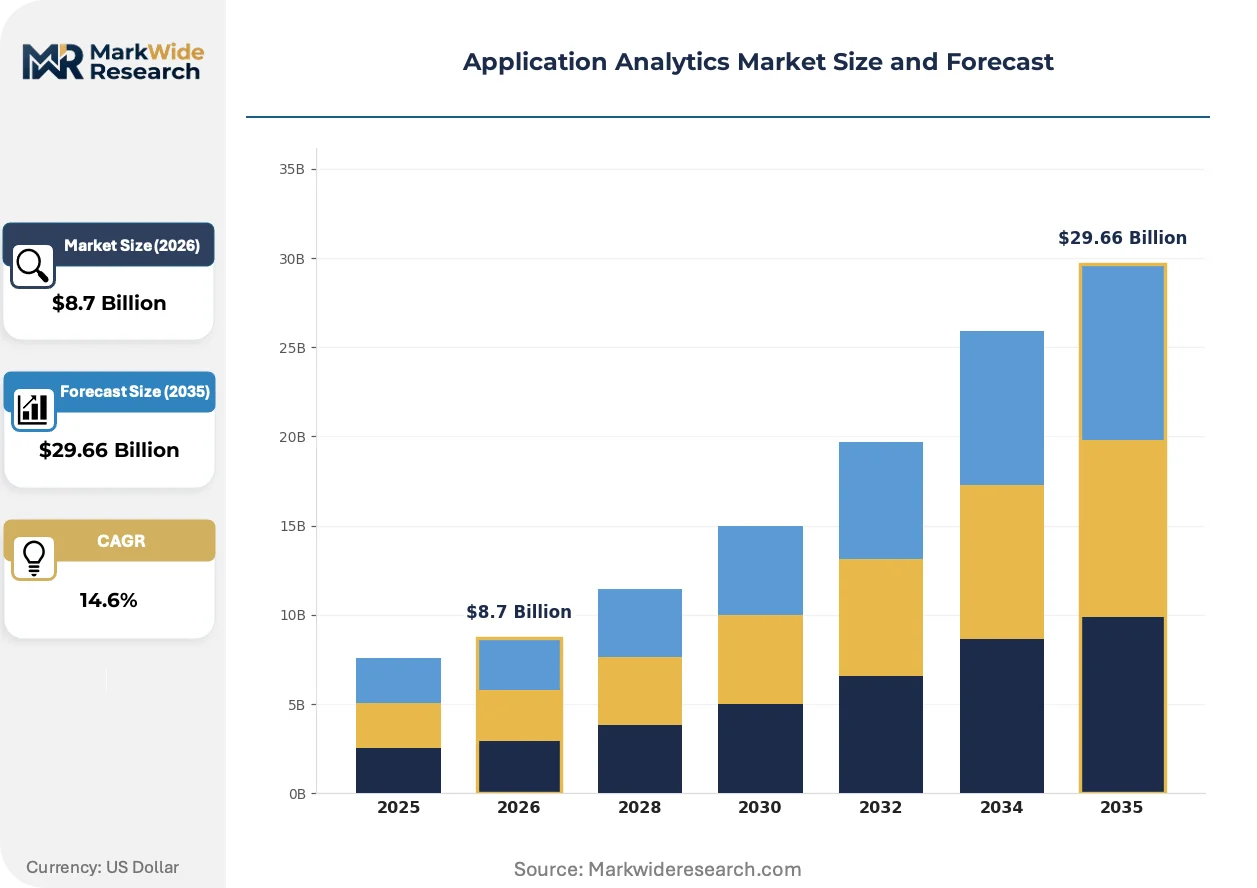
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, SaaS End User: Retail, Healthcare, Finance, Telecommunications Deployment: Public Cloud, Private Cloud, Multi-Cloud, Edge Solution: Self-Service Analytics, Predictive Analytics, Data Visualization, Reporting |
| Companies Covered | Google, Adobe, Mixpanel, Amplitude, Microsoft, AppsFlyer, IBM, Adjust, App Annie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Analytics Market Emerging Trajectories
Behavioral data architectures are converging with AI inference pipelines, compressing the latency between insight generation and automated action. This fusion is reshaping competitive differentiation across deployment models.
Stream processing engines with native vector database integration are electrifying real-time personalization workflows. Subscription commerce platforms in the United States are deploying these architectures to automate churn intervention within single session windows. The technology is compressing the traditional batch-to-action cycle from hours to milliseconds.
The EU AI Act's high-risk system classification is mandating explainability modules for predictive analytics deployed in credit and health contexts. Vendors must now engineer interpretable model outputs alongside raw prediction scores. Healthcare networks in Germany are prioritizing procurement specifications that document algorithmic decision pathways for clinical validation.
Self-service exploration interfaces are displacing static dashboard subscriptions as the primary procurement criterion. Mid-market retailers in India are demanding natural language query capabilities that bypass SQL dependencies. This behavioral shift is visible most acutely in competitive evaluations where vendor selection hinges on time-to-first-insight metrics rather than feature breadth.
Application Analytics Market Segmentation
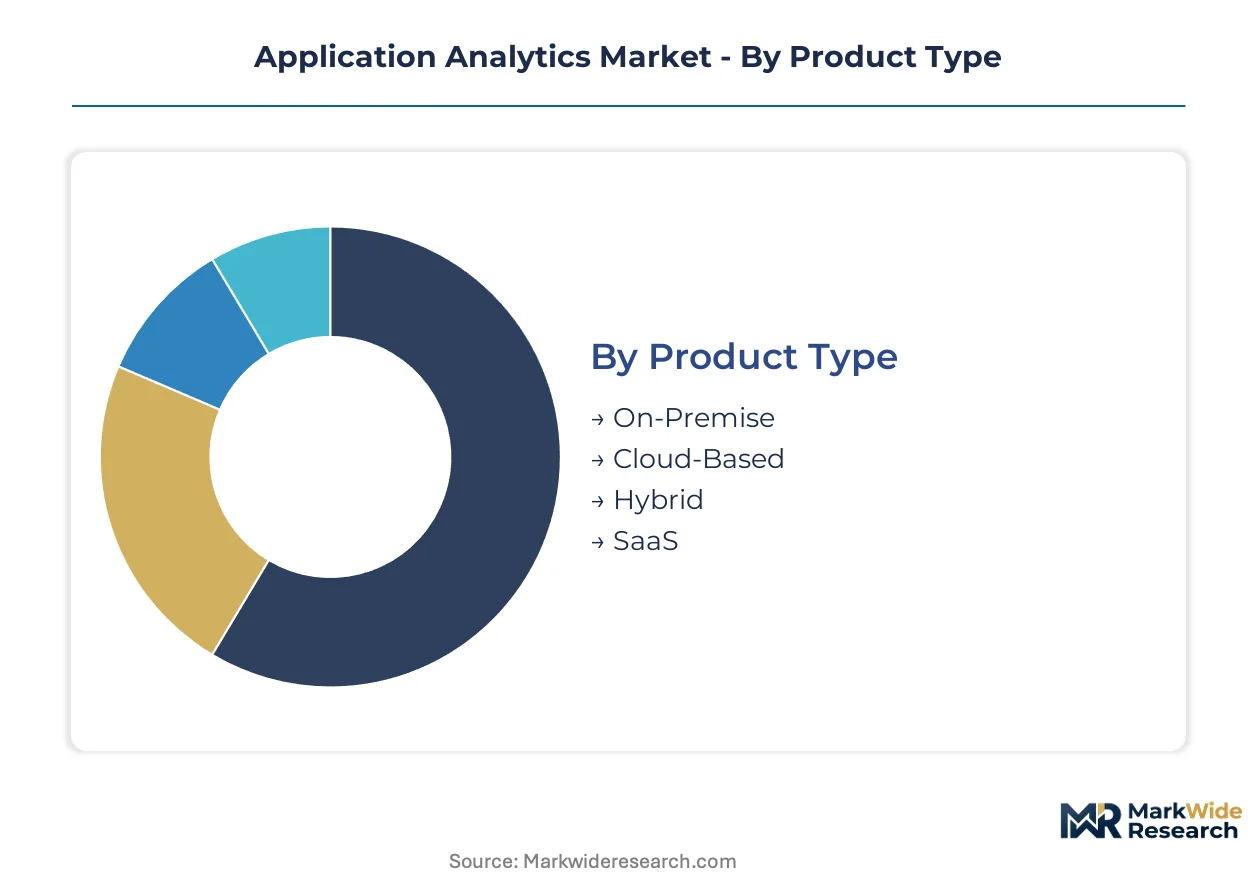
Application analytics procurement patterns diverge sharply by infrastructure maturity and regulatory exposure. Buyers with legacy data centers prioritize control and auditability, while cloud-native enterprises optimize for elastic event throughput and sub-second latency.
Product Type:
Standalone deployments dominate regulated sectors requiring air-gapped environments, whereas embedded analytics integrate directly into operational software workflows.
- On-Premise:Hardware-resident installations running within enterprise data centers with direct storage area network connectivity. German automotive suppliers and US defense contractors mandate these configurations for ITAR and GDPR Article 44 compliance, accepting higher capital intensity for sovereign data control.
- Cloud-Based:Fully managed services with elastic compute provisioning across distributed availability zones. Indian digital commerce platforms and US subscription retailers are scaling these deployments to handle Unified Payments Interface transaction spikes and real-time churn intervention without infrastructure provisioning delays.
- Hybrid:Architectures partitioning sensitive data on-premise while bursting compute-intensive workloads to public cloud. Financial services institutions in Germany deploy these models to satisfy BaFin operational resilience requirements while accessing GPU clusters for predictive modeling.
- SaaS:Multi-tenant software delivered via browser with zero infrastructure footprint. Mid-market healthcare networks in the United States select these offerings for rapid deployment without dedicated database administration.
Volume placements concentrate in Cloud-Based configurations; the faster expansion belongs to Hybrid architectures bridging compliance and elasticity requirements.
End User:
Cost-tier segmentation separates enterprise buyers with dedicated implementation teams from mid-market adopters purchasing through vendor-managed services.
- Retail:Omnichannel merchants tracking cross-device customer journeys through event stream processing. US specialty apparel chains and German grocery cooperatives are consolidating vendor relationships under centralized procurement to reduce schema governance overhead across mobile applications and point-of-sale terminals.
- Healthcare:Provider networks and payers analyzing patient engagement patterns for readmission risk stratification. FDA software-as-medical-device validation protocols are constraining vendor selection to platforms with documented algorithmic decision pathways.
- Finance:Banks and insurers monitoring transaction anomalies and customer lifetime value across digital channels. RBI data localization mandates in India and SEC record-keeping rules in the United States are shaping deployment architecture decisions.
- Telecommunications:Mobile network operators optimizing network performance and subscriber retention through real-time usage analytics. German operators are co-locating processing nodes at 5G base stations to reduce transit costs for personalization workloads.
Procurement scale peaks in Retail; Healthcare claims the steepest expansion trajectory as reimbursement pathways open for validated predictive models.
Deployment:
Geographic distribution of compute resources determines latency, sovereignty compliance, and disaster recovery posture for event-intensive workloads.
- Public Cloud:Shared infrastructure with pay-per-use pricing and global region availability. Indian e-commerce platforms leverage these deployments for Diwali traffic spikes without capacity planning.
- Private Cloud:Single-tenant environments with dedicated physical or virtualized resources. German manufacturers select these configurations to satisfy EU AI Act high-risk system documentation requirements.
- Multi-Cloud:Orchestrated workloads across AWS, Azure, and GCP to avoid vendor lock-in and optimize spot pricing. US enterprise retailers are standardizing on these architectures following recent cloud provider outages.
- Edge:Processing at network periphery within mobile base stations, retail stores, or manufacturing floors. Telecommunications operators in India and Germany are deploying these nodes to enable millisecond-latency personalization without core network transit.
Public Cloud captures dominant volume share; Edge deployment is climbing the fastest as 5G infrastructure densifies.
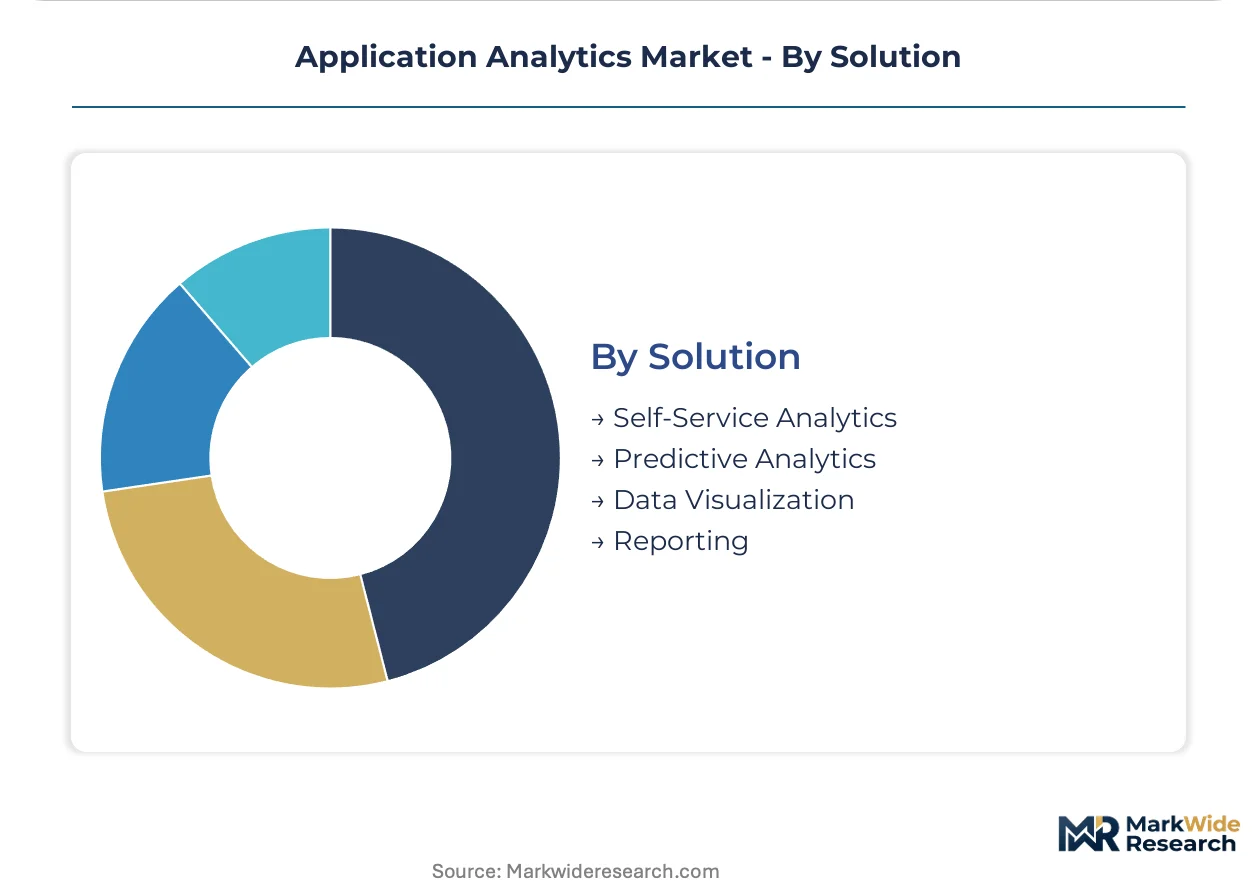
Solution:
Maturity-stage differentiation separates baseline visualization tools from advanced predictive capabilities requiring specialized data science integration.
- Self-Service Analytics:Interfaces enabling business users to construct queries and dashboards without engineering support. Mid-market retailers in India are prioritizing natural language query capabilities that eliminate SQL dependencies.
- Predictive Analytics:Machine learning models forecasting churn, conversion, and lifetime value from behavioral signals. Healthcare networks in Germany require explainability modules satisfying EU AI Act high-risk system classifications.
- Data Visualization:Interactive charting and dashboard construction with drill-down capabilities. This capability segment is gaining share fastest as procurement criteria shift from feature breadth to time-to-first-insight metrics.
- Reporting:Scheduled distribution of standardized metrics to stakeholder audiences. Finance and healthcare compliance teams depend on these outputs for regulatory submission and internal governance.
Reporting solutions maintain the largest installed base; Data Visualization is expanding most quickly as self-service expectations mature across buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States, Germany, and India concentrate application analytics demand as these markets build digital commerce infrastructure and enforce data sovereignty mandates. Cloud migration accelerates platform procurement across all three jurisdictions.
United States
Retail enterprises and healthcare networks drive procurement of real-time user behavior tools. FDA software-as-medical-device guidance validates predictive patient engagement models for clinical analytics reimbursement. The San Francisco Bay Area and Seattle anchor cloud-native platform development clusters where subscription commerce platforms deploy millisecond-latency personalization architectures.
Germany
Automotive suppliers and grocery cooperatives consolidate vendor relationships under centralized IT governance for omnichannel journey tracking. EU AI Act high-risk system classifications mandate explainability modules for credit and health predictive analytics. Munich and Berlin host healthcare networks prioritizing algorithmic decision pathway documentation for clinical validation procurement.
India
Digital commerce platforms scale adoption to handle Unified Payments Interface transaction spikes generating unprecedented event data streams. RBI data localization mandates shape deployment architecture decisions for finance sector buyers. Bangalore and Mumbai clusters concentrate greenfield demand as mid-market retailers prioritize natural language query capabilities eliminating SQL dependencies.
United Kingdom
Mid-market retailers and financial services institutions adopt self-service analytics interfaces as baseline procurement expectations. GDPR Article 30 compliance mandates force platform upgrades to automated audit trails. London anchors fintech clusters where edge computing deployment at 5G base stations reduces data transit costs for real-time personalization workloads.
Japan
Mobile network operators optimize subscriber retention through real-time usage analytics co-located at 5G infrastructure nodes. METI operational resilience requirements influence hybrid architecture procurement for financial institutions. Tokyo and Osaka metropolitan areas concentrate demand for cloud-native event streaming specifications from telecommunications and subscription commerce platforms.
Application Analytics Market Vendor Landscape
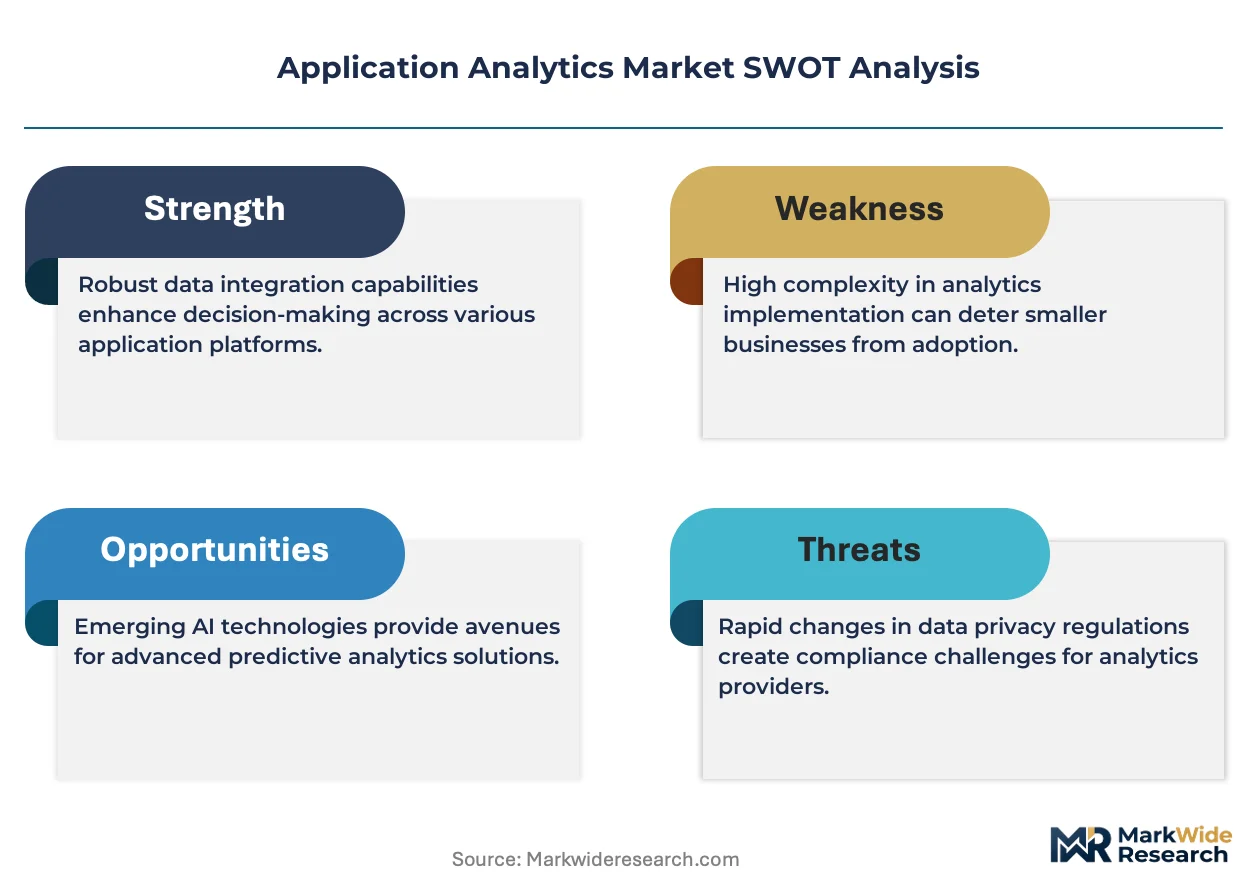
United States-based technology conglomerates anchor one tier of the competitive structure; specialized analytics vendors from multiple geographies hold differentiated positions in product-led growth and mobile attribution segments. The market exhibits tiered concentration with horizontal platform providers, vertical specialists, and open-source alternatives coexisting. Three strategic archetypes dominate: cloud-embedded distribution players, standalone product-analytics specialists, and mobile attribution-focused vendors. Competitive moves center on generative AI convergence for natural language interfaces and edge computing partnerships for latency-sensitive deployments.
Within the cloud-embedded tier, Microsoft exemplifies enterprise distribution leverage through Azure-embedded deployment channels, while Google occupies a position spanning advertising analytics and cloud infrastructure integration. Adobe represents creative-cloud workflow integration with analytics capabilities. Among standalone specialists, Amplitude anchors product-led growth tooling tailored to subscription business models, and Mixpanel sits within the self-service analytics archetype targeting mid-market buyers prioritizing time-to-first-insight metrics.
| Leading Market Players |
|---|
| Adobe |
| Mixpanel |
| Amplitude |
| Microsoft |
| AppsFlyer |
| IBM |
| Adjust |
| App Annie |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up analytics specialists anchor supply-side discipline through portfolio consolidation, translating event-stream infrastructure investments into tiered SaaS pricing power while cloud hyperscalers compress margins at the mid-market entry point.
Pricing Analysis
Volume concentrates in cloud-native SaaS tiers where per-seat subscriptions dominate, while margin pools sit with predictive analytics modules and edge-computing deployments. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade explainability modules from self-serve visualization tools. Pricing pressure stems from open-source stream-processing alternatives and hyperscaler bundling, compressing standalone vendor margins. Mid-market retailers in India exhibit highest price sensitivity due to thin digital commerce margins, whereas German automotive suppliers accept premium tiers for EU AI Act compliance documentation.
Supply Chain Analysis
Freight and data-transit costs concentrate procurement attention on regional instance provisioning, with vendors distributing compute across United States, Germany, and India to satisfy sovereignty mandates. Cloud infrastructure draws from AWS, Azure, and GCP availability zones, while specialized vector database components rest on single-source licensing from niche providers. Single-source vulnerability in GPU cluster access for predictive modeling creates bottleneck risk during demand spikes. Distribution runs through direct enterprise sales teams for regulated sectors and self-serve web onboarding for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The application analytics market is accelerating into a vertical-integration race as vendors pursue captive control over edge-computing hardware partnerships to secure millisecond-latency personalization capabilities.
For Market Incumbents: Lock in enterprise distribution through Azure-embedded and AWS Marketplace channels before hyperscalers deepen native analytics offerings. Consolidate schema governance tooling acquisitions to defend against open-source alternatives eroding mid-market share. Prioritize EU AI Act documentation capabilities as procurement gatekeepers in German healthcare and automotive verticals.
For New Entrants and Emerging Players: The price-point gap between premium explainability modules and economy-tier visualization tools creates entry space for mid-market challengers. Target Indian digital commerce platforms with UPI-optimized event ingestion as the most penetrable greenfield segment. Lead with natural-language query interfaces that eliminate SQL dependencies for business-user-led procurement.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mobile attribution specialists with SDK distribution density in India and Southeast Asia as consolidation targets. Long-term viability hinges on generative-AI integration depth and edge-computing partnership portfolios. Watch FDA software-as-medical-device validation pathways as the inflection signal for healthcare analytics reimbursement expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Partnership | Co-location at 5G base stations in India and Germany reduces transit costs for real-time personalization workloads. |
| Generative AI Integration | Natural language query interfaces from large language models eliminate SQL dependencies for mid-market business users. |
| Regulatory Compliance Investment | EU AI Act explainability modules open procurement pathways in German healthcare and automotive supplier networks. |
| Vertical Specialization | FDA-validated predictive patient engagement models unlock reimbursement for clinical analytics in US healthcare networks. |
| Geographic Expansion | Unified Payments Interface transaction spike handling captures greenfield demand from Indian digital commerce platforms. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and App Annie/Sensor Tower mobile analytics data formed the secondary backbone, cross-referenced with primary interviews across platform engineers at cloud-native vendors, IT procurement officers at mid-market retailers, integration specialists at systems integrators, and regulatory affairs leads at healthcare networks. Bottom-up event-stream volume estimates and top-down SaaS revenue triangulation validated segmentation splits across deployment models, organization sizes, and vertical adoption patterns.
Bottom-up modeling aggregated per-customer event throughput and tiered subscription pricing across cloud-native, hybrid, and on-premise configurations, while top-down analysis calibrated aggregate market expansion against IT software spending trends. Segmentation dimensions spanned deployment architecture, end-user vertical, solution maturity stage, and regional regulatory cluster. CAGRs derived from elasticity-adjusted growth curves incorporating 5G infrastructure densification and GDPR enforcement intensity.
Inputs from SEC filings and mobile analytics databases were available through the study window; gaps in private-company event-volume disclosures introduce uncertainty bands around mid-market penetration estimates. Forecasts reflect documented assumptions regarding cloud migration velocity and regulatory enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Asia-Pacific Crowd Analytics Market
Analytics
Global in-Store Analytics Market
Analytics
Pandemic Analytics Market
Analytics
Data Wrangling Market
Analytics
Network Analytics Services Market
Analytics
Video Analytics Market
Analytics
Multichannel Analytics Market
Analytics
Global Mobile BI Market
Analytics
Sentiment Analytics Market
Analytics
Canada Contact Center Analytics Market
Analytics
Legal Analytics Market
Analytics
Analytics Sandbox Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Sales Intelligence Market
Analytics
Customer Data Platform Market