
 Condition Monitoring Service Market | 2026-2036
Condition Monitoring Service Market Size, Share, and Industry Trends Forecast 2026-2036
Condition Monitoring Service Market Analysis
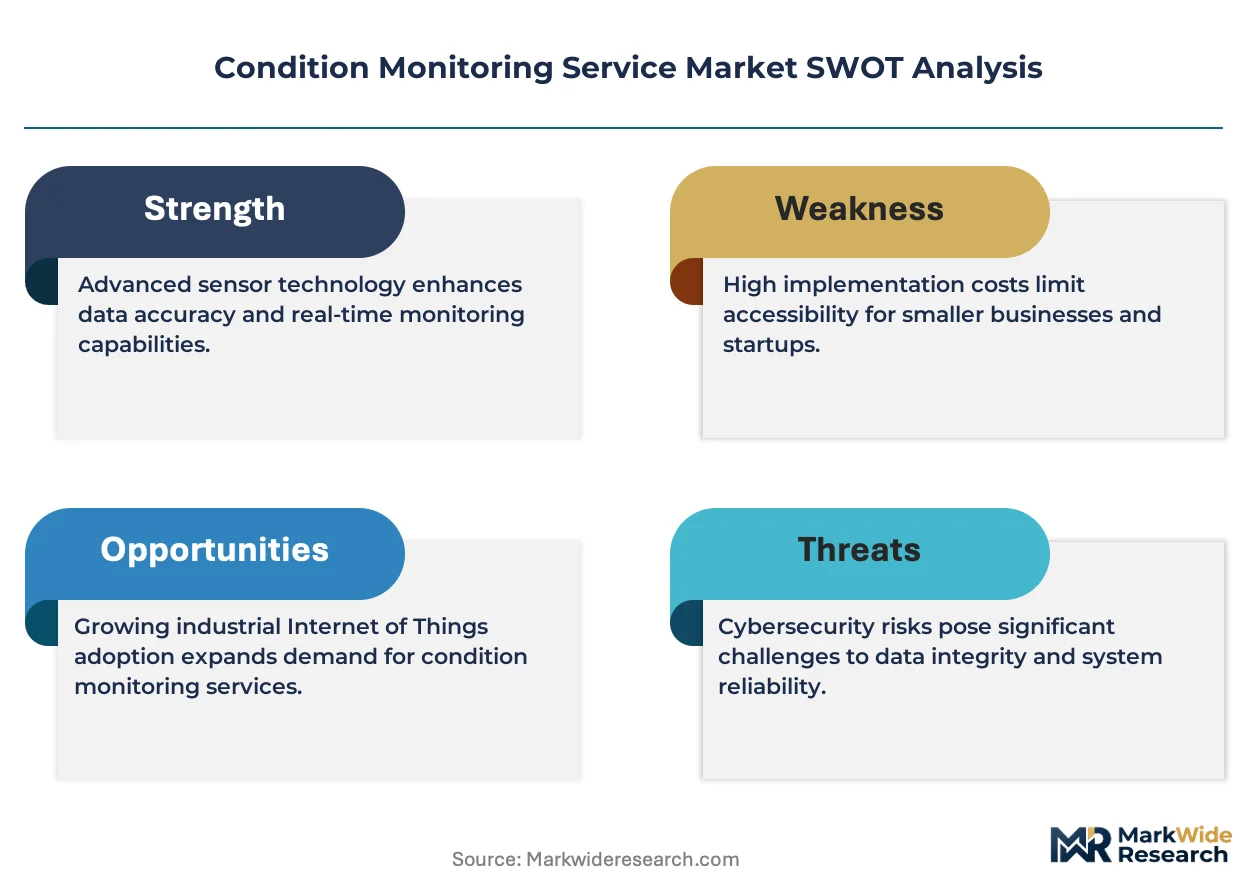
The EU Green Deal is pivoting industrial operators toward predictive asset strategies that cut emissions through reduced equipment failure and optimized energy draw. SKF AB leverages its bearing diagnostics heritage to anchor rotating machinery contracts across European process industries. Siemens AG competes through integrated software platforms that merge IoT sensor streams with digital twin visualization. Emerson Electric Co. specializes in vibration analysis protocols for oil and gas infrastructure, sustaining deep relationships with offshore operators.
Condition monitoring service encompasses the systematic acquisition and interpretation of machinery health indicators—vibration spectra, thermal profiles, oil particulate counts, and acoustic emissions—typically sampled at intervals from continuous to quarterly depending on criticality and failure modes. These services translate raw sensor data into maintenance decisions that prevent catastrophic asset failure and extend mean time between repairs. Predictive maintenance commands the largest revenue pool among service types, while AI Solutions within the technology dimension is capturing the fastest expansion as neural networks improve fault classification accuracy from noisy operational data. Manufacturing dominates the industry vertical split, though Energy is narrowing the gap as renewable fleets multiply the count of geographically dispersed turbines and inverters requiring remote oversight.
The EU Machinery Directive and ISO 17359 standards mandate documented risk assessment procedures for mechanical systems, directly elevating the compliance value of formalized monitoring programs. EPA leak detection protocols in the United States and Japan's METI energy efficiency guidelines for industrial facilities similarly embed continuous oversight into permitted operations. Stakeholders must weigh whether to build captive analytics capabilities or outsource to platform-native providers as sensor data volumes scale beyond conventional maintenance team bandwidth.
Market Dynamics
Energy utilities are expanding predictive maintenance contracts to reduce unplanned downtime, while the EU F-Gas Regulation and Machinery Directive tighten equipment reliability requirements across industrial sites. This regulatory compression is forcing asset-intensive operators to formalize continuous oversight programs or risk operational penalties.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants mandates leak detection protocols that embed continuous monitoring into HVAC and process cooling systems across chemical plants.
- AI Solutions:Neural networks are improving fault classification accuracy from noisy operational data, expanding service attach rates in manufacturing facilities with legacy sensor infrastructure.
- German automotive clusters:Dense asset bases in Stuttgart and Wolfsburg require continuous oversight, concentrating demand for vibration and thermal analysis services.
Market Restraints
- Sensor hardware cost volatility:MEMS accelerometer and infrared thermography component prices fluctuate with semiconductor foundry capacity constraints in East Asia.
- Data interoperability gaps:Proprietary protocols from incumbent automation vendors fragment analytics platforms, complicating multi-site dashboard consolidation.
- Qualified analyst scarcity:Vibration spectrum interpretation and oil particulate diagnosis require certified personnel whose training pipelines lag market expansion.
Strategic Opportunities
- Offshore wind expansion:Geographically dispersed turbine fleets in the North Sea create demand for remote vibration monitoring and drone-based thermal inspection services.
- EU Green Deal incentives:Carbon border adjustment mechanisms reward predictive strategies that cut emissions through reduced equipment failure and optimized energy draw.
- Edge-to-cloud convergence:Integration of on-premise inference engines with centralized digital twins enables tiered service pricing based on latency requirements.
Industry Challenges
- ISO 17359 certification timelines:Documented risk assessment procedures for mechanical systems require specialized auditing capacity that stretches third-party service providers.
- Legacy SCADA integration:Brownfield facilities operate decades-old control architectures that resist seamless sensor data ingestion without costly gateway retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condition Monitoring Service Market |
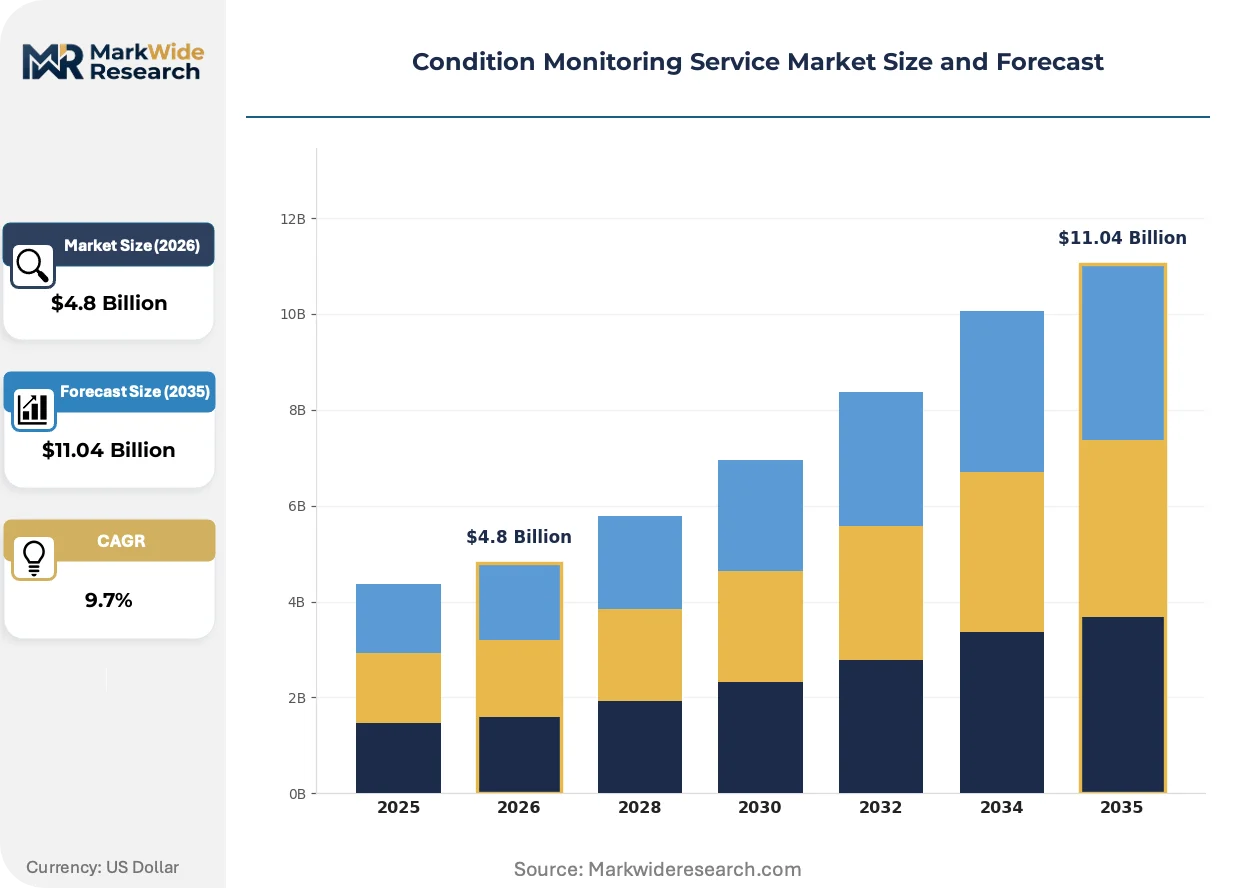
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Remote Monitoring, Predictive Maintenance, Data Analytics, Visual Inspection Industry Vertical: Manufacturing, Energy, Transportation, Healthcare Technology: IoT Sensors, Software Platforms, Cloud Computing, AI Solutions Application: Equipment Health, Asset Management, Performance Optimization, Compliance Monitoring |
| Companies Covered | Emerson Electric Co., SKF AB, Honeywell International Inc., General Electric, Siemens AG, Rockwell Automation Inc., ABB Ltd, Schaeffler Group, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condition Monitoring Service Market Emerging Trajectories
Digital twin visualization is merging with IoT sensor streams to create persistent machinery replicas that update in near-real time. This convergence is compressing the feedback loop between anomaly detection and maintenance dispatch across process industries.
Edge-deployed machine learning inference engines are rewriting how vibration and acoustic data get processed at the asset level. Offshore oil and gas operators are adopting these systems fastest, driven by bandwidth constraints on subsea fiber links. The technology is rewriting contract structures by enabling tiered service levels based on local versus cloud analytics.
The EU Machinery Directive's 2023 amendments tightened documented risk assessment requirements for mechanical systems with safety-critical functions. Industrial operators must now demonstrate continuous oversight or face operational shutdown authority from national market surveillance agencies. German chemical manufacturers and Italian packaging machinery exporters are responding by embedding monitoring clauses into supplier qualification questionnaires.
Asset owners are unbundling after-sales service contracts from original equipment manufacturer supply agreements. Procurement teams at European automotive Tier-1 suppliers now issue separate RFPs for diagnostics software, sensor hardware, and analyst labor. This pattern is most visible in the Rhine-Ruhr industrial corridor, where multi-site fleet operators negotiate directly with platform-native analytics providers.
Condition Monitoring Service Market Segmentation
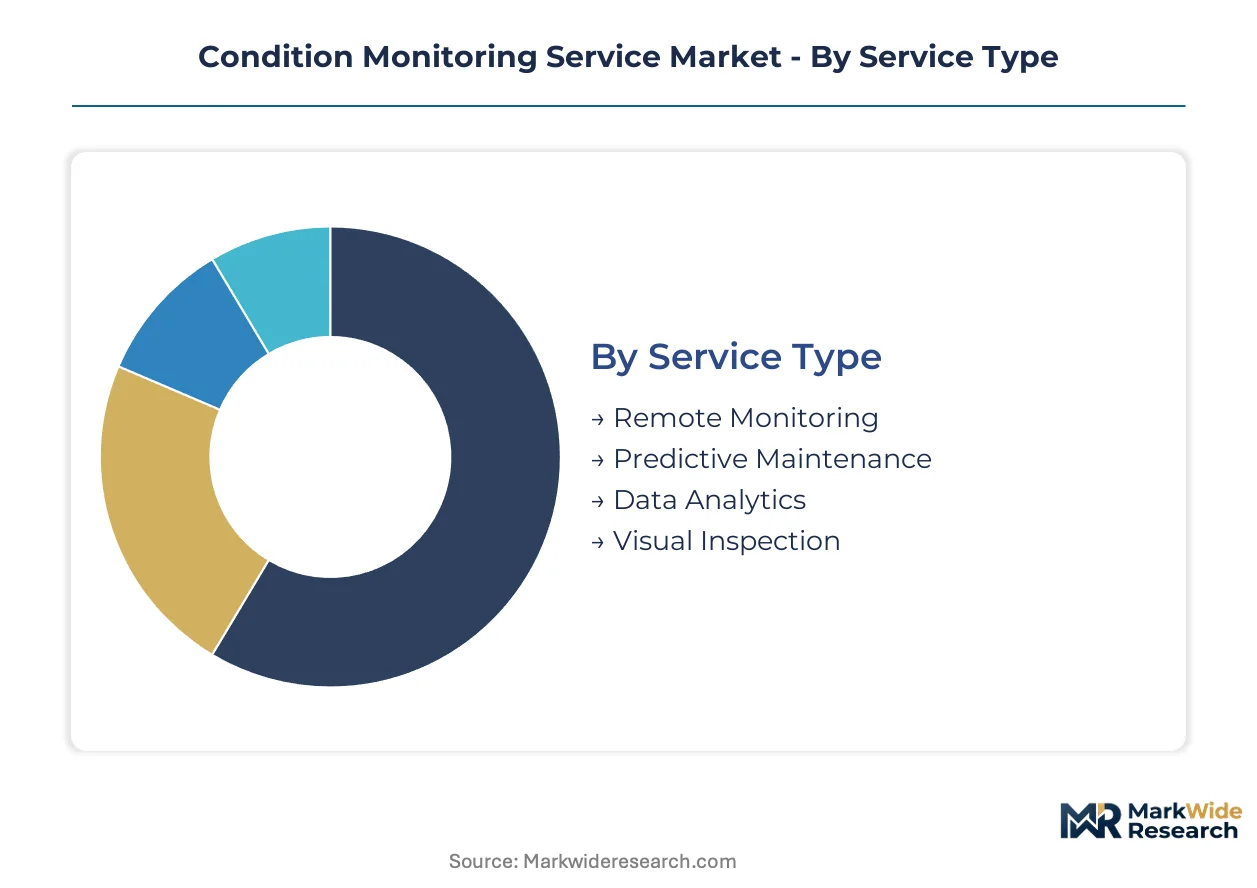
Condition monitoring services fragment across four dimensions that determine procurement priorities. Service type and technology choices dominate contract negotiations, while industry vertical dictates regulatory exposure and application scope shapes sensor deployment density.
Service Type:
Standardization dominates remote diagnostics, whereas predictive maintenance contracts demand heavy customization to asset failure modes and operational criticality tiers.
- Predictive Maintenance:Systematic scheduling of interventions based on degradation trend analysis rather than fixed intervals. German automotive manufacturers and North Sea offshore operators anchor demand, driven by unplanned downtime costs exceeding $100,000 per hour in continuous process environments.
- Remote Monitoring:Continuous data transmission from geographically dispersed assets to centralized diagnostic centers. Demand concentrates in US wind farm portfolios and Australian mining operations, where travel costs for manual inspection dwarf sensor hardware investments.
- Data Analytics:Pattern recognition across historical operational datasets to identify precursors to failure.
- Visual Inspection:Periodic technician-led assessment using borescope, thermal imaging, and drone-mounted cameras.
Leading the category by volume: Predictive Maintenance. Growing fastest: Remote Monitoring.
Industry Vertical:
Manufacturing procurement emphasizes cost-per-unit-produced metrics, while energy operators prioritize availability guarantees and regulatory audit trails.
- Energy:Oversight of turbines, transformers, and inverters across generation, transmission, and distribution networks. US utility-scale solar and German offshore wind expansion are concentrating demand, with FERC interconnection reliability standards and EU Green Deal carbon accounting requirements mandating documented asset health.
- Manufacturing:Rotating machinery, hydraulic systems, and thermal processing equipment in discrete and process production. Italian packaging machinery exporters and Japanese automotive Tier-1 suppliers dominate procurement, responding to ISO 17359 risk assessment mandates and customer supplier qualification questionnaires.
- Transportation:Fleet-wide diagnostics for rail rolling stock, commercial aviation, and maritime vessels.
- Healthcare:Critical equipment reliability for imaging systems, sterilization infrastructure, and emergency power.
Highest contract values: Energy. Steepest expansion trajectory: Manufacturing quality compliance programs.
Technology:
IoT sensors and software platforms command mature pricing, while AI Solutions capture premium margins through fault classification accuracy gains.
- AI Solutions:Neural network architectures trained on labeled failure mode datasets to automate anomaly classification from vibration, thermal, and acoustic signatures. US oil and gas supermajors and South Korean shipbuilders are deploying these systems fastest, driven by analyst scarcity and the need to process sensor data volumes exceeding human interpretation capacity.
- IoT Sensors:MEMS accelerometers, infrared thermography arrays, and oil particulate counters deployed at the asset level. Chinese semiconductor foundry output and German precision engineering clusters supply hardware, though MEMS pricing volatility complicates multi-year service contract structuring.
- Software Platforms:Dashboard visualization, alert routing, and maintenance work order integration.
- Cloud Computing:Scalable storage and compute for multi-site fleet analytics.
Widest deployment: IoT Sensors. Climbing the fastest: AI Solutions.
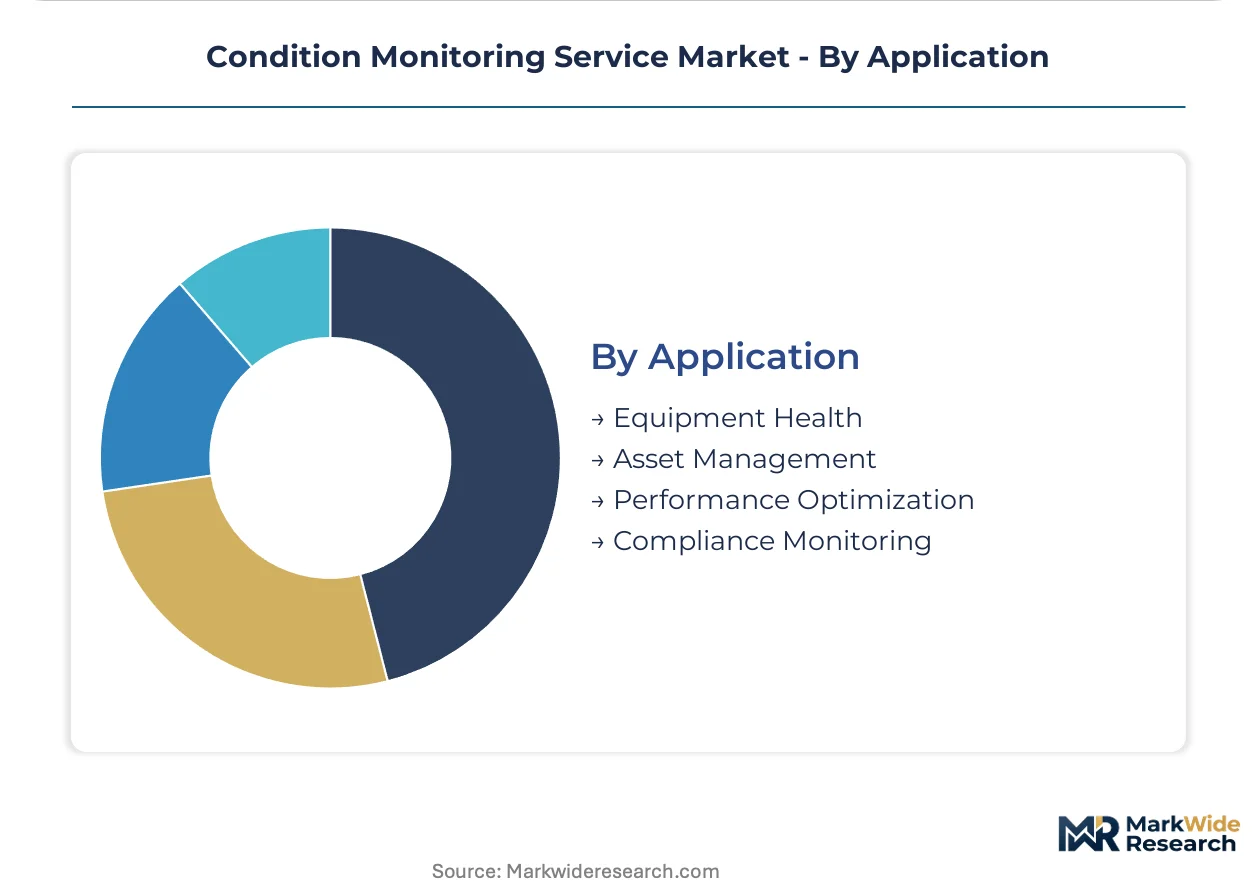
Application:
Equipment Health monitoring focuses on single-asset failure prevention, while Asset Management scales to fleet-wide optimization and capital planning.
- Equipment Health:Real-time tracking of vibration spectra, thermal profiles, and lubricant condition to prevent catastrophic failure. US chemical plants subject to EPA leak detection protocols and EU chemical manufacturers under F-Gas Regulation refrigerant phasedown requirements are embedding continuous oversight into permitted operations.
- Asset Management:Fleet-wide visibility into utilization rates, remaining useful life estimation, and capital replacement timing. Brazilian mining conglomerates and Saudi Aramco processing facilities leverage these capabilities to optimize maintenance spend across dispersed asset bases.
- Performance Optimization:Energy efficiency and throughput maximization through operational parameter adjustment.
- Compliance Monitoring:Automated documentation for regulatory audit trails and certification maintenance.
Deepest market penetration: Equipment Health. Gaining share fastest: Asset Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service delivery concentrates in Western Europe and East Asia where precision manufacturing density sustains analyst talent pools, while North American utilities drive contract scale through renewable fleet expansion.
Germany
Automotive OEMs in Stuttgart and Wolfsburg operate dense asset bases requiring continuous vibration oversight. The EU Machinery Directive mandates documented risk assessment for mechanical systems with safety-critical functions. Chemical manufacturers along the Rhine-Ruhr corridor embed F-Gas Regulation leak detection protocols into HVAC and process cooling contracts.
United States
Utility-scale solar and offshore wind portfolios multiply geographically dispersed turbine and inverter counts demanding remote oversight. FERC interconnection reliability standards require documented asset health for grid-connected generation. Texas and California energy operators anchor predictive maintenance contract volume through renewable fleet expansion.
China
Steel and cement producers under dual carbon goals deploy thermal monitoring to optimize energy draw and cut emissions. GB standards for industrial equipment reliability elevate compliance value of formalized programs. Yangtze River Delta manufacturing clusters integrate MEMS accelerometer networks into legacy production lines.
Japan
Shipbuilders and automotive Tier-1 suppliers process sensor data volumes exceeding human interpretation capacity. METI energy efficiency guidelines for industrial facilities embed continuous oversight into permitted operations. Nagoya automotive clusters and Kobe maritime yards anchor demand for acoustic emission analysis.
South Korea
Semiconductor foundries and battery cell manufacturers operate continuous process environments where unplanned downtime costs exceed $100,000 per hour. MFDS-equivalent industrial safety frameworks pressure formalized monitoring adoption. Gyeonggi-do electronics manufacturing complexes contract vibration spectrum interpretation services.
Condition Monitoring Service Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive sensor hardware production. European bearing specialists and American automation platforms occupy distinct tier positions, while Asian electronics fabricators challenge on MEMS component cost. Three archetypes dominate: rotating machinery heritage players, integrated software-IoT platforms, and precision sensor component suppliers. Consolidation pressure runs through strategic partnerships between analytics software vendors and semiconductor foundries, alongside geographic expansion into offshore wind service corridors.
Within the rotating machinery heritage tier, SKF AB and Schaeffler Group exemplify European precision engineering concentration, anchoring vibration diagnostics contracts through bearing-centric expertise. Siemens AG and Emerson Electric Co. represent the integrated platform archetype, merging IoT sensor streams with visualization layers. Honeywell International Inc. and Rockwell Automation Inc. occupy positions spanning industrial automation hardware and predictive analytics software, reflecting American conglomerate diversification patterns.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| SKF AB |
| Honeywell International Inc. |
| General Electric |
| Siemens AG |
| Rockwell Automation Inc. |
| ABB Ltd |
| Schaeffler Group |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
Captive sensor production by diversified industrial conglomerates anchors both supply security and pricing power in condition monitoring services. German precision engineering clusters and Chinese semiconductor foundries feed component networks that service providers leverage to bundle hardware with analytics software, compressing third-party supplier margins while elevating integrated platform pricing authority.
Pricing Analysis
Cost-down pressure on mid-tier service contracts accelerates because MEMS accelerometer pricing volatility complicates multi-year agreement structuring. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17359-certified predictive maintenance programs from remote monitoring subscriptions and per-incident diagnostic calls. Price differentiation traces to certification grade and geographic service density, with North Sea offshore operators showing lowest price sensitivity due to unplanned downtime costs exceeding six figures hourly, while mid-size manufacturing facilities in Eastern Europe negotiate aggressively on sensor hardware bundles.
Supply Chain Analysis
Domestic-content mandates in China's dual carbon policy framework and India's PLI scheme for industrial automation are reshaping sourcing patterns for vibration sensors and thermal imaging arrays. Component supply concentrates in China, Germany, and South Korea, with MEMS foundry output, precision bearing manufacturing, and infrared detector fabrication feeding downstream integration. Raw material dependencies span silicon wafers, rare-earth magnet materials, and specialized lubricant formulations. Single-source vulnerability in semiconductor foundry capacity poses structural risk. Distribution runs through OEM aftermarket channels, direct platform subscriptions, and third-party service integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as AI-native analytics platforms displace legacy diagnostic labor models, forcing sub-scale service providers toward acquisition or exit. Analyst scarcity and certification bottlenecks amplify competitive sorting.
For Market Incumbents: To counter AI-native platform entrants automating vibration spectrum interpretation, SKF AB and Siemens AG must deepen captive sensor production through backward integration into MEMS design partnerships, while locking multi-site automotive contracts via embedded digital twin clauses that raise switching costs for German OEM procurement teams. For New Entrants and Emerging Players: The price-point gap between premium ISO-certified predictive programs and economy-tier remote monitoring subscriptions creates entry space for mid-market specialists targeting Italian packaging machinery exporters and Australian mining operations with hybrid offerings—combining drone-based thermal inspection with cloud analytics dashboards sold through regional automation distributors rather than direct enterprise salesforces. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial conglomerates seeking analytics software capabilities. Long-term viability hinges on platform attach rates rather than hardware shipment volumes. Acquisition targets with demonstrated F-Gas Regulation compliance modules and offshore wind service credentials command premium positioning. The signal to watch is contract renewal rates among North Sea turbine operators as proxy for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Diagnostics Platform Launch | Neural network automation addresses certified analyst scarcity constraining service expansion. |
| Offshore Wind Service Corridor Expansion | North Sea turbine fleets require remote vibration monitoring beyond legacy oil and gas infrastructure. |
| Backward Integration into MEMS Sensors | Captive accelerometer production insulates margin from Chinese foundry pricing volatility. |
| EU Green Deal Compliance Module Development | Carbon border adjustment mechanisms reward predictive strategies with documented emission reductions. |
| Digital Twin Integration Partnership | Persistent machinery replicas compress anomaly-to-dispatch feedback loops for process industries. |
Methodological Framework
Independent corroboration across maintenance directors at German automotive OEMs, platform engineers at industrial software vendors, and procurement leads at North Sea offshore operators underwrites the qualitative findings. Secondary validation drew from SEC filings of listed automation conglomerates, EU Machinery Directive implementation guidance, and FERC interconnection reliability standards. Bottom-up service contract enumeration and top-down industrial automation spend estimates were reconciled through iterative triangulation.
Rate-of-change decomposition across the analysis window segmented expansion by service type, technology tier, industry vertical, and application scope—specifically isolating predictive maintenance attach rates, AI solution penetration curves, and remote monitoring adoption in renewable energy fleets. CAGRs were derived from fitted growth curves applied to documented contract values and sensor deployment volumes, with cross-checks against utility-scale solar capacity additions and offshore wind turbine installation pipelines.
Inputs from primary fieldwork and regulatory publication databases were available through the study window; gaps in privately held service provider financials introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions regarding MEMS pricing stabilization, analyst certification pipeline expansion, and EU F-Gas Regulation enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Marketing Analytics Software Market
Analytics
Data Discovery Market
Analytics
Identity Analytics Market
Analytics
Greece ICT Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
UK Video Analytics Market
Analytics
Load (ETL) Market
Analytics
Global Mobile BI Market
Analytics
Global Hadoop Big Data Analytics Market
Analytics
Global Healthcare Cloud Based Analytics Market
Analytics
Business Value Dashboard Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Global in-Store Analytics Market
Analytics
Imagery Analytics Market
Analytics
Web Analytics Market
Analytics
Middle East and Africa Location Analytics Market