
 Global Social Intelligence Market | 2026-2036
Global Social Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Global Social Intelligence Market Outlook
Enterprise software distribution through cloud marketplaces is reshaping how social intelligence platforms reach buyers. IBM Corporation leverages its hybrid cloud infrastructure to anchor large-scale deployments across regulated industries. Brandwatch competes through specialized visual analytics capabilities that differentiate its offering from generalist competitors. Dataminr sustains real-time alert delivery dominance by controlling proprietary data ingestion pipelines for breaking event detection.
Social intelligence encompasses the systematic collection, processing, and analysis of publicly available social media data, natural language inputs, and digital behavioral signals using machine learning models, semantic analysis engines, and network graph algorithms to generate actionable organizational insights. Cloud-based deployment leads the infrastructure mix due to elastic compute requirements for streaming data processing, though hybrid architectures are gaining traction among healthcare providers and government agencies managing sensitive information boundaries. Application activity concentrates in brand monitoring and customer experience management, where margin pools sit thickest because these use cases deliver directly measurable return on marketing spend and retention outcomes.
The EU AI Act and GDPR impose strict algorithmic accountability and data minimization requirements on automated sentiment classification and personal data extraction, compelling vendors to embed explainability layers and consent management protocols. The US FDA and SEC are scrutinizing health-related social listening and financial sentiment tools for potential regulatory arbitrage in consumer protection domains. Stakeholders must monitor evolving cross-border data transfer restrictions and emerging sector-specific AI governance frameworks that will determine which platform architectures sustain market access.
Market Dynamics
Cloud marketplaces are consolidating distribution power for social intelligence platforms, compressing traditional enterprise sales cycles while amplifying vendor switching costs through integrated billing and identity management layers.
Growth Catalysts
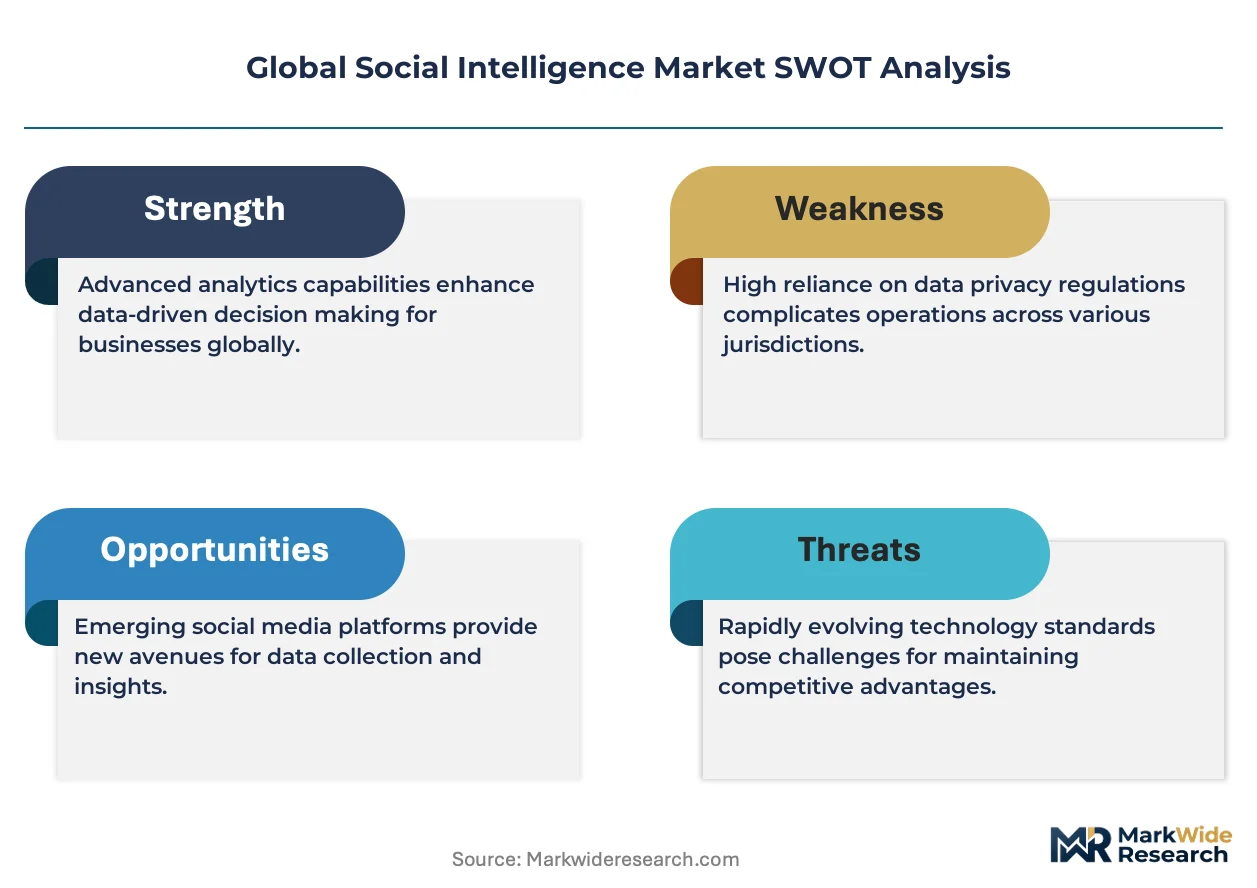
- EU AI Act compliance mandates:The EU AI Act's risk classification framework for automated decision systems is forcing enterprises to upgrade legacy sentiment analysis tools, creating replacement demand for explainable AI architectures.
- Real-time streaming infrastructure:Financial institutions in the United States are deploying predictive risk analytics on social data streams to detect market-moving events before traditional news channels capture them.
- Visual content explosion:Image and video analytics capabilities are expanding addressable use cases beyond text-based monitoring into logo detection, scene classification, and influencer content verification.
Market Restraints
- API cost volatility:Platform dependency on Twitter/X, Reddit, and Meta APIs exposes vendors to unpredictable pricing resets and access term changes that compress gross margins.
- GDPR data minimization:European regulators are restricting historical data retention periods for personal social media posts, limiting training dataset depth for machine learning models.
- Technical hallucination rates:Large language models deployed for sentiment classification generate false positive rates above acceptable thresholds for regulated industries like healthcare and finance.
Strategic Opportunities
- India's digital public infrastructure:The country's expanding UPI transaction data and open social graph protocols create novel signal sources for consumer behavior prediction unavailable in Western markets.
- Convergence of social intelligence with threat detection:Fusion of social listening platforms with cybersecurity incident response tools is opening enterprise security budgets as a new revenue pool.
- Japan's METI data trust frameworks:Regulatory clarity on cross-border data flows is positioning Japanese financial institutions as early adopters of offshore-processed social analytics.
Industry Challenges
- Multilingual NLP engineering scarcity:Talent capable of building accurate sentiment models for low-resource languages commands premium compensation that stretches R&D budgets.
- Legacy system integration friction:Enterprise CRM and marketing automation platforms require custom connector development that extends implementation timelines and strains professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Social Intelligence Market |
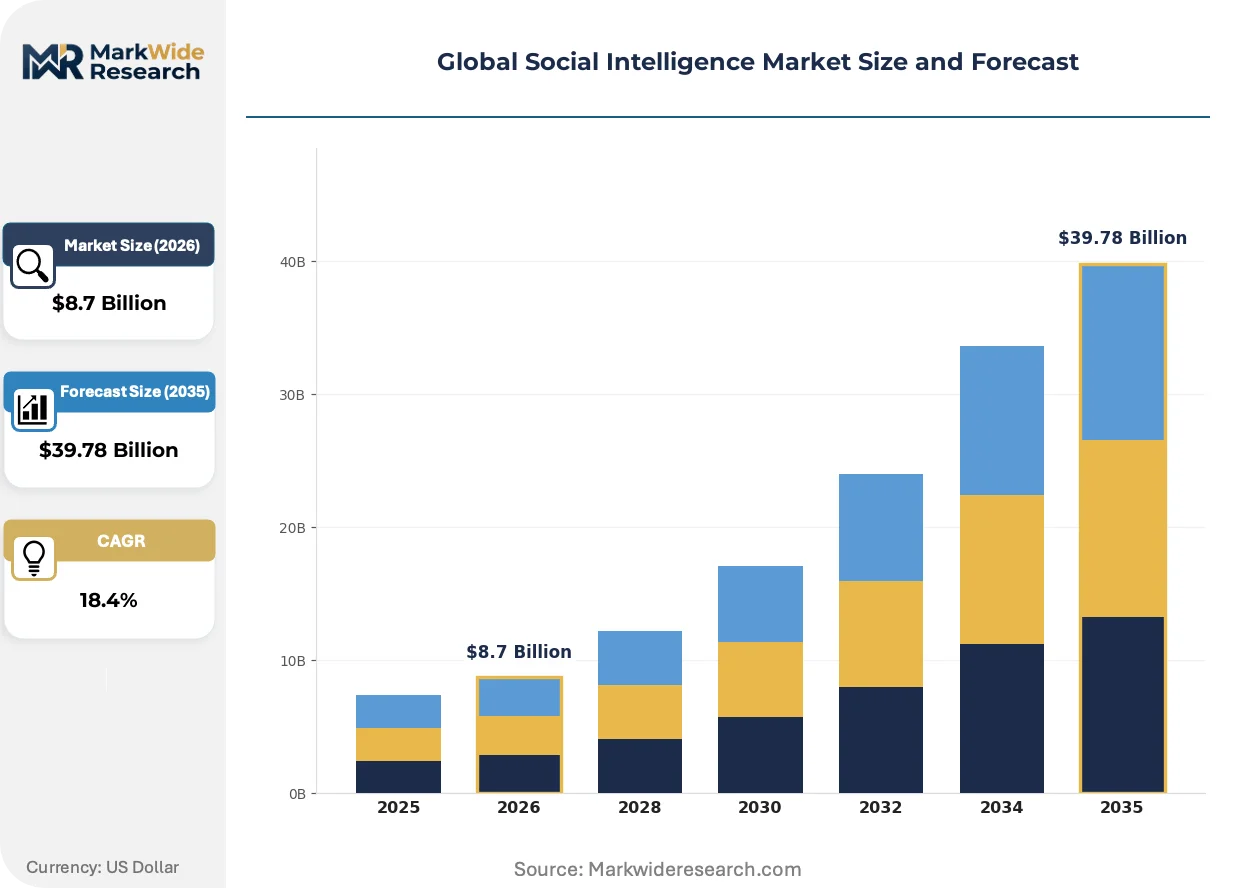
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Retailers, Financial Institutions, Healthcare Providers, Government Agencies Service Type: Consulting, Integration, Managed Services, Support Application: Brand Monitoring, Customer Experience, Market Research, Crisis Management |
| Companies Covered | Synthesio, Dataminr, IBM Corporation, Gupshup, Moz, Brandwatch, SOCi, Hearsay Systems, Sysomos Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Social Intelligence Market Strategic Shifts
Foundation models are compressing the feature gap between specialized social intelligence vendors and generalist AI platforms, forcing differentiation through proprietary data pipelines and vertical-specific tuning rather than raw algorithmic performance.
Multimodal transformer architectures are digitizing how platforms process video, audio, and image content alongside text. Retailers in the United States are deploying these systems to track brand presence in user-generated TikTok and Instagram content at scale. The technology is digitizing competitive intelligence workflows that previously required manual human review of visual assets.
The EU AI Act's transparency requirements for high-risk AI systems are mandating algorithmic impact assessments and human oversight protocols for automated content moderation tools. Social intelligence vendors serving European enterprises must now embed explainability layers that trace sentiment classifications back to source evidence. Financial services firms in Germany and France are demanding these audit trails as procurement prerequisites.
Subscription fatigue among mid-market buyers is fragmenting purchasing authority away from centralized IT procurement toward line-of-business units with discretionary budgets. Marketing departments in the United Kingdom are increasingly procuring point solutions through self-service marketplaces rather than enterprise-wide platform contracts. This shift concentrates vendor attention on product-led growth mechanics and usage-based pricing experimentation.
Global Social Intelligence Market Segmentation
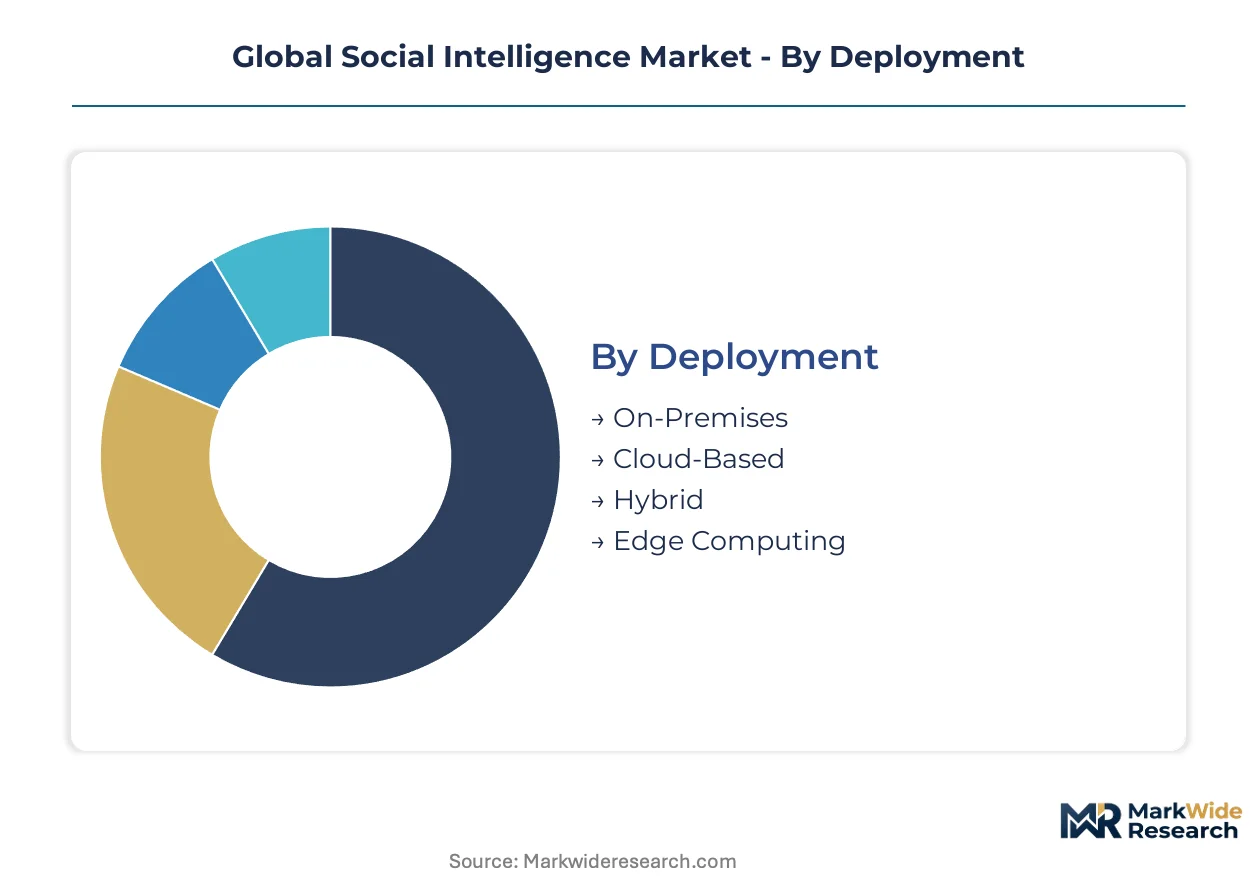
Social intelligence platforms fragment across deployment architectures, buyer verticals, and service delivery models. Each segment carries distinct margin profiles, renewal dynamics, and integration complexity that shape vendor resource allocation and partnership strategies.
Deployment:
After-sales service intensity varies sharply across deployment modes, with on-premises installations demanding sustained field engineering support while cloud-based deployments shift burden toward remote monitoring and API maintenance.
- Cloud-Based:Elastic compute infrastructure enables streaming data processing at scale without capital expenditure. Financial institutions in the United States concentrate procurement here for predictive risk analytics, driven by regulatory pressure for real-time market surveillance capabilities.
- Hybrid:Split architectures partition sensitive data processing on-premises while leveraging cloud analytics for non-regulated workloads. Healthcare providers and government agencies adopt this model to manage information boundaries under HIPAA and classified data protocols.
- On-Premises:Fully captive infrastructure serves defense contractors and intelligence agencies with air-gapped security requirements.
- Edge Computing:Distributed processing nodes reduce latency for retail location-based sentiment analysis and real-time influencer content verification.
By volume, Cloud-Based leads. By growth pace, Hybrid is gaining share fastest as regulated industries seek compliance-flexible architectures.
End User:
Customer concentration patterns diverge across verticals, with financial services buyers consolidating spend through central procurement while retail procurement fragments across brand-level marketing units.
- Financial Institutions:Banks, hedge funds, and insurance carriers deploy predictive risk analytics on social data streams to detect market-moving events. Demand concentrates in the United States under SEC scrutiny of sentiment-driven trading signals.
- Retailers:Brand monitoring and customer experience management dominate use cases, with TikTok and Instagram visual analytics commanding premium pricing. Procurement authority is decentralizing toward line-of-business marketing departments.
- Healthcare Providers:Patient sentiment tracking and adverse event detection require FDA-aligned validation protocols that extend implementation timelines.
- Government Agencies:Crisis management and public opinion monitoring drive classified procurements with stringent domestic data residency requirements.
Financial Institutions anchor current revenue. Retailers show the steepest expansion trajectory as visual content analytics penetrates influencer marketing workflows.
Service Type:
Margin accretion concentrates in recurring revenue streams, with managed services and support contracts delivering superior lifetime value against one-time integration projects.
- Managed Services:Outsourced platform operation and model retraining relieve enterprise talent constraints. Demand is climbing fastest among mid-market buyers lacking internal data science capacity.
- Integration:Custom connector development for CRM and marketing automation platforms extends professional services engagement duration. Legacy system friction stretches timelines and strains vendor delivery capacity.
- Consulting:Strategic advisory on use case selection and organizational change management accompanies initial deployments.
- Support:Tiered response commitments and dedicated technical account management underpin enterprise renewal rates.
Integration commands the largest project value. Managed Services delivers the most predictable recurring revenue expansion.
Application:
Use case maturity determines pricing power, with brand monitoring and customer experience management offering direct marketing ROI measurement that justifies premium platform fees.
- Brand Monitoring:Systematic tracking of logo presence, sentiment trajectory, and competitive positioning across social channels. Retailers in the United States deploy multimodal transformers to process TikTok and Instagram video content at scale.
- Customer Experience:Real-time response routing and satisfaction prediction based on social touchpoint analysis. Financial institutions prioritize this application for retention outcome measurement.
- Market Research:Qualitative signal extraction for product development and campaign pre-testing, competing directly with traditional survey methodologies.
- Crisis Management:Breaking event detection and escalation protocols for reputation threats, with Dataminr sustaining dominance through proprietary data ingestion pipelines.
Brand Monitoring holds the largest installed base. Crisis Management is expanding most quickly as enterprise security budgets converge with social listening platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable systems landing at Ashburn, Virginia and Bude, England underpin data throughput capacity for social intelligence platforms processing North American and European social media streams.
United States
Financial institutions in Manhattan deploy predictive risk analytics on real-time social data streams under SEC scrutiny of sentiment-driven trading signals. The FDA examines health-related social listening tools for consumer protection compliance. Silicon Valley clusters anchor cloud marketplace distribution channels that compress enterprise sales cycles.
Germany
Automotive manufacturers in Stuttgart and Munich integrate social sentiment feeds into supply chain risk monitoring systems. The EU AI Act mandates algorithmic impact assessments for automated content moderation tools deployed by German enterprises. Frankfurt's financial services sector demands explainable AI audit trails as procurement prerequisites.
United Kingdom
Marketing departments in London procure point solutions through self-service cloud marketplaces rather than centralized IT contracts. The Information Commissioner's Office enforces GDPR data minimization rules that restrict historical social media data retention. Manchester and Birmingham house mid-market buyers driving managed services demand.
Japan
METI data trust frameworks provide regulatory clarity on cross-border data flows for financial institutions adopting offshore-processed social analytics. Tokyo-based enterprises lead early adoption of multimodal transformer architectures for visual content verification. Osaka manufacturers apply social intelligence to B2B customer experience management.
India
The country's expanding UPI transaction data and open social graph protocols generate novel consumer behavior signals unavailable in Western markets. SEBI monitors social sentiment tools for market manipulation risks in Mumbai's equity trading ecosystem. Bangalore and Hyderabad clusters concentrate engineering talent for multilingual NLP model development.
Global Social Intelligence Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying data ingestion pipelines and semantic analysis engines. The vendor base organizes around three strategic archetypes: cloud infrastructure anchors, visual analytics specialists, and real-time alert delivery platforms. Consolidation pressure concentrates among mid-market players lacking proprietary data assets. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and vertical integration into managed services delivery.
Within the cloud infrastructure tier, IBM Corporation exemplifies the hybrid deployment anchor position across regulated industries. Dataminr occupies a distinctive position controlling proprietary data ingestion pipelines for breaking event detection. Brandwatch represents the visual analytics specialization vector that differentiates from generalist competitors through multimodal content processing capabilities.
| Leading Market Players |
|---|
| Synthesio |
| Dataminr |
| IBM Corporation |
| Gupshup |
| Moz |
| Brandwatch |
| SOCi |
| Hearsay Systems |
| Sysomos Inc. |
| Others |
Value Chain & Pricing Dynamics
Ashburn, Virginia's hyperscale data center cluster anchors elastic compute capacity for streaming social data processing, concentrating infrastructure leverage among cloud-native platforms and compressing margins for vendors lacking captive server resources. This geographic concentration of processing power translates directly into pricing tier compression for mid-market buyers while amplifying cost advantages for incumbents with dedicated capacity reservations.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, mid-market, and self-service entry levels, with annual contract value thresholds determining platform access depth and API rate limits. Certification under the EU AI Act's high-risk system protocols commands premium positioning, particularly among Frankfurt and Paris financial institutions demanding explainable AI audit trails. Cost compression in the mid-market tier intensifies because API cost volatility from Twitter/X and Meta data access erodes vendor gross margins. Enterprise financial institutions exhibit the lowest price sensitivity due to regulatory compliance mandates, while UK marketing departments procuring through self-service marketplaces drive pricing softness through fragmented purchasing authority.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for semiconductor-dependent inference hardware, with NVIDIA GPU procurement timelines extending vendor delivery schedules. Taiwan, South Korea, and the United States anchor geographic supply concentration for high-performance compute chips essential to multimodal transformer deployment. Raw material dependencies span advanced memory modules, specialized networking silicon, and liquid cooling infrastructure. Single-source vulnerability concentrates in TSMC's advanced node fabrication for training accelerators. Distribution runs through hyperscale cloud marketplaces that compress traditional enterprise sales cycles while embedding vendor switching costs through integrated billing layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering talent for multilingual NLP model development sits as the binding constraint, with Bangalore and Hyderabad clusters commanding premium compensation that stretches R&D budgets across the competitive landscape. This capability scarcity rewards vendors who lock in technical teams through equity structures and research partnerships with Indian Institutes of Technology.
For Market Incumbents: Build proprietary data ingestion moats around real-time breaking event pipelines to defend against generalist AI platform encroachment. Deepen backward integration into custom silicon for inference acceleration, reducing dependency on NVIDIA's supply-constrained GPU allocations. Consolidate mid-market competitors lacking captive data assets before foundation models compress feature differentiation further. For New Entrants and Emerging Players: Pursue India's UPI transaction data integration as a white-space signal source unavailable to Western incumbents, leveraging the country's open social graph protocols for consumer behavior prediction. Target Japanese financial institutions adopting offshore-processed social analytics under METI data trust frameworks as the most penetrable geography. Lead with managed services wrapping to bypass enterprise IT procurement friction. For Investors and Strategic Acquirers: Long-term, this sits as a data-asset consolidation play because proprietary pipeline control determines sustainable competitive positioning as algorithmic performance commoditizes. Prioritize acquisition targets with exclusive API relationships to Twitter/X, Reddit, or regional social platforms. Watch SEBI enforcement actions in Mumbai as the signal for regulatory tightening that would accelerate compliance-oriented vendor replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Data Pipeline Acquisition | Exclusive Twitter/X and Reddit API access locks in real-time alert delivery dominance against generalist competitors. |
| EU AI Act Compliance Certification | Algorithmic impact assessment capabilities open procurement at Frankfurt banks demanding explainable AI audit trails. |
| Multimodal Transformer Development | Video and image processing expansion captures TikTok and Instagram analytics budgets from retail marketing departments. |
| Managed Services Capability Buildout | Outsourced platform operation relieves mid-market buyer talent constraints and deepens recurring revenue predictability. |
| Hybrid Cloud Architecture Investment | Split on-premises and cloud deployment addresses HIPAA-bound healthcare providers and classified government agencies. |
Study Parameters
A spread of perspectives from social intelligence platform CTOs, enterprise marketing procurement officers, financial services risk analytics directors, and hyperscale cloud marketplace integration specialists converged on the working assumptions. Primary interviews combined with secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory impact assessments, and social media API pricing documentation. Bottom-up deployment estimates triangulated against top-down addressable market calculations across cloud-based, hybrid, on-premises, and edge computing infrastructure segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling deployment architecture, end-user vertical, service type, and application use case dimensions. CAGRs derived from segment-level growth rate convergence informed value expansion trajectories. Industry-specific forecast inputs incorporated API cost volatility scenarios, EU AI Act compliance timeline assumptions, and visual content analytics adoption curves among US retailers.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories affecting enterprise software procurement cycles or escalation in cross-border data transfer restrictions would shift the trajectory. Forecasts reflect documented assumptions about foundation model performance advancement and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Social Business Intelligence Market
Analytics
Global Customer Experience Analytics Market
Analytics
Global Streaming Analytics Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Global Network Analytics Market
Analytics
Network Traffic Analytics Market
Analytics
Multichannel Analytics Market
Analytics
Self Service Analytics Market
Analytics
Capacity Management Analytics Market
Analytics
Embedded Business Intelligence Market
Analytics
Asia-Pacific Edge Analytics Market
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
Text Analytics Market
Analytics
Big Data Analytics in BFSI Market
Analytics
Manufacturing Predictive Analytics Market
Analytics
Drone Analytics Software Market