
 US Video Analytics Market | 2026-2036
US Video Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
US Video Analytics Market Insights
The capability gap between cloud-native platforms and legacy on-premise vendors is bifurcating competitive dynamics across the US Video Analytics Market. Cisco Systems leverages its networking infrastructure to anchor edge-to-cloud video pipelines for enterprise clients. Honeywell International sustains manufacturing scale advantages in hardened hardware for critical infrastructure sites. Motorola Solutions dominates public safety verticals through deep integration with dispatch and radio systems.
Video analytics encompasses algorithmic processing of video streams to extract actionable metadata, encompassing object detection, behavioral classification, and anomaly flagging through frame-by-frame computational analysis. Deep Learning technology leads commercial deployments by enabling facial recognition accuracy above human baselines in unconstrained environments, while Edge Computing architectures address latency constraints for autonomous response systems. Retail Surveillance applications occupy mature margin pools through shrinkage reduction, whereas Smart Buildings represents the fastest structural expansion as facility operators integrate occupancy analytics with HVAC and access control networks.
FAA regulations govern drone-mounted video analytics for aerial surveillance, while NIST frameworks shape algorithmic bias testing for federal procurement eligibility. The SEC's oversight of AI disclosures indirectly pressures publicly traded adopters to document video analytics governance. Stakeholders must monitor evolving state-level biometric privacy statutes that fragment compliance requirements across California, Illinois, and Texas jurisdictions.
Market Dynamics
The convergence of edge AI inference with 5G network slicing is compressing deployment timelines for real-time video analytics, forcing infrastructure decisions before software stacks mature.
Growth Catalysts
- National Defense Authorization Act:Federal procurement mandates for AI-enabled surveillance systems are standardizing interoperability requirements across defense and civilian agencies.
- Smart Buildings:Facility operators in Texas and California are integrating occupancy analytics with HVAC networks, creating bundled service contracts that expand addressable spend per installation.
- Deep Learning:Facial recognition accuracy gains in unconstrained environments are unlocking new deployment scenarios for municipal police departments and transit authorities.
Market Restraints
- GPU Supply Concentration:Edge AI hardware depends on concentrated semiconductor fabrication, creating procurement risk for domestic system integrators.
- Illinois Biometric Privacy Act:Private-sector facial recognition deployments face statutory damages exposure that chills commercial adoption outside regulated critical infrastructure.
- Legacy VMS Integration:On-premise video management systems require costly middleware layers to ingest AI metadata, extending payback periods for retrofit projects.
Strategic Opportunities
- Drone-mounted Analytics:FAA Part 107 waivers for beyond-visual-line-of-sight operations are expanding aerial surveillance use cases for border security and disaster response.
- Behavioral Classification:Retail loss prevention teams are adopting anomaly detection for organized retail crime, representing a greenfield application with measurable ROI.
- NIST AI Risk Management Framework:Federal eligibility requirements for algorithmic bias testing are creating certification services demand that favors early-compliant vendors.
Industry Challenges
- Computer Vision Talent Scarcity:Model optimization for resource-constrained edge devices requires specialized firmware engineering skills that outpace domestic training pipelines.
- Multi-vendor Interoperability:ONVIF Profile compliance gaps between camera OEMs and analytics platforms force custom integration work that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Video Analytics Market |
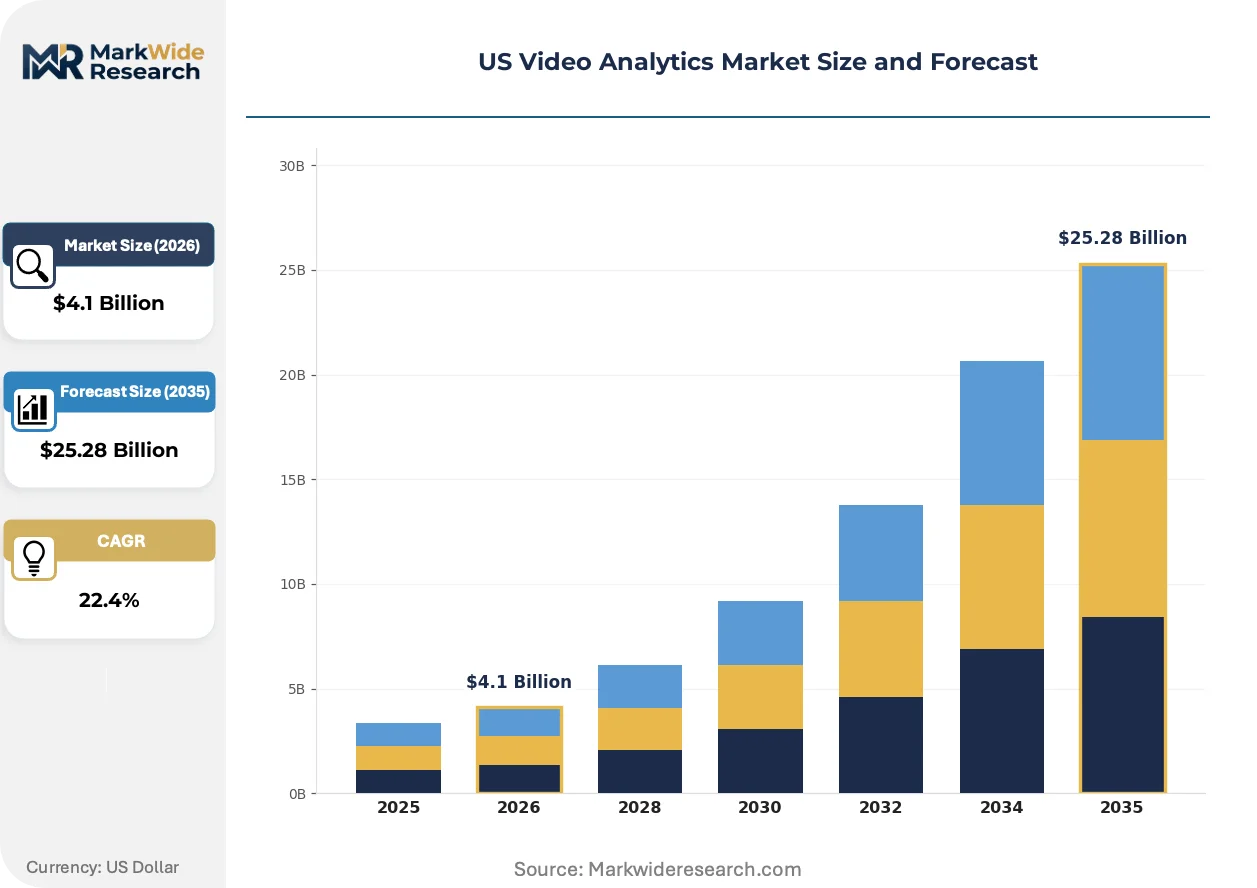
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $25.28 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Retail Surveillance, Traffic Monitoring, Smart Buildings, Crowd Management Technology: Deep Learning, Edge Computing, Cloud Computing, Video Content Analysis End User: Government, Transportation, Hospitality, Education Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Cisco Systems, Inc., Honeywell International Inc., Motorola Solutions, Inc., Avigilon Corporation, IBM Corporation, Axis Communications AB, Genetec Inc., Verint Systems, Inc., Qualcomm Technologies, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Video Analytics Market Trends and Innovations
Algorithmic processing is migrating from centralized data centers toward distributed edge nodes, altering how vendors architect software-hardware bundles and how buyers evaluate total cost of ownership.
Neural network accelerators are miniaturizing to fit within thermal envelopes of existing camera housings, eliminating separate edge appliance procurement. Critical infrastructure operators in Texas border zones are deploying these system-on-chip modules for autonomous threat response without cloud dependency. The technology is miniaturizing hardware footprints while compressing installation timelines from weeks to days.
NIST frameworks for algorithmic bias testing are reshaping federal procurement eligibility, requiring documentation of training data provenance and demographic performance metrics. Defense contractors and municipal agencies must now submit AI governance attestations before contract award. California police departments are responding by establishing internal algorithmic auditing functions that slow procurement but reduce litigation exposure.
Facility operators are unbundling video analytics from integrated security contracts, preferring software-as-a-service subscriptions with usage-based pricing. This displaces capital-intensive on-premise deployments in commercial real estate portfolios. The shift is most visible in California smart city corridors where municipal budgets favor operational expenditure treatment for technology investments.
US Video Analytics Market Segmentation
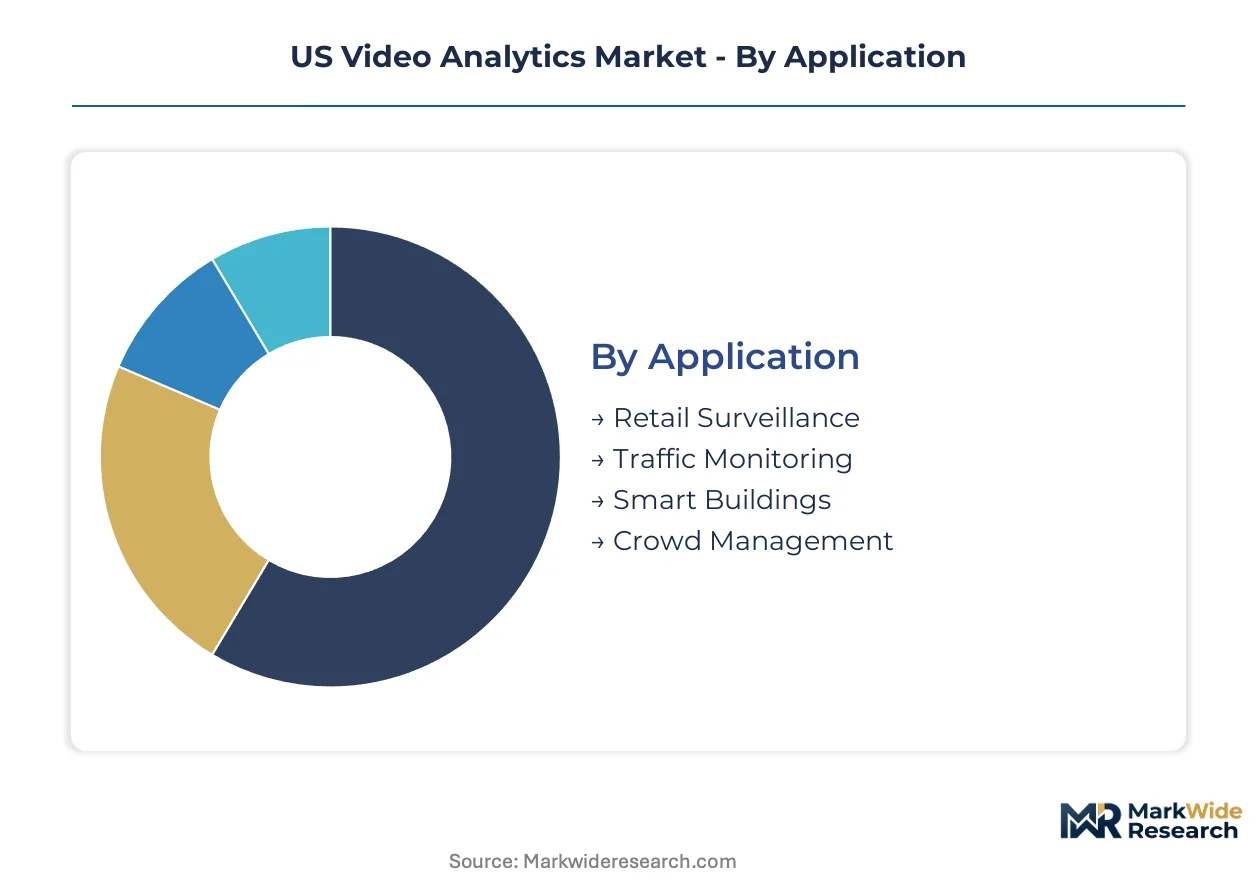
Video analytics vendors structure product portfolios around distinct deployment architectures and buyer risk profiles. Segment boundaries determine channel strategy, pricing models, and integration complexity for system integrators serving federal, municipal, and commercial accounts.
Application:
Channel mix varies sharply by use case maturity—retail flows through security integrators with recurring service contracts, while smart buildings increasingly route through facility management platforms.
- Retail Surveillance:Shrinkage reduction algorithms process point-of-sale video streams to flag suspicious behaviors before merchandise exits stores. California's organized retail crime task forces are expanding deployments through loss prevention vendor partnerships.
- Smart Buildings:Occupancy analytics integrate with HVAC and access control networks, enabling automated energy adjustments based on real-time space utilization. Texas commercial real estate operators are bundling these capabilities into tenant experience platforms.
- Traffic Monitoring:License plate recognition and incident detection systems serve state DOT maintenance contracts.
- Crowd Management:Density estimation and flow analysis tools secure transit hubs and entertainment venues.
Retail Surveillance dominates installed base. Smart Buildings is where expansion concentrates.
Technology:
Cost tier stratification separates premium neural network deployments from commoditized rule-based analysis, with edge inference commanding hardware premiums over cloud subscriptions.
- Deep Learning:Convolutional neural networks enable facial recognition accuracy exceeding human baselines in unconstrained lighting and angles. Municipal police departments in Illinois and Texas are prioritizing these capabilities despite biometric privacy litigation exposure.
- Edge Computing:On-camera inference eliminates cloud latency for autonomous response systems. Border security zones in Texas deploy thermal-constrained system-on-chip modules for standalone threat classification.
- Cloud Computing:Centralized model training and elastic storage serve multi-site commercial portfolios with limited IT staff.
- Video Content Analysis:Rules-based motion detection and object tracking persist in price-sensitive retrofit installations.
Deep Learning captures premium pricing tiers. Edge Computing is climbing the fastest as autonomy requirements harden.
End User:
Procurement authority patterns diverge—government buyers mandate NIST-compliant bias documentation while hospitality and education sectors prioritize rapid deployment over certification depth.
- Government:Federal agencies and municipal departments require algorithmic governance attestations under National Defense Authorization Act procurement standards. California police departments have established internal auditing functions to satisfy eligibility requirements.
- Transportation:Transit authorities and port operators integrate video analytics with dispatch systems for incident response coordination.
- Hospitality:Casino and resort operators deploy guest flow optimization and security screening through managed service contracts.
- Education:K-12 and university campuses adopt perimeter intrusion detection with limited integration to existing access control infrastructure.
Government accounts anchor long-term contract values. Transportation is gaining share fastest as infrastructure modernization accelerates.
Deployment:
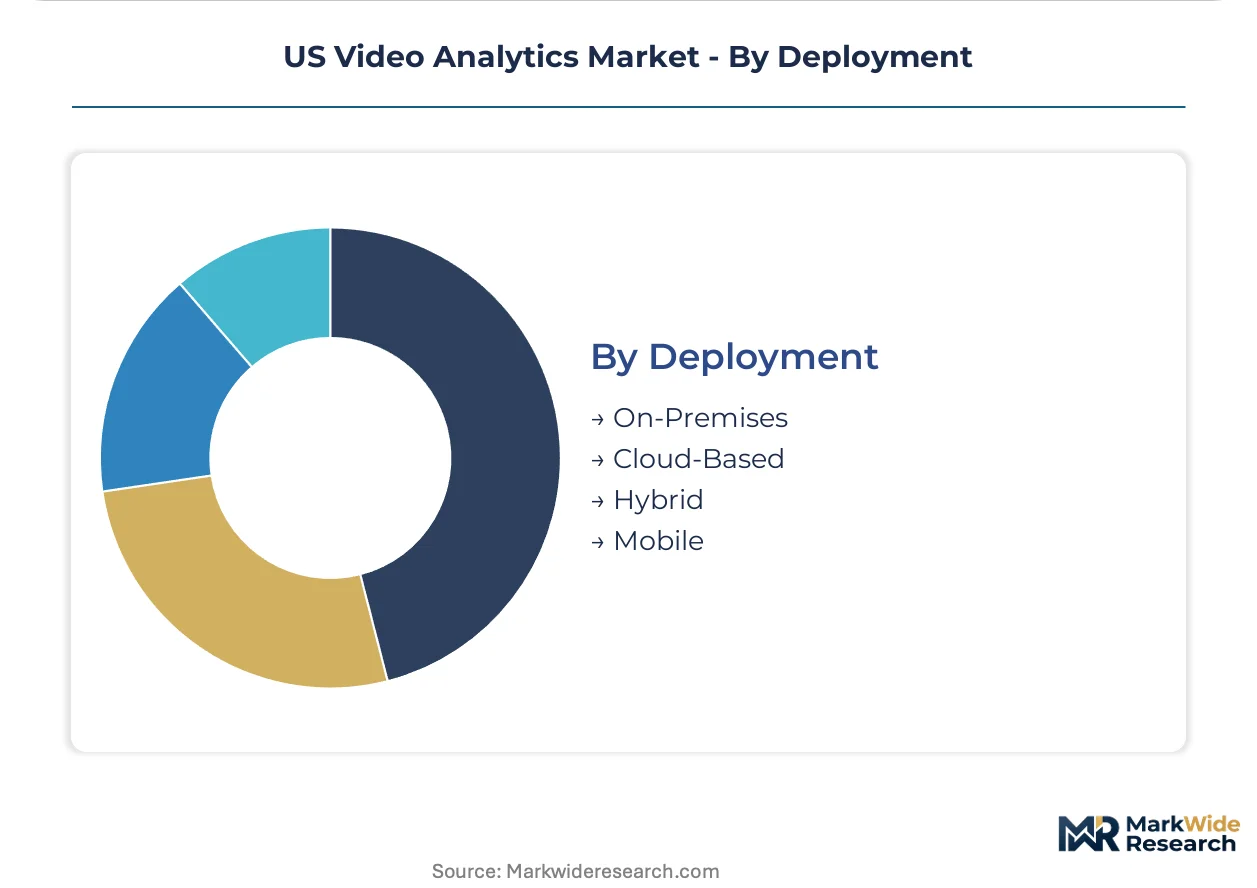
Volume concentration sits with hybrid architectures that preserve on-premise storage while leveraging cloud analytics, though pure cloud subscriptions are displacing capital-intensive models in commercial real estate.
- On-Premises:Air-gapped installations serve critical infrastructure sites with zero-trust security requirements. Legacy VMS integration costs extend payback periods for federal retrofit projects.
- Cloud-Based:SaaS consumption models with usage-based pricing appeal to California municipal budgets favoring operational expenditure treatment. Multi-tenant platforms reduce per-camera software licensing overhead.
- Hybrid:Local buffering with cloud analytics balances latency sensitivity against centralized model management.
- Mobile:Drone-mounted and vehicle-based deployments require FAA Part 107 waivers for beyond-visual-line-of-sight operations.
Hybrid configurations hold the largest installed footprint. Cloud-Based is expanding most quickly as facility operators unbundle analytics from integrated security contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's smart city corridors command pricing premiums over Texas border security zones due to bundled facility management contracts, while Illinois biometric litigation exposure suppresses commercial adoption rates relative to other states.
California
Smart building operators in Los Angeles and San Francisco integrate occupancy analytics with HVAC networks, driving bundled service contract values. Municipal budgets favor operational expenditure treatment under state procurement guidelines. Silicon Valley technology clusters accelerate edge AI inference deployments for autonomous response systems.
Texas
Border security zones deploy thermal-constrained system-on-chip modules for standalone threat classification without cloud dependency. FAA Part 107 waivers expand beyond-visual-line-of-sight drone operations for aerial surveillance. Dallas-Fort Worth commercial real estate operators bundle video analytics into tenant experience platforms.
Illinois
Biometric Privacy Act statutory damages exposure chills private-sector facial recognition adoption outside regulated critical infrastructure. Chicago municipal police departments prioritize deep learning capabilities despite litigation risk. Internal algorithmic auditing functions slow procurement timelines but reduce legal exposure for law enforcement agencies.
New York Metro
Transit authorities integrate video analytics with dispatch systems for incident response coordination across multi-modal hubs. Port operators deploy license plate recognition for cargo security screening. SEC oversight of AI disclosures pressures publicly traded adopters to document video analytics governance frameworks.
Pacific Northwest
Seattle-area cloud infrastructure providers serve multi-site commercial portfolios with elastic storage and centralized model training. Oregon data centers support hybrid deployment architectures balancing latency sensitivity against centralized management. Regional technology clusters concentrate computer vision engineering talent for edge device optimization.
US Video Analytics Market Competitive Landscape
Concentration sits with diversified technology conglomerates anchoring enterprise and public safety verticals through integrated hardware-software bundles. The vendor base separates into three strategic archetypes: networking infrastructure providers leveraging edge-to-cloud pipelines, manufacturing specialists delivering hardened hardware for critical infrastructure, and public safety integrators with deep dispatch system connectivity. Dominant competitive moves include strategic partnerships with facility management platforms and portfolio diversification into SaaS consumption models.
Among diversified technology conglomerates, Cisco Systems, Inc., Honeywell International Inc., and Motorola Solutions, Inc. occupy distinct positioning archetypes within the US Video Analytics Market. Cisco represents networking-centric platform plays, Honeywell exemplifies manufacturing scale advantages in hardened deployments, and Motorola anchors public safety vertical integration. These three entities collectively illustrate how infrastructure heritage, manufacturing depth, and vertical specialization determine competitive positioning across federal, municipal, and commercial account segments.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Honeywell International Inc. |
| Motorola Solutions, Inc. |
| Avigilon Corporation |
| IBM Corporation |
| Axis Communications AB |
| Genetec Inc. |
| Verint Systems, Inc. |
| Qualcomm Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for GPU-accelerated edge devices concentrate procurement power with semiconductor distributors, compressing margins for system integrators while elevating pricing premiums for air-gapped federal deployments. This inventory tightness feeds directly into how vendors structure software-hardware bundles across California smart city corridors and Texas border security zones.
Pricing Analysis
Configured-to-order pricing for NIST-compliant deep learning systems commands spreads exceeding standard edge analytics by certification depth and thermal envelope customization. The dominant pricing structure stratifies across SaaS subscriptions for commercial real estate, perpetual licensing for critical infrastructure, and project-based federal contracts bundling hardware with algorithmic governance documentation. Price differentiation hinges on NIST AI Risk Management Framework attestation tier and edge inference latency specification. Cost compression in cloud-native tiers is intensifying because facility operators are unbundling analytics from integrated security contracts. Municipal police departments exhibit lowest price sensitivity due to NDAA procurement mandates, while K-12 education buyers face capital budget constraints that favor economy-tier rule-based analysis.
Supply Chain Analysis
Inventory tightness for neural network accelerators extends fulfillment timelines for thermal-constrained system-on-chip modules deployed in Texas border zones. Manufacturing concentrates in Taiwan for GPU fabrication, South Korea for memory components, and domestic US facilities for hardened hardware assemblies. Raw material dependencies span silicon wafers, rare earth elements for thermal management, and specialized polymers for camera housing ingress protection. Single-source vulnerability sits with concentrated semiconductor fabrication for edge AI inference chips. Distribution runs through defense contractors for federal accounts, security integrators for municipal deployments, and facility management platforms for commercial real estate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Video Analytics Market represents high-growth disruption as edge AI inference compresses deployment timelines faster than software stack maturation, with FAA Part 107 waivers and NDAA procurement mandates creating simultaneous regulatory tailwinds.
For Market Incumbents: Shield federal contract values by accelerating NIST AI Risk Management Framework certification completion before eligibility windows narrow, while consolidating channel control over security integrators serving California smart city corridors. GPU supply concentration threatens margin stability; backward integration into edge hardware design or captive supply agreements with Taiwanese foundries reduces procurement risk. Priority R&D investment belongs to on-camera neural network accelerators that eliminate separate edge appliance procurement. For New Entrants and Emerging Players: SaaS consumption gaps in commercial real estate facility management platforms offer white-space entry where incumbents anchor on-premise legacy architectures. Illinois biometric privacy litigation exposure has chilled private-sector facial recognition adoption, creating penetrable demand for behavioral classification algorithms that avoid biometric capture. Target hospitality and education segments with rapid-deployment perimeter analytics requiring minimal VMS integration. Go-to-market leverage rests with usage-based pricing models that displace capital-intensive procurement. For Investors and Strategic Acquirers: Long-term, this sits as a vertical software platform play because video analytics is unbundling from integrated security contracts toward standalone SaaS architectures with recurring revenue profiles. Acquisition targets should display edge AI firmware optimization capabilities and existing NIST compliance documentation. The signal to watch is FAA regulatory expansion for beyond-visual-line-of-sight drone operations, which would inflect aerial surveillance addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| NIST AI Risk Management Framework Certification | Federal procurement eligibility under NDAA standards mandates algorithmic bias documentation for defense contractors. |
| Edge Hardware Miniaturization | System-on-chip neural accelerators fit within existing camera thermal envelopes, compressing installation timelines. |
| SaaS Pricing Transition | Usage-based subscriptions displace capital-intensive on-premise deployments in California municipal budgets. |
| Drone-mounted Analytics Expansion | FAA Part 107 waivers unlock beyond-visual-line-of-sight aerial surveillance for border security applications. |
| Facility Management Platform Integration | Occupancy analytics bundling with HVAC networks drives bundled service contract values in Texas commercial real estate. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with municipal police procurement officers, federal defense contractors, commercial real estate facility managers, security integrators, and edge AI firmware engineers. Secondary validation drew from FAA regulatory filings, NDAA procurement documentation, NIST AI Risk Management Framework publications, SEC AI disclosure filings, and state-level biometric privacy statute databases. Bottom-up camera deployment estimates triangulated against top-down federal budget appropriations for AI-enabled surveillance systems.
Across the analysis window, volume and value outputs reflect segmented modeling across deployment architecture, technology tier, application vertical, and end-user procurement authority. Analytical frameworks incorporated edge inference latency requirements, NIST compliance depth, and SaaS subscription penetration rates as industry-specific forecast inputs. CAGRs were derived from installation base expansion trajectories and average revenue per camera trends.
Underlying assumptions cover sustained NDAA procurement mandate enforcement, continued GPU supply concentration, and FAA regulatory expansion for drone operations, with deviation risk concentrated in Illinois biometric privacy litigation spillover and state-level algorithmic auditing requirement fragmentation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Prescriptive Analytics Market
Analytics
Global User and Entity Behavior Analytics Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
United States Geospatial Analytics Market
Analytics
Legal Analytics Market
Analytics
Tourism Industry Big Data Analytics Market
Analytics
Brazil Big Data Analytics Market
Analytics
Load (ETL) Market
Analytics
Global Streaming Analytics Market
Analytics
App Analytics Market
Analytics
Construction Data Analytics Software Market
Analytics
Israel Geospatial Analytics Market
Analytics
Mobile Apps and Web Analytics Market
Analytics
Crowd Analytics Market
Analytics
Japan Geospatial Analytics Market
Analytics
IoT Analytics Market