
 Big Data Analytics in Semiconductor and Electronics Market | 2026-2036
Big Data Analytics in Semiconductor and Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data Analytics in Semiconductor and Electronics Market Outlook
Multi-source analytics procurement is expanding across semiconductor fabs as yield complexity outstrips single-vendor capabilities. Microsoft Corporation leverages its Azure cloud backbone to capture foundry workloads requiring elastic compute for wafer inspection pipelines. IBM Corporation anchors high-performance data warehousing contracts with IDMs prioritizing on-premise sovereignty. Intel Corporation competes through in-house analytics silicon that reduces inference latency for real-time defect detection.
Big Data Analytics in Semiconductor and Electronics encompasses distributed processing architectures that ingest terabyte-scale sensor streams from lithography, etching, and deposition equipment to extract actionable manufacturing intelligence. These systems employ edge-to-cloud pipelines with sub-millisecond latency thresholds to flag process excursions before yield collapse. Predictive Maintenance and Yield Management command the deepest margin pools because downtime costs at advanced nodes exceed millions per hour. Cloud Analytics represents the fastest-expanding technology segment as fabs migrate off capital-intensive on-premise clusters toward operational-expenditure models.
The EU AI Act imposes algorithmic transparency mandates on automated quality systems exported to Europe, while REACH restricts hazardous substance reporting that analytics platforms must track across multi-tier supply chains. The EPA enforces emissions disclosure rules affecting semiconductor manufacturing data collection in the United States. Stakeholders must weigh regulatory compliance costs against analytics-driven yield gains when selecting deployment architectures for new fabrication facilities.
Market Dynamics
Foundry operators face mounting pressure to compress defect detection cycles as advanced node geometries shrink below 3nm, where single-particle contamination destroys entire wafer batches worth millions in sunk lithography costs.
Growth Catalysts
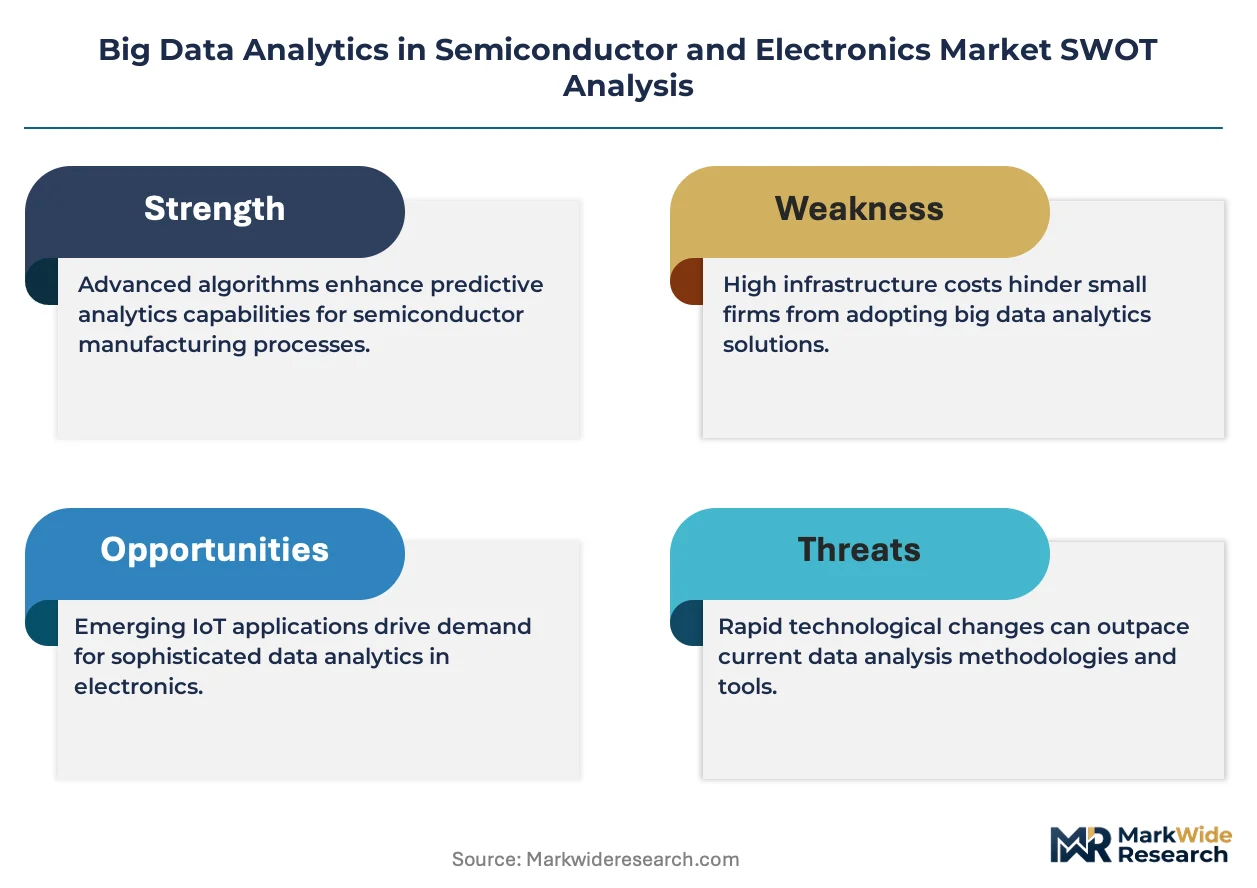
- EU AI Act transparency mandates:Automated quality systems exported to Europe now require algorithmic audit trails, forcing semiconductor firms to upgrade analytics architectures with embedded governance layers.
- Advanced packaging proliferation:Chiplet-based designs generate exponentially more metrology data points per die, expanding the addressable base for distributed processing platforms.
- Hsinchu Science Park cluster effects:TSMC and MediaTek anchor concentrated demand for real-time yield optimization, creating procurement templates that diffuse to secondary foundries.
Market Restraints
- Silicon photonics input volatility:Co-packaged optics substrates face supply bottlenecks from limited germanium and indium phosphide refining capacity.
- Cloud egress cost structures:Terabyte-scale sensor streams from etching and deposition equipment incur prohibitive bandwidth charges under standard hyperscaler pricing tiers.
- REACH substance tracking complexity:Multi-tier supply chain reporting for hazardous materials requires retrofitted data lineage systems that extend implementation timelines.
Strategic Opportunities
- India PLI scheme incentives:Domestic semiconductor fabrication subsidies create greenfield demand for analytics infrastructure without legacy on-premise baggage.
- Edge-to-cloud convergence:Hybrid architectures combining NVIDIA DGX-class edge nodes with elastic cloud bursting address latency-sensitive defect detection use cases.
- Carbon accounting mandates:CSRD disclosure requirements position emissions-tracking analytics modules as compliance-enabling add-ons to core yield platforms.
Industry Challenges
- Semiconductor data science talent scarcity:The intersection of device physics, statistical process control, and distributed systems engineering commands premium compensation that strains mid-tier vendor hiring.
- Fab equipment protocol fragmentation:Proprietary SECS-GEM implementations across lithography tool vendors from ASML, Nikon, and Canon require costly middleware normalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data Analytics in Semiconductor and Electronics Market |
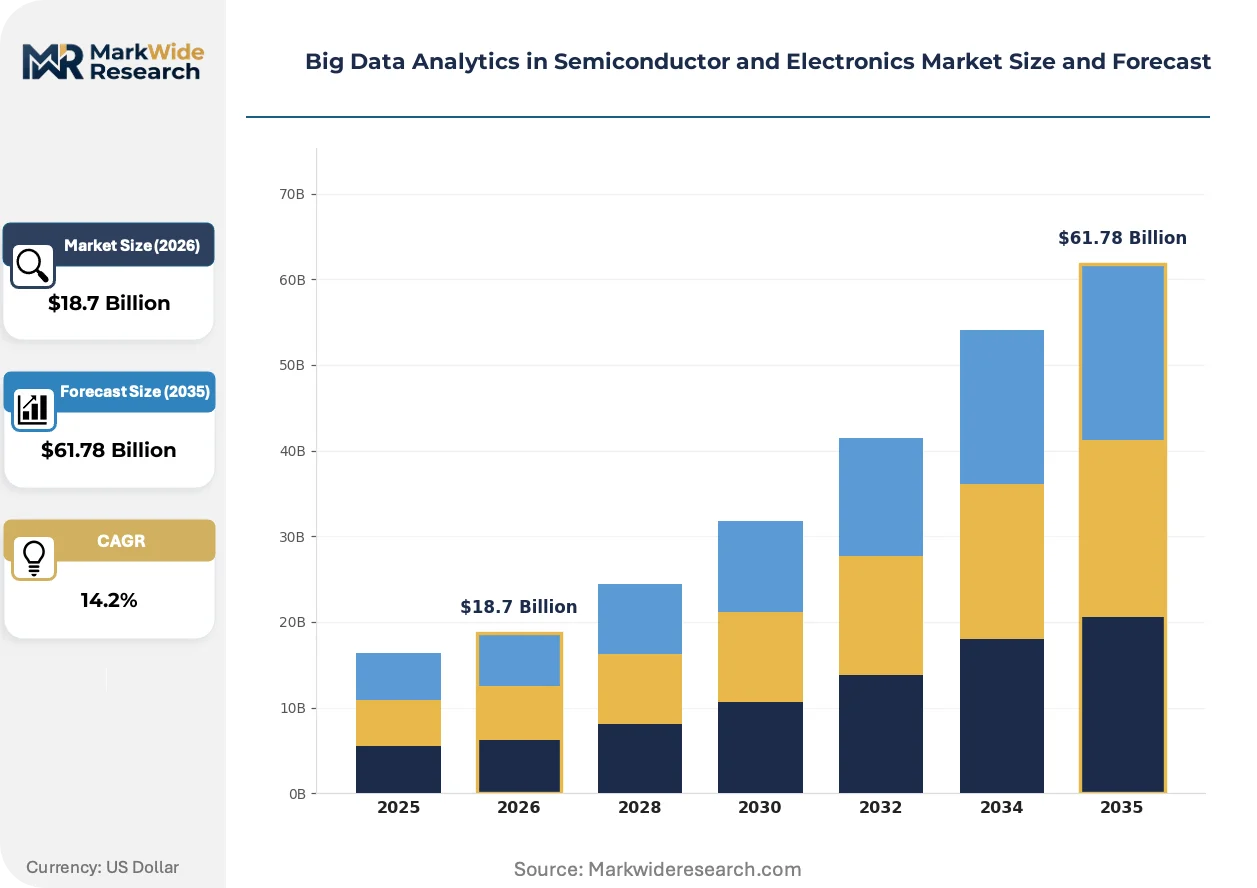
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Predictive Maintenance, Quality Control, Supply Chain Optimization, Yield Management Technology: Machine Learning, Data Warehousing, Data Mining, Cloud Analytics End User: Consumer Electronics, Telecommunications, Automotive, Aerospace Solution: Data Visualization, Real-Time Processing, Reporting Tools, Performance Metrics |
| Companies Covered | Amazon Web Services, IBM Corporation, Microsoft Corporation, Cisco Systems, Inc., Dell EMC, SAP SE, SAS Institute Inc., Splunk Inc., Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data Analytics in Semiconductor and Electronics Market Strategic Shifts
Analytics architectures are pivoting from retrospective yield analysis toward predictive intervention, compressing the gap between process excursion detection and automated tool correction from minutes to milliseconds.
Digital twin implementations are integrating physics-based simulation with live sensor feeds to model etch depth uniformity across wafer lots before physical metrology completion. Memory manufacturers in South Korea deploy these twins at 176-layer NAND nodes to anticipate stringer defects. The technology is integrating control-loop automation that bypasses human engineer review for classified excursion signatures.
EPA emissions disclosure rules now mandate granular energy consumption reporting from semiconductor manufacturing facilities, extending data collection requirements to sub-fab auxiliary systems previously exempt from environmental monitoring. IDMs with US fabrication presence reconfigure building management system integrations to capture chilled water and compressed air metrics. Backend packaging houses in Malaysia and Vietnam face downstream pressure to align reporting formats with EPA templates to maintain contract eligibility.
Consumption patterns among analog and power semiconductor buyers are compressing analytics procurement cycles from multi-year enterprise agreements toward modular subscriptions tied to individual tape-out programs. Fabless design houses now purchase defect classification algorithms by the wafer-start rather than licensing perpetual seats. This unbundling is most pronounced among automotive MCU suppliers qualifying parts under AEC-Q100 standards, where program-specific analytics spend aligns with customer audit requirements.
Big Data Analytics in Semiconductor and Electronics Market Segmentation
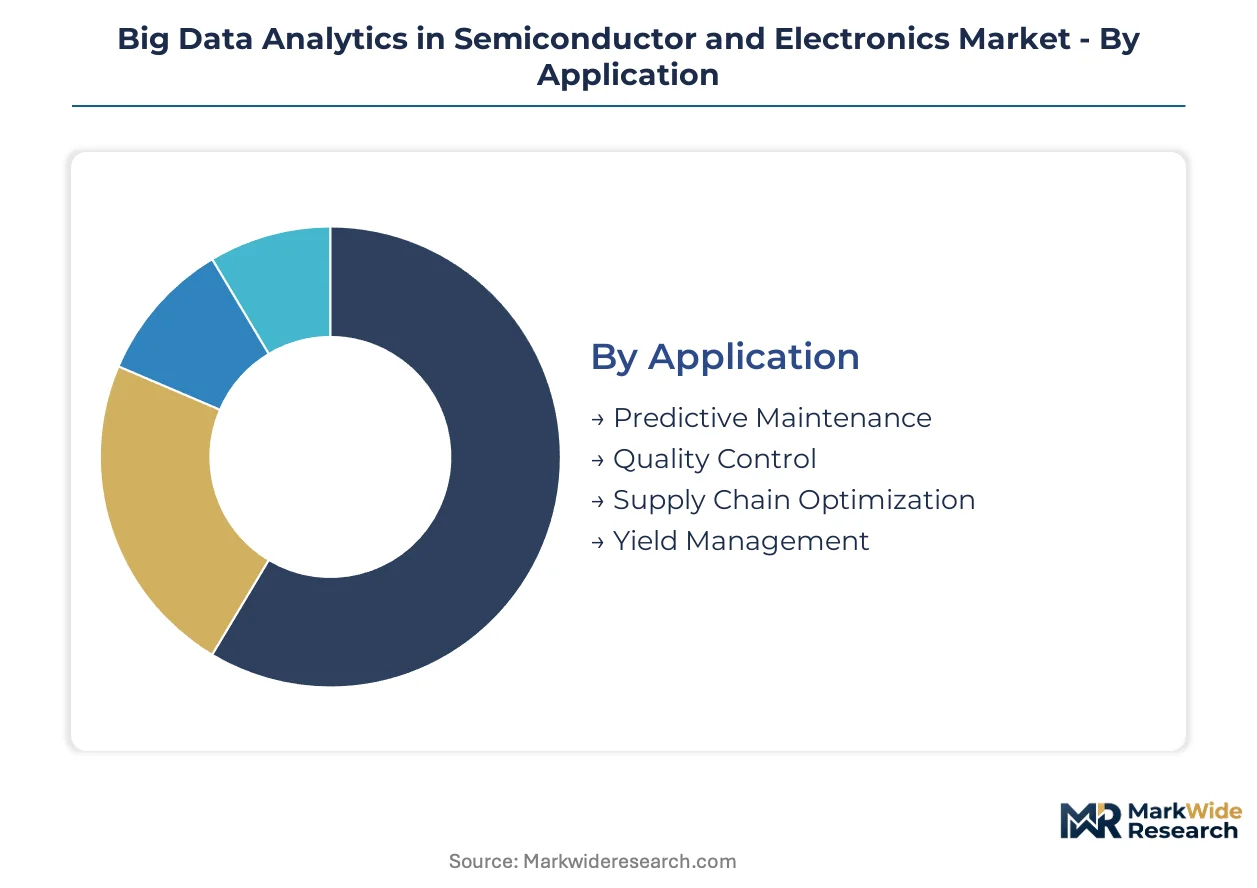
Semiconductor fabs deploy analytics modules at varying depths of manufacturing integration, from standalone quality dashboards to embedded real-time control loops. Segmentation reveals which solution architectures command premium pricing versus commodity procurement. Procurement patterns diverge sharply between IDMs running captive analytics stacks and foundries outsourcing to multi-tenant cloud platforms.
Application:
Integration depth separates applications that operate as bolt-on visibility layers from those embedded directly into tool control systems.
- Yield Management:Embedded algorithms intercept lithography and etching tool parameters before wafer damage occurs. TSMC's Hsinchu fabs deploy these systems at 3nm nodes where single-particle defects destroy million-dollar wafer batches.
- Predictive Maintenance:Vibration and thermal sensor streams from deposition equipment feed neural networks forecasting pump failures 48-72 hours before catastrophic downtime. Samsung's Pyeongtaek memory complex anchors regional demand for these capabilities.
- Quality Control:Automated optical inspection data pipelines classify defect signatures against historical libraries.
- Supply Chain Optimization:Multi-tier visibility platforms track wafer lots through backend assembly and test houses.
Yield Management leads volumes today; Predictive Maintenance is gaining share fastest.
Technology:
Cost tier structures separate capital-intensive on-premise deployments from operational-expenditure cloud models favored by newer entrants.
- Cloud Analytics:Elastic compute pools absorb terabyte-scale sensor bursts during process excursions without permanent infrastructure. India's PLI-funded greenfield fabs adopt these architectures to avoid legacy data center investments.
- Machine Learning:Supervised and unsupervised models classify defect patterns across heterogeneous equipment vintages. NVIDIA DGX-class edge nodes handle inference workloads requiring sub-10 millisecond latency for real-time tool intervention.
- Data Warehousing:Centralized repositories consolidate decades of process history for longitudinal yield analysis.
- Data Mining:Pattern extraction algorithms identify subtle correlations between ambient fab conditions and device parametric drift.
Data Warehousing dominates installed base; Cloud Analytics is expanding most quickly.
End User:
Application maturity varies by end-use sector, with automotive qualification standards imposing the most stringent data lineage requirements.
- Automotive:AEC-Q100 and ISO 26262 mandates require complete process parameter traceability from wafer start to final test. Infineon's Dresden fab maintains 15-year data retention for liability defense.
- Consumer Electronics:High-volume smartphone SoC production prioritizes throughput optimization over individual lot traceability. Apple's foundry partners concentrate analytics spend on die-per-wafer maximization at advanced nodes.
- Telecommunications:Baseband processor reliability requirements drive predictive maintenance investments for 5G infrastructure silicon.
- Aerospace:Radiation-hardened device qualification demands extended environmental test data archival.
Consumer Electronics anchors procurement volumes; Automotive commands the steepest expansion trajectory.
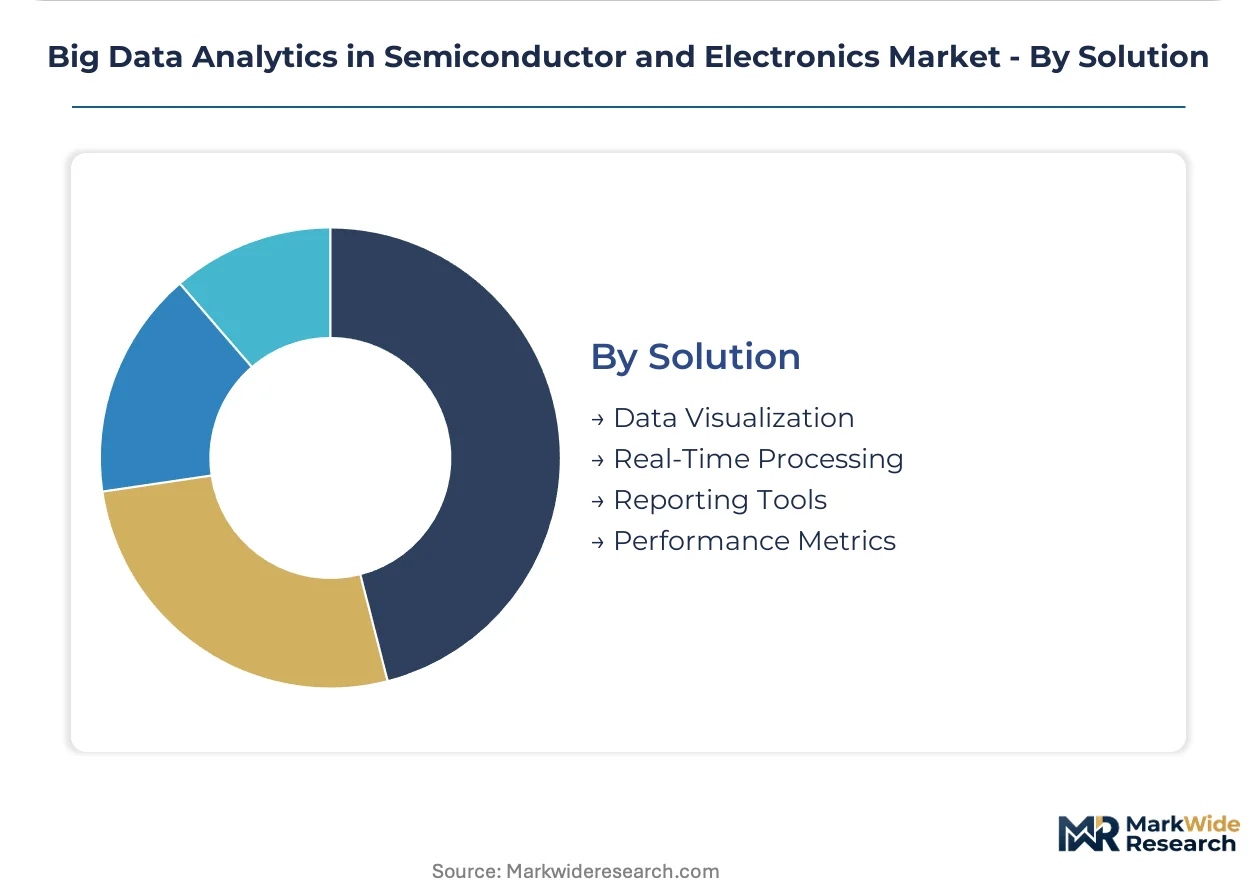
Solution:
Customer type segmentation separates packaged software licenses from modular subscriptions tied to specific tape-out programs.
- Real-Time Processing:Stream processing architectures ingest SECS-GEM equipment messages with sub-second latency for automated excursion response. ASML's lithography tools in Taiwan's Hsinchu cluster feed these pipelines directly.
- Data Visualization:Interactive dashboards translate complex multivariate process data into engineer-actionable formats. Qualcomm's fabless design teams rely on these tools for remote fab monitoring without on-site presence.
- Reporting Tools:Automated compliance documentation generators satisfy EPA emissions disclosure and EU AI Act algorithmic transparency mandates.
- Performance Metrics:Standardized KPI frameworks benchmark fab efficiency against industry peer groups.
Data Visualization leads current deployments; Real-Time Processing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the densest concentration of semiconductor analytics procurement worldwide, with foundry operators deploying predictive systems across 3nm-class fabrication lines. The analysis spans five countries where advanced node manufacturing and regulatory complexity drive differentiated analytics architectures.
Taiwan
TSMC and MediaTek command the deepest investments in real-time yield optimization systems for sub-3nm production. The National Science and Technology Council funds domestic analytics infrastructure through the Chip Implementation Center initiative. Hsinchu Science Park fabs operate edge-to-cloud pipelines processing terabyte-scale sensor streams from ASML lithography equipment.
United States
Intel's captive foundry operations and Qualcomm's fabless design teams generate concentrated demand for hybrid cloud analytics. EPA emissions disclosure rules mandate granular energy consumption reporting from fabrication facilities. Arizona's emerging semiconductor corridor attracts greenfield analytics deployments for facilities under construction.
South Korea
Samsung Electronics and SK Hynix anchor regional demand for predictive maintenance systems at memory fabrication complexes. The Ministry of Trade, Industry and Energy subsidizes AI-enabled manufacturing platforms through the Manufacturing Innovation Strategy. Pyeongtaek's semiconductor cluster deploys digital twin architectures for 176-layer NAND defect anticipation.
China
SMIC and domestic equipment vendors drive localization requirements for supply chain analytics platforms. MIIT standards mandate data sovereignty architectures for semiconductor manufacturing intelligence. The Yangtze River Delta concentration of memory and logic fabs generates procurement for indigenous analytics middleware.
Germany
Infineon and Bosch anchor automotive semiconductor analytics investments tied to AEC-Q100 qualification requirements. The EU AI Act imposes algorithmic transparency mandates on automated quality systems exported from German facilities. Dresden's Silicon Saxony cluster maintains 15-year data retention architectures for liability defense in automotive MCU production.
Big Data Analytics in Semiconductor and Electronics Market Competitive Environment
Global majors compete with regional champions across cloud infrastructure and specialized analytics software layers, producing a tiered structure where hyperscalers capture elastic compute workloads while niche vendors retain on-premise sovereignty contracts. Three archetypes dominate: hyperscale cloud providers with semiconductor-specific service tiers, legacy enterprise software vendors with deep data warehousing relationships, and silicon manufacturers offering in-house analytics acceleration. Competitive moves concentrate on strategic partnerships between equipment vendors and cloud platforms, plus vertical integration of inference silicon into real-time control systems.
Within the hyperscale tier, Amazon Web Services and Microsoft Corporation exemplify cloud-native architectures capturing foundry workloads requiring elastic compute bursts. IBM Corporation occupies a position among legacy enterprise vendors anchoring high-performance data warehousing contracts with integrated device manufacturers prioritizing on-premise data sovereignty. Intel Corporation represents the silicon-integrated archetype, competing through captive analytics hardware that reduces inference latency for defect detection pipelines.
| Leading Market Players |
|---|
| Amazon Web Services |
| IBM Corporation |
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Dell EMC |
| SAP SE |
| SAS Institute Inc. |
| Splunk Inc. |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
Edge-to-cloud pipeline migration simultaneously compresses capital expenditure burdens and redistributes pricing power toward hyperscale infrastructure providers. Taiwan's Hsinchu Science Park cluster anchors premium analytics procurement as foundries absorb terabyte-scale sensor streams without permanent on-premise data center investments.
Pricing Analysis
Input-cost pass-through from NVIDIA DGX-class edge nodes and elastic cloud compute tiers shapes SaaS subscription models with usage-based scaling. Price differentiation hinges on latency thresholds for real-time defect detection and AEC-Q100 certification grade for automotive traceability modules. Cost compression in mid-tier data warehousing intensifies because IBM and Dell EMC compete for IDM sovereignty contracts. Fabless design houses exhibit highest price sensitivity, while captive foundries at TSMC and Intel tolerate premium tiers for sub-millisecond inference pipelines.
Supply Chain Analysis
Reverse-logistics flows for refurbished NVIDIA inference accelerators and redeployed edge nodes extend hardware lifecycles across secondary foundries. Supply concentrates in Taiwan, South Korea, and the United States for lithography-integrated analytics middleware. Raw material dependencies span germanium substrates for photonics modules, high-bandwidth memory stacks from SK Hynix, and ASML EUV sensor components. Single-source vulnerability around ASML equipment protocols threatens continuity. Distribution runs through direct OEM partnerships with tool vendors rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme subsidies offset the EU AI Act compliance costs burdening European facilities. The cost differential between greenfield cloud-native deployments and retrofitted on-premise governance architectures exceeds two-to-one for equivalent throughput capacity.
For Market Incumbents: Acquire specialized edge inference hardware portfolios to neutralize NVIDIA's DGX dominance in sub-10 millisecond defect detection. Consolidate middleware normalization capabilities for proprietary SECS-GEM implementations across ASML, Nikon, and Canon lithography stacks. Defensive positioning requires backward integration into sensor fusion IP to counter emerging cloud-native entrants. For New Entrants and Emerging Players: Launch via modular per-wafer-start subscriptions targeting automotive MCU suppliers under AEC-Q100 qualification pressure. White-space concentration sits in India's greenfield PLI-funded fabs lacking legacy on-premise baggage. Secondary foundries in Malaysia and Vietnam present penetrable targets for emissions-tracking analytics add-ons. For Investors and Strategic Acquirers: Valuations sit cheapest among regional middleware specialists with SECS-GEM protocol expertise and existing foundry relationships. Long-term viability over the next decade hinges on cloud-edge convergence architectures displacing pure on-premise deployments. Monitor EPA emissions disclosure enforcement intensity and EU AI Act audit trail mandates as regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Convergence | Hybrid NVIDIA DGX edge nodes with elastic cloud bursting address latency-sensitive defect detection use cases. |
| Regulatory Compliance Integration | Embedded governance layers satisfy EU AI Act algorithmic transparency mandates for automated quality systems. |
| Digital Twin Deployment | Physics-based simulation with live sensor feeds anticipates stringer defects at Samsung's 176-layer NAND nodes. |
| Carbon Accounting Module Development | CSRD disclosure requirements position emissions-tracking analytics as compliance-enabling add-ons to yield platforms. |
| Middleware Protocol Normalization | ASML, Nikon, and Canon SECS-GEM integration reduces implementation timelines for multi-vendor fab environments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement encompassed fab operations directors, cloud procurement officers at foundries, SECS-GEM integration engineers, and regulatory compliance leads at IDMs. Secondary validation drew from EPA emissions filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and SEMI equipment connectivity standards. Bottom-up sensor stream volume estimates and top-down foundry analytics spend allocations were triangulated against disclosed infrastructure investments.
Comparable-period anchoring linked the projection horizon to historical wafer-start growth trajectories and capital intensity cycles across memory and logic fabrication. Segmentation modeling spanned application depth, deployment architecture, end-use sector maturity, and regional regulatory cluster. CAGRs were derived from equipment vendor order backlogs and cloud infrastructure expansion announcements. Industry-specific inputs incorporated EUV lithography node transition timelines and AEC-Q100 qualification pipeline volumes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance tracking enforcement or ASML equipment export restriction scenarios. Practitioners should monitor EPA granular energy reporting rulemakings and MIIT data sovereignty mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global People and HR Analytics Software Market
Analytics
Big Data in Automotive Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Global Hadoop Big Data Analytics Market
Analytics
Attribution Software Market
Analytics
Global Cognitive Analytics Market
Analytics
Sales Intelligence Market
Analytics
Active Data Warehousing Market
Analytics
Drone Analytics Software Market
Analytics
Retail Analytics Market
Analytics
Online Analytical Processing Market
Analytics
Germany Geospatial Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
Europe Retail Analytics Market
Analytics
Europe Speech Analytics Market
Analytics
Global Sentiment Analytics Software Market