
 Neon Gas for Laser Market | 2026-2036
Neon Gas for Laser Market Size, Share, and Industry Trends Forecast 2026-2036
Neon Gas for Laser Market Insights
Skilled cryogenic gas technician availability is rotating toward scarcity in traditional supply regions while expanding in Asian manufacturing corridors. Linde plc leverages its integrated air separation network to sustain helium-neon co-production economics across multiple continents. Air Liquide anchors European supply security through its Antwerp pipeline hub and specialized purification assets. Cryoin Engineering Ltd competes by concentrating on Ukrainian-sourced neon recovery and regional distribution flexibility.
Neon gas for laser applications denotes a noble gas with atomic number 10, typically supplied at purities exceeding 99.999% for excimer and helium-neon laser systems where its red emission line at 632.8 nanometers serves as the foundational wavelength. Ultra-High Purity Neon commands premium positioning due to semiconductor lithography requirements where parts-per-billion contamination tolerances determine laser reliability. Laser Cutting applications dominate volume offtake from manufacturing plants, while Medical Lasers generate higher per-unit margins through stringent certification protocols and smaller batch requirements.
FDA oversight of medical laser systems in the United States and CE marking requirements under the EU MDR shape product traceability and purity documentation obligations for gas suppliers. EPA emissions tracking and OSHA workplace exposure limits further constrain handling protocols and distribution infrastructure design. Stakeholders must monitor rare gas supply chain resilience against geopolitical disruptions while evaluating on-site generation investments versus traditional cylinder dependency.
Market Dynamics
Semiconductor lithography expansion in East Asian fabrication clusters is compressing supply timelines for ultra-high purity neon while tightening contamination tolerances to parts-per-billion thresholds. This demand concentration is forcing gas suppliers to co-locate purification assets directly adjacent to customer facilities, fundamentally restructuring traditional cylinder-based distribution economics.
Growth Catalysts
- Semiconductor lithography:Deep ultraviolet and extreme ultraviolet systems in South Korean and Taiwanese fabs require 99.999% purity neon for excimer laser stability, creating dedicated offtake agreements with multi-year tenors.
- REACH and RoHS compliance:European purity specifications for laser-grade gases now mandate enhanced traceability documentation, locking in premium supplier relationships and raising barriers to spot-market sourcing.
- Helium-neon laser legacy:Medical and scientific instrumentation in North American and Japanese research institutions sustains steady demand for red emission line sources at 632.8 nanometers despite solid-state alternatives.
Market Restraints
- Crude neon concentration:Cryogenic air separation for neon extraction concentrates in Ukrainian and Russian industrial corridors, exposing downstream purification to geopolitical supply interruptions and force majeure declarations.
- Helium co-production dependency:Economic viability of neon recovery hinges on helium market pricing, creating margin compression when helium oversupply devalues the co-product stream.
- Diode laser substitution:Solid-state and fiber laser systems in industrial cutting applications are eliminating helium-neon alignment lasers, eroding volume demand in metal fabrication verticals.
Strategic Opportunities
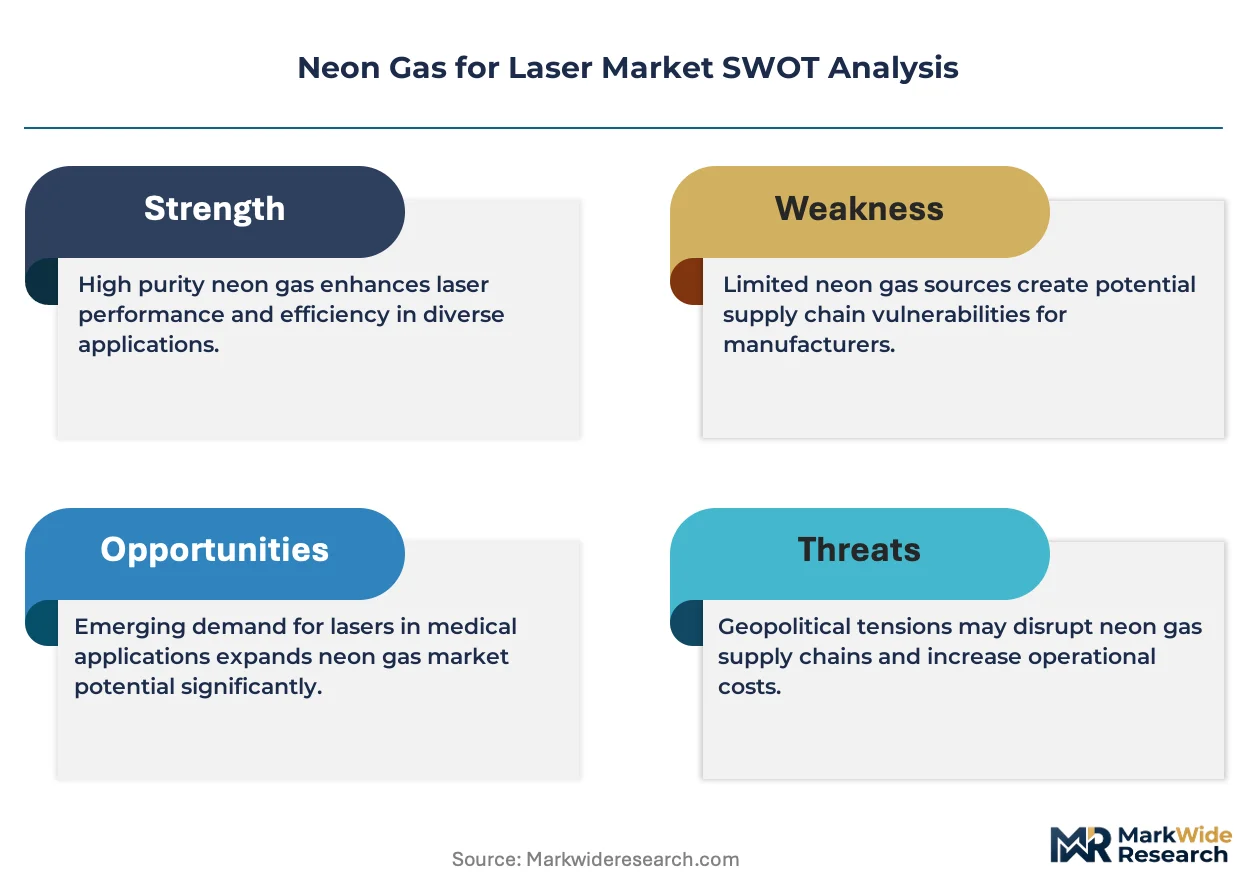
- On-site generation systems:Membrane and pressure-swing adsorption technologies enable captive neon recovery at semiconductor fabs, bypassing cylinder logistics and reducing contamination risk during transport.
- Indian semiconductor manufacturing:PLI scheme subsidies for domestic fab construction under India's semiconductor mission create greenfield demand for localized gas supply infrastructure without incumbent supplier lock-in.
- EU Green Deal alignment:Carbon border adjustment mechanisms favor regional neon purification over transoceanic cylinder shipments, rewarding European air separation operators with pipeline-connected assets.
Industry Challenges
- Cryogenic technician scarcity:Qualified personnel for cold-end operations and vacuum jacket maintenance are rotating toward Asian manufacturing corridors, leaving traditional supply regions with aging workforce pipelines and training gaps.
- CE marking timeline compression:EU MDR certification for medical laser systems now requires extended purity documentation and batch retention protocols, extending gas supplier qualification cycles by 12-18 months.
- Legacy cylinder fleet integration:Existing aluminum and steel cylinder pools lack the valve and internal surface specifications for sub-ppb contamination control, forcing capital-intensive fleet replacement programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neon Gas for Laser Market |
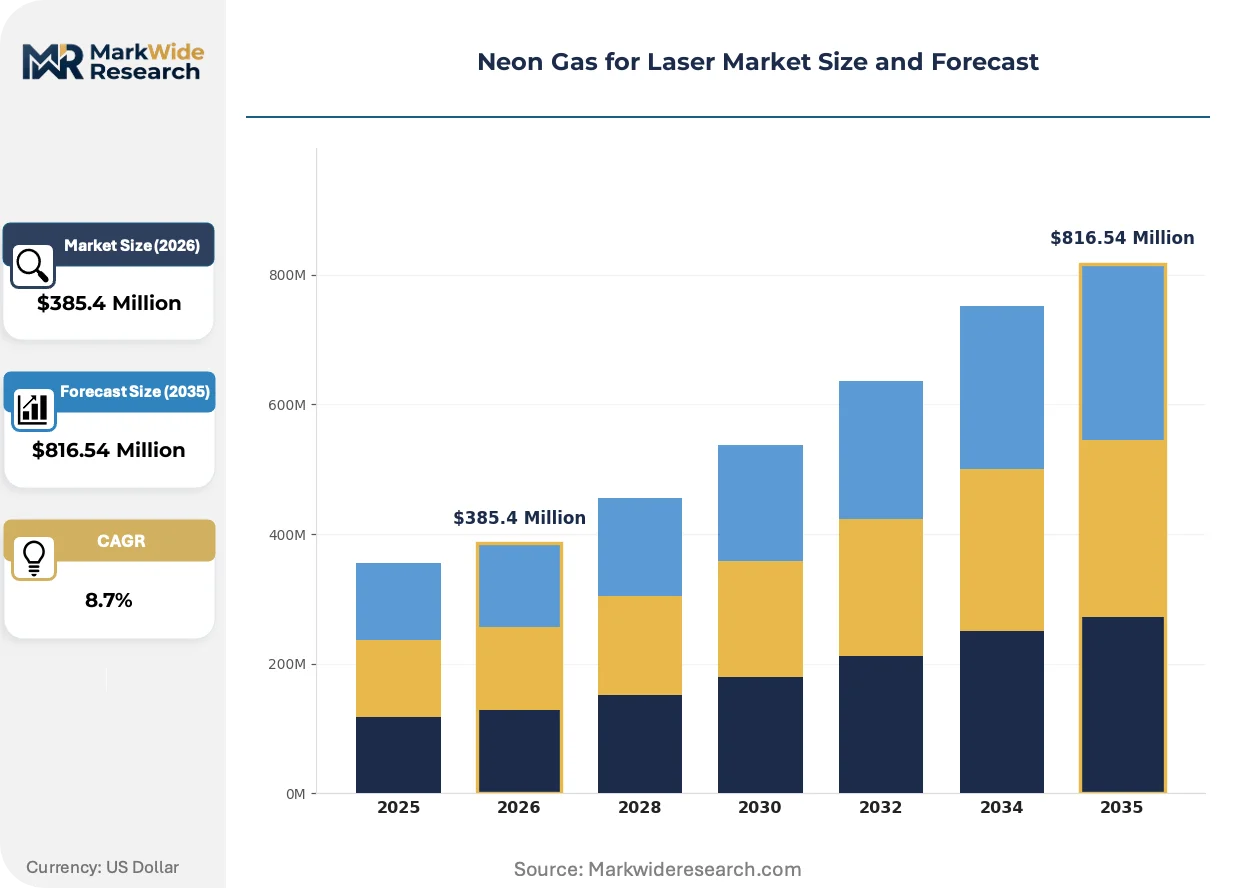
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultra-High Purity Neon, Industrial Grade Neon, Specialty Neon, Medical Grade Neon Application: Laser Cutting, Laser Engraving, Medical Lasers, Research Applications End User: Healthcare Facilities, Manufacturing Plants, Research Institutions, Technical Schools Delivery Mode: Gas Cylinders, Bulk Supply, On-Site Generation, Packaged Gas Solutions |
| Companies Covered | Air Liquide, Linde plc, Air Products and Chemicals, Inc., Messer Group GmbH, Matheson Tri-Gas, Inc., Airgas, Inc., Cryoin Engineering Ltd, Ingas, Axcel Gases, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neon Gas for Laser Market Trends and Innovations
Neon supply architecture is pivoting from centralized air separation hubs toward distributed purification nodes co-located with semiconductor manufacturing. This spatial reconfiguration is compressing logistics chains while raising technical barriers for traditional merchant gas distributors.
Closed-loop neon recycling systems are supplanting single-pass consumption models in high-volume lithography operations. ASML and Nikon lithography tool operators in Hsinchu and Pyeongtaek are retrofitting scrubber and cryogenic recovery units to capture spent neon for re-purification, reducing fresh gas offtake by 60-80 percent per wafer layer and compressing merchant supplier revenue per fab.
REACH authorization requirements for substance-integrated articles are tightening documentation obligations across European laser system supply chains. ECHA's 2024 updates to Annex XIV candidate list screening now mandate full supply chain disclosure for neon-containing assemblies, forcing gas suppliers to implement blockchain-tracked certificates of analysis and extending qualification timelines for non-EU purification sources.
Direct long-term contracting is displacing spot market purchases among tier-one semiconductor manufacturers. Samsung Foundry and TSMC are negotiating take-or-pay agreements with 5-7 year tenors directly with air separation operators, bypassing traditional industrial gas distributors and compressing margin pools for cylinder logistics specialists in East Asian corridors.
Neon Gas for Laser Market Segmentation
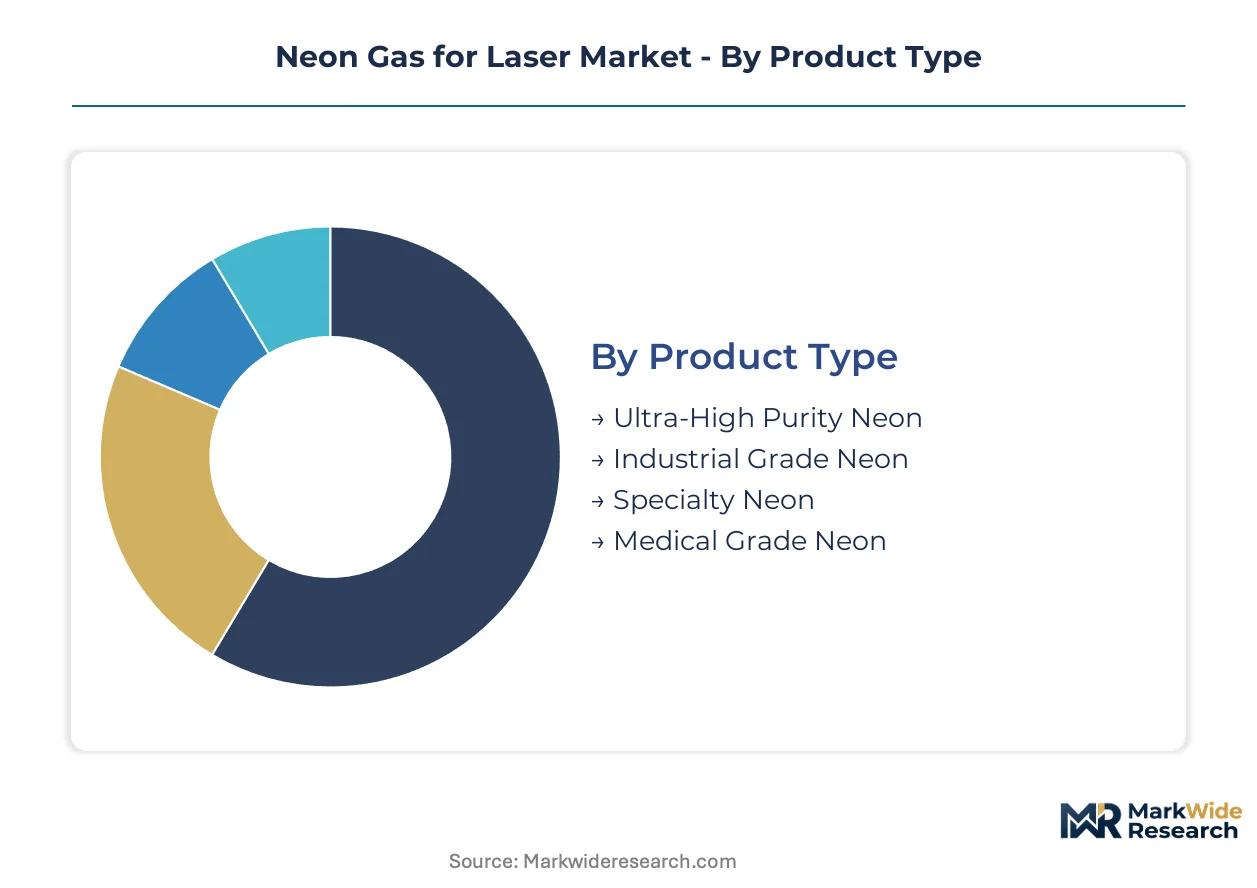
Segmentation in neon gas for laser applications separates specification-driven semiconductor lithography demand from cost-sensitive industrial cutting operations. Regulatory thresholds for medical and research end-uses create distinct purity tiers that reshape supplier qualification requirements and margin structures across each category.
Product Type:
REACH and RoHS compliance in Europe, FDA purity documentation in the United States, and CE marking under EU MDR impose divergent certification burdens across grade specifications.
- Ultra-High Purity Neon:Specifications exceed 99.999% purity with parts-per-billion contamination tolerances for excimer laser stability. Demand concentrates at South Korean and Taiwanese semiconductor fabrication facilities where ASML and Nikon lithography tools require dedicated offtake agreements with multi-year tenors.
- Industrial Grade Neon:Standard purity levels serve helium-neon laser alignment systems in metal fabrication. Cost pressures from diode laser substitution in industrial cutting applications are compressing volume offtake and forcing suppliers toward bulk delivery economics.
- Specialty Neon:Custom isotopic compositions and controlled impurity profiles address niche scientific instrumentation requirements.
- Medical Grade Neon:Batch retention protocols and extended purity documentation satisfy FDA oversight and EU MDR traceability mandates for surgical laser systems.
Established volume favors Industrial Grade Neon; emerging adoption favors Ultra-High Purity Neon.
Application:
Margin structures diverge sharply between high-volume manufacturing processes and low-volume certified medical systems.
- Laser Cutting:Metal fabrication plants in East Asian manufacturing corridors consume the largest cylinder volumes for CO2 laser alignment and beam path stabilization. Diode laser substitution is eroding this segment's growth trajectory in automotive and shipbuilding verticals.
- Medical Lasers:Ophthalmic and dermatological systems command premium per-unit margins through stringent certification protocols. FDA and CE marking requirements extend supplier qualification cycles and lock in premium relationships.
- Laser Engraving:Jewelry and electronics marking applications sustain steady demand for red emission line sources at 632.8 nanometers.
- Research Applications:North American and Japanese scientific institutions maintain legacy helium-neon laser installations despite solid-state alternatives.
Manufacturing scale concentrates in Laser Cutting; margin expansion concentrates in Medical Lasers.
End User:
Procurement sophistication varies from centralized hospital purchasing to distributed technical school maintenance budgets.
- Manufacturing Plants:Semiconductor fabs and metal fabrication facilities negotiate direct long-term contracts with air separation operators, bypassing traditional distributors. Samsung Foundry and TSMC procurement teams favor take-or-pay agreements with 5-7 year tenors.
- Healthcare Facilities:Hospital systems and outpatient surgical centers require full supply chain disclosure under ECHA's Annex XIV screening updates.
- Research Institutions:University and government laboratory procurement depends on grant-funded capital cycles with irregular volume patterns.
- Technical Schools:Vocational training programs prioritize cost minimization over specification compliance for educational laser systems.
Contract sophistication favors Manufacturing Plants; documentation intensity favors Healthcare Facilities.
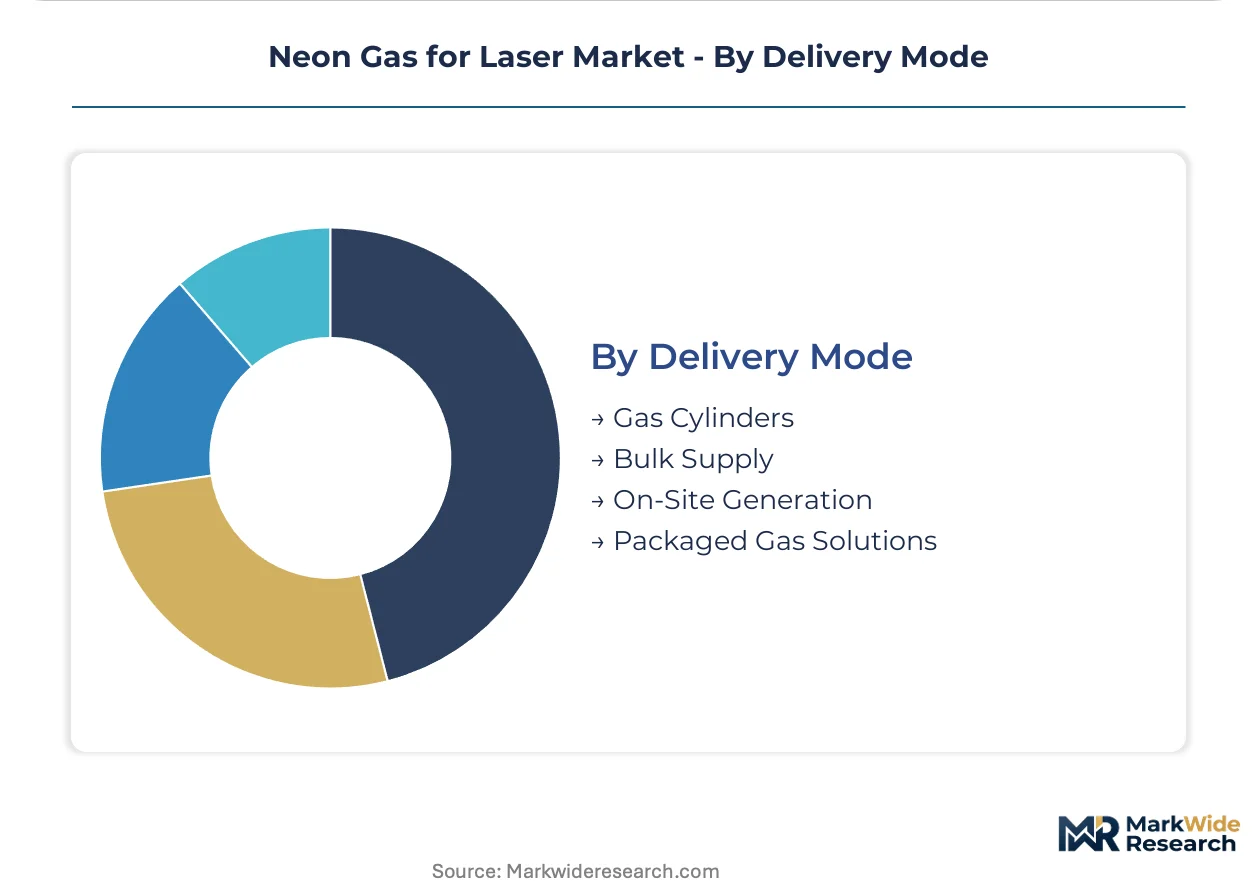
Delivery Mode:
Spatial reconfiguration of supply architecture is compressing logistics chains while raising capital barriers for market entry.
- On-Site Generation:Membrane and pressure-swing adsorption technologies enable captive neon recovery at semiconductor fabs. TSMC and Samsung Foundry retrofit scrubber and cryogenic recovery units to capture spent neon for re-purification, reducing fresh gas offtake by 60-80 percent per wafer layer.
- Bulk Supply:Pipeline-connected assets at European air separation hubs serve regional lithography clusters with reduced contamination risk versus cylinder transport.
- Gas Cylinders:Legacy aluminum and steel cylinder pools lack valve and internal surface specifications for sub-ppb contamination control, forcing capital-intensive fleet replacement programs.
- Packaged Gas Solutions:Bundled cylinder and regulator offerings address small-volume research and medical customers with simplified procurement.
Capital intensity favors On-Site Generation; flexibility favors Packaged Gas Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neon consumption patterns diverge sharply by geography: East Asian semiconductor corridors demand ultra-high purity grades for lithography, while North American and European markets sustain legacy helium-neon laser applications in medical and scientific instrumentation.
South Korea
Samsung Foundry and SK Hynix fabs in Pyeongtaek and Yongin drive concentrated demand for 99.999% purity neon under multi-year take-or-pay contracts. The country's national industrial regulator enforces strict contamination tolerances for excimer laser stability. Hsinchu-adjacent procurement patterns in Korean semiconductor clusters are compressing traditional cylinder logistics in favor of on-site generation retrofits.
Taiwan
TSMC's advanced packaging and lithography operations in Hsinchu Science Park anchor regional neon offtake with dedicated pipeline-connected purification assets. CE marking alignment under EU MDR traceability mandates shapes documentation protocols for exported laser systems. Kaohsiung-based metal fabrication plants sustain residual industrial-grade demand despite diode laser substitution pressures.
United States
FDA oversight of medical laser systems and EPA emissions tracking constrain handling protocols for surgical and dermatological applications. Research institutions in Greater Boston and the San Francisco Bay Area maintain legacy helium-neon installations at 632.8 nanometers. OSHA workplace exposure limits further shape distribution infrastructure design across domestic manufacturing corridors.
Germany
REACH and RoHS compliance requirements tighten purity specifications for laser-grade gases distributed through the Antwerp pipeline hub. The country's automotive laser cutting sector faces margin compression from solid-state alternatives in Bavarian and Baden-Württemberg metal fabrication plants. ECHA's 2024 Annex XIV updates mandate full supply chain disclosure for neon-containing assemblies.
Japan
METI industrial standards and PMDA medical device regulations govern laser system certification and gas supplier qualification cycles. Research institutions in Kanto and Kansai regions sustain steady demand for red emission line sources despite solid-state competition. Osaka-based scientific instrumentation manufacturers prioritize batch retention protocols for niche isotopic compositions.
Neon Gas for Laser Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in neon gas for laser applications. The upper tier comprises continental air separation operators with pipeline-connected assets and multi-continent helium-neon co-production economics. Below them, regional purification specialists compete on distribution flexibility and localized customer proximity. Strategic differentiation clusters around three archetypes: integrated industrial gas conglomerates with captive air separation networks; specialized rare gas recovery operators concentrating on Ukrainian-sourced feedstock; and distributor-integrators bundling cylinder logistics with regulator hardware. Dominant competitive moves include co-location of purification assets adjacent to semiconductor fabs and direct long-term contracting that bypasses traditional merchant distributors.
Among integrated industrial gas operators, Air Liquide and Linde plc exemplify the scale-driven archetype with continental pipeline networks and specialized purification assets. Cryoin Engineering Ltd occupies a position within the regional specialist tier, concentrating on Ukrainian-sourced neon recovery and distribution flexibility in Eastern European corridors. These three anchors illustrate how competitive positioning stratifies between capital-intensive infrastructure players and nimble regional suppliers.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products and Chemicals, Inc. |
| Messer Group GmbH |
| Matheson Tri-Gas, Inc. |
| Airgas, Inc. |
| Cryoin Engineering Ltd |
| Ingas |
| Axcel Gases |
| Others |
Pricing and Supply Chain Analysis
Long-term take-or-pay contracts between semiconductor fabs and air separation operators lock in supply access and price visibility for ultra-high purity neon across East Asian manufacturing corridors. These multi-year agreements with Samsung Foundry and TSMC procurement teams compress spot market liquidity while anchoring premium pricing tiers for 99.999% purity grades.
Pricing Analysis
Contract-based long-term offtake dominates neon procurement for semiconductor lithography, with pricing stratifying across ultra-high purity, industrial grade, and medical certification tiers. Price differentiation hinges on contamination tolerance levels and REACH documentation burden, with CE marking under EU MDR extending supplier qualification cycles. Cost compression in industrial-grade segments intensifies because diode laser substitution erodes helium-neon alignment laser volumes. Manufacturing plants exhibit highest price sensitivity through direct air separation operator negotiations, while medical laser system buyers accept premium positioning for FDA-compliant batch retention protocols.
Supply Chain Analysis
Ukraine and Russia anchor crude neon concentration through cryogenic air separation feedstock, with downstream purification drawing from Belgian and German pipeline-connected assets. Raw material dependencies center on helium co-production economics, Ukrainian-sourced crude neon, and specialized adsorbent materials for purification. Single-source vulnerability runs through geopolitical disruption exposure in Eastern European feedstock corridors. Distribution runs through co-located purification nodes adjacent to Taiwanese and South Korean semiconductor fabs, bypassing traditional cylinder logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neon supply architecture is approaching a platform-economics inflection where closed-loop recycling systems and on-site generation create interoperability between lithography tool operators and gas purification assets.
For Market Incumbents: Shield lithography-grade market position through backward integration into on-site generation retrofits at TSMC and Samsung Foundry facilities. Anchor European supply security via Antwerp pipeline hub capacity expansion before carbon border adjustment mechanisms favor regional purification. Diode laser substitution in metal fabrication verticals threatens industrial-grade volume pools. For New Entrants and Emerging Players: CE marking fast-track under EU MDR traceability mandates creates qualification arbitrage for medical-grade neon suppliers serving ophthalmic laser system manufacturers. White-space concentrates in Indian semiconductor manufacturing corridors under PLI scheme subsidies, where greenfield fab construction lacks incumbent supplier lock-in. Target hospital procurement committees through bundled cylinder-regulator offerings with blockchain-tracked certificates of analysis. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors pipeline-connected air separation operators with captive helium-neon co-production economics. Long-term viability over the projection horizon rests on supply chain resilience against geopolitical disruption and on-site generation technology maturation. Acquisition targets should demonstrate scrubber retrofit capabilities at existing lithography installations. Watch for force majeure declarations in Ukrainian feedstock corridors as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Generation Retrofit | TSMC and Samsung Foundry scrubber installations reduce fresh gas offtake by 60-80 percent per wafer layer. |
| Pipeline Hub Expansion | Air Liquide's Antwerp asset base secures REACH-compliant supply for EU lithography clusters under carbon border mechanisms. |
| CE Marking Fast-Track | ECHA Annex XIV documentation protocols extend qualification timelines for non-EU purification sources. |
| Helium-Neon Co-Production | Linde plc's integrated air separation network sustains economics across multiple continents despite helium price volatility. |
| Closed-Loop Recycling System | ASML lithography tool operators in Hsinchu capture spent neon for re-purification, compressing merchant supplier revenue. |
Research Methodology
Initial hypotheses were tested against primary input from gas supply procurement managers, cryogenic operations technicians, semiconductor fab materials directors, and medical device regulatory affairs leads, then refined through secondary validation. Bottom-up modeling triangulated customs trade data, SEC filings from industrial gas conglomerates, ECHA REACH registration databases, and hospital GPO contract disclosures. Top-down segmentation cross-checked against air separation capacity announcements and lithography tool shipment records.
Variance-decomposition across purity grade, application vertical, delivery mode, and regional manufacturing cluster shaped the analytical framework. CAGRs were derived from installed base projections for excimer and helium-neon laser systems, overlaying semiconductor capital expenditure cycles and medical laser certification timelines. Forecast inputs incorporated on-site generation adoption curves at leading-edge fabs and helium market pricing co-dependency effects.
The analysis sits within stated boundaries; outcomes outside sustained East Asian semiconductor capacity expansion or stable Ukrainian feedstock access would require recalibration. Forecasts reflect assumptions regarding lithography tool utilization rates and regulatory documentation burden stability. Recalibration cycles align with material shifts in geopolitical supply disruption events and on-site generation technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Neon Gas Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Industrial Oxygen Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
North America Syngas Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
High Purity Gas Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
High Purity Methane Gas Market