
 North American Feed Testing Market | 2026-2036
North American Feed Testing Market Size, Share, and Industry Trends Forecast 2026-2036
North American Feed Testing Market Analytics
Integrated livestock operations are unwinding reliance on commodity spot testing in favor of continuous monitoring contracts. Eurofins Scientific leverages its North American laboratory network to anchor multi-state feedlot accounts. SGS SA competes through onsite mobile units that reduce sample transit times for remote cattle operations. Bruker Bioscience Corporation differentiates with spectroscopy platforms that cut mycotoxin detection turnaround to under four hours.
North American feed testing encompasses analytical protocols that quantify nutritional composition, detect pathogenic contamination, verify additive concentrations, and certify regulatory compliance across commercial feed streams. Chromatography and immunoassay methods detect aflatoxin thresholds below FDA action limits of twenty parts per billion. Mycotoxin testing commands premium pricing due to seasonal grain volatility and zero-tolerance export standards. Nutritional analysis sustains steady volume from dairy ration balancing programs, while laboratory analysis services capture recurring revenue through subscription-based monitoring contracts with feed manufacturers.
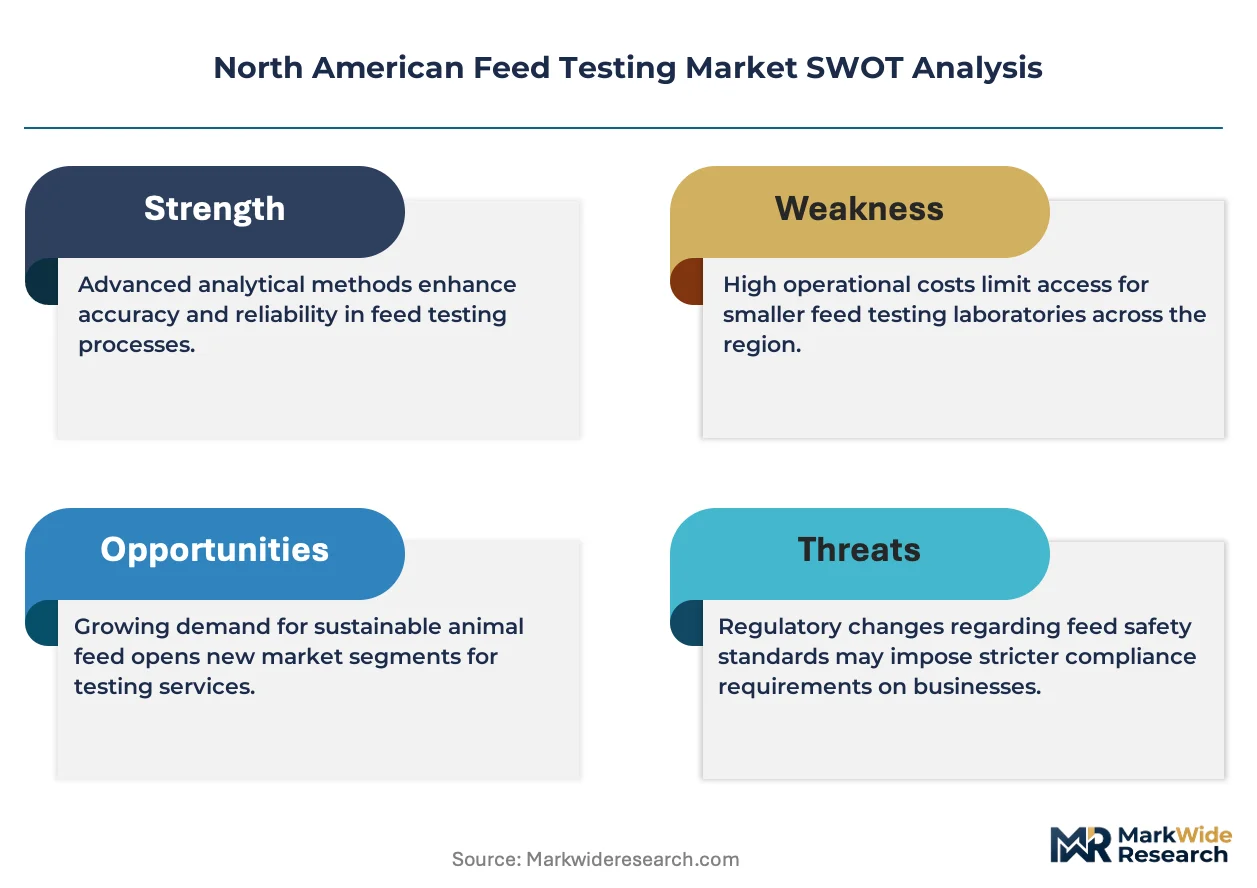
FDA feed safety rules, EPA pesticide residue thresholds, and USDA grain inspection standards collectively mandate documented testing chains from ingredient sourcing through finished feed delivery. The EPA's tolerance-setting authority for feed crop pesticides directly shapes laboratory method development priorities. Stakeholders must monitor evolving FSMA enforcement patterns and state-level veterinary feed directive compliance to align service portfolios with inspection intensity.
Market Dynamics
FSMA enforcement intensity is compressing testing timelines across the US feed manufacturing base, forcing laboratories to restructure service delivery around continuous monitoring contracts rather than episodic batch verification.
Growth Catalysts
- FSMA Preventive Controls Rule:FDA-mandated hazard analysis and preventive controls require documented testing protocols for animal food facilities, expanding recurring revenue opportunities for certified laboratories.
- Midwest feedlot corridor concentration:Iowa, Nebraska, and Kansas host the densest commercial cattle finishing operations in North America, generating concentrated demand for mycotoxin surveillance and nutritional ration validation.
- Zero-tolerance export standards:EU and Asian import authorities reject grain shipments exceeding strict aflatoxin thresholds, compelling US exporters to maintain in-house or contracted testing capacity.
Market Restraints
- Laboratory instrumentation costs:LC-MS/MS systems required for multi-mycotoxin panels carry capital expenditures exceeding $300,000 per unit, constraining independent laboratory expansion.
- Midwest grain belt weather volatility:Drought-flood cycles in the Corn Belt produce irregular mycotoxin pressure, creating demand unpredictability that complicates capacity planning.
- Veterinary feed directive compliance friction:FDA restrictions on medically important antibiotics in feed require additional documentation chains, extending turnaround times for medicated feed verification.
Strategic Opportunities
- Canadian prairie expansion:Alberta and Saskatchewan feedlot operations lack dense laboratory infrastructure, creating white space for mobile testing units and regional satellite facilities.
- Real-time spectroscopy integration:Convergence of near-infrared hardware with cloud-based calibration models enables at-line nutritional analysis, bypassing centralized laboratory bottlenecks.
- USDA Organic certification growth:Rising organic livestock production mandates prohibited substance verification, opening specialized testing segments with premium pricing power.
Industry Challenges
- Analytical chemist recruitment gaps:Rural laboratory locations in Kansas and Nebraska struggle to attract LC-MS operators, extending hiring timelines and constraining throughput expansion.
- ISO 17025 accreditation maintenance:Triennial reassessment cycles demand continuous method validation documentation, diverting technical staff from revenue-generating analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North American Feed Testing Market |
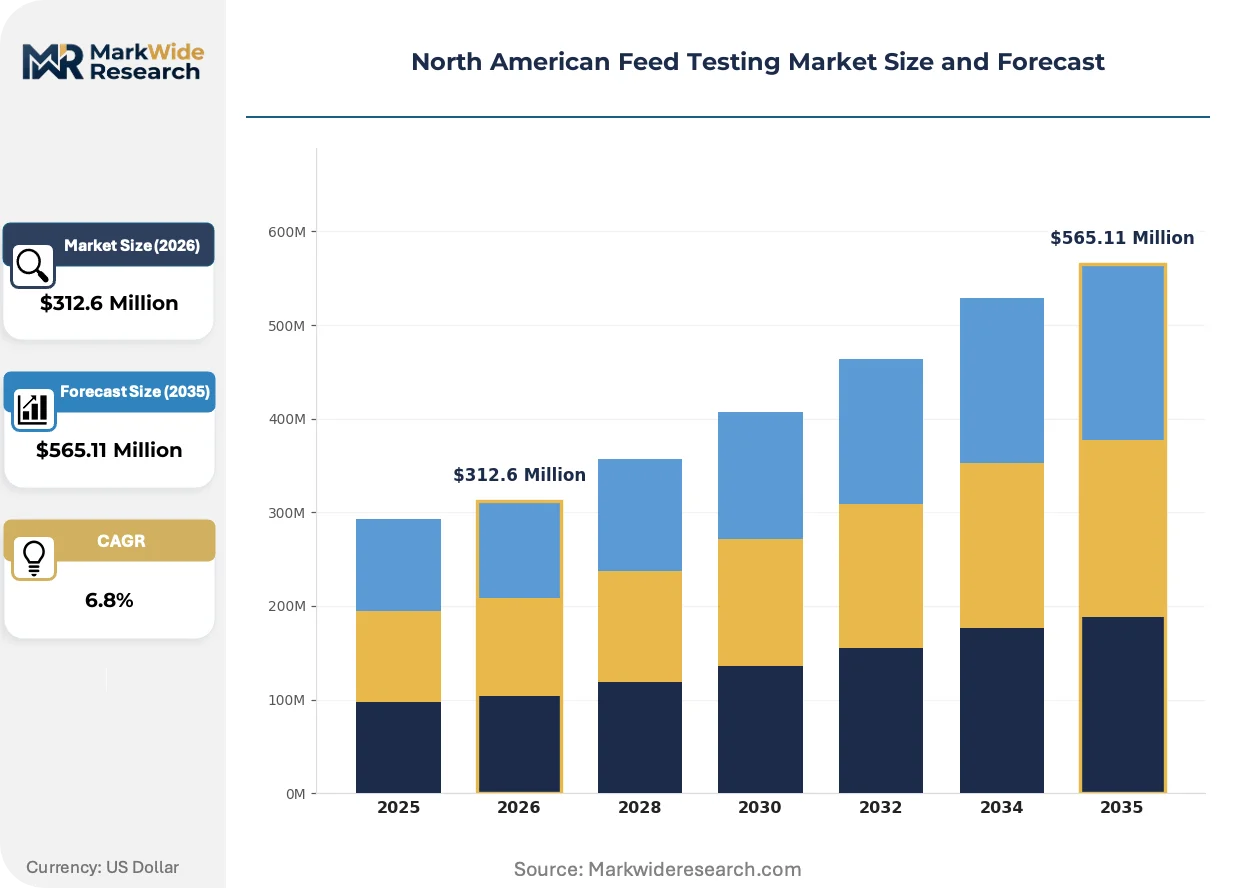
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbiological Tests, Nutritional Analysis, Chemical Tests, Mycotoxin Testing Application: Animal Feed, Pet Food, Aquaculture Feed, Ingredients Testing End User: Feed Manufacturers, Livestock Farms, Research Institutions, Quality Control Labs Service Type: Consultancy Services, Onsite Testing, Laboratory Analysis, Compliance Testing |
| Companies Covered | Eurofins Scientific, SGS SA, Intertek Group Plc, Bruker Bioscience Corporation, SYNLAB, Bureau Veritas SA, Adpen Laboratories Inc, Romer Labs Inc, Silliker Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North American Feed Testing Market Evolving Landscape
Spectroscopy platforms and automated sample handling are compressing detection timelines from days to hours, while regulatory digitization mandates reshape documentation workflows across the testing value chain.
Raman spectroscopy is decomposing traditional chromatography workflows for mycotoxin screening in corn and soybean meal. Large integrated pork processors in North Carolina and Iowa are adopting handheld units for inbound grain inspection. This technology is decomposing the economics of centralized laboratory testing by enabling dockside acceptance decisions without sample transit delays.
FSMA Intentional Adulteration Rule requirements are extending vulnerability assessment documentation to feed ingredient suppliers. Facilities must now identify actionable process steps and implement mitigation strategies with verification testing. The rule most affects bulk grain receiving operations in the US Midwest, where feed mills are deploying environmental monitoring for chemical hazards alongside biological surveillance.
Subscription-based monitoring contracts are displacing spot-test purchasing among dairy nutrition consultants. Large herd veterinarians in Wisconsin and New York are bundling monthly TMR analysis with ration balancing software licenses. This shift is most visible in the upper Midwest dairy belt, where 500-plus cow operations prioritize nutritional consistency over per-test cost minimization.
North American Feed Testing Market Segmentation
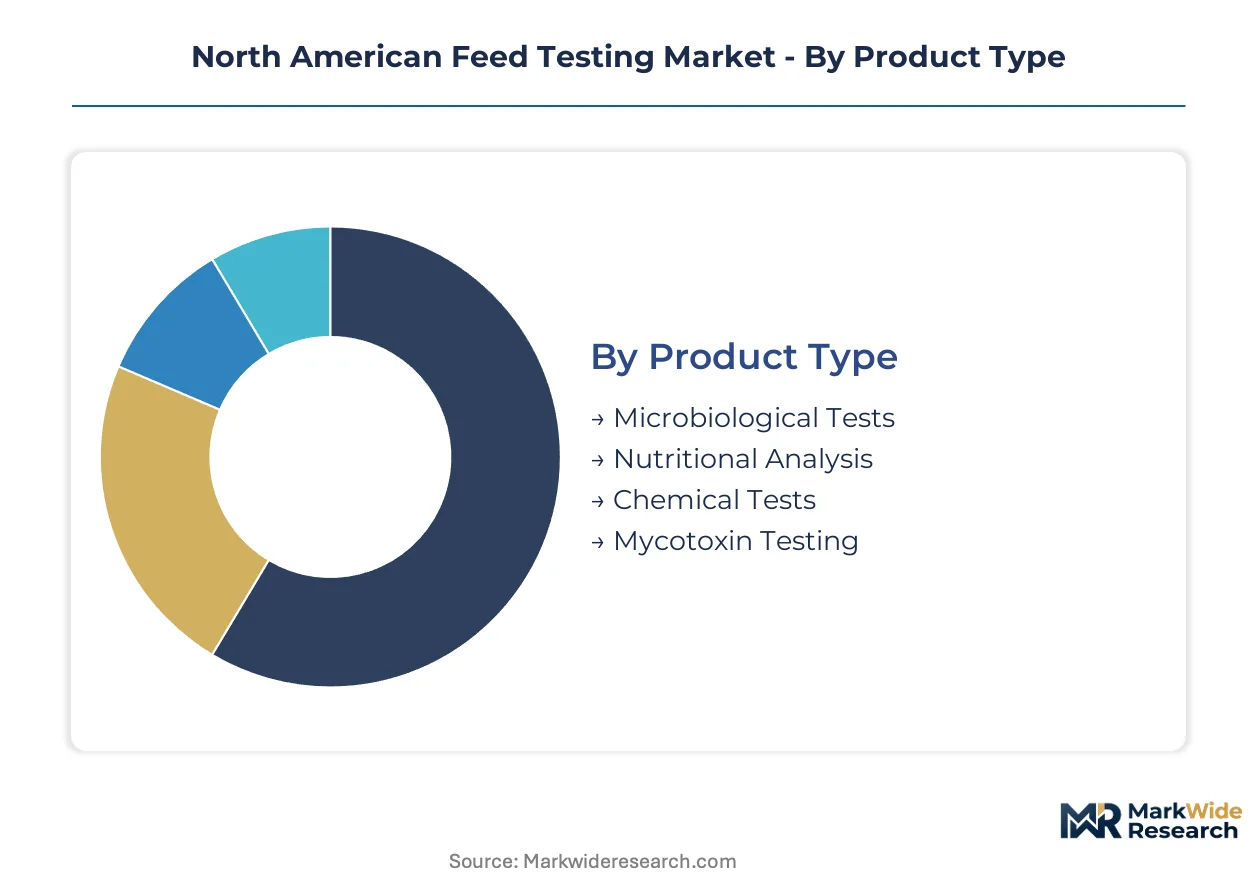
Feed testing segmentation in North America reflects divergent compliance pressures across domestic livestock operations versus export-oriented grain handlers. Testing intensity varies sharply between routine nutritional validation for dairy ration balancing and zero-tolerance mycotoxin surveillance for EU-bound shipments.
Product Type:
Domestic feedlots drive nutritional analysis volume, while export grain elevators concentrate mycotoxin testing investment. Chemical test demand splits between FDA-mandated medicated feed verification and EPA pesticide residue monitoring.
- Nutritional Analysis:Proximate analysis, amino acid profiling, and energy density quantification support dairy TMR optimization and poultry feed formulation. Wisconsin and New York dairy nutrition consultants bundle monthly analysis with ration balancing software subscriptions, generating recurring revenue streams independent of commodity price cycles.
- Mycotoxin Testing:Aflatoxin, DON, fumonisin, and zearalenone detection employs LC-MS/MS and immunoassay methods with FDA action limits at twenty parts per billion for aflatoxin. Iowa and Nebraska grain elevators maintain continuous surveillance contracts during harvest volatility to protect EU and Asian export access.
- Microbiological Tests:Salmonella, E. coli, and Listeria screening addresses FSMA preventive controls for animal food facilities.
- Chemical Tests:Pesticide residue quantification and heavy metal detection serve EPA tolerance compliance and organic certification requirements.
Nutritional analysis commands the established base. The steepest expansion runs through mycotoxin testing.
Application:
Commercial animal feed dominates testing volume, though pet food safety scandals have elevated analytical standards for companion animal nutrition. Aquaculture feed represents a nascent category with specialized fatty acid and contaminant profiles.
- Animal Feed:Cattle finishing operations in the Midwest feedlot corridor generate concentrated demand for ration validation and medicated feed documentation. Large integrated pork processors in Iowa and North Carolina deploy handheld spectroscopy units for inbound grain inspection, compressing acceptance decision timelines.
- Pet Food:Premiumization trends and FDA food safety rule extension to pet food manufacturers drive contaminant surveillance and nutritional claim verification. Melamine and cyanuric acid detection protocols established post-2007 recalls remain standard practice.
- Aquaculture Feed:Marine and freshwater species formulations require specialized proximate analysis and heavy metal screening for farm-to-table traceability programs.
- Ingredients Testing:Pre-formulation verification of grain, oilseed, and additive lots protects finished feed quality and supports supplier qualification programs.
Animal feed anchors volume concentration. Pet food claims the fastest margin expansion trajectory.
End User:
Feed manufacturers internalize compliance testing to protect brand liability, while livestock farms outsource specialized analysis to certified laboratories. Quality control laboratories serve as intermediaries aggregating demand from mid-sized operations lacking in-house capacity.
- Feed Manufacturers:Large integrated mills maintain in-house LC-MS/MS capability for real-time release testing and FSMA preventive controls documentation. Capital investment in multi-mycotoxin panels exceeds three hundred thousand dollars per unit, favoring scale concentration.
- Livestock Farms:Dairy operations exceeding five hundred cow capacity subscribe to monthly TMR analysis services. Independent cattle feeders in Kansas and Nebraska rely on regional satellite laboratories or mobile testing units for mycotoxin surveillance.
- Quality Control Labs:Third-party certification bodies and commercial analytical services aggregate spot-test demand from mid-tier operations.
- Research Institutions:University extension services and veterinary colleges conduct method development and validation studies supporting industry standard evolution.
Feed manufacturers dominate capital deployment. Livestock farms represent the most rapid outsourcing adoption curve.
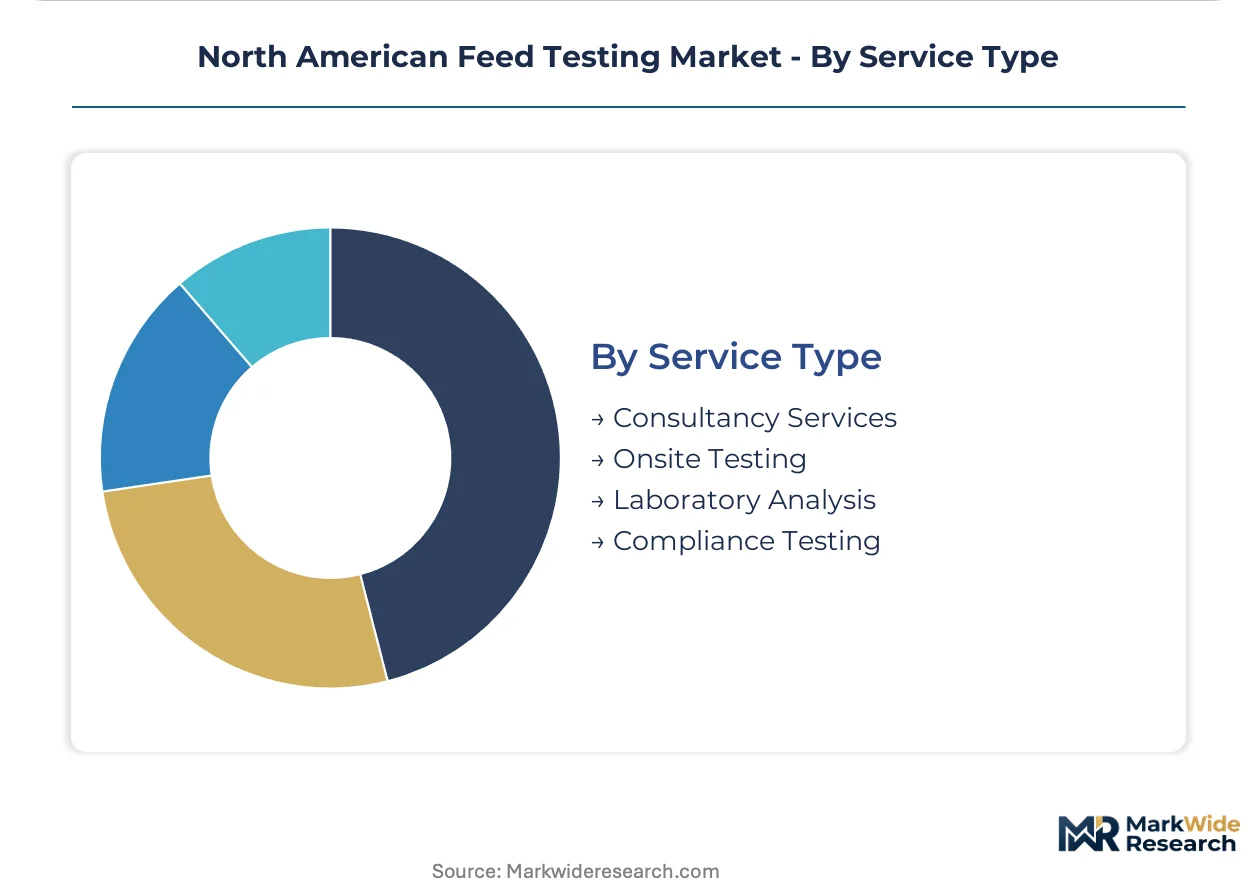
Service Type:
Laboratory analysis retains the revenue core, though onsite testing and subscription monitoring contracts are displacing episodic batch verification. Consultancy services attach to complex regulatory navigation and ration optimization programs.
- Laboratory Analysis:Centralized chromatography and spectroscopy facilities deliver definitive quantitative results with ISO 17025 accreditation. Eurofins Scientific and SGS SA anchor multi-state accounts through North American laboratory networks and mobile unit deployment.
- Onsite Testing:Portable near-infrared and Raman spectroscopy platforms enable at-line nutritional analysis and dockside grain acceptance. Bruker Bioscience Corporation differentiates with mycotoxin detection turnaround under four hours.
- Compliance Testing:FSMA preventive controls, veterinary feed directive documentation, and organic certification verification require standardized protocols with audit trail integrity.
- Consultancy Services:Regulatory interpretation, hazard analysis preparation, and ration formulation support attach to analytical service relationships.
Laboratory analysis secures the revenue foundation. Onsite testing gains share most quickly through hardware convergence and cloud calibration models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated livestock operations and export grain handlers drive testing demand concentration across the continent. Feed manufacturers and veterinary consultants form the core buyer archetypes, with procurement patterns splitting between subscription monitoring contracts and spot-test verification.
United States
The Midwest feedlot corridor spanning Iowa, Nebraska, and Kansas generates the densest commercial cattle finishing demand. FDA FSMA preventive controls enforcement compels documented testing protocols from ingredient sourcing through finished feed delivery. Chicago-area grain elevators maintain continuous mycotoxin surveillance contracts during harvest volatility to protect EU and Asian export access.
Canada
Alberta and Saskatchewan feedlot operations lack dense laboratory infrastructure, creating white space for mobile testing deployment. Health Canada and CFIA feed safety regulations align with FDA frameworks while maintaining distinct veterinary drug residue monitoring requirements. Calgary and Edmonton serve as distribution nodes for prairie livestock operations seeking outsourced analytical services.
Mexico
Northern border states concentrate commercial poultry and pork production serving US-integrated supply chains. SENASICA feed safety oversight requires documented pathogen surveillance for export-oriented operations. Querétaro and Guanajuato host expanding feed manufacturing capacity with growing third-party testing adoption.
North American Feed Testing Market Competitive Landscape
Player mix skews toward diversified testing conglomerates with multi-site laboratory networks anchoring regional accounts. Market structure concentrates around three strategic tiers: pan-continental laboratory networks with ISO 17025 accreditation, specialized mycotoxin boutiques with rapid turnaround capabilities, and equipment-integrated service providers bundling hardware with analytical subscriptions. Competitive dynamics center on geographic coverage expansion through satellite facility deployment and technology convergence partnerships linking spectroscopy platforms with cloud-based calibration services.
Within the diversified laboratory network tier, Eurofins Scientific and SGS SA occupy positions exemplifying multi-state account anchoring through distributed facility footprints. Bruker Bioscience Corporation represents the equipment-integrated archetype, with spectroscopy platforms serving as entry points for subscription-based analytical relationships.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS SA |
| Intertek Group Plc |
| Bruker Bioscience Corporation |
| SYNLAB |
| Bureau Veritas SA |
| Adpen Laboratories Inc |
| Romer Labs Inc |
| Silliker Inc |
| Others |
Value Network & Pricing Analysis
Subscription monitoring contracts with named volume commitments lock in laboratory capacity access and flatten price volatility for Midwest feedlot operators facing FSMA compliance deadlines. These multi-year agreements tie pricing to grain harvest cycles and mycotoxin surveillance intensity, converting spot-test uncertainty into predictable operational expenditure.
Pricing Analysis
Cost-plus contracts indexed to LC-MS/MS consumable costs and analyst labor rates dominate the laboratory services tier. Three-tier pricing structure across ISO 17025-accredited, state-certified, and unaccredited service levels separates premium turnaround guarantees from standard batch processing. Pricing pressure stems from portable spectroscopy hardware reducing reliance on centralized chromatography. Small independent cattle feeders in Kansas exhibit highest price sensitivity, while integrated pork processors prioritize speed over per-test cost.
Supply Chain Analysis
Germany and the United States anchor mass spectrometry instrumentation manufacturing, with Japan supplying critical detector components. Laboratory reagents and chromatography columns draw from specialty chemical production concentrated in Switzerland and the Netherlands. Single-source vulnerability runs through helium supply for GC-MS systems, where geopolitical disruption threatens analytical throughput. Distribution runs through manufacturer-direct sales for large laboratory networks and regional distributors serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American feed testing market rewards organizations that control scarce LC-MS/MS operator talent and ISO 17025 accreditation depth. Rural laboratory locations in Nebraska and Kansas struggle to recruit analytical chemists, creating persistent throughput bottlenecks that favor incumbents with established training pipelines.
For Market Incumbents: Consolidate regional satellite laboratory networks to capture mobile testing demand from remote cattle operations in the Canadian prairie. Acquire spectroscopy platform providers to bundle hardware with recurring calibration subscriptions, neutralizing Bruker Bioscience Corporation's equipment-integrated service model. Defend against portable Raman spectroscopy substitution by embedding laboratory chemists directly into large feed mill quality control operations. For New Entrants and Emerging Players: Lead with Alberta and Saskatchewan feedlot corridors where laboratory infrastructure density lags Midwest benchmarks by sixty percent. Target mid-sized dairy operations in Wisconsin and New York with bundled TMR analysis and ration balancing software subscriptions, displacing incumbent spot-test relationships. Deploy cloud-connected near-infrared units with remote calibration support to bypass capital-intensive LC-MS/MS investment requirements. For Investors and Strategic Acquirers: Regional satellite laboratories with established FSMA compliance documentation capabilities and trained LC-MS/MS operators present the most defensible acquisition targets. Long-term viability hinges on spectroscopy-platform convergence and regulatory digitization mandates expanding addressable monitoring contract value. Watch FDA enforcement intensity in the Midwest feedlot corridor as the primary inflection signal for laboratory capacity utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Spectroscopy Platform Integration | Bruker Bioscience Corporation's sub-four-hour mycotoxin detection compresses acceptance decision timelines for Iowa grain elevators. |
| Mobile Testing Unit Deployment | SGS SA's onsite units reduce sample transit times for remote Kansas cattle operations lacking laboratory proximity. |
| Subscription Monitoring Contracts | Eurofins Scientific anchors multi-state accounts through recurring revenue independent of commodity price volatility. |
| ISO 17025 Accreditation Investment | Triennial reassessment cycles demand continuous method validation, diverting technical staff from revenue-generating analysis. |
| Canadian Prairie Expansion | Alberta and Saskatchewan feedlot operations lack dense laboratory infrastructure, creating white space for satellite facility deployment. |
Research Methodology
Operator-level perspectives from feed mill quality control managers, veterinary nutrition consultants, LC-MS/MS laboratory directors, and grain elevator procurement officers anchored the qualitative base. Primary interviews combined with secondary validation from FDA FSMA guidance documents, EPA pesticide tolerance databases, USDA grain inspection standards, and ISO 17025 accreditation registries. Bottom-up testing volume estimates from state-level feed manufacturing facility counts triangulated against top-down laboratory revenue aggregation across the analysis window.
Sensitivity analysis on grain harvest volatility and mycotoxin pressure indices shaped the forecast framework across the projection horizon. Segmentation dimensions modeled include product type (nutritional analysis, mycotoxin testing, microbiological screening), end-user category (feed manufacturers, livestock farms, quality control laboratories), and service delivery mode (centralized laboratory, onsite testing, subscription monitoring). CAGRs derived from historical testing intensity trends and regulatory enforcement pattern projections, with specific inputs from veterinary feed directive compliance friction and spectroscopy adoption curves.
Forecasts assume regulatory continuity in FDA FSMA enforcement and EPA tolerance-setting regimes; material policy shifts would require re-modeling. Specific risks include Midwest drought-flood cycles producing irregular mycotoxin pressure, helium supply disruption constraining GC-MS throughput, and analytical chemist recruitment gaps extending laboratory hiring timelines. Recalibration cycles align with material shifts in FSMA enforcement intensity and spectroscopy hardware cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Testing, Inspection, and Certification for Agriculture & Food Market
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Pesticide Residue Testing Market
Agricultural Testing Services
Impact Soil Tester Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Plant Nutrient Testing Equipment Market
Agricultural Testing Services
Animal Feed Testing Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Soil Sampling Services Market
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Poultry Diagnostic Testing Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Irrigation Testing Kit Market
Agricultural Testing Services
Nematode Testing Services Market