
 Testing, Inspection, and Certification for Agriculture & Food Market | 2026-2036
Testing, Inspection, and Certification for Agriculture & Food Market Size, Share, and Industry Trends Forecast 2026-2036
Testing, Inspection, and Certification for Agriculture & Food Market Insights
On-site audit revenue is rewriting margin allocation across the TIC value chain. SGS leverages its global laboratory footprint to capture high-value pesticide residue testing contracts. Bureau Veritas anchors its position through specialized mycotoxin analysis capabilities in grain-import corridors. Eurofins Scientific differentiates via genomic sequencing methods that accelerate pathogen identification timelines.
Testing, Inspection, and Certification for Agriculture & Food encompasses analytical verification of chemical residues, microbiological contaminants, and authenticity markers across crop and livestock supply chains, employing chromatography, mass spectrometry, and DNA-based methods to verify compliance with safety thresholds and label claims. Its primary commercial purpose is to enable market access by generating defensible evidence that products meet buyer specifications and regulatory ceilings for hazards. Quality Assurance services command the largest revenue share due to recurring batch-release obligations in food processing, while IoT Solutions represent the fastest-expanding technology segment as sensor networks enable real-time temperature and humidity monitoring during transport. HACCP Certification maintains mature demand in developed markets, whereas Sustainability Certification is emerging as a margin-rich category as retailers impose scope-three emissions disclosure requirements on suppliers.
EU Green Deal targets and REACH chemical registration rules are tightening maximum residue limits for imported produce, directly expanding testing volumes at European border inspection posts. FDA enforcement of the Food Safety Modernization Act preventive controls and China's SAMR implementation of GB food safety standards are converging toward hazard-analysis-based verification, elevating demand for accredited third-party audits. Stakeholders must monitor divergence between regional digital traceability mandates to determine whether to invest in unified data platforms or maintain jurisdiction-specific compliance architectures.
Market Dynamics
EU Green Deal residue limit mandates are forcing food processors to triple testing frequencies at border posts, compressing turnaround times from days to hours and reshaping laboratory capacity planning across import corridors.
Growth Catalysts
- REACH Chemical Registration:ECHA's expanded substance evaluation list requires additional analytical verification for pesticide metabolites in imported grains, driving contract volume at specialized residue laboratories.
- IoT Sensor Networks:Real-time temperature and humidity monitoring during cold-chain transport creates continuous data streams that require third-party validation for insurance and liability purposes.
- German Dairy Cooperatives:Large-scale milk pooling operations in Bavaria and Lower Saxony mandate batch-level mycotoxin screening, sustaining high-frequency testing relationships with certification bodies.
Market Restraints
- Reference Material Scarcity:Certified analytical standards for novel pesticide compounds face production bottlenecks, extending method validation timelines and delaying contract execution.
- Laboratory Concentration:Accredited pesticide residue testing capacity clusters in Germany, Netherlands, and France, creating geographic access barriers for producers in Eastern European sourcing regions.
- Mass Spectrometry Cost Structure:High-resolution LC-MS/MS instrumentation requires seven-figure capital deployment with five-year depreciation cycles, constraining mid-tier laboratory expansion.
Strategic Opportunities
- Scope-Three Emissions Disclosure:EU CSRD mandates for supply chain carbon accounting create demand for farm-level audit services that verify agricultural input footprints and land-use change metrics.
- Blockchain-Enabled Traceability:Distributed ledger verification of organic and geographic origin claims converges with traditional certification, opening hybrid service models for premium food segments.
- Polish Processing Corridor:Underpenetrated meat and dairy processing capacity near Warsaw offers expansion potential for HACCP audit services as facilities seek export qualification to Western European retail chains.
Industry Challenges
- Genomic Sequencing Talent Gap:Pathogen identification via whole-genome sequencing requires bioinformatics specialists with food microbiology cross-training, a combination scarce in European labor markets.
- Multi-Jurisdiction Certification Overlap:Divergent digital traceability mandates between EU member states force laboratories to maintain parallel data architectures, inflating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testing, Inspection, and Certification for Agriculture & Food Market |
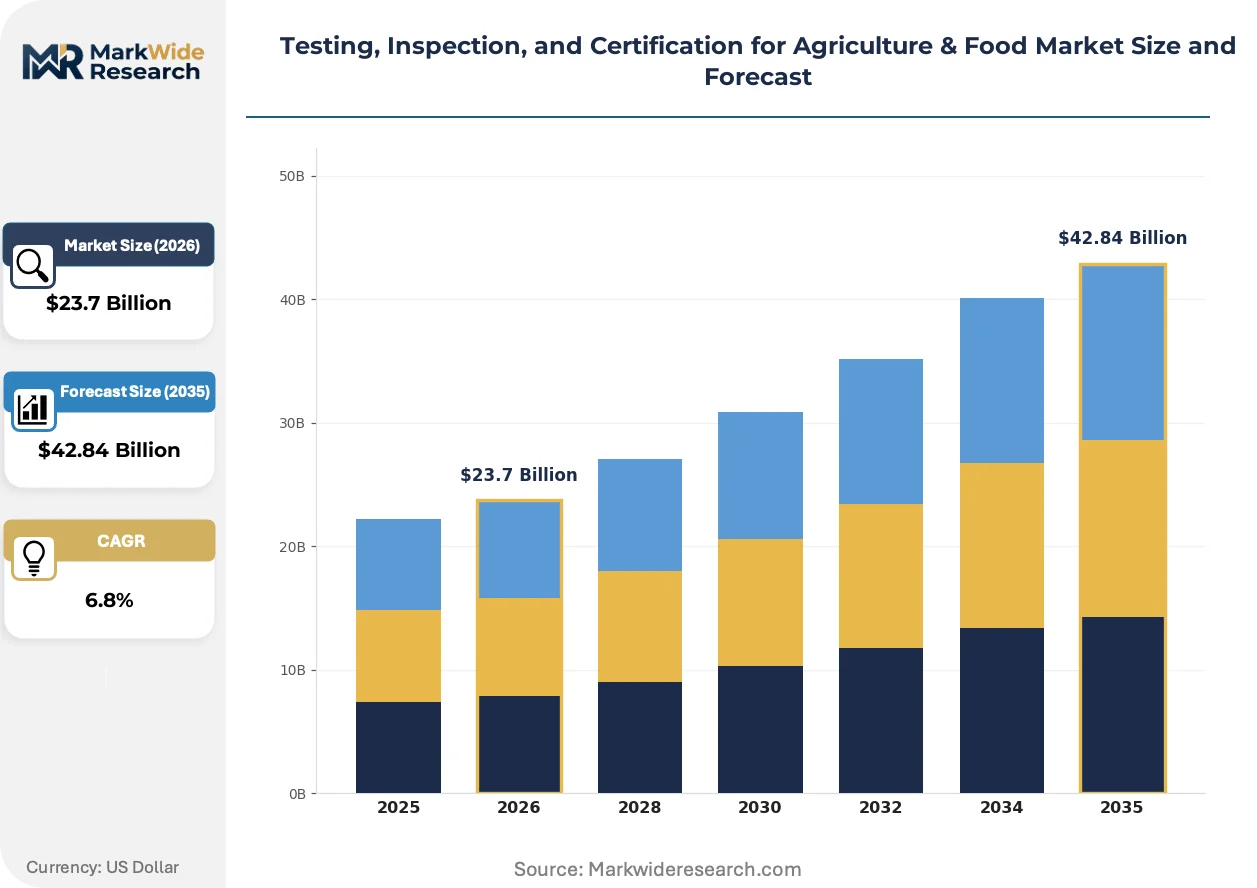
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quality Assurance, Safety Testing, Regulatory Compliance, Certification Services End Use Industry: Agriculture, Food Processing, Dairy, Horticulture Technology: Lab Analysis, Remote Sensing, Decentralized Testing, IoT Solutions Certification Type: Organic Certification, Quality Management, HACCP Certification, Sustainability Certification |
| Companies Covered | Eurofins Scientific, DEKRA, SGS, ALS Limited, DNV, Bureau Veritas, TÜV SÜD, AsureQuality, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testing, Inspection, and Certification for Agriculture & Food Market Trends and Innovations
Digital verification protocols are displacing paper-based audit trails across agricultural supply chains, with sensor data and distributed ledgers converging to create continuous rather than point-in-time compliance evidence.
Portable mass spectrometry is collapsing the distinction between laboratory and field-based residue testing. Grain elevators and port terminals in Rotterdam and Hamburg are deploying handheld devices for same-day clearance decisions, compressing the traditional 72-hour laboratory turnaround into under four hours and eliminating demurrage costs for bulk commodity shipments.
EU Green Deal Farm-to-Fork Strategy mandates 50% reduction in chemical pesticide use by 2030, forcing testing laboratories to develop analytical panels for metabolite breakdown products rather than parent compounds alone. Specialty crop importers from Mediterranean sourcing regions face the steepest method recalibration burden as maximum residue limits tighten for legacy active ingredients.
Retailer-driven sustainability scorecards are fragmenting procurement specifications across European grocery chains. Danish and Swedish retail cooperatives now require separate carbon footprint verification alongside traditional safety certification, compelling food processors to contract with multiple specialized auditors rather than single-source full-service providers.
Testing, Inspection, and Certification for Agriculture & Food Market Segmentation
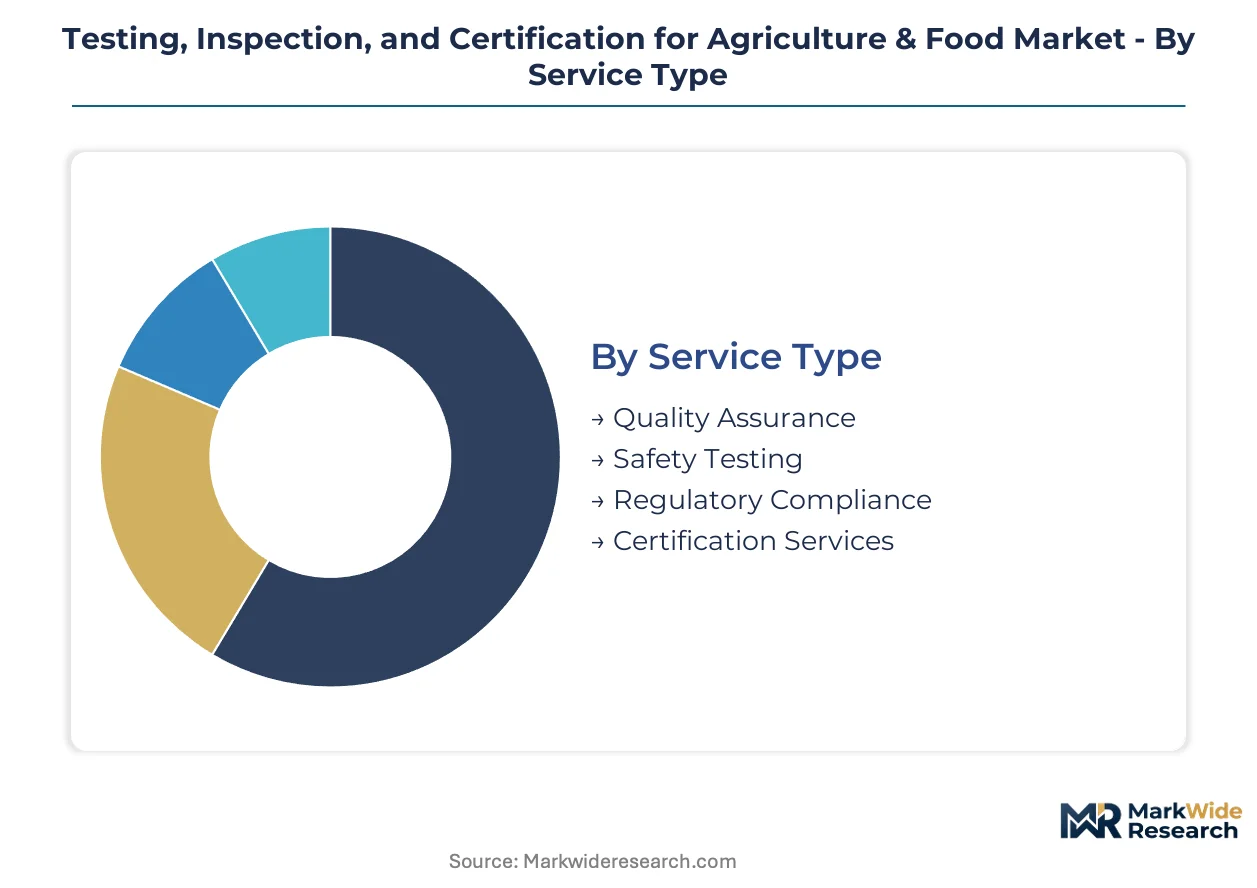
Segmentation in agricultural TIC services determines contract pricing, laboratory capital allocation, and auditor specialization. Each dimension—service tier, end-use vertical, technology platform, and certification standard—creates distinct margin profiles and competitive barriers.
Service Type:
Cost tier differentiation separates routine compliance work from premium advisory services, with pricing power concentrating at the upper end of technical complexity.
- Quality Assurance:Batch-release testing and process verification dominate revenue volume in food processing facilities. German dairy cooperatives sustain recurring contracts for mycotoxin screening at milk pooling stations.
- Safety Testing:Chromatography and mass spectrometry methods detect pesticide residues, heavy metals, and microbiological hazards. EU border inspection posts in Rotterdam and Hamburg compress turnaround times from days to hours under Green Deal mandates.
- Regulatory Compliance:Documentation audits verify adherence to REACH chemical registration and FDA preventive controls requirements.
- Certification Services:Third-party attestation of management systems and product claims enables market access to regulated jurisdictions.
Quality Assurance holds installed capacity. Safety Testing is rotating up the share rankings.
End Use Industry:
Application-specific testing protocols create divergent equipment and talent requirements across crop and livestock value chains.
- Food Processing:Continuous batch monitoring for chemical residues and authenticity markers. Facilities near Warsaw expand HACCP audit demand for Western European retail qualification.
- Agriculture:Pre-harvest testing of soil contaminants and grain moisture content at elevator networks.
- Dairy:Rapid pathogen detection and antibiotic residue screening in Bavaria and Lower Saxony pooling operations.
- Horticulture:Phytosanitary certification and pesticide metabolite analysis for Mediterranean specialty crop exporters.
Food Processing commands the largest contract values. Dairy is climbing the fastest on testing frequency metrics.
Technology:
Technology platform selection determines capital intensity, geographic reach, and data defensibility in contested procurement situations.
- Lab Analysis:High-resolution LC-MS/MS and genomic sequencing deliver definitive residue and pathogen identification. Seven-figure instrumentation costs and five-year depreciation cycles constrain mid-tier laboratory expansion.
- IoT Solutions:Real-time temperature and humidity sensors generate continuous cold-chain data streams requiring third-party validation for insurance purposes.
- Remote Sensing:Satellite and drone-based crop health monitoring supports precision agriculture compliance verification.
- Decentralized Testing:Handheld mass spectrometry devices at grain elevators collapse 72-hour laboratory turnaround into under four hours.
Lab Analysis anchors current revenue. IoT Solutions show the steepest expansion trajectory on sensor network deployment.
Certification Type:
Certification standard selection reflects buyer procurement specifications and regulatory jurisdiction requirements.
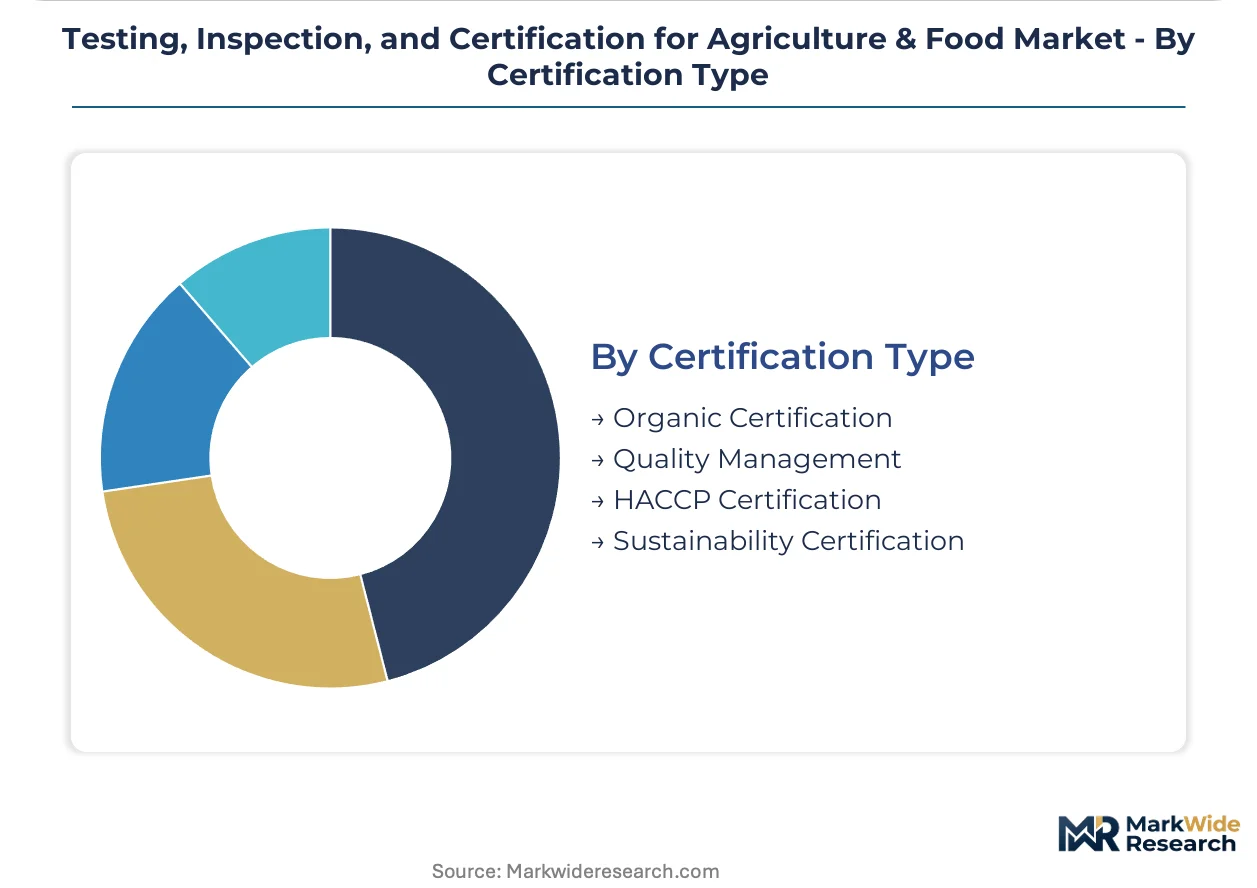
- HACCP Certification:Hazard-analysis-based preventive controls verification maintains mature demand in developed markets with established food safety frameworks.
- Sustainability Certification:Farm-level carbon accounting and scope-three emissions disclosure audits respond to EU CSRD mandates and retailer scorecard requirements.
- Organic Certification:Geographic origin and input verification through blockchain-enabled traceability systems.
- Quality Management:ISO-based system audits for operational consistency in multi-site processing operations.
HACCP Certification retains the largest certified facility base. Sustainability Certification is gaining share fastest on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Eastern European sourcing regions exhibit acute price sensitivity due to geographic distance from accredited laboratories, while German dairy cooperatives demonstrate low elasticity as regulatory mandates compel mandatory batch-level screening regardless of cost.
Germany
Bavarian and Lower Saxony milk pooling stations sustain Europe's densest concentration of mycotoxin screening contracts, with cooperatives mandating rapid-turnaround pathogen detection. ECHA's REACH substance evaluation list drives metabolite verification demand at specialized residue laboratories. Hamburg port terminals deploy handheld mass spectrometry devices to compress grain clearance from 72 hours to under four hours.
Netherlands
Rotterdam's border inspection posts face compressed turnaround mandates under EU Green Deal residue limits, forcing laboratories to triple testing frequencies. EFSA tightening of maximum residue limits for legacy pesticides expands analytical panel requirements for Mediterranean produce transshipments. Wageningen agricultural research clusters anchor method development for novel pesticide metabolite detection.
France
Specialty crop importers from Mediterranean sourcing corridors bear the steepest method recalibration burden as ANSM enforces stricter legacy active ingredient thresholds. Paris Basin grain elevators integrate IoT sensor networks for continuous cold-chain validation. Lyon-based laboratories concentrate genomic sequencing capacity for pathogen identification in dairy export certification.
Poland
Meat and dairy processing facilities near Warsaw generate underpenetrated demand for HACCP audit services as operators seek Western European retail qualification. The country's national food safety regulator implements GB-aligned standards that converge with EU hazard-analysis frameworks. Masovian Voivodeship processing corridors attract certification body expansion to capture export-oriented contract volume.
United States
Midwest grain elevators adopt portable mass spectrometry to eliminate demurrage costs on bulk commodity shipments awaiting laboratory clearance. FDA enforcement of Food Safety Modernization Act preventive controls elevates third-party audit demand at multi-site processing operations. California's specialty crop exporters face dual compliance overhead from state-level pesticide regulations and buyer-specific residue protocols.
Testing, Inspection, and Certification for Agriculture & Food Market Competitive Landscape
Full-service multinationals and specialized regional laboratories split the market along capability-depth and geographic-coverage vectors. Consolidation pressures concentrate accredited pesticide residue capacity in Germany, Netherlands, and France, while mid-tier players face capital constraints from seven-figure LC-MS/MS instrumentation requirements. Two strategic archetypes dominate: global laboratory networks leveraging cross-border method standardization, and boutique specialists anchoring single-corridor relationships through mycotoxin or genomic sequencing depth. Dominant competitive moves include strategic partnerships for blockchain-enabled traceability integration and geographic expansion into underpenetrated Eastern European processing corridors.
Within the full-service tier, SGS leverages its laboratory footprint to capture high-value residue contracts, while Bureau Veritas anchors grain-import corridor positioning through specialized analytical capabilities. Eurofins Scientific exemplifies the technology-differentiation archetype via genomic sequencing methods. Among these, SGS and Bureau Veritas occupy positions reflecting scale-driven coverage models, whereas Eurofins Scientific represents premium-tier positioning through accelerated pathogen identification timelines.
| Leading Market Players |
|---|
| Eurofins Scientific |
| DEKRA |
| SGS |
| ALS Limited |
| DNV |
| Bureau Veritas |
| TÜV SÜD |
| AsureQuality |
| Intertek Group |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Hamburg grain corridor freight costs concentrate accredited laboratory capacity in Germany and the Netherlands, forcing Eastern European processors to absorb premium logistics surcharges or accept extended turnaround times that compress their pricing power against Western European buyers.
Pricing Analysis
After-sales service contracts and multi-year certification subscriptions drive lifetime value beyond initial testing fees. Three-tier pricing structure across premium genomic sequencing, standard chromatography panels, and economy rapid-test tiers separates SGS and Eurofins from mid-tier regional laboratories. Cost compression in standard pesticide residue screening is intensifying because portable mass spectrometry devices eliminate demurrage-driven urgency premiums. Polish meat processors exhibit acute price sensitivity due to distance from accredited capacity, while Bavarian dairy cooperatives show low elasticity under mandatory batch-release obligations.
Supply Chain Analysis
Contract laboratory capacity concentrates at SGS, Bureau Veritas, and Eurofins facilities in Germany, the Netherlands, and France. High-resolution LC-MS/MS instrumentation, certified reference materials, and bioinformatics talent pools draw from Swiss, German, and US supplier networks. Single-source vulnerability runs through German mycotoxin screening hubs serving pan-European dairy cooperatives. Distribution runs through port-terminal laboratories at Rotterdam and Hamburg for import clearance, with satellite collection points in Warsaw and Prague for Eastern European sample logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Testing, Inspection, and Certification for Agriculture & Food Market functions as a service-attach opportunity where recurring certification subscriptions and real-time IoT validation contracts expand faster than capital-intensive laboratory hardware sales.
For Market Incumbents: Insulate core residue testing margins by embedding IoT sensor validation into long-term cold-chain service contracts, and secure backward integration into certified reference material production to neutralize supply bottlenecks for novel pesticide metabolite standards. Portable mass spectrometry entrants threaten point-in-time laboratory revenue. For New Entrants and Emerging Players: Build out HACCP audit capacity in Poland's Masovian Voivodeship meat and dairy processing corridor, where Western European retail qualification demand outpaces accredited local supply. Blockchain-enabled organic traceability verification offers a differentiated go-to-market angle against established full-service incumbents. For Investors and Strategic Acquirers: Boutique genomic sequencing specialists with food microbiology cross-training capabilities command scarcity premiums as pathogen identification timelines compress under EU Green Deal enforcement. Monitor ECHA substance evaluation list expansions as inflection indicators for metabolite testing contract volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Enabled Traceability Integration | Converges distributed ledger verification with traditional certification for premium organic segments. |
| Portable Mass Spectrometry Deployment | Collapses 72-hour laboratory turnaround to under four hours at Rotterdam and Hamburg terminals. |
| Genomic Sequencing Capability Acquisition | Accelerates pathogen identification timelines for dairy export certification under EFSA requirements. |
| Eastern European Laboratory Expansion | Captures underpenetrated Polish processing corridor demand for Western European retail qualification. |
| Reference Material Production Integration | Secures captive supply of certified analytical standards for novel pesticide metabolite detection. |
Research Methodology
The analysis maps pesticide residue testing, mycotoxin screening, pathogen identification, and sustainability certification verticals, each validated through laboratory operations directors, food safety compliance officers, dairy cooperative procurement managers, and third-party auditor field teams. Primary interview findings triangulate against ECHA substance evaluation databases, EU border inspection post clearance records, FDA FSMA enforcement reports, and German dairy cooperative annual disclosures. Bottom-up contract volume estimates reconcile with top-down market sizing across service type, technology platform, and certification standard dimensions.
Baseline assumptions hold EU Green Deal residue limit trajectories and REACH chemical registration timelines fixed across the projection horizon, with scenario variants testing accelerated metabolite panel expansion and delayed reference material availability. Segmentation modeling spans service tier complexity, end-use vertical equipment requirements, technology platform capital intensity, and certification standard jurisdictional coverage. CAGRs derive from laboratory capacity deployment schedules, regulatory mandate implementation calendars, and sensor network installation trajectories.
Stress conditions across reference material production bottlenecks, genomic sequencing talent availability, and multi-jurisdiction digital traceability divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume continued ECHA substance evaluation expansion and sustained FDA FSMA preventive controls enforcement. Quarterly review of ECHA candidate list additions, EU member state digital mandate harmonization progress, and portable mass spectrometry adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Soil Sampling Services Market
Agricultural Testing Services
Soil Erosion Testing Market
Agricultural Testing Services
Poultry Diagnostic Testing Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Animal Feed Testing Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Asia Pacific Feed Testing Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Global Agriculture Testing Services Market
Agricultural Testing Services
Impact Soil Tester Market