
 Automation Control Components and Devices Market | 2026-2036
Automation Control Components and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Automation Control Components and Devices Market Analysis
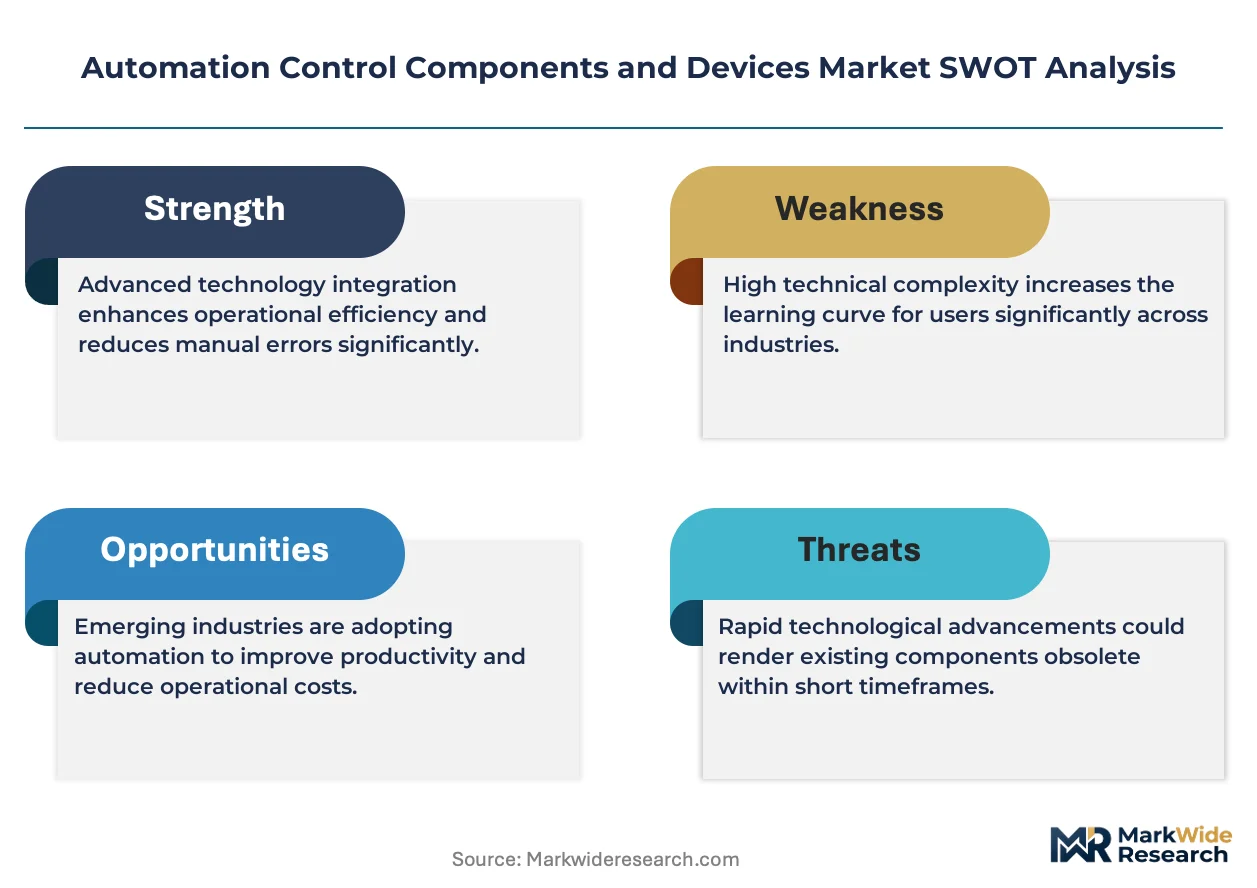
Silicon carbide is restructuring power electronics economics across motor drives and inverters, cutting switching losses and thermal management costs. Siemens leverages its captive semiconductor supply to dominate high-performance drive architectures. ABB sustains technology leadership through deep specialization in synchronous motor control algorithms. Rockwell Automation anchors its position in North American discrete manufacturing through tight channel control over system integrator networks.
Automation control components and devices encompass electromechanical and electronic apparatus—relays rated for 10A to 100A switching currents, contactors with AC-3 duty classifications, inductive and photoelectric sensors, and pneumatic or electric actuators—that execute, monitor, and regulate machine processes in industrial environments. These elements form the physical layer of factory automation, translating digital commands into mechanical action while feeding operational data back to supervisory systems. The technology dimension shows Programmable Logic Controllers retaining the largest installed base, while Distributed Control Systems command the highest margin pools in continuous process industries. Sensors represent the fastest-expanding product category, driven by predictive maintenance mandates and edge-computing architectures that require dense field-level data acquisition.
The EU AI Act and Machinery Directive are tightening conformity requirements for autonomous control systems, forcing redesigns of safety-critical logic modules. In the United States, OSHA lockout-tagout rules and FCC emissions standards for industrial wireless equipment shape product certification pathways. China's GB standards and MIIT cybersecurity regulations for industrial control systems add compliance layers for equipment sold into domestic smart factory programs. Stakeholders must weigh certification portfolio breadth against the engineering cost of region-specific safety architectures.
Market Dynamics
The EU AI Act and Machinery Directive are forcing redesigns of safety-critical logic modules across European installations, while semiconductor supply concentration in South Korea and Taiwan creates chokepoints for advanced drive architectures.
Growth Catalysts
- Semiconductor Fab Expansion:South Korean and Taiwanese semiconductor manufacturers are scaling automation footprints to sustain yield targets, pulling demand for precision motion control and vacuum-compatible actuators.
- EU AI Act Conformity Mandates:The EU AI Act's risk-classification framework for autonomous systems is compelling industrial OEMs to upgrade safety-rated PLCs and redundant sensor arrays.
- Silicon Carbide Adoption:Silicon carbide power devices are cutting switching losses in motor drives, enabling higher-frequency control loops that improve positioning accuracy in robotics.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings from Chinese export controls are compressing margins for servo motor manufacturers dependent on high-performance permanent magnets.
- Foundry Capacity Concentration:Advanced node semiconductor fabrication for industrial ASICs concentrates in Taiwan, exposing automation component supply to single-point geopolitical risk.
- Legacy Fieldbus Entrenchment:Profibus and DeviceNet installed bases in brownfield plants create switching costs that slow Ethernet-IP and Profinet migration timelines.
Strategic Opportunities
- India Manufacturing Incentives:India's PLI scheme for industrial automation is attracting component assembly investments to serve domestic smart factory programs and export markets.
- Edge-AI Sensor Fusion:Convergence of time-of-flight vision sensors with vibration analysis algorithms is opening predictive maintenance contracts in chemical processing.
- Battery Gigafactory Buildouts:European and North American lithium-ion cell manufacturing expansions require explosion-proof actuators and cleanroom-rated motion systems with limited incumbent suppliers.
Industry Challenges
- Functional Safety Engineering Scarcity:TUV-certified safety system designers are in short supply relative to demand for SIL-3 and PLe-rated machinery redesigns.
- Multi-Standard Certification Burden:Simultaneous UL, CE, and CCC approval timelines for control cabinets stretch 14-18 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automation Control Components and Devices Market |
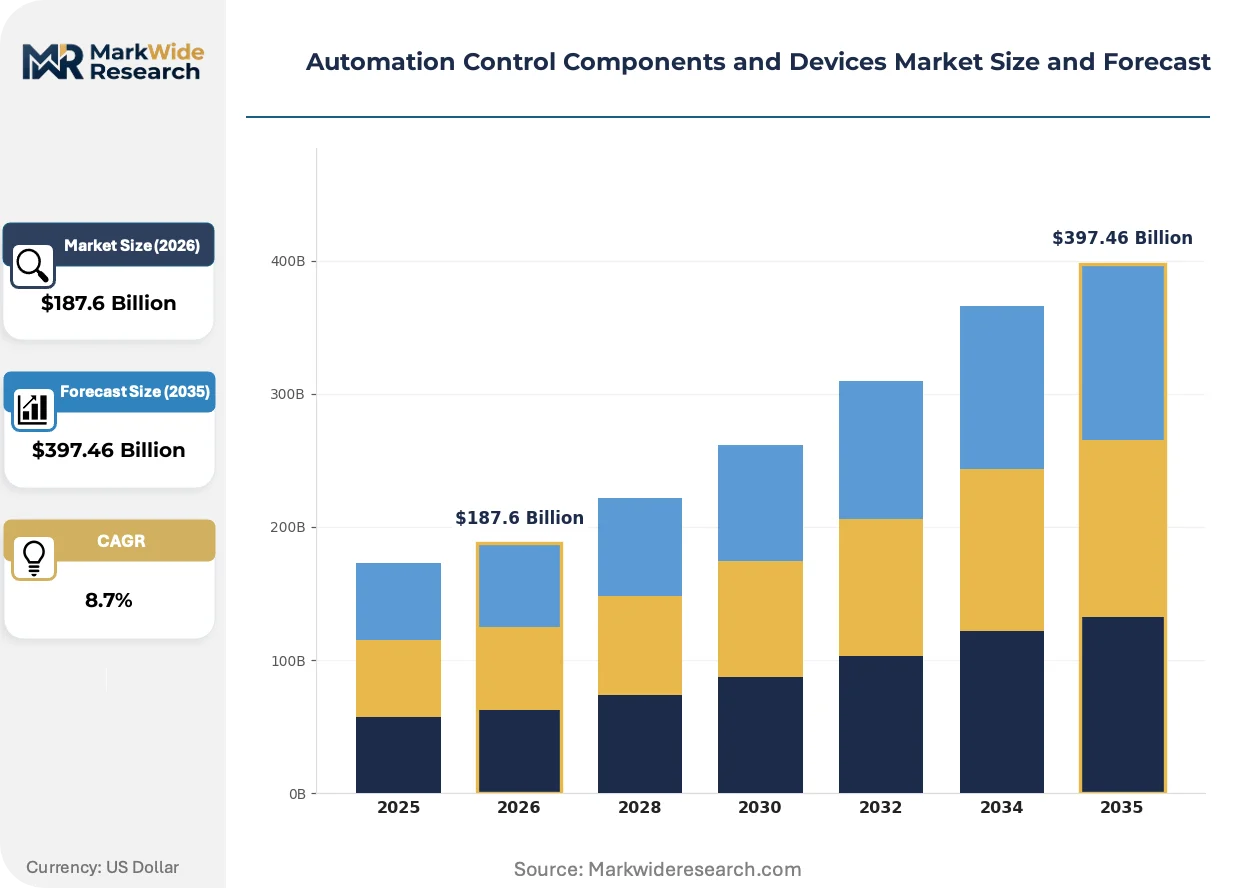
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Relays, Contactors, Sensors, Actuators Technology: Programmable Logic Controllers, Distributed Control Systems, Supervisory Control And Data Acquisition, Human Machine Interface End User: Manufacturing, Oil & Gas, Pharmaceuticals, Food & Beverage Installation: Panel Mounted, Rack Mounted, DIN Rail Mounted, Surface Mounted |
| Companies Covered | FANUC, Emerson, Siemens, Yaskawa Electric, Honeywell, ABB, Schneider Electric, Mitsubishi Electric, Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automation Control Components and Devices Market Emerging Trajectories
Digital twin architectures are compressing commissioning cycles for complex motion systems, while software-defined safety functions are decoupling hardware from certification timelines.
Time-sensitive networking over standard Ethernet is automating deterministic control loops previously requiring dedicated fieldbus hardware. Automotive battery manufacturers in Germany's industrial corridor are deploying TSN-enabled servo drives to synchronize coating and winding operations with microsecond precision. This convergence is collapsing the traditional separation between IT infrastructure and OT control layers.
The EU Machinery Directive's 2023 update tightens requirements for autonomous mobile robot safety validation, forcing recertification of collaborative robot installations. German automotive OEMs are responding by embedding safety-rated torque sensors directly into joint actuators rather than relying on external guarding. This regulatory pressure is accelerating modular safety component sales across European assembly operations.
System integrators are unbundling hardware supply from engineering services, selling control architectures as subscription-based performance contracts. North American discrete manufacturers are adopting this model for packaging line retrofits, paying per unit of throughput rather than capitalizing equipment. The shift is most visible in food and beverage processing, where seasonal volume swings favor operational expenditure structures.
Automation Control Components and Devices Market Segmentation
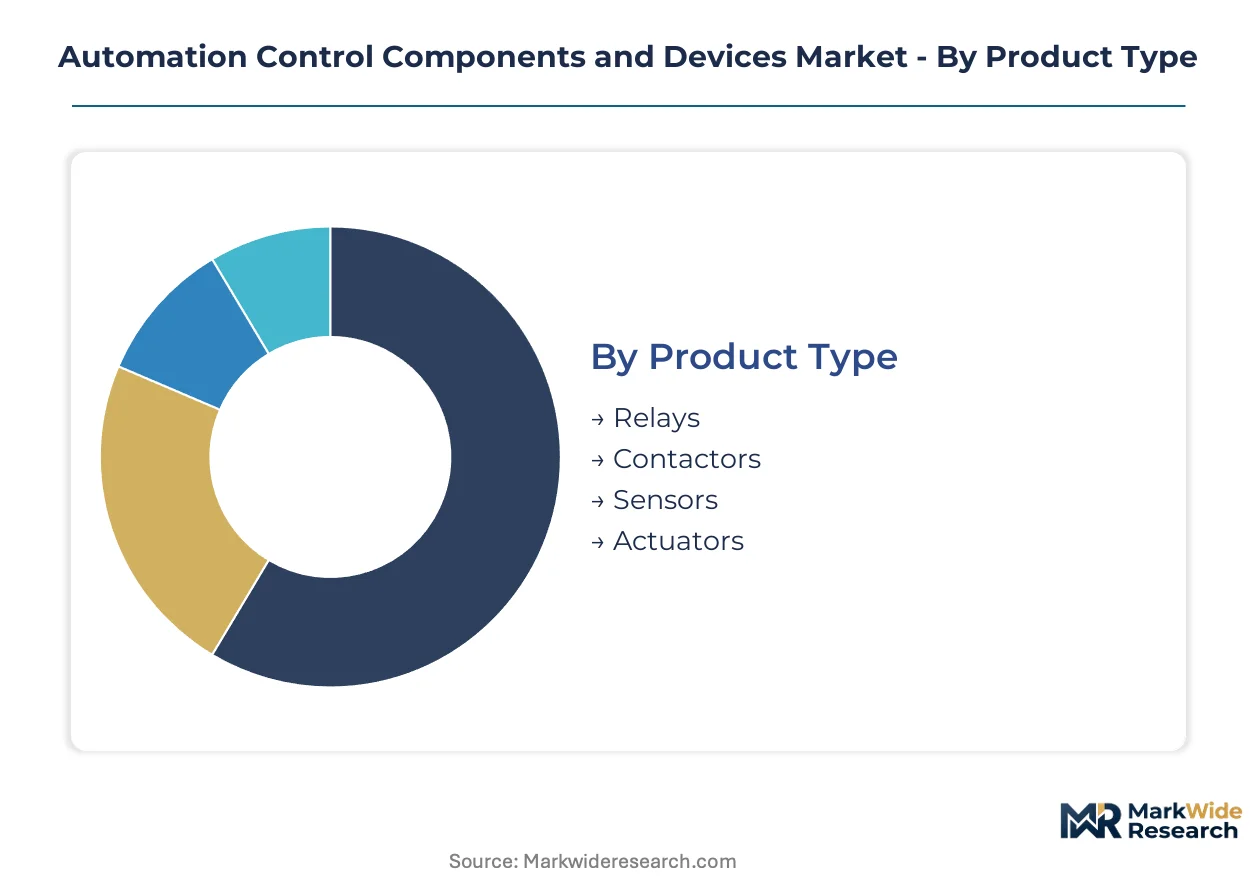
Segmentation in automation control components reveals how technical specifications, deployment environments, and regulatory requirements reshape procurement patterns across industrial verticals. Buyers prioritize different performance thresholds depending on whether they operate continuous process plants or discrete assembly operations.
Product Type:
Cost tier separates commodity electromechanical components from precision sensing and motion systems requiring advanced semiconductor content.
- Relays:Electromechanical switching devices rated for 10A to 100A currents, with coil voltages spanning 24VDC to 480VAC. German automotive OEMs specify force-guided safety relays for assembly line retrofits to satisfy EU Machinery Directive conformity requirements.
- Sensors:Inductive, photoelectric, and time-of-flight devices converting physical parameters into process signals. Semiconductor fabs in South Korea and Taiwan deploy vacuum-compatible proximity sensors to sustain yield targets in lithography equipment.
- Contactors:AC-3 duty classified switching equipment for motor control circuits. IEC 60947-4-1 certification dominates procurement specifications for heavy industrial applications.
- Actuators:Pneumatic cylinders and electric servo motors executing mechanical motion from control signals. Cleanroom-rated linear actuators face supply constraints from limited incumbent suppliers serving battery gigafactory buildouts.
Volume sits with relays and contactors; growth tilts toward sensors.
Technology:
Application criticality determines whether buyers prioritize deterministic real-time control or distributed architectures spanning geographically dispersed assets.
- Programmable Logic Controllers:Ruggedized industrial computers executing ladder logic for discrete manufacturing sequences. The largest installed base resides in North American automotive and packaging operations where legacy fieldbus entrenchment slows Ethernet-IP migration.
- Distributed Control Systems:Hierarchical architectures managing continuous processes through redundant controller networks. Chemical processing and oil & gas operations in Germany's industrial corridor generate the highest margin pools due to safety-critical certification requirements.
- Supervisory Control And Data Acquisition:Software platforms aggregating field-level data for centralized monitoring. Water treatment and power distribution utilities specify SCADA with IEC 62443 cybersecurity compliance.
- Human Machine Interface:Touch panels and industrial PCs enabling operator interaction with control systems. Food and beverage processors favor IP69K-rated HMIs for washdown environments.
Installed base concentrates in PLCs; expansion tilts toward DCS upgrades in process industries.
End User:
Margin structure varies sharply between regulated life sciences and price-sensitive discrete manufacturing.
- Manufacturing:Automotive, electronics assembly, and packaging operations requiring high-speed synchronized motion. Battery cell manufacturers in Germany deploy explosion-proof actuators for coating and winding operations.
- Pharmaceuticals:Batch processing and aseptic filling operations governed by FDA 21 CFR Part 11 and EMA GMP Annex 15. Validated control systems command 40-60% price premiums over standard industrial configurations.
- Oil & Gas:Upstream drilling and downstream refining with SIL-rated safety instrumented systems. Offshore platforms specify corrosion-resistant enclosures meeting ATEX and IECEx hazardous area standards.
- Food & Beverage:Hygienic processing equipment with stainless steel construction and CIP-cleanable designs. Seasonal volume swings favor subscription-based performance contracts over capital expenditure structures.
Revenue concentrates in manufacturing; steepest expansion trajectory appears in pharmaceuticals.
Installation:
Physical mounting method dictates enclosure ratings, thermal management, and maintenance accessibility in crowded electrical rooms.
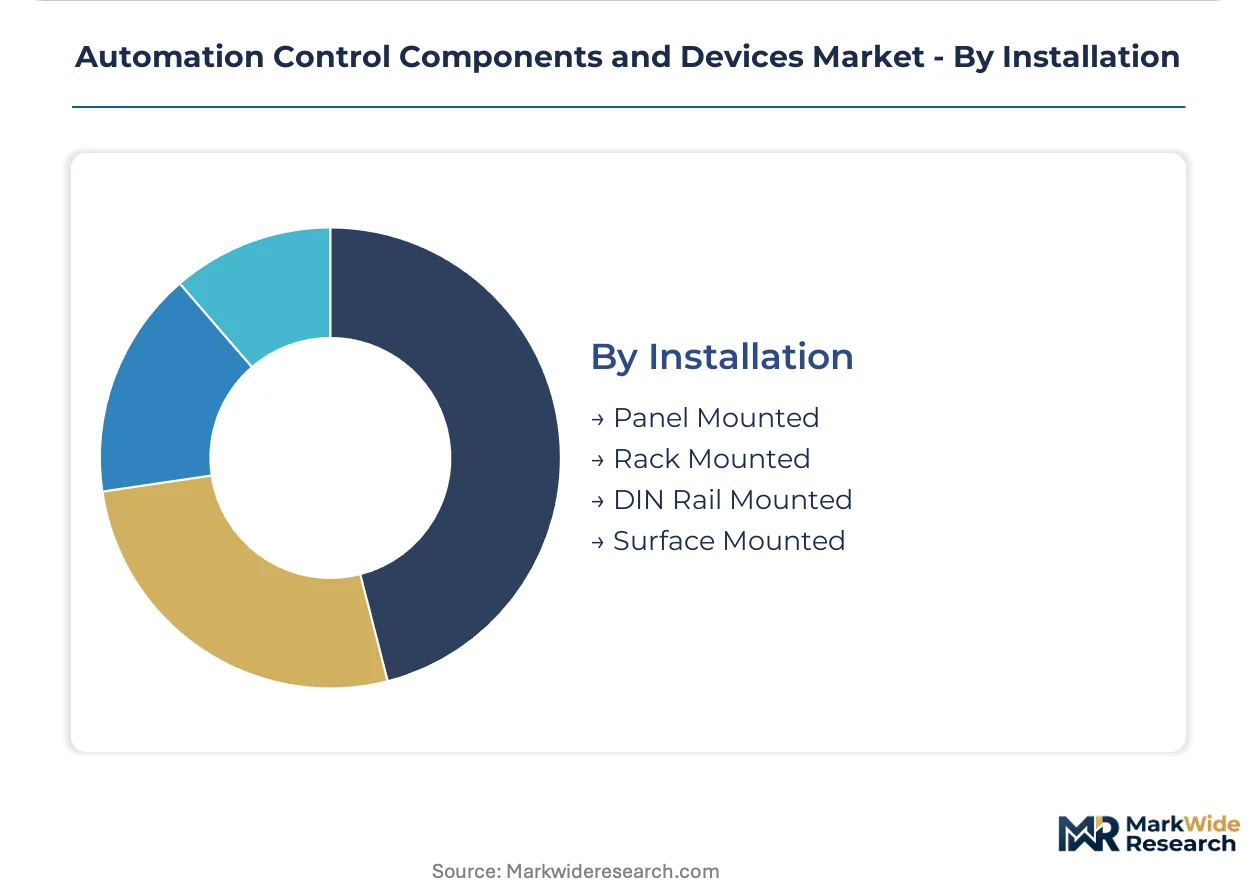
- DIN Rail Mounted:Standardized 35mm rail systems enabling rapid component replacement in control cabinets. European machine builders prefer this topology for modular safety component architectures.
- Panel Mounted:Direct attachment to custom electrical enclosures for integrated HMI and controller assemblies. North American system integrators specify NEMA 4X stainless steel panels for food processing environments.
- Rack Mounted:19-inch industrial chassis housing high-density I/O modules in data center-style configurations. Edge-computing architectures favor rack-mounted PLCs with TSN-enabled Ethernet backplanes.
- Surface Mounted:Direct wall or machine-frame attachment for distributed I/O nodes in sprawling process plants. Oil and gas facilities deploy surface-mounted junction boxes with explosion-proof conduit seals.
Volume sits with DIN rail; growth tilts toward rack-mounted edge controllers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly in Germany's industrial corridor, where automotive OEMs retrofit legacy assembly lines with networked sensor-actuator arrays. Semiconductor fabs in South Korea and Taiwan are expanding automation footprints to sustain yield targets. Regulatory divergence across major economies is fragmenting certification requirements for safety-critical control systems.
Germany
Automotive battery manufacturers deploy explosion-proof actuators for coating and winding operations in Baden-Württemberg and Bavaria. The EU Machinery Directive's 2023 update forces recertification of collaborative robot installations. Stuttgart-based OEMs embed safety-rated torque sensors directly into joint actuators rather than relying on external guarding.
United States
North American discrete manufacturers adopt subscription-based performance contracts for packaging line retrofits. OSHA lockout-tagout rules and FCC emissions standards for industrial wireless equipment shape product certification pathways. System integrators in Michigan and Ohio unbundle hardware supply from engineering services, selling control architectures as operational expenditure structures.
South Korea
Semiconductor manufacturers scale automation footprints to sustain yield targets, pulling demand for precision motion control and vacuum-compatible actuators. The country's national industrial regulator enforces cybersecurity standards for smart factory programs. Samsung and SK Hynix facilities in Gyeonggi Province drive dense field-level data acquisition through edge-computing architectures.
China
GB standards and MIIT cybersecurity regulations for industrial control systems add compliance layers for equipment sold into domestic smart factory programs. Battery gigafactory buildouts in Jiangsu and Fujian require cleanroom-rated motion systems with limited incumbent suppliers. State-backed semiconductor localization targets reduce dependence on Taiwanese foundry capacity for industrial ASICs.
India
The PLI scheme for industrial automation attracts component assembly investments to serve domestic smart factory programs and export markets. Maharashtra and Gujarat host expanding facilities for relay and contactor manufacturing. Food and beverage processors in Haryana favor IP69K-rated HMIs for washdown environments amid seasonal volume swings.
Automation Control Components and Devices Market Vendor Landscape
Capacity expansion dominates the current landscape as foundry constraints expose supply vulnerabilities. The vendor base organizes into three tiers: diversified conglomerates with captive semiconductor supply, specialized motion control houses with algorithmic differentiation, and regional system integrators with channel control over discrete manufacturing. Strategic archetypes include vertical integrators securing upstream component access, safety specialists capturing premium margins from EU regulatory mandates, and service-oriented players monetizing throughput-based contracts. M&A activity and strategic partnerships concentrate around edge-AI sensor fusion capabilities and TSN-enabled drive architectures.
Among diversified industrial conglomerates, Siemens and ABB exemplify distinct strategic postures. Siemens leverages its captive semiconductor supply to dominate high-performance drive architectures, while ABB sustains technology leadership through deep specialization in synchronous motor control algorithms. Rockwell Automation anchors the North American discrete manufacturing tier through tight channel control over system integrator networks. Japanese specialists FANUC, Yaskawa Electric, and Mitsubishi Electric occupy positions in precision motion control, with FANUC representing the robotics-integrated control archetype and Yaskawa exemplifying servo system density in semiconductor manufacturing environments.
| Leading Market Players |
|---|
| FANUC |
| Emerson |
| Siemens |
| Yaskawa Electric |
| Honeywell |
| ABB |
| Schneider Electric |
| Mitsubishi Electric |
| Rockwell Automation |
| Others |
Supply Flow & Price Mechanics
Neodymium and dysprosium price indices from Chinese export controls cascade through servo motor supply chains into three-tier pricing structure across premium, standard, and economy levels. Rare earth magnet volatility compresses margins for manufacturers dependent on high-performance permanent magnets while forcing buyers toward alternative magnetic materials or redesigned motor topologies.
Pricing Analysis
Volume concentrates in commodity relays and contactors where price differentiation hinges on IEC certification grade and volume scale; premium tiers capture safety-rated PLCs and redundant sensor arrays serving EU AI Act mandates. Pricing pressure stems from foundry capacity concentration in Taiwan exposing automation component supply to single-point geopolitical risk. Automotive OEMs in Germany's industrial corridor show least price sensitivity for SIL-3 certified safety modules, while packaging line operators in North America prioritize operational expenditure structures over capital equipment.
Supply Chain Analysis
Container freight rates from Asia to Europe and North America directly impact landed costs for DIN rail-mounted components and rack-mounted edge controllers. Advanced node semiconductor fabrication for industrial ASICs centers on Taiwan, South Korea, and select US facilities, drawing from silicon carbide substrates, rare earth magnets, and precision-machined aluminum enclosures. Single-source vulnerability in Taiwanese foundry capacity creates chokepoints for drive architectures. Distribution runs through authorized distributor networks and system integrator channels rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automation control components market sits in a technology-transition phase as time-sensitive networking over standard Ethernet displaces legacy Profibus and DeviceNet fieldbus architectures. This protocol convergence collapses traditional IT-OT boundaries and reshapes competitive positioning.
For Market Incumbents: Cement technology leadership through captive semiconductor supply securing high-performance drive architectures against Taiwanese foundry chokepoints. Deepen algorithmic specialization in synchronous motor control to defend margin pools from emerging motion control houses. Prioritize TUV-certified safety system design capabilities to capture EU Machinery Directive upgrade cycles.
For New Entrants and Emerging Players: Begin with edge-AI sensor fusion capabilities targeting predictive maintenance contracts in chemical processing where incumbent coverage remains thin. India's PLI scheme for industrial automation offers the most penetrable geography for component assembly investments serving domestic smart factory programs. Pursue subscription-based performance contracts unbundling hardware from engineering services to bypass capital expenditure barriers in food and beverage processing.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized motion control houses with algorithmic differentiation in South Korea and Taiwan where semiconductor fab automation demand sustains yield-target pull. Long-term viability over the projection horizon rests on edge-computing architecture adoption and TSN-enabled drive penetration. Watch battery gigafactory buildout pace in Europe and North America as inflection indicator for explosion-proof actuator demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Supply | Siemens leverages captive chip production to dominate high-performance drive architectures and bypass Taiwanese foundry constraints. |
| TSN-Enabled Drive Architecture Deployment | Automotive battery manufacturers in Germany synchronize coating operations with microsecond precision over standard Ethernet infrastructure. |
| Safety-Rated Sensor Embedding | Stuttgart-based OEMs embed torque sensors directly into joint actuators to satisfy EU Machinery Directive recertification mandates. |
| Subscription-Based Performance Contracting | North American system integrators monetize packaging line throughput rather than capitalized equipment in seasonal food processing. |
| Edge-AI Sensor Fusion Capability Buildout | Convergence of time-of-flight vision with vibration analysis opens predictive maintenance contracts in chemical processing operations. |
Methodological Framework
Independent corroboration across plant engineers at automotive OEMs, procurement leads at battery manufacturers, and aftermarket service heads at system integrator networks underwrites the qualitative findings. Primary interviews with maintenance directors, OEM procurement teams, and technical R&D directors at relay and contactor manufacturers combined with secondary validation from SEC filings, customs and trade data, and IEC certification databases. Bottom-up component demand modeling and top-down industrial automation spending analysis triangulate volume estimates.
Comparable historical periods across the projection horizon anchor growth assumptions to verified installation bases and replacement cycles. Segmentation dimensions modeled include product type, technology architecture, end-use vertical, and installation topology alongside regional regulatory cluster differentiation. CAGRs derive from installed base evolution, technology substitution rates, and compliance-driven upgrade timelines. Forecast inputs incorporate silicon carbide adoption curves, EU AI Act implementation phases, and rare earth magnet price volatility scenarios.
Underlying measurement precision varies by segment; sensors and edge controllers carry tighter precision than commodity electromechanical components given denser data availability. Forecasts reflect assumptions about TSN migration speed, foundry capacity expansion, and regulatory harmonization timelines. Stakeholders should weight assumptions against their own operating context and supply chain exposure to Taiwanese semiconductor fabrication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Smart Temperature Management Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Temperature Monitoring Devices Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
Force Sensor Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
Robotic Sensors Market