
 Miso Market | 2026-2036
Miso Market Size, Share, and Industry Trends Forecast 2026-2036
Miso Market Outlook
Multi-source koji supply is shifting toward vertically integrated in-house cultivation among large miso manufacturers. Marukome Co., Ltd. leverages captive rice-koji operations to stabilize raw material costs across seasonal swings. Hatcho Miso Co., Ltd. sustains its position through soybean-only fermentation protocols that differentiate its product in premium channels. Eden Foods Inc. competes in North American retail by emphasizing organic certification and domestic production scale.
Miso is a fermented soybean paste produced through koji mold inoculation of steamed grains, followed by months-long aging in cedar vats or temperature-controlled steel tanks; the finished product delivers umami depth, preservative-free shelf stability, and probiotic content for culinary and nutritional applications. White miso commands premium positioning in restaurant sauces and dressings due to shorter fermentation cycles and sweeter flavor profiles that appeal to Western palates. Food manufacturers represent the fastest-growing end user segment as packaged soup, sauce, and ready-meal brands seek clean-label umami sources to replace synthetic flavor enhancers.
Japan's Ministry of Health, Labour and Welfare enforces Food Sanitation Act standards that govern koji starter purity and fermentation facility hygiene, while CODEX Alimentarius guidelines on fermented soybean products shape import acceptance criteria for European and North American regulators. The US FDA classifies miso under fermented food safety protocols that require acidification monitoring and pathogen control plans for domestic producers. Stakeholders must monitor evolving probiotic health claims regulations and carbon accounting requirements for long-fermentation processes that extend production cycles and energy consumption.
Market Dynamics
Long-fermentation miso production is absorbing intensifying energy cost pressure as Japanese manufacturers retrofit cedar vat facilities with solar thermal systems and biomass boilers to preserve traditional aging protocols without carbon penalty exposure.
Growth Catalysts
- Clean-label reformulation mandates:Packaged food manufacturers across Germany and France are replacing synthetic MSG with koji-derived umami sources to meet EFSA guidance on additive reduction in processed foods.
- Probiotic positioning:Japan's Food Sanitation Act now permits qualified fermentation health claims on retail packaging, opening pharmacy and wellness channel access previously restricted to supplements.
- Restaurant menu expansion:North American fine-dining establishments are deploying white miso in butter emulsions and caramel applications, creating volume pull independent of traditional soup bases.
Market Restraints
- Soybean input volatility:Brazilian drought cycles and Argentine export taxes are compressing margin predictability for non-vertically integrated producers dependent on spot commodity purchases.
- Koji starter supply concentration:Domestic Japanese koji mold culture banks control access to authenticated Aspergillus oryzae strains, creating licensing bottlenecks for new market entrants in Europe and North America.
- Fermentation facility capital intensity:Temperature-controlled steel tank installations and HACCP-compliant aging rooms require seven-figure capex commitments that deter mid-scale capacity expansion.
Strategic Opportunities
- Ready-meal channel penetration:UK and Netherlands supermarket private-label ranges are introducing miso-glazed protein and noodle bowl formats, creating branded ingredient supply contracts.
- Carbon accounting differentiation:Producers documenting fermentation energy use and cedar vat forestry sourcing can access EU Green Deal-aligned procurement preferences from sustainability-focused foodservice distributors.
- Non-soy substrate development:Chickpea and fava bean koji fermentation protocols are expanding allergen-free positioning for North American retail shelves restricted by soy sensitivity prevalence.
Industry Challenges
- Master brewer talent scarcity:Traditional toji expertise in multi-month fermentation monitoring is concentrating among aging practitioners in Nagano Prefecture without structured apprenticeship pipelines.
- Cross-border certification timelines:US FDA acidification monitoring protocols and state-level cottage food exemptions create fragmented compliance burdens for artisanal exporters seeking direct-to-consumer channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Miso Market |
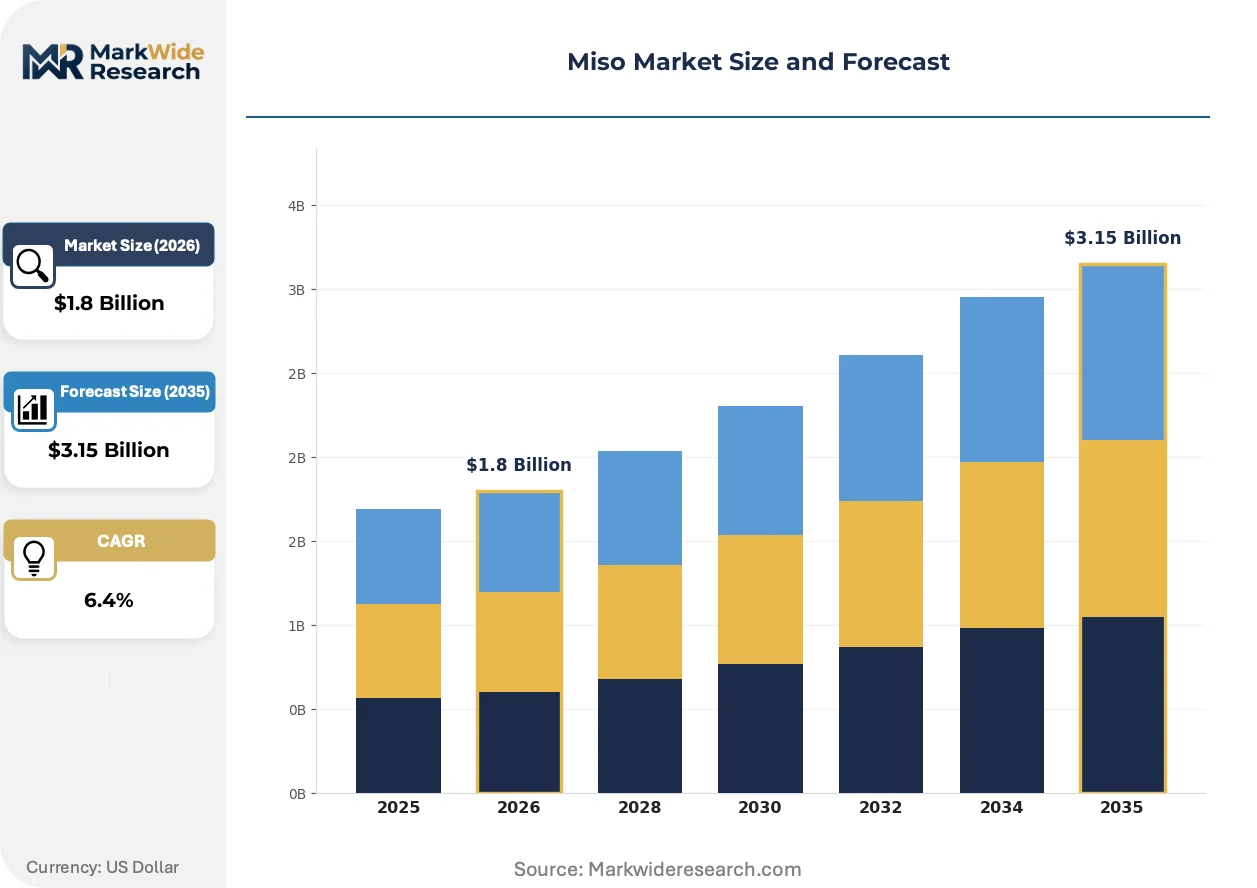
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Miso, White Miso, Mixed Miso, Barley Miso End User: Restaurants, Retail, Food Manufacturers, Households Packaging Type: Bottles, Tubs, Sachets, Jars Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Marusan-Ai Co., Ltd., Eden Foods Inc., Marukome Co., Ltd., Hatcho Miso Co., Ltd., Miyasaka Brewing Company, Ltd., Hikari Miso Co., Ltd., Yamato Soysauce & Miso Co., Ltd., Takeya Miso Co., Ltd., Kikkoman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Miso Market Strategic Shifts
Automation is penetrating koji cultivation rooms without displacing sensory judgment, as optical sensors and IoT humidity controls augment rather than replace human oversight of mold propagation cycles.
Controlled-environment koji cultivation is absorbing capital investment from large manufacturers seeking batch consistency. Marukome and regional competitors are retrofitting rice-koji rooms with automated temperature ramping systems. This technology is absorbing variability that previously required experienced toji intervention, compressing training timelines while preserving output quality.
Japan's Ministry of Health, Labour and Welfare is tightening Food Sanitation Act enforcement on fermentation facility hygiene documentation, requiring digital traceability for koji starter provenance. Domestic producers are responding by integrating blockchain-enabled batch records. Premium export channels to Switzerland and Australia are most affected, as these jurisdictions reference Japanese regulatory alignment for import acceptance.
Direct procurement relationships between miso manufacturers and restaurant groups are displacing traditional distributor intermediaries in North American urban markets. Chef-owners in Los Angeles and New York are contracting dedicated fermentation runs with specified aging duration. This pattern is most visible in the fine-casual segment, where menu differentiation depends on exclusive flavor profiles unavailable through broadline distribution.
Miso Market Segmentation
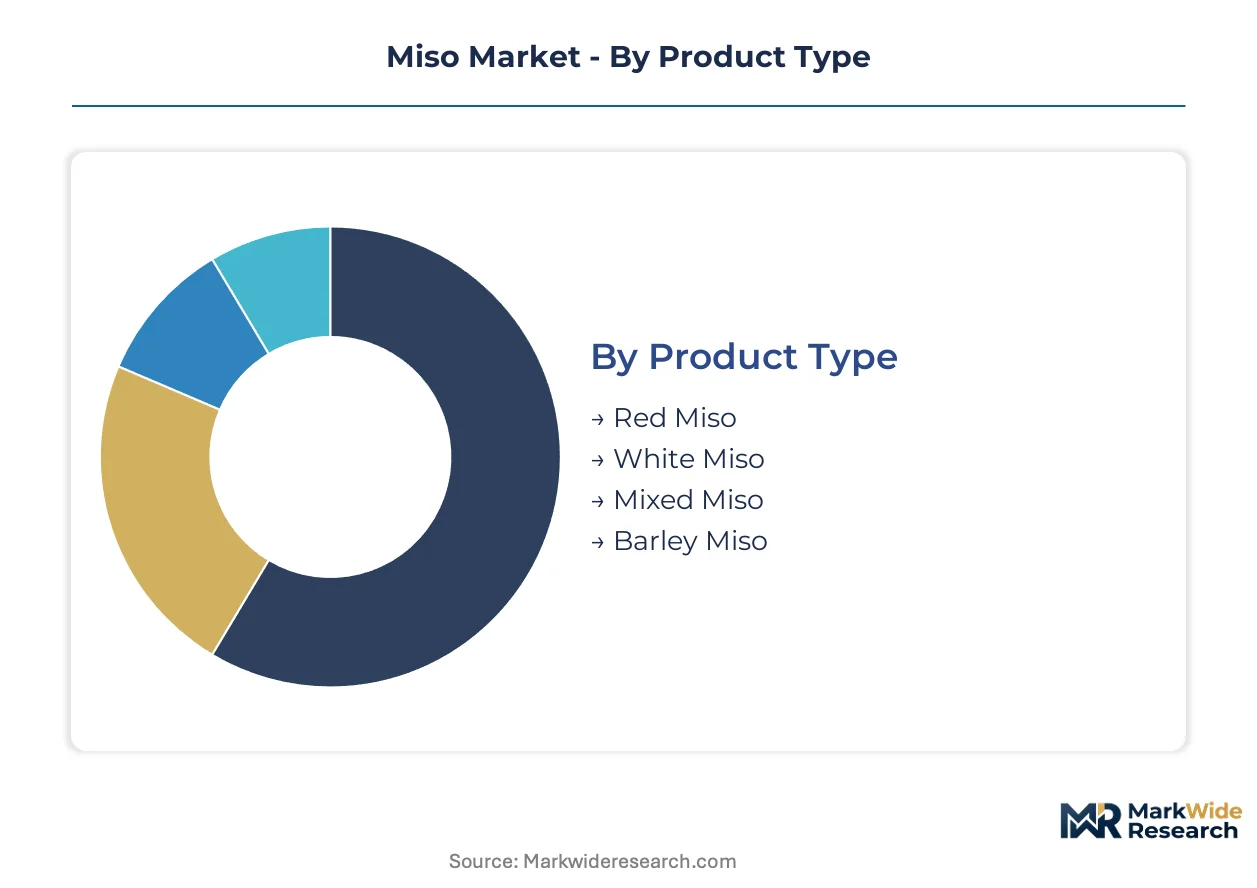
Miso segmentation reveals how fermentation duration, buyer sophistication, and channel economics create distinct profit pools. Manufacturers configure production assets and koji protocols differently for each slice, with premium white miso commanding restaurant premiums while bulk red miso serves industrial soup bases.
Product Type:
Buyers in this category differentiate by fermentation patience and flavor intensity requirements, with premium channels paying steep markups for shorter-aged sweetness while industrial users prioritize cost-efficient umami depth.
- Red Miso:Long-fermented soybean paste aged 12-24 months in cedar vats delivers intense salt-forward profiles and dark coloration. Nagano Prefecture breweries supply Japanese restaurant chains and instant ramen manufacturers seeking concentrated umami bases. Production cycles extend energy costs but lock in traditionalist positioning.
- White Miso:Short-fermented varieties using higher rice-koji ratios achieve pale coloration and pronounced sweetness within 2-12 weeks. North American fine-dining establishments in Los Angeles and New York deploy white miso in butter emulsions and dessert applications, creating volume pull outside traditional soup uses. Shorter aging compresses working capital needs.
- Mixed Miso:Blended profiles combining multiple fermentation durations balance versatility with manufacturing efficiency.
- Barley Miso:Mugi varieties incorporating roasted barley grains yield earthy, nutty flavor profiles distinct from rice-based formulations.
Red miso leads volumes today; white miso is gaining share fastest.
End User:
Channel economics in this category hinge on batch size predictability and specification stringency, with food manufacturers demanding tonnage consistency while households tolerate formulation variation.
- Restaurants:Fine-casual and fine-dining establishments contract dedicated fermentation runs with specified aging duration, displacing traditional distributor intermediaries in urban markets. Chef-owners in New York seek exclusive flavor profiles unavailable through broadline distribution. Direct procurement relationships compress margin capture for middlemen.
- Food Manufacturers:Packaged soup, sauce, and ready-meal brands seek clean-label umami sources to replace synthetic flavor enhancers. UK and Netherlands supermarket private-label ranges introduce miso-glazed protein formats, creating branded ingredient supply contracts with volume guarantees.
- Retail:Grocery channels move standard-grade products through supermarket and specialty store placements.
- Households:Direct-to-consumer sales through online channels serve home cooks with smaller pack sizes.
Restaurants dominate value capture; food manufacturers are expanding most quickly.
Packaging Type:
Packaging selection tracks consumption velocity and contamination risk tolerance, with high-turnover foodservice favoring bulk formats while retail prioritizes shelf presence and resealability.
- Tubs:Polypropylene containers dominate foodservice procurement for restaurant and manufacturing channels, enabling scoop-access and volume pricing. HACCP-compliant sealing systems preserve probiotic viability through distribution. Bulk tub formats minimize per-unit packaging cost for high-throughput buyers.
- Sachets:Single-serve portions address convenience positioning in UK and Netherlands ready-meal kits, with precise dosing eliminating waste. Portion control appeals to household experimentation without commitment to full-size containers.
- Bottles:Squeeze formats serve sauce and dressing applications requiring controlled dispensing.
- Jars:Glass packaging commands premium retail positioning with traditional aesthetic signaling.
Tubs anchor industrial volumes; sachets show steepest expansion trajectory.
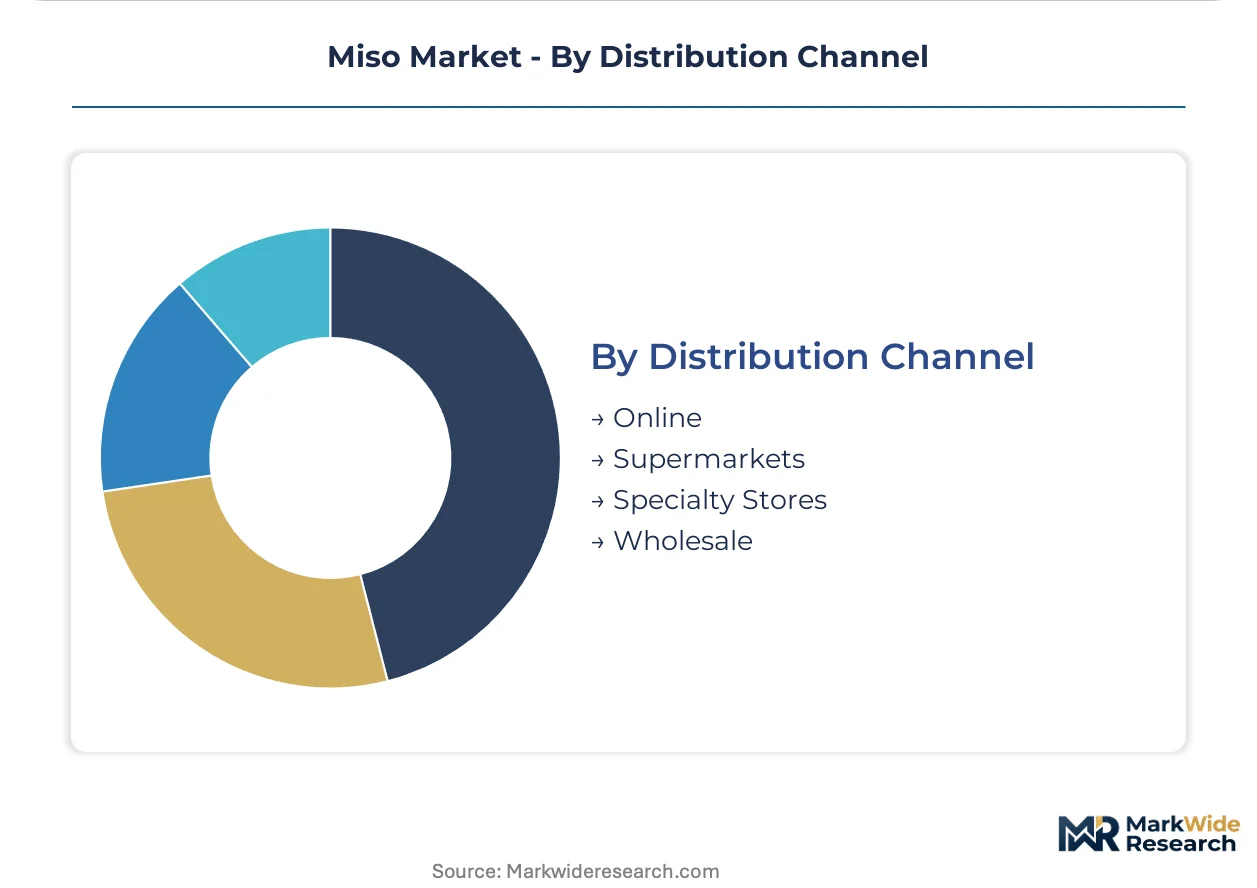
Distribution Channel:
Channel selection in this category reflects buyer search behavior and certification documentation requirements, with specialty retailers validating authenticity claims while wholesale moves undifferentiated tonnage.
- Supermarkets:Mass retail chains in Germany and France stock miso adjacent to Asian ingredient sets, with placement decisions driven by clean-label reformulation mandates and EFSA guidance on additive reduction. Private-label penetration is intensifying price competition.
- Specialty Stores:Japanese grocers and fermentation-focused retailers authenticate provenance for discerning buyers, with blockchain-enabled batch records satisfying Switzerland and Australia import requirements. Curated assortments command margin premiums unavailable in mass channels.
- Online:Direct-to-consumer platforms serve geographically dispersed enthusiasts with subscription formats.
- Wholesale:Broadline distributors aggregate volume for restaurant and manufacturing procurement with contract pricing.
Supermarkets move the most units; specialty stores extract highest margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nagano Prefecture anchors production gravity for traditional cedar-vat fermentation, while demand expansion concentrates in North American and European urban markets seeking clean-label umami alternatives.
Japan
Domestic consumption in Nagano and Aichi prefectures sustains koji-based craft production clusters. The Ministry of Health, Labour and Welfare enforces Food Sanitation Act standards governing koji starter purity and facility hygiene documentation. Aging toji expertise concentrates in Nagano without structured apprenticeship pipelines, threatening long-fermentation protocol continuity.
United States
Fine-dining establishments in Los Angeles and New York deploy white miso in butter emulsions and dessert applications outside traditional soup bases. The FDA classifies miso under fermented food safety protocols requiring acidification monitoring and pathogen control plans. Direct procurement relationships between chef-owners and manufacturers are displacing traditional distributor intermediaries in urban markets.
Germany
Packaged food manufacturers replace synthetic MSG with koji-derived umami sources to meet EFSA guidance on additive reduction in processed foods. The EU Green Deal shapes procurement preferences for producers documenting fermentation energy use and cedar vat forestry sourcing. Supermarket chains stock miso adjacent to Asian ingredient sets, intensifying private-label price competition.
United Kingdom
Supermarket private-label ranges introduce miso-glazed protein and noodle bowl formats, creating branded ingredient supply contracts with volume guarantees. REACH compliance requirements govern packaging material specifications for retail distribution. London-based fermentation-focused retailers authenticate provenance for discerning buyers with blockchain-enabled batch records.
Australia
Import acceptance criteria reference Japanese regulatory alignment for premium export channel access. The TGA monitors probiotic health claims on retail packaging as wellness channel positioning expands. Specialty retailers in Sydney and Melbourne curate assortments commanding margin premiums unavailable in mass channels.
Miso Market Competitive Environment
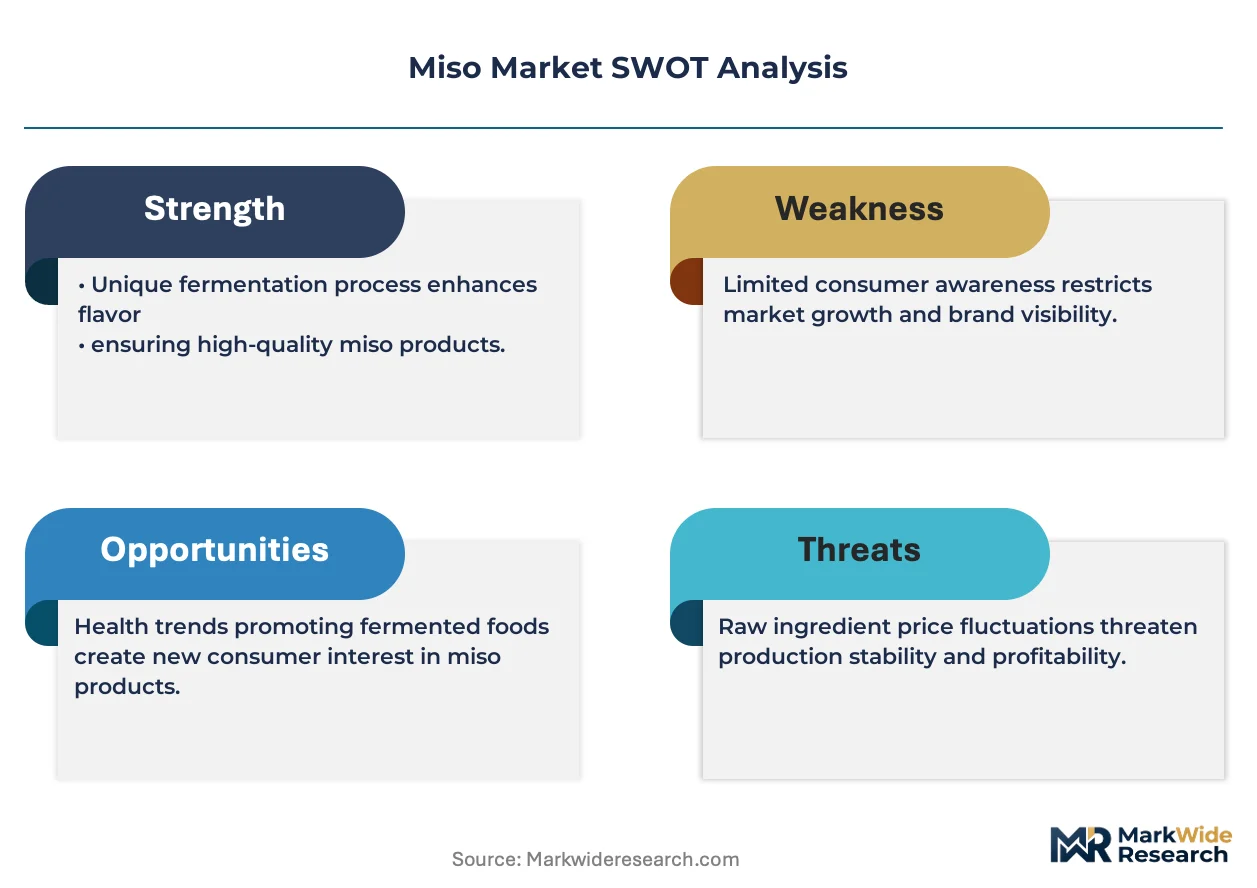
Established producers occupy the standard tier; emerging entrants pursue non-soy substrate development and carbon-accounting differentiation. Market structure reflects moderate consolidation among Japanese heritage manufacturers alongside fragmented North American organic specialists. Two strategic archetypes dominate: vertically integrated koji cultivators leveraging captive rice-koji operations, and premium-protocol traditionalists sustaining soybean-only fermentation. Competitive moves concentrate on backward integration into raw material supply and sustainability certification acquisition.
Within the heritage-manufacturer tier, Marukome Co., Ltd. and Hatcho Miso Co., Ltd. exemplify divergent strategic positioning. Marukome anchors scale-driven production through in-house koji cultivation infrastructure. Hatcho Miso occupies a premium-protocol position sustained through differentiated fermentation approaches. Eden Foods Inc. represents North American organic certification specialists competing through domestic production scale and clean-label retail positioning.
| Leading Market Players |
|---|
| Marusan-Ai Co., Ltd. |
| Eden Foods Inc. |
| Marukome Co., Ltd. |
| Hatcho Miso Co., Ltd. |
| Miyasaka Brewing Company, Ltd. |
| Hikari Miso Co., Ltd. |
| Yamato Soysauce & Miso Co., Ltd. |
| Takeya Miso Co., Ltd. |
| Kikkoman Corporation |
| Others |
Value Chain & Pricing Dynamics
Soybean procurement costs originating in Brazil and Argentina cascade through three distinct pricing tiers before reaching North American food manufacturers, with spot-market exposure compressing margins for non-integrated producers while captive cultivation operations insulate heritage Japanese manufacturers from commodity volatility.
Pricing Analysis
Input-cost pass-through from Brazilian drought cycles and Argentine export taxes is compressing margin predictability for mid-scale producers dependent on spot commodity purchases. Three-tier pricing structure across premium, standard, and economy levels separates cedar-vat aged varieties from temperature-controlled steel tank output and bulk industrial bases. Pricing pressure stems from energy cost intensity in long-fermentation protocols, with solar thermal retrofits partially offsetting carbon accounting penalties. Food manufacturers exhibit highest price sensitivity due to volume procurement and specification fungibility, while fine-dining establishments tolerate premium markups for exclusive flavor profiles.
Supply Chain Analysis
Dual-sourcing requirements are emerging among North American restaurant groups and European supermarket private-label buyers seeking to mitigate koji starter supply concentration risk. Geographic supply concentration centers on Japan for authenticated Aspergillus oryzae strains, the United States for organic certified production, and Germany for clean-label reformulation demand. Raw material dependencies include Brazilian soybeans, domestic Japanese rice for koji cultivation, and cedar vat forestry from Nagano Prefecture. Single-source vulnerability in domestic Japanese koji mold culture banks creates licensing bottlenecks for new market entrants. Distribution runs through direct procurement relationships displacing traditional distributor intermediaries in urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The miso market functions as a stable compounder where clean-label reformulation mandates across European packaged food manufacturers generate steady volume pull independent of cyclical consumer discretionary patterns.
For Market Incumbents: Lock in backward integration into rice-koji cultivation to neutralize seasonal raw material cost swings and preserve margin stability against Brazilian commodity volatility. Secure carbon accounting documentation for cedar vat forestry sourcing to access EU Green Deal-aligned procurement preferences from sustainability-focused foodservice distributors. Expand capacity in temperature-controlled steel tank infrastructure to serve food manufacturer tonnage consistency requirements without sacrificing traditional protocol credibility. For New Entrants and Emerging Players: Launch via direct-to-chef contracting models in Los Angeles and New York fine-casual segments where menu differentiation commands premium pricing unavailable through broadline distribution. Target non-soy substrate development using chickpea and fava bean koji fermentation protocols to capture allergen-free positioning in North American retail channels restricted by soy sensitivity prevalence. Pursue pharmacy and wellness channel access through Japan's qualified fermentation health claims pathway. For Investors and Strategic Acquirers: Consolidation pressure builds where aging toji expertise concentrates among practitioners in Nagano Prefecture without structured apprenticeship pipelines threatening protocol continuity. Long-term viability favors vertically integrated operators with captive koji infrastructure and documented sustainability credentials over pure-play trading entities. Acquisition target archetype: mid-scale Japanese heritage manufacturers with underutilized cedar vat capacity and export certification alignment. Signal to watch: EU regulatory movement toward mandatory fermented food probiotic labeling standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Koji Cultivation | Marukome's captive rice-koji operations stabilize raw material costs across seasonal swings. |
| Carbon Accounting Certification | Documented fermentation energy use unlocks EU Green Deal procurement preferences from sustainability-focused distributors. |
| Non-Soy Substrate Development | Chickpea and fava bean koji fermentation expands allergen-free positioning for North American soy-sensitive retail shelves. |
| Direct Chef Procurement Relationships | Los Angeles and New York fine-casual establishments contract dedicated fermentation runs displacing distributor intermediaries. |
| Blockchain-Enabled Batch Traceability | Digital koji starter provenance records satisfy Japan's tightening Food Sanitation Act enforcement and Swiss import requirements. |
Study Parameters
Coverage spans Japan, the United States, Germany, the United Kingdom, and Australia, with primary inputs from each market combining interviews with toji master brewers, fermentation facility operations directors, restaurant chef-owners, supermarket category buyers, and packaged food manufacturer procurement leads. Secondary validation draws from Japan's Ministry of Health Labour and Welfare regulatory filings, FDA fermented food safety protocols, EFSA guidance documentation, EU Green Deal implementation texts, and CODEX Alimentarius standards. Bottom-up volume modeling triangulates against top-down value estimates across production clusters.
Granularity-level modeling disaggregates the analysis window by product type, end user channel, packaging format, and distribution pathway, with additional dimensioning by fermentation duration protocol and koji substrate composition. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion patterns. Forecast inputs incorporate energy cost trajectory assumptions for cedar vat facilities, Brazilian soybean supply volatility projections, and evolving probiotic health claims regulatory pathways.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EFSA additive prohibition timelines or sudden koji starter supply disruption. Deviation in Japanese apprenticeship pipeline restoration or toji talent migration patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Dong Quai Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Dill Juice Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Super Foods Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Heat-Stable Fruit Fillings Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Vegan Salad Dressing Market