
 Silk Fabric Market | 2026-2036
Silk Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Silk Fabric Market Insights
Bundle-and-blend configurations is hardening as buyers shift from pure silk yardage toward pre-coordinated silk blend collections that reduce sourcing complexity. Zhejiang Jiaxin Silk Co., Ltd. leverages its captive mulberry cultivation and weaving capacity to control cost structures across the supply chain. Bolt Threads anchors the technical segment with biosynthetic silk alternatives that attract sustainability-focused fashion labels. Wensli Group Co., Ltd. competes through heritage branding and museum-grade digital printing techniques that command premium positioning in Asian luxury markets.
Silk fabric denotes protein-based textile derived from Bombyx mori and wild silkworm cocoons, typically measured in momme weight for density and characterized by triangular prism fiber structures that refract light. The material serves high-end apparel, interior decoration, and medical sutures where biocompatibility and tensile strength matter. Woven silk occupies the largest revenue pool due to its dominance in formalwear and bridal segments, while silk blend categories capture the fastest expansion as mills respond to price-sensitive buyers seeking drape and breathability at lower cost points. Mulberry silk maintains margin leadership through its fineness and uniformity, whereas tussar and eri grades attract artisanal and eco-conscious niche channels.
China's GB standards and SAMR oversight govern domestic silk labeling and quality classification, while REACH and the EU Green Deal restrict azo dyes and mandate chemical disclosure for European market access. India's Central Silk Board and BIS certification requirements shape export-grade specifications for tussar and muga varieties. Stakeholders must monitor how evolving biosecurity protocols for silkworm disease management and emerging carbon-border adjustment mechanisms will reshape sourcing economics and regional competitiveness across the value chain.
Market Dynamics
The European Union's Ecodesign for Sustainable Products Regulation is compressing lead times for mills while simultaneously mandating fiber traceability systems that reshape procurement relationships across the value chain.
Growth Catalysts
- Regulatory Pressure on Chemical Disclosure:REACH and the EU Green Deal are forcing mills to reformulate dye chemistries, creating first-mover advantages for facilities with pre-certified low-impact finishing lines.
- Heritage Brand Positioning:Museum-grade digital printing techniques are commanding premium positioning in Asian luxury markets as consumers associate provenance with authenticity.
- Integrated Sericulture Clusters:Zhejiang and Jiangsu provinces supply captive mulberry cultivation through weaving capacity that controls cost structures across multiple supply chain stages.
Market Restraints
- Input Cost Volatility:Raw silk prices fluctuate with Bombyx mori disease outbreaks and climate stress on mulberry leaf yields, compressing margin predictability for weavers without backward integration.
- Supply Concentration Risk:China's dominance in reeling and throwing capacity creates single-source vulnerability for European and North American converters seeking volume guarantees.
- Technical Limitation of Natural Fiber:Pure silk's moisture sensitivity and care requirements limit adoption in mass-market apparel where machine-washability is non-negotiable.
Strategic Opportunities
- Biosynthetic Alternatives:Fermentation-derived protein fibers attract sustainability-focused fashion labels seeking to bypass sericulture's land and water intensity while maintaining drape and tensile performance.
- Medical Suture Applications:Biocompatibility requirements in surgical mesh and ophthalmic procedures open technical-grade demand channels with price insensitivity and long-term supply contracts.
- Carbon Border Adjustment Preparation:Early adoption of lifecycle assessment tools positions mills to defend European market access as the EU phases in embodied carbon tariffs on textile imports.
Industry Challenges
- Sericulture Skill Attrition:Rural labor migration away from mulberry farming and cocoon rearing in China's eastern provinces threatens the knowledge base for quality raw silk production.
- Traceability System Integration:Blockchain and mass-balance certification requirements from luxury houses demand IT infrastructure investments that smaller throwing mills struggle to finance.
- Dyehouse Compliance Timelines:Zero-disclosure mandates under tightening MEE enforcement in China compress the window for effluent treatment upgrades without production interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silk Fabric Market |
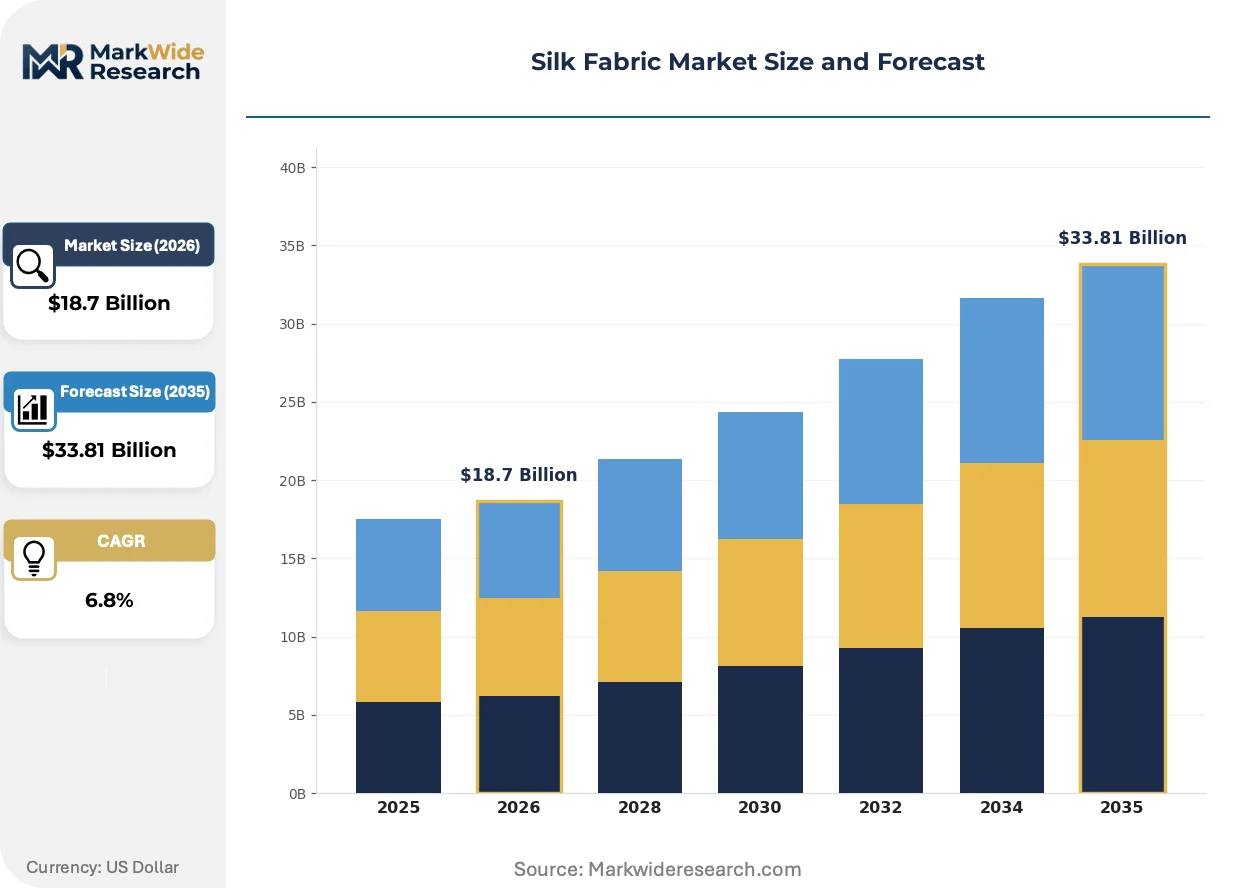
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Silk, Knitted Silk, Silk Blend, Printed Silk Application: Apparel, Home Furnishings, Accessories, Upholstery Grade: Mulberry Silk, Tussar Silk, Eri Silk, Muga Silk Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Bolt Threads, Zhejiang Jiaxin Silk Co., Ltd., Shengkun Silk Manufacturing Co., Ltd., Wensli Group Co., Ltd., China Silk Corporation, Wujiang First Textile Co., Ltd., Anhui Silk, Kraig Biocraft Laboratories, Inc., AM Silk GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silk Fabric Market Trends and Innovations
Digital traceability infrastructure and biosynthetic material platforms are restructuring how quality is verified and how fiber origins are communicated to end buyers.
Blockchain-based fiber provenance systems are unifying batch records from mulberry cultivation through finished fabric inspection into immutable ledgers. Luxury apparel houses in Italy and France are mandating these systems for supplier qualification. The technology is unifying previously fragmented documentation into single-source truth that reduces audit costs and accelerates customs clearance.
REACH authorization lists and the EU Green Deal's restriction timeline are phasing out azo dyes and heavy-metal mordants from European market access. Mills serving export channels must reformulate coloration chemistry or forfeit positioning. Italian finishing houses are responding fastest, converting wet-processing lines to GOTS-certified low-impact systems ahead of compliance deadlines.
Bundle-and-blend configurations are displacing pure silk yardage as the default procurement format. Ready-to-wear buyers now specify pre-coordinated silk-cotton and silk-viscose collections that reduce sourcing complexity and inventory risk. This pattern is most visible in Zhejiang's integrated clusters, where converters offer curated swatch books with guaranteed dye-lot consistency across blended constructions.
Silk Fabric Market Segmentation
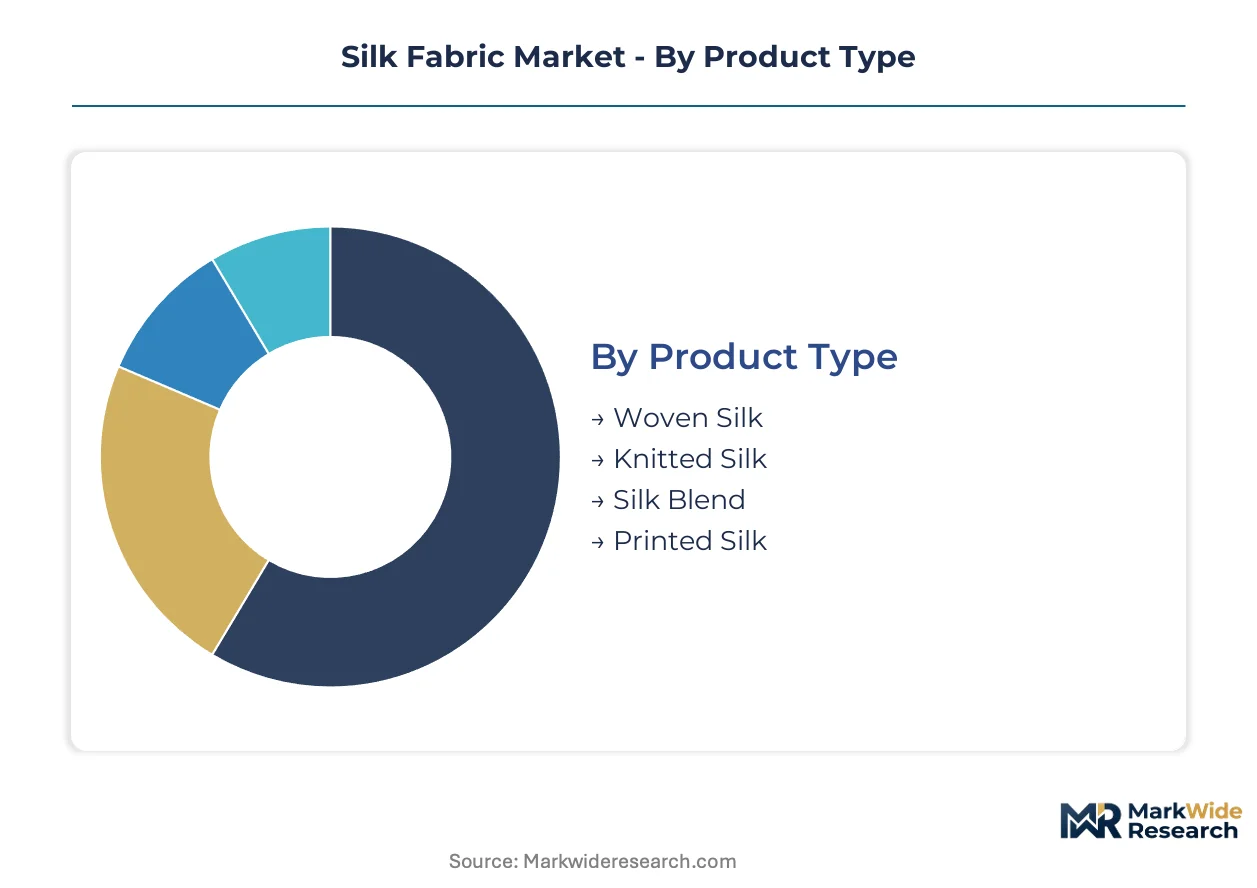
Silk fabric segmentation reveals how protein-based textiles serve divergent value chains—from haute couture houses demanding momme-specific woven grades to mass-market apparel seeking blended constructions with machine-washability. Understanding these partitions exposes where margin concentrates versus where volume expansion occurs.
Product Type:
Standalone silk constructions dominate formalwear and luxury channels, while embedded blend formats penetrate price-sensitive apparel segments seeking drape without pure fiber cost.
- Woven Silk:Interlaced warp-and-weft constructions measured in momme weight deliver the triangular prism light refraction prized in bridal gowns and eveningwear. Italian and French luxury houses anchor procurement here for haute couture lines where fiber fineness commands premium positioning. Woven silk leads volumes today; silk blend is gaining share fastest.
- Silk Blend:Pre-coordinated silk-cotton and silk-viscose collections reduce sourcing complexity for ready-to-wear buyers managing inventory risk. Zhejiang's integrated clusters supply curated swatch books with guaranteed dye-lot consistency across these constructions.
- Knitted Silk:Loop-structured constructions offer stretch recovery for lingerie and base-layer applications where body-conforming drape matters.
- Printed Silk:Digital and screen-printed yardage serves scarf manufacturers and resort-wear labels seeking rapid pattern turnaround.
Bundle-and-blend configurations are displacing pure silk yardage as the default procurement format across mid-market channels.
Application:
Apparel absorbs the largest revenue pool while technical and interior segments exploit silk's biocompatibility and light-refractive properties for specialized end-uses.
- Apparel:Formalwear, bridal segments, and luxury ready-to-wear consume the highest-grade mulberry constructions. REACH and EU Green Deal dye restrictions are reformulating coloration chemistry for export-grade finishing.
- Home Furnishings:Curtain and bedding applications favor heavier momme weights for opacity and durability. Chinese domestic demand concentrates in Zhejiang and Jiangsu provinces where integrated sericulture-to-weaving clusters control cost structures.
- Accessories:Scarves, ties, and pocket squares command heritage branding premiums through museum-grade digital printing techniques.
- Upholstery:High-traffic furniture applications leverage silk's tensile strength when blended with synthetic fibers for abrasion resistance.
Apparel maintains revenue leadership; home furnishings show the steepest expansion trajectory as Asian luxury consumption broadens beyond personal wear.
Grade:
Fineness and uniformity separate commercial tiers, with Bombyx mori-derived grades commanding margin leadership over wild silkworm varieties serving artisanal niches.
- Mulberry Silk:Bombyx mori cocoons fed cultivated mulberry leaves yield the finest, most uniform filaments. China's GB standards and SAMR oversight govern domestic labeling and quality classification for this grade.
- Tussar Silk:Antheraea mylitta wild silkworm varieties produce coarser, more textured filaments attracting eco-conscious and artisanal channels. India's Central Silk Board and BIS certification requirements shape export-grade specifications.
- Eri Silk:Samia ricini-derived fibers offer cotton-like handle and thermal properties for winter accessory applications.
- Muga Silk:Antheraea assamensis endemic to Assam delivers golden natural coloration without dyeing, serving heritage textile preservation markets.
Mulberry silk dominates commercial volumes; tussar and eri grades are expanding most quickly in sustainability-positioned niche channels.
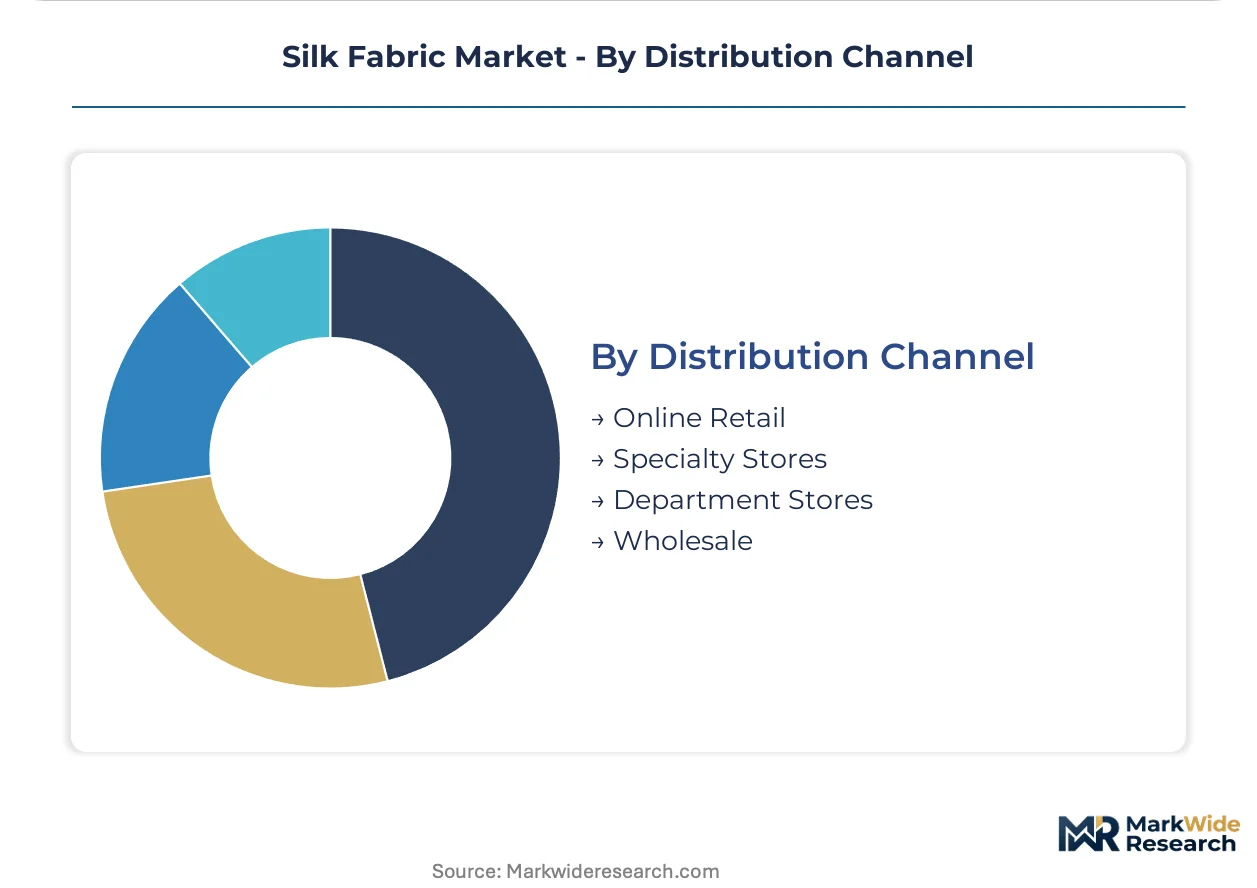
Distribution Channel:
Direct-to-consumer platforms are compressing traditional wholesale hierarchies while specialty retail maintains positioning power for tactile-dependent purchases.
- Specialty Stores:Fabric merchants and luxury textile boutiques offer hand-feel validation and custom-order services for bridal and couture clients. Italian and French apparel houses rely on these channels for supplier qualification and fiber provenance verification.
- Online Retail:E-commerce platforms aggregate fragmented demand from small-scale designers and regional garment manufacturers. Blockchain-based traceability systems are unifying batch records for digital channel credibility.
- Department Stores:Curated silk departments serve affluent consumers seeking branded home furnishing and accessory collections.
- Wholesale:Volume converters in Zhejiang and Jiangsu provinces supply North American and European garment manufacturers through long-term supply contracts.
Specialty stores anchor premium positioning; online retail is climbing the fastest as digital traceability infrastructure reduces purchase risk for unseen fabric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sericulture originated in Neolithic China, where mulberry cultivation and silkworm domestication created the foundation for an industry that now spans continents. The modern silk fabric trade retains this geographic DNA, with production clustering where climatic conditions, skilled labor, and finishing infrastructure converge.
China
Zhejiang and Jiangsu provinces host integrated sericulture-to-weaving clusters that supply the bulk of global raw silk and finished fabric. GB standards and SAMR oversight govern domestic labeling and quality classification, while MEE enforcement tightens zero-discharge mandates for dyehouse effluent. Suzhou and Hangzhou maintain captive mulberry cultivation through weaving capacity that controls cost structures across multiple supply chain stages.
India
Tussar and eri silk varieties attract artisanal and eco-conscious niche channels seeking alternatives to mulberry uniformity. The Central Silk Board and BIS certification requirements shape export-grade specifications for wild silkworm grades. Karnataka and West Bengal concentrate reeling and handloom weaving operations where rural cooperatives preserve traditional knowledge against urban labor migration.
Italy
Luxury apparel houses in Como and Milan expand silk procurement for ready-to-wear and haute couture lines demanding momme-specific woven constructions. REACH authorization lists and the EU Green Deal restrict azo dyes and mandate chemical disclosure, accelerating conversion to GOTS-certified low-impact finishing systems. Lombardy-based finishing houses are responding fastest to compliance deadlines.
France
Heritage branding premiums command museum-grade digital printing techniques in Lyon, where silk weaving dates to the Renaissance. The Ecodesign for Sustainable Products Regulation compresses lead times for mills while mandating fiber traceability systems that reshape procurement relationships. Rhône-Alpes converters supply Parisian couture houses with batch-verified provenance documentation.
Japan
Technical-grade demand channels exploit silk's biocompatibility for medical sutures and ophthalmic procedures where price insensitivity supports long-term supply contracts. METI and JIS standards govern fiber specifications for surgical applications. Yamanashi Prefecture maintains specialized reeling capacity for pharmaceutical-grade filament production.
Silk Fabric Market Competitive Landscape
Premium-margin players sit above commodity-margin players across traceability certification and finishing technology tiers. The vendor base stratifies between integrated sericulture operations with captive mulberry supply and merchant converters dependent on spot raw silk markets. Three archetypes dominate: heritage-brand heritage houses leveraging provenance marketing, integrated Chinese mills with backward control over cultivation, and biosynthetic specialists engineering fermentation-derived alternatives. Competitive moves concentrate on blockchain traceability system deployment and low-impact finishing line certification ahead of regulatory deadlines.
Within the integrated mill tier, Zhejiang Jiaxin Silk Co., Ltd. and Wensli Group Co., Ltd. represent archetypes of Chinese supply chain control and heritage branding respectively. Bolt Threads anchors the technical segment with biosynthetic platforms that attract sustainability-focused fashion labels seeking to bypass sericulture's land intensity. These three entities exemplify how geographic origin and organizational structure map to distinct competitive positioning vectors in a market where fiber provenance increasingly determines supplier qualification.
| Leading Market Players |
|---|
| Bolt Threads |
| Zhejiang Jiaxin Silk Co., Ltd. |
| Shengkun Silk Manufacturing Co., Ltd. |
| Wensli Group Co., Ltd. |
| China Silk Corporation |
| Wujiang First Textile Co., Ltd. |
| Anhui Silk |
| Kraig Biocraft Laboratories, Inc. |
| AM Silk GmbH |
| Others |
Pricing and Supply Chain Analysis
Italian and French luxury apparel houses anchor procurement for haute couture lines, concentrating buying power around momme-specific woven constructions that sustain premium-mid-economy pricing differentiation across mulberry grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates museum-grade digital printing from commodity blend yardage. Price differentiation rests on certification tier—GOTS-certified low-impact finishing commands premiums over conventional dyehouse output—and volume scale, where long-term supply contracts compress unit costs for ready-to-wear buyers. Cost compression in standard-grade blends is intensifying because Zhejiang's integrated clusters optimize captive mulberry cultivation through weaving capacity. Mass-market apparel buyers exhibit highest price sensitivity; surgical mesh and ophthalmic procedure channels show least sensitivity due to biocompatibility requirements.
Supply Chain Analysis
Regional distribution centers in Hangzhou and Suzhou feed hub-and-spoke patterns radiating toward European finishing houses and North American garment manufacturers. Geographic supply concentrates in China, India, and Italy, with Zhejiang and Jiangsu provinces hosting integrated sericulture-to-weaving clusters. Raw material dependencies draw from Bombyx mori cocoon supply, mulberry leaf cultivation, and azo-free dye formulations. Single-source vulnerability pervades reeling and throwing capacity concentrated in eastern China. Distribution runs through long-term supply contracts for volume converters and specialty fabric merchants for couture channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH authorization lists and the EU Green Deal's restriction timeline on azo dyes and heavy-metal mordants force mill reformulation and create first-mover advantages for certified facilities.
For Market Incumbents: Lock in backward integration into captive mulberry cultivation to defend margin predictability against raw silk price volatility from Bombyx mori disease outbreaks. Prioritize GOTS-certified low-impact finishing line conversion ahead of EU compliance deadlines to secure supplier qualification with Italian and French luxury houses mandating fiber traceability systems.
For New Entrants and Emerging Players: Capture biosynthetic alternative demand from sustainability-focused fashion labels seeking fermentation-derived protein fibers that bypass sericulture's land intensity. Target medical suture applications where biocompatibility requirements support price-insensitive long-term supply contracts. Lead with lifecycle assessment tools to position for EU carbon border adjustment mechanisms.
For Investors and Strategic Acquirers: Luxury apparel houses are the most active acquirer in this space, consolidating heritage-brand positioning and museum-grade digital printing capabilities. Five-to-ten-year viability favors integrated mills with blockchain traceability infrastructure and zero-discharge dyehouse compliance. Watch for MEE enforcement tightening on effluent treatment upgrades as inflection indicator for regional competitiveness shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sericulture | Zhejiang and Jiangsu mills control cost structures across multiple supply chain stages through captive mulberry cultivation. |
| GOTS-Certified Finishing Conversion | Italian finishing houses secure European market access ahead of REACH azo dye restrictions and EU Green Deal mandates. |
| Blockchain Traceability Deployment | Luxury apparel houses in Como and Lyon mandate immutable batch records from cultivation through inspection for supplier qualification. |
| Biosynthetic Platform Development | Fermentation-derived protein fibers attract sustainability-focused labels seeking alternatives to land-intensive sericulture. |
| Medical-Grade Filament Specialization | Yamanashi Prefecture facilities exploit silk's biocompatibility for surgical mesh and ophthalmic procedure applications. |
Research Methodology
Bottom-up apparel and home furnishings modeling reconciled against top-down sericulture and reeling capacity tracking forms the analytical core. Primary interviews with silk mill operations directors, luxury house procurement leads, dyehouse compliance officers, and medical device sourcing managers combined with secondary validation from customs/trade data, Central Silk Board export statistics, GB standards documentation, and SEC filings from listed textile converters. Triangulation between demand-side consumption patterns and supply-side production volumes ensures cross-verified outputs.
Input-output matrices map filament grade, construction type, end-use application, and regional regulatory cluster across the projection horizon. Segmentation dimensions include product type, application, grade, and distribution channel, with CAGRs derived from trend extrapolation against historical volume trajectories and elasticity-adjusted price evolution. Forecast inputs incorporate mulberry leaf yield projections, dye chemistry reformulation timelines, and biosecurity protocol impacts on Bombyx mori cocoon supply.
Underlying measurement precision varies by segment; mulberry silk and woven constructions carry tighter precision than tussar grades and artisanal channels where cooperative data fragmentation persists. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity for biosynthetic alternatives. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
Gum Fiber Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Global Cotton Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Organic Cotton Market
Natural Fibers
Jute Bags Market
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
Silk Mask Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Textile Staples Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Hessian Sacks Market
Natural Fibers
Acoustic Cotton Market
Natural Fibers
Down and Feather Market