
 Natural Fiber Composite (NFC) Market | 2026-2036
Natural Fiber Composite (NFC) Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Fiber Composite (NFC) Market Foresight
Modular panel systems for automotive interiors is repositioning buyer evaluation criteria from standalone material cost to total assembly efficiency. UPM leverages its integrated pulp-to-composite supply chain to secure consistent fiber quality for Tier 1 suppliers. TECNARO GmbH differentiates through specialized compounding expertise in hemp-PP formulations. Trex Company, Inc. anchors the North American landscape with scaled extrusion capacity and established building-products distribution.
Natural Fiber Composites combine lignocellulosic fibers such as hemp, flax, or kenaf with thermoplastic or thermoset matrices to achieve density reductions of 25-40% versus glass fiber equivalents while maintaining acceptable stiffness for semi-structural applications. Their primary purpose centers on replacing petroleum-reinforced plastics in weight-sensitive, moderate-load environments where end-of-life biodegradability or incineration compliance carries regulatory weight. Flax-based formulations currently command the strongest position in European automotive programs due to established cultivation networks and consistent bast fiber geometry. Injection molding dominates volume throughput for consumer goods and small automotive trim, though compression molding retains margin concentration in aerospace component trials where void control and fiber orientation precision justify slower cycle economics.
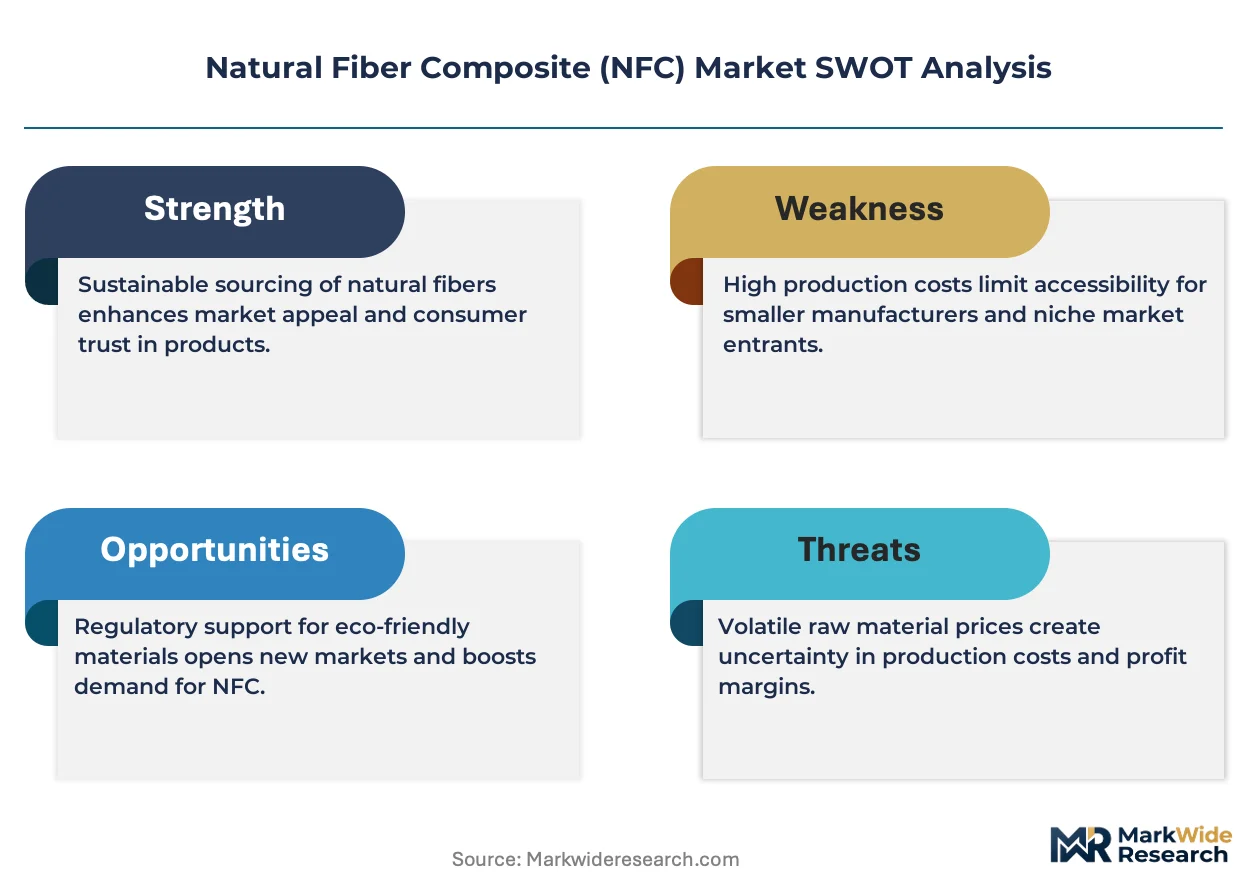
The EU Green Deal's carbon border adjustments and REACH restrictions on persistent synthetic additives are tightening compliance requirements for composite imports into European manufacturing chains. EPA guidelines on volatile organic compound emissions from thermoset processing shape domestic US facility permitting and equipment investment timelines. FDA food-contact assessments for natural fiber packaging substrates are opening parallel qualification pathways distinct from conventional plastic approvals. Stakeholders must track evolving biodegradability certification standards across jurisdictions to avoid stranded inventory as retail and automotive procurement rules tighten.
Market Dynamics
Automotive OEMs in Germany are consolidating NFC procurement around bast fiber supply clusters, compressing supplier qualification timelines from 18 months to 9 months as weight-reduction mandates tighten.
Growth Catalysts
- EU Green Deal carbon border adjustments:REACH restrictions on synthetic polymer content redirect Tier 1 procurement toward hemp-flax hybrids for interior panels.
- Injection molding throughput gains:Compounding advances in twin-screw extrusion cut fiber attrition rates, opening consumer goods volume.
- Kenaf cultivation expansion in Bangladesh:Bast fiber geometry consistency improves, reducing lot-to-lot variability for compression molders.
Market Restraints
- Flax fiber price volatility:Weather-driven yield swings in France and Belgium compress compounder margins during contract renegotiations.
- Thermoset curing energy intensity:Natural gas input costs for epoxy-kenaf aerospace trials strain program economics against carbon fiber alternatives.
- Moisture absorption ceiling:Lignocellulosic fiber hydrophilicity caps outdoor construction applications below 15% equilibrium moisture content.
Strategic Opportunities
- India PLI scheme for advanced materials:Domestic jute-PP compounding capacity qualifies for production-linked incentives, attracting European joint ventures.
- Packaging substrate qualification:FDA food-contact assessments for molded fiber trays open parallel pathways distinct from petroleum-based approvals.
- Hybrid natural-synthetic layups:Flax-glass interlayers in wind turbine nacelles balance stiffness targets with end-of-life incineration compliance.
Industry Challenges
- Fiber orientation control:Compression molders lack real-time shear visualization tools, generating void rates above 3% in aerospace trials.
- Biodegradability certification fragmentation:Competing ISO 17088, EN 13432, and ASTM D6400 standards strand inventory when retail procurement rules shift.
- Legacy thermoset equipment retrofit costs:Natural fiber preform heating profiles differ from glass, requiring press control system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Fiber Composite (NFC) Market |
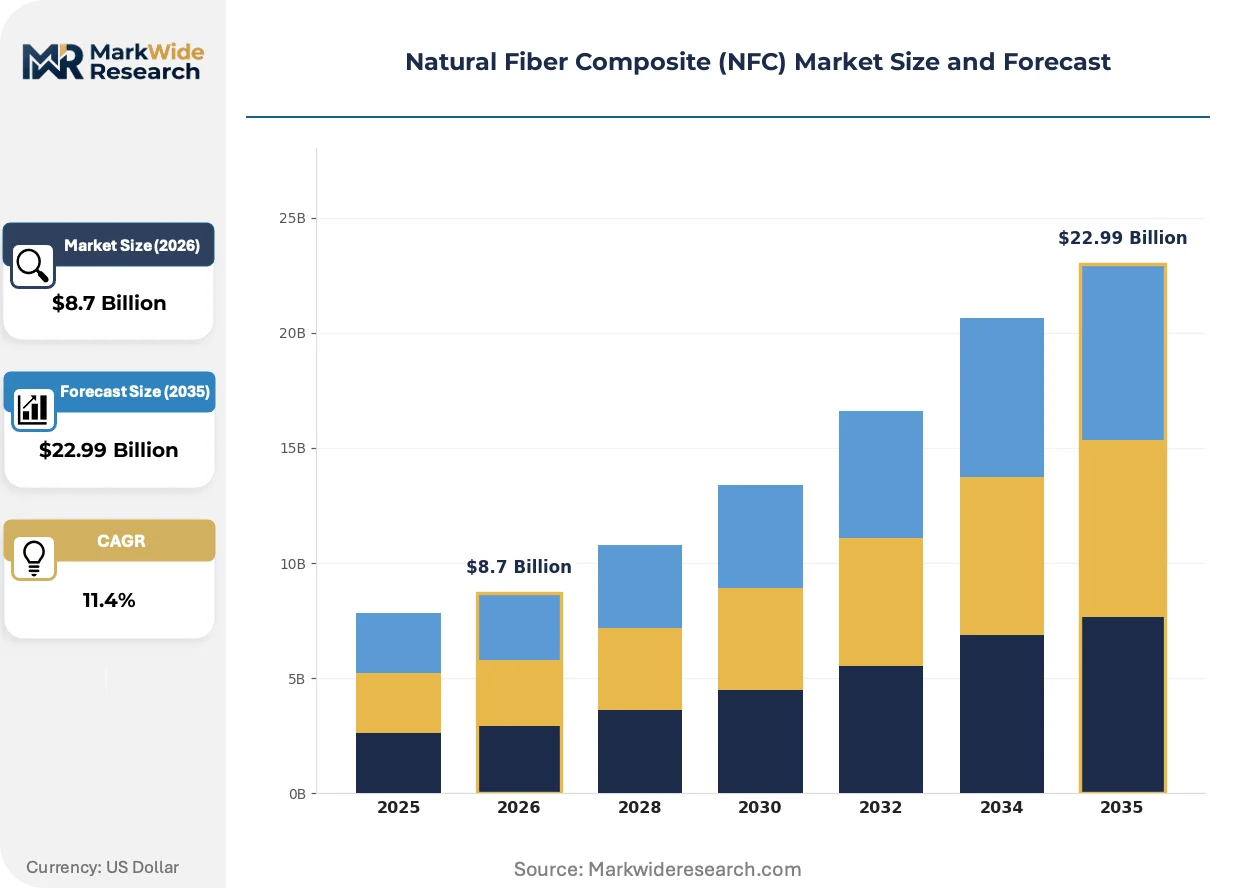
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Hemp, Flax, Kenaf, Jute End User: Automotive, Construction, Aerospace, Consumer Goods Application: Interior Panels, Furniture, Aerospace Components, Packaging Processing Technique: Injection Molding, Compression Molding, Extrusion, 3D Printing |
| Companies Covered | UPM, TECNARO GmbH, Polyvlies Franz Beyer GmbH, Flexform SpA, Trex Company, Inc., Bcomp, Procotex, Green Dot Bioplastics, FlexForm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Fiber Composite (NFC) Market Shifts & Advancements
Processing technology and regulatory compliance frameworks are compressing development cycles while opening application categories previously closed to bio-based materials.
Hybrid thermoplastic-thermoset intermediates are converging with automated fiber placement systems. Aerospace tier suppliers in Toulouse and Hamburg adopt these pre-impregnated tapes for secondary structure trials, cutting layup labor by 40% while maintaining void control. The convergence is displacing hand-layup natural fiber methods in programs above 500 units annually.
EPA volatile organic compound guidelines for phenolic resin curing are tightening facility permitting timelines. Thermoset processors in Michigan and Ohio face 14-month equipment approval queues, redirecting capital toward water-based polyurethane alternatives. Compression molders serving construction markets absorb the longest delays, accelerating in-house emissions testing capabilities.
Automotive interior buyers are consolidating supplier panels from twelve to four approved compounders per platform. BMW and Mercedes-Benz procurement teams now mandate cradle-to-gate carbon accounting, disqualifying vendors without ISO 14040-compliant life cycle assessments. German OEM supply chains exhibit the strictest consolidation, with French and Italian programs following 18 months behind.
Natural Fiber Composite (NFC) Market Segmentation
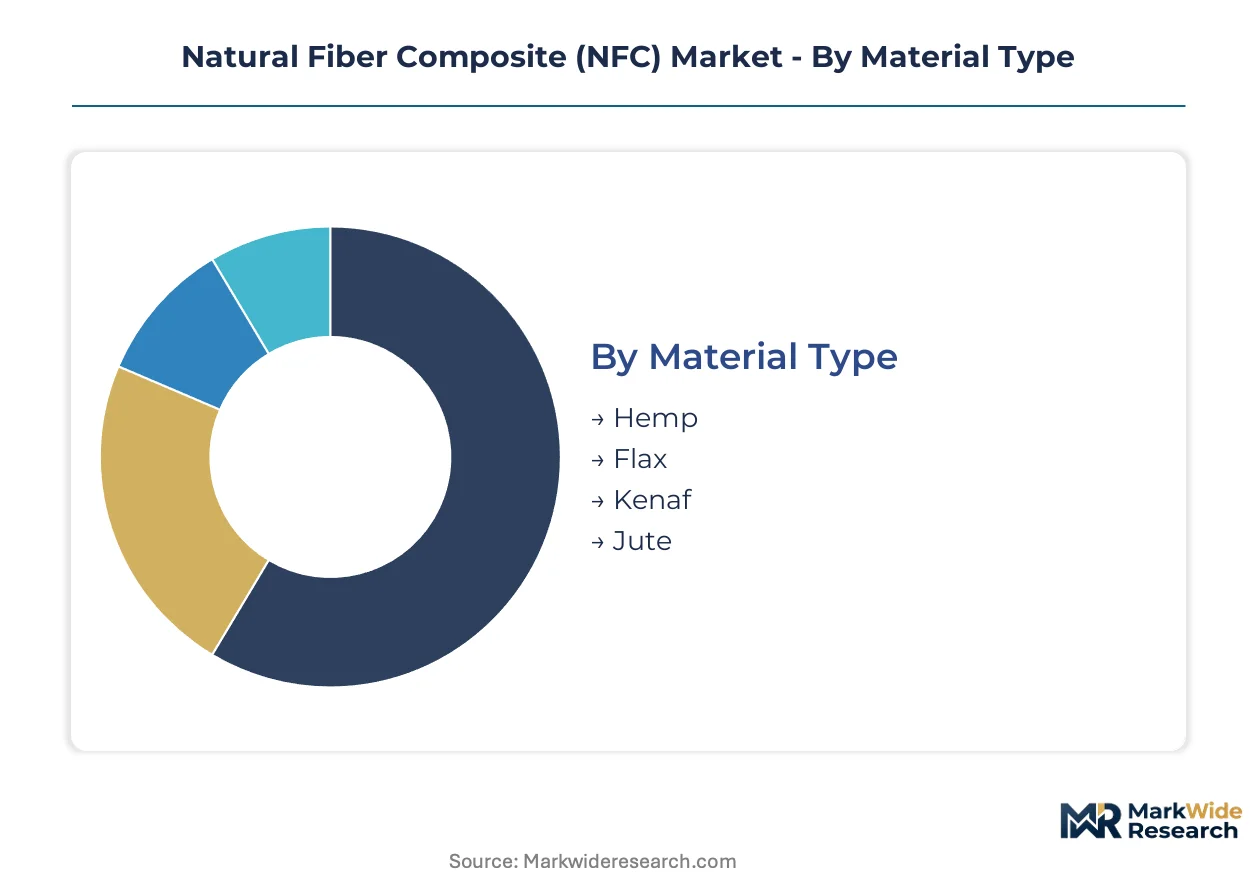
NFC procurement teams segment by certification burden and processing compatibility. Material type dictates REACH compliance pathways. End-use determines whether FDA food-contact, EPA emissions, or EASA airworthiness approvals dominate supplier qualification.
Material Type:
REACH restrictions on synthetic polymer content create divergent certification burdens across bast fiber categories. Hemp and flax suppliers face ECHA scrutiny on pesticide residues. Kenaf and jute processors navigate BIS quality standards for Asian supply chains.
- Hemp:Bast fiber geometry delivers consistent tensile strength for automotive load floors. German OEMs consolidate procurement around Bavarian cultivation cooperatives to secure ISO 17088 biodegradability documentation. Leading the category by volume: Flax. Growing fastest: Hemp.
- Flax:Established European cultivation networks in France and Belgium supply linen-grade bast with low lot-to-lot variability. Compression molders favor flax-PP for interior panels where surface finish requirements match glass fiber alternatives.
- Kenaf:Bangladesh expansion improves fiber consistency for construction board applications. Central bank export financing supports processing infrastructure near Dhaka.
- Jute:India's PLI scheme for advanced materials subsidizes domestic compounding capacity. Jute-PP formulations target packaging substrates requiring FDA food-contact assessments.
Cost tier stratification separates premium flax from economy jute grades.
End User:
Automotive buyers mandate cradle-to-gate carbon accounting per ISO 14040. Aerospace programs require EASA airworthiness certification for secondary structures. Construction and consumer goods segments face lighter regulatory loads.
- Automotive:BMW and Mercedes-Benz procurement panels compress supplier qualification from 18 months to 9 months. Weight-reduction mandates drive bast fiber adoption for door panels, seat backs, and package trays. Leading the category by volume: Automotive. Expanding most quickly: Aerospace.
- Construction:Moisture absorption above 15% equilibrium content limits exterior structural deployment. Interior molding and trim applications dominate volume.
- Aerospace:Toulouse and Hamburg tier suppliers trial flax-epoxy layups for secondary structures. Automated fiber placement cuts labor by 40% versus hand-layup methods.
- Consumer Goods:Injection molding throughput gains open electronics housing and appliance trim categories. Twin-screw extrusion advances reduce fiber attrition rates.
Application maturity varies sharply across end-use segments.
Application:
Interior panels command the deepest supplier qualification requirements. Furniture and packaging segments offer faster market entry. Aerospace components demand the longest development cycles.
- Interior Panels:Modular systems reposition buyer criteria from material cost to total assembly efficiency. German OEMs consolidate around four approved compounders per platform. Leading the category by volume: Interior Panels. Climbing the fastest: Packaging.
- Furniture:Compression molding serves chair shells and table bases where surface aesthetics drive specification. European retailers require EN 13432 compostability certification.
- Aerospace Components:Void rates above 3% disqualify suppliers from secondary structure trials. Real-time shear visualization tools remain scarce.
- Packaging:FDA food-contact assessments open pathways distinct from petroleum-based plastic approvals. Molded fiber trays target retail produce and electronics protection.
Processing technique selection locks in capital equipment decisions.
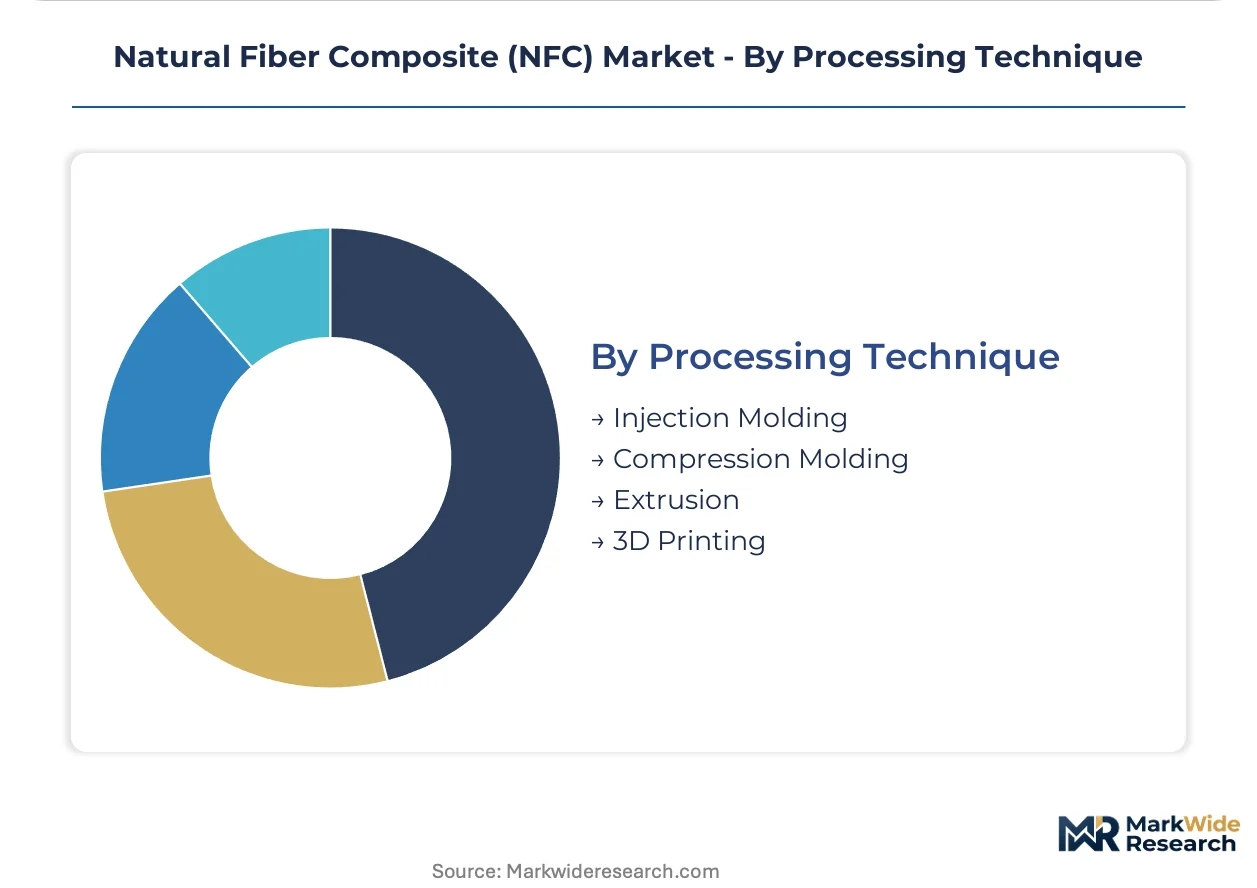
Processing Technique:
Injection molding dominates consumer goods volume. Compression molding retains margin concentration in aerospace trials. Extrusion anchors building products. 3D printing remains pre-commercial.
- Injection Molding:Twin-screw extrusion compounding cuts fiber length attrition, enabling complex geometries for automotive trim and consumer electronics. Cycle economics favor high-volume programs above 100,000 units annually. Leading the category by volume: Injection Molding. Gaining share fastest: 3D Printing.
- Compression Molding:Void control and fiber orientation precision justify slower cycle times for aerospace and premium furniture applications. Preform heating profiles differ from glass fiber, requiring press control retrofits.
- Extrusion:Scaled capacity in North American building products distribution serves decking and fencing markets. Trex Company anchors this channel with established retail relationships.
- 3D Printing:Fused filament fabrication with natural fiber-reinforced thermoplastics enables prototyping and low-volume customization. Technical fiber processing clusters in Germany and the Netherlands pilot production-scale systems.
Customer type concentration shapes equipment investment priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in European fiber processing clusters while consumption accelerates across automotive supply chains in Germany and North American building products distribution. This geographic split shapes trade flows and supplier qualification requirements.
Germany
Bavarian cultivation cooperatives supply hemp bast fiber to consolidated OEM procurement panels. KBA vehicle certification requirements now incorporate cradle-to-gate carbon accounting for interior components. The Stuttgart-Munich corridor hosts four approved compounders per platform serving BMW and Mercedes-Benz programs.
United States
Building products distribution drives extrusion demand for decking and fencing applications. EPA volatile organic compound guidelines extend thermoset facility permitting timelines to fourteen months in Michigan and Ohio. Trex Company anchors scaled capacity through established retail relationships in the Midwest and Southeast.
France
Linen-grade flax cultivation networks in Normandy and Brittany deliver low lot-to-lot variability for compression molders. ECHA scrutiny on pesticide residues shapes hemp supplier documentation requirements. The Hauts-de-France region concentrates technical fiber processing infrastructure for automotive interior panels.
India
Domestic jute-PP compounding capacity qualifies under the PLI scheme for advanced materials production-linked incentives. BIS quality standards govern Asian supply chain integration for European joint ventures. West Bengal and Bangladesh border regions expand kenaf cultivation with central bank export financing support.
China
MIIT industrial standards for bio-based materials accelerate domestic compounding capacity expansion. Dual carbon goals redirect procurement toward natural fiber alternatives in consumer goods injection molding. Yangtze River Delta technical fiber clusters pilot automated fiber placement systems for aerospace trials.
Natural Fiber Composite (NFC) Market Competitive Landscape
The competitive structure tilts toward integrated pulp-to-composite specialists and regional compounding experts. German automotive supply chains consolidate around four approved compounders per platform, compressing qualification timelines from eighteen to nine months. Three archetypes dominate: integrated fiber suppliers with captive cultivation, specialized compounders with formulation IP, and scaled extruders with building-products distribution. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs mandate ISO 14040-compliant life cycle assessments.
Among integrated specialists, UPM leverages its pulp-to-composite supply chain position. TECNARO GmbH exemplifies the compounding expertise archetype within German technical fiber clusters. Trex Company, Inc. anchors the scale-driven North American position through established retail distribution channels.
| Leading Market Players |
|---|
| UPM |
| TECNARO GmbH |
| Polyvlies Franz Beyer GmbH |
| Flexform SpA |
| Trex Company, Inc. |
| Bcomp |
| Procotex |
| Green Dot Bioplastics |
| FlexForm Technologies |
| Others |
Supply & Pricing Matrix
Twin-screw extrusion compounding advances are compressing fiber attrition rates while simultaneously concentrating procurement power among German OEMs with captive cultivation networks. This technical transition rewards integrated pulp-to-composite specialists with cost predictability while squeezing standalone compounders facing flax price volatility from weather-driven yield swings in France and Belgium.
Pricing Analysis
Margin tightening in standard-grade bast fiber formulations reflects automotive OEM consolidation around four approved compounders per platform. Three-tier pricing structure across premium linen-grade flax, standard hemp-PP, and economy jute grades differentiates by fiber geometry consistency and ISO 14040 life cycle documentation. Cost-down pressure on economy tiers accelerates because Bangladesh kenaf expansion improves lot-to-lot variability. Tier 1 automotive buyers exhibit lowest price sensitivity due to weight-reduction mandate compliance requirements, while construction distributors show highest sensitivity to equilibrium moisture content thresholds.
Supply Chain Analysis
EU Green Deal domestic-content requirements for bio-based materials are redirecting procurement toward Bavarian hemp cooperatives and Normandy flax cultivation networks. Raw material flows draw from French linen-grade bast, German automotive-grade hemp, and Bangladeshi kenaf expansion zones. Single-source vulnerability concentrates in European automotive qualification panels where KBA certification timelines compress from eighteen to nine months. Distribution runs through Tier 1 supplier compounders in the Stuttgart-Munich corridor for automotive interiors, with Trex Company anchoring North American building products through Midwest and Southeast retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as OEMs mandate cradle-to-gate carbon accounting and fiber quality consistency. Players are pursuing upstream control over cultivation networks to secure qualification panel positions.
For Market Incumbents: Anchor qualification panel positions by deepening backward integration into Bavarian and Normandy cultivation cooperatives. Defend against Bangladesh kenaf expansion by investing in real-time shear visualization tools to cut aerospace void rates below three percent. Prioritize ISO 17088 biodegradability certification investment to meet tightening EU retail procurement rules.
For New Entrants and Emerging Players: Capture white space in FDA food-contact packaging substrates where petroleum-based plastic approval pathways face parallel qualification delays. Target India's PLI-subsidized jute-PP compounding capacity for export-oriented joint ventures with European distributors. Lead with water-based polyurethane alternatives to bypass fourteen-month EPA thermoset permitting queues in Michigan and Ohio.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap compounders with captive fiber supply and EASA airworthiness trial progress. Long-term viability hinges on automated fiber placement adoption rates in Toulouse and Hamburg aerospace clusters. Watch hybrid natural-synthetic layup qualification in wind turbine nacelles as the inflection signal for scaled aerospace migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Networks | Bavarian hemp cooperatives secure consistent bast fiber geometry for KBA-certified automotive programs. |
| Automated Fiber Placement Adoption | Toulouse and Hamburg tier suppliers cut layup labor by forty percent in flax-epoxy secondary structure trials. |
| Water-Based Polyurethane Transition | Michigan and Ohio processors bypass EPA phenolic resin curing permit delays for construction markets. |
| FDA Food-Contact Qualification | Molded fiber tray producers open retail produce pathways distinct from petroleum-based plastic approvals. |
| Hybrid Natural-Synthetic Layup Development | Flax-glass interlayers balance wind turbine stiffness targets with end-of-life incineration compliance. |
Research Methodology
Document review covered ECHA REACH guidance, EPA volatile organic compound guidelines, and FDA food-contact assessment protocols, complemented by interviews with Tier 1 automotive procurement managers, compression molding plant engineers, and technical fiber processing cluster directors. Secondary validation drew from customs trade data, SEC filings of listed building products manufacturers, and BIS quality standards documentation. Bottom-up fiber cultivation and compounding capacity estimates were triangulated against top-down automotive interior panel demand projections.
Cross-referencing historical qualification timeline compression against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include bast fiber type, end-use application, processing technique, and regional regulatory cluster. CAGRs were derived from demand elasticity analysis against EU Green Deal carbon border adjustment implementation. Industry-specific inputs incorporated KBA vehicle certification requirement evolution and MIIT industrial standards for bio-based materials.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to flax yield volatility from climate patterns and biodegradability certification fragmentation across ISO 17088, EN 13432, and ASTM D6400 standards. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Abaca Fiber Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Sugarcane Fiber Bowls Market
Natural Fibers
Indonesia Textiles Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Acoustic Cotton Market
Natural Fibers
Silk Textiles Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
North America Cotton Market
Natural Fibers
North America Alpaca Fiber Market