
 Thailand Textile Market | 2026-2036
Thailand Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Textile Market Outlook
Thailand's Board of Investment incentive framework is consolidating the cost-of-entry calculus for new textile investments by tying tax holidays to environmental compliance benchmarks. Thai Toray Textile Mills Public Company Limited leverages its synthetic fiber expertise to dominate technical textile supply for automotive seating applications. Luckytex (Thailand) Public Company Limited anchors its competitive position through integrated dyeing and finishing capabilities that sustain margin control across cotton and blended fabric lines.
Thailand textiles encompass woven, knitted, and non-woven materials engineered from natural and synthetic fibers for apparel, industrial, and household applications, with technical specifications ranging from 10-200 denier filament counts and tensile strengths calibrated to end-use performance standards. Polyester leads product type volume due to its cost-efficiency in sportswear and upholstery applications, while silk retains premium positioning in fashion exports to Japan and European markets. Technical textiles within the application dimension represent the fastest-expanding margin pool, driven by automotive airbag fabric and geotextile demand from Thailand's infrastructure pipeline.
Thailand's Ministry of Industry enforces wastewater discharge standards under the Factory Act that shape dyehouse location decisions and capital expenditure timelines. The Thai Industrial Standards Institute certifies fiber content labeling and flammability protocols that govern export access to EU and US destinations. Stakeholders must monitor how the Eastern Economic Corridor's utility pricing and environmental clearance timelines influence site selection trade-offs between coastal provinces and Bangkok periphery zones.
Market Dynamics
Thailand's Board of Investment incentive framework is consolidating capital allocation toward green manufacturing by tying tax holidays to environmental compliance benchmarks. This regulatory mechanism is redirecting investment flows from conventional dyeing operations toward integrated textile parks with captive wastewater treatment.
Growth Catalysts
- BOI Green Manufacturing Incentives:Thailand's Board of Investment offers eight-year tax exemptions for facilities achieving ISO 14001 certification and zero liquid discharge standards, accelerating capital deployment into recycled polyester capacity.
- Automotive Technical Textile Demand:Airbag fabric and seat upholstery specifications from Thailand's vehicle assembly plants are pulling synthetic fiber innovation toward higher tenacity polyester and nylon blends.
- Eastern Economic Corridor Clustering:Integrated textile parks in Chonburi and Rayong provinces concentrate dyeing, weaving, and finishing operations within single utility zones, compressing logistics costs and environmental clearance timelines.
Market Restraints
- Petrochemical Feedstock Volatility:Purified terephthalic acid and monoethylene glycol price swings from Thai Oil and PTT Global Chemical operations compress margin predictability for polyester spinners.
- Chinese Synthetic Fiber Import Pressure:Low-cost polyester filament yarn from Zhejiang and Jiangsu provinces displaces domestic Thai production in commodity apparel applications.
- Factory Act Wastewater Standards:Thailand's Ministry of Industry enforces biological oxygen demand and chemical oxygen demand discharge limits that extend capital expenditure timelines for new dyehouse construction by 18-24 months.
Strategic Opportunities
- Technical Textile Underpenetration:Geotextile demand from Thailand's infrastructure pipeline—including high-speed rail and flood management projects—remains underserved by domestic woven polypropylene and polyester manufacturers.
- Silk Premium Export Channels:Japanese department store buyers and European luxury houses are consolidating supplier relationships with Thai silk weavers in Nakhon Ratchasima and Khon Kaen provinces for traceable, hand-reeled fiber.
- Digital Printing Convergence:Integration of reactive ink formulations with single-pass print heads is enabling Bangkok-based converters to bypass rotary screen setup costs for short-run fashion orders.
Industry Challenges
- Dye Chemist Talent Scarcity:Thailand's technical education pipeline produces insufficient color matching and formulation specialists to staff expanded EEC textile park operations.
- EU REACH Compliance Timelines:Thai Industrial Standards Institute certification for fiber content labeling and restricted substance testing creates 90-120 day delays for first-time exporters to European markets.
- Legacy ERP Integration Friction:Family-owned mills in Samut Prakan and Pathum Thani provinces face data migration complexity when connecting traditional inventory systems to customer EDI platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Textile Market |
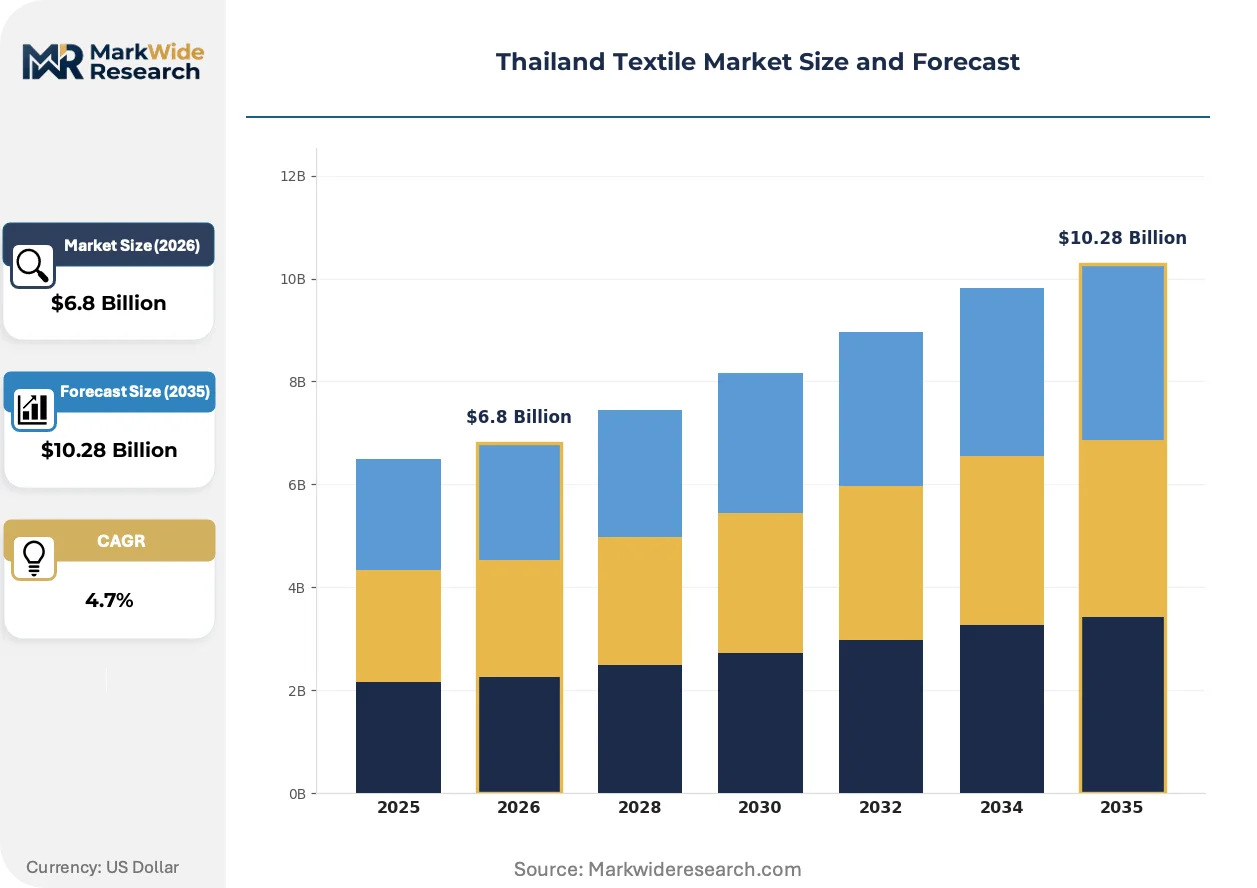
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Silk, Wool End User: Apparel Manufacturers, Home Textiles, Automotive, Industrial Application: Fashion, Upholstery, Technical Textiles, Bedding Distribution Channel: Online Retail, Wholesale, Direct Sales, Export |
| Companies Covered | Thai Textile Industry Public Company Limited, Luckytex (Thailand) Public Company Limited, Thanulux Public Company Limited, Erawan Textile Co Ltd, Thai Toray Textile Mills Public Company Limited, Textile Prestige Public Company Limited, Nan Yang Textile Group, High-Tech Apparel Co Ltd, Thai Rayon Public Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Textile Market Strategic Shifts
Digitization of color development and distributed manufacturing networks are compressing traditional sample-to-bulk timelines. Thai converters are reconfiguring production workflows around these capabilities.
Digital textile printing is decentralizing production geography by eliminating rotary screen cylinder fabrication and enabling same-day color approval. Bangkok-based fashion converters and automotive trim suppliers are adopting single-pass inkjet systems at 15-20% annual replacement rates for screen printing capacity. This technology is decentralizing order fulfillment from centralized dyehouses to satellite print facilities in provincial industrial zones.
Thailand's Ministry of Industry has tightened Factory Act enforcement for biological oxygen demand and chemical oxygen demand discharge parameters, mandating membrane bioreactor upgrades for existing wet processing facilities. Dyeing operations in Samut Prakan face 30-40% capital surcharge compliance costs versus greenfield EEC installations. Integrated textile parks in Chonburi and Rayong are responding with shared centralized effluent treatment infrastructure to distribute compliance burden.
Automotive seating suppliers are consolidating vendor lists around vertically integrated fiber-to-fabric converters capable of simultaneous flammability, abrasion, and colorfastness certification. Tier-1 seat assemblers in the Eastern Economic Corridor are replacing fragmented yarn, weaving, and finishing procurement with single-source technical textile contracts. This concentration is most visible in Rayong province, where Toyota and Honda assembly plants have reduced approved airbag fabric suppliers from twelve to four over the past five years.
Thailand Textile Market Segmentation
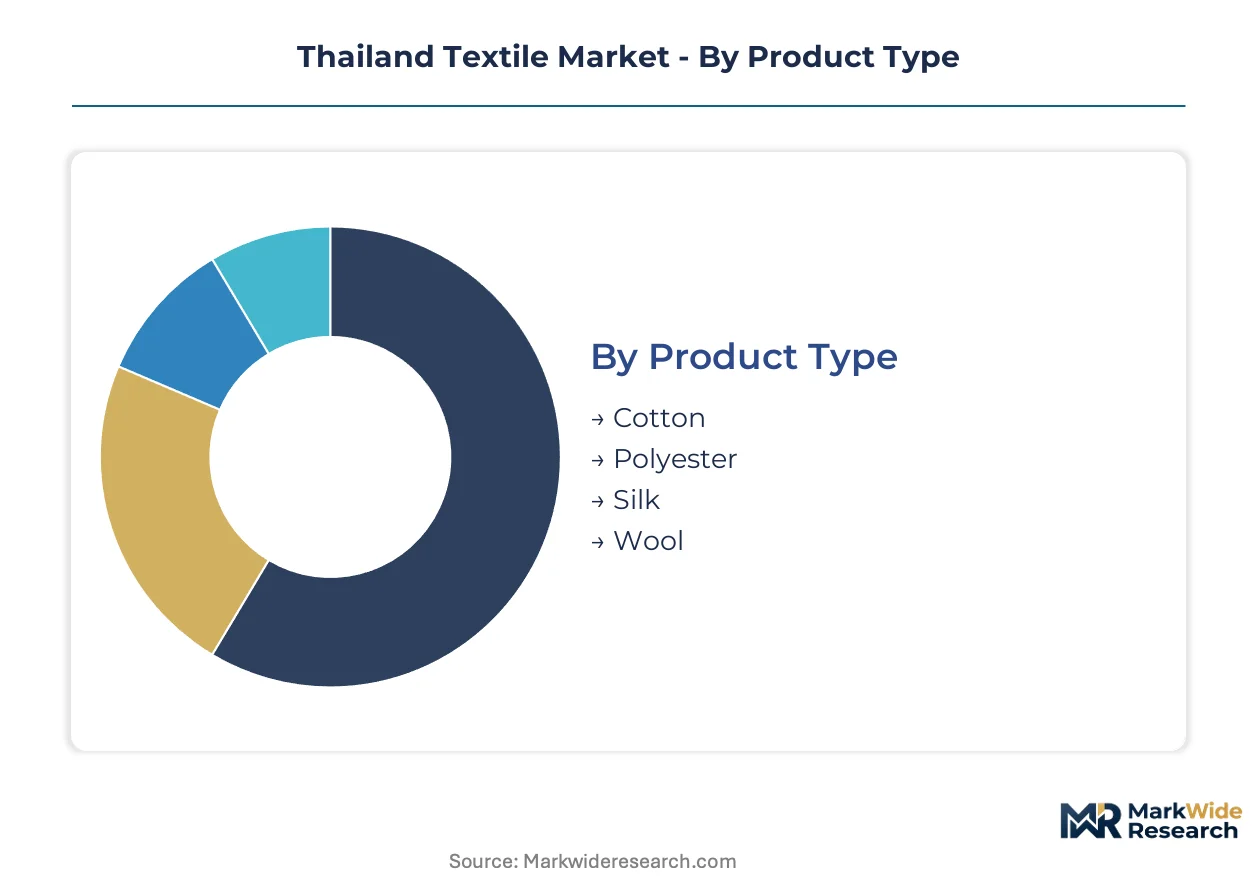
Thailand's textile market segmentation reflects divergent buyer priorities across synthetic versus natural fiber preferences, technical performance specifications, and channel access economics. Understanding these fault lines enables targeted capacity allocation and margin capture strategies.
Product Type:
Buyers differentiate primarily on cost-efficiency versus premium positioning, with procurement teams trading off petrochemical price exposure against artisanal supply security.
- Polyester:Synthetic polymer fiber engineered from purified terephthalic acid and monoethylene glycol with 10-150 denier filament counts. Demand concentrates in Bangkok-area sportswear converters and Eastern Economic Corridor automotive seating plants, where Thai Oil feedstock proximity compresses working capital cycles.
- Cotton:Cellulosic staple fiber with staple lengths of 25-40mm for ring-spun yarn applications. Domestic spinners in Samut Prakan source from Board of Investment-approved ginning facilities in Kanchanaburi, though Pakistani and Indian import competition constrains local seed cotton premiums.
- Silk:Sericin-coated fibroin filament from Bombyx mori cocoons, graded by momme weight for luxury apparel. Nakhon Ratchasima weavers supply Japanese department store buyers seeking traceable, hand-reeled fiber with ISO-certified reeling houses.
- Wool:Keratin-based animal fiber imported primarily from Australian Merino clips for limited suiting and knitwear applications in Bangkok's bespoke tailoring district.
Polyester leads volumes today; silk is gaining share fastest in export value terms.
End User:
Volume concentration varies sharply between cyclical fashion procurement and long-term automotive supply contracts with divergent qualification timelines.
- Apparel Manufacturers:Cut-make-trim operations in Greater Bangkok and Chiang Mai sourcing woven and knitted fabrics for fast-fashion and mid-market retail chains. Margin pressure from Chinese synthetic fiber imports forces converters toward digital printing and quick-turn sample capabilities.
- Automotive:Tier-1 seating and airbag fabric suppliers in Rayong province serving Toyota, Honda, and Isuzu assembly plants. Technical specifications require simultaneous flammability, abrasion, and colorfastness certification that consolidates vendor lists around vertically integrated fiber-to-fabric converters.
- Home Textiles:Curtain, upholstery, and decorative fabric finishers in Pathum Thani and Nonthaburi provinces targeting domestic retail and ASEAN export markets.
- Industrial:Geotextile, filtration, and conveyor belt fabric consumers from Thailand's infrastructure pipeline and manufacturing sector.
Apparel manufacturers absorb the highest fabric tonnage; automotive procurement is expanding most quickly on a value-per-kilogram basis.
Application:
Performance requirements stratify procurement into commodity volume plays versus specification-driven technical contracts with divergent margin profiles.
- Technical Textiles:Engineered fabrics for load-bearing, protective, or functional applications including automotive airbags, geotextiles, and industrial filtration media. Thailand's high-speed rail and flood management infrastructure projects are pulling woven polypropylene and polyester demand that domestic manufacturers currently underserve.
- Fashion:Seasonal apparel fabrics across woven shirting, denim, and knitted jersey constructions. Bangkok-based converters are adopting single-pass digital inkjet systems to bypass rotary screen setup costs for short-run orders.
- Upholstery:Heavy-duty woven and knitted fabrics for residential, commercial, and automotive seating applications with abrasion resistance specifications.
- Bedding:Sheetings, pillowcases, and mattress tickings requiring specific thread counts and finishing treatments for softness and durability.
Fashion commands the largest volume position; technical textiles show the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects order size economics, certification requirements, and geographic proximity to manufacturing clusters.
- Export:Containerized shipment of finished fabrics and made-ups to Japan, EU, and US markets through Bangkok Port and Laem Chabang. Thai Industrial Standards Institute certification for fiber content labeling and restricted substance testing creates 90-120 day delays for first-time EU market entrants.
- Wholesale:Bulk fabric distribution through Pratunam and Sampeng market intermediaries serving domestic garment factories and regional traders.
- Direct Sales:Mill-direct relationships between integrated textile parks and large apparel or automotive customers, compressing margin extraction by intermediaries.
- Online Retail:E-commerce platforms for small-lot fabric sales to independent designers, home sewers, and micro-manufacturers, currently marginal in revenue contribution.
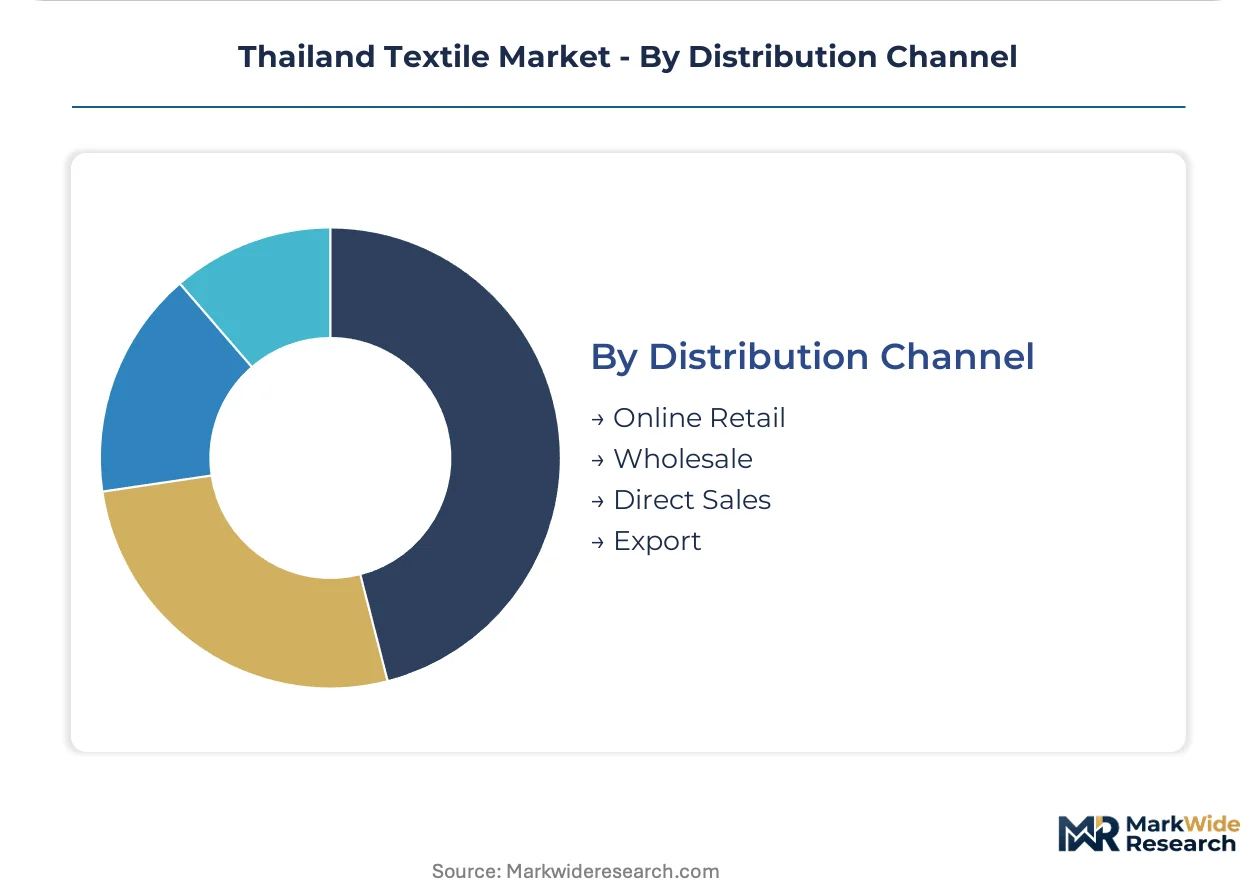
Export channels dominate revenue value; direct sales are climbing fastest as Eastern Economic Corridor clustering reduces customer acquisition friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai textile manufacturing traces its modern lineage to 1950s state-led import substitution policies that established Bangkok's dyeing and weaving infrastructure. The sector subsequently migrated toward export orientation during 1980s Board of Investment incentive waves, concentrating capacity in the Greater Bangkok periphery before dispersing to coastal provinces under environmental compliance pressures.
Greater Bangkok Metropolitan Region
Apparel converters in Pathum Thani and Samut Prakan drive woven fabric consumption for fast-fashion supply chains. Thailand's Ministry of Industry enforces Factory Act wastewater discharge standards that extend dyehouse permitting timelines by 18-24 months. Digital printing adoption clusters in Bangkok's Rangsit and Lat Krabang industrial zones where single-pass inkjet systems bypass rotary screen setup costs.
Eastern Economic Corridor
Automotive seating and airbag fabric specifications from Rayong assembly plants pull synthetic fiber demand toward higher tenacity polyester blends. Thailand's Board of Investment offers eight-year tax exemptions for ISO 14001-certified facilities achieving zero liquid discharge standards. Integrated textile parks in Chonburi concentrate captive wastewater treatment, dyeing, and finishing operations within single utility zones.
Northeastern Region
Silk weaving in Nakhon Ratchasima and Khon Kaen provinces supplies Japanese department store buyers seeking traceable, hand-reeled fiber. The Thai Industrial Standards Institute certifies fiber content labeling for export access to EU markets. Artisan clusters around Pak Thong Chai maintain ISO-certified reeling houses that consolidate supplier relationships with European luxury houses.
Central Plains
Cotton ginning operations in Kanchanaburi feed domestic spinners under Board of Investment-approved agricultural processing incentives. Pakistani and Indian import competition constrains local seed cotton premiums. Ginning capacity expansion aligns with Samut Prakan spinner demand for 25-40mm staple lengths in ring-spun yarn applications.
Thailand Textile Market Competitive Environment
The competitive structure tilts toward integrated synthetic fiber specialists with captive petrochemical feedstock access. Market concentration is moderate, with tier-1 players commanding automotive technical textile contracts while fragmented regional mills serve commodity apparel applications. Two strategic archetypes dominate: vertically integrated fiber-to-fabric converters securing multi-year automotive supply agreements, and specialized dyeing houses leveraging digital printing for short-run fashion orders. Capacity expansion and backward integration into polymer production represent the dominant competitive moves.
Within the integrated synthetic fiber tier, Thai Toray Textile Mills Public Company Limited and Thai Rayon Public Company Limited exemplify archetypes with petrochemical feedstock proximity. Luckytex (Thailand) Public Company Limited occupies a position among dyeing and finishing specialists sustaining margin control across cotton and blended fabric lines. These entities represent the spectrum from upstream polymer integration to downstream wet processing specialization that characterizes Thailand's competitive configuration.
| Leading Market Players |
|---|
| Thai Textile Industry Public Company Limited |
| Luckytex (Thailand) Public Company Limited |
| Thanulux Public Company Limited |
| Erawan Textile Co Ltd |
| Thai Toray Textile Mills Public Company Limited |
| Textile Prestige Public Company Limited |
| Nan Yang Textile Group |
| High-Tech Apparel Co Ltd |
| Thai Rayon Public Company Limited |
| Others |
Value Chain & Pricing Dynamics
Tier-1 automotive seating suppliers in Rayong province command contract-based long-term offtake agreements that compress margin volatility for polyester spinners while fragmenting pricing power among Bangkok apparel converters facing spot-market cotton volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified technical textile contracts from commodity apparel fabrics and unbranded wholesale lots. Price differentiation rests on certification grade and volume scale, with automotive procurement teams least sensitive to unit cost. Cost compression in commodity polyester apparel lines is intensifying because Chinese filament yarn imports displace domestic Thai production.
Supply Chain Analysis
Post-consumer textile collection for mechanical recycling flows through Bangkok's Pratunam wholesale district, though reverse logistics infrastructure remains underdeveloped compared to forward distribution. Geographic supply concentrates in Thailand, China, and Vietnam for woven and knitted finished goods. Raw material dependencies draw from purified terephthalic acid and monoethylene glycol feedstocks, plus imported Australian Merino wool for limited suiting applications. Single-source vulnerability to PTT Global Chemical's aromatics output creates petrochemical price transmission risk. Distribution runs through mill-direct relationships with EEC-integrated textile parks and containerized export via Laem Chabang.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through BOI green manufacturing incentives that reward environmental compliance with extended tax holidays, compressing effective production costs for certified operators.
For Market Incumbents: Anchor defensive positioning by deepening backward integration into recycled polyester chip production and securing captive wastewater treatment capacity within EEC textile parks. Chinese synthetic fiber import pressure demands consolidation of automotive technical textile vendor lists around fiber-to-fabric certification capabilities. For New Entrants and Emerging Players: Enter via geotextile supply for Thailand's high-speed rail and flood management infrastructure pipeline, where domestic woven polypropylene and polyester manufacturers currently underserve demand. Digital printing convergence for short-run Bangkok fashion orders offers the most penetrable entry angle, bypassing rotary screen setup cost barriers. For Investors and Strategic Acquirers: Automotive Tier-1 seating suppliers are the most active acquirer in this space, consolidating fragmented weaving and finishing capabilities to secure single-source technical textile contracts. Long-term viability favors vertically integrated fiber specialists with ISO 14001 certification and EEC utility zone access. Monitor BOI incentive renewal timelines and Factory Act enforcement intensity for inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Polyester Chip Production | Captures margin from petrochemical feedstock volatility while qualifying for BOI green manufacturing tax exemptions. |
| EEC Textile Park Capacity Expansion | Compresses logistics costs and environmental clearance timelines through shared centralized effluent treatment infrastructure. |
| ISO 14001 and Zero Liquid Discharge Certification | Unlocks eight-year tax holidays and consolidates vendor list positioning for automotive technical textile contracts. |
| Digital Printing Technology Adoption | Enables same-day color approval and short-run order fulfillment without rotary screen cylinder fabrication costs. |
| Silk Traceability and Hand-Reeled Fiber Certification | Secures premium export channels to Japanese department store buyers and European luxury houses in Nakhon Ratchasima. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with textile mill operations directors, automotive Tier-1 procurement managers, dyehouse compliance officers, and Board of Investment incentive specialists with secondary validation against Thai Industrial Standards Institute certification records, Factory Act enforcement disclosures, Eastern Economic Corridor development authority filings, and customs trade data. Bottom-up capacity surveys and top-down consumption estimates were triangulated to anchor volume and value outputs.
Segment-weighting approaches modeled product type splits across polyester, cotton, silk, and wool, end-user concentrations in apparel manufacturing and automotive supply chains, application stratification between technical textiles and fashion fabrics, and distribution channel economics across export, wholesale, direct sales, and online retail. CAGRs were derived from trend extrapolation adjusted for incentive-driven capacity deployment and regulatory compliance cost trajectories. Forecast inputs incorporated BOI tax holiday renewal assumptions and Factory Act wastewater standard enforcement intensity.
Inputs from primary mill interviews and regulatory filings were available through the study window; gaps in real-time dyehouse compliance cost data and unreported digital printing adoption rates introduce uncertainty bands around near-term margin compression estimates. Practitioners should monitor PTT Global Chemical feedstock pricing announcements and EU REACH compliance timeline changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Green Fibers Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Silk Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Hessian Sacks Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Down and Feather Market
Natural Fibers
North America Alpaca Fiber Market
Natural Fibers
North America Cotton Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Silk Mask Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Sugarcane Fiber Bowls Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Cellulose Fiber Market