
 Acoustic Cotton Market | 2026-2036
Acoustic Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Cotton Market Analysis
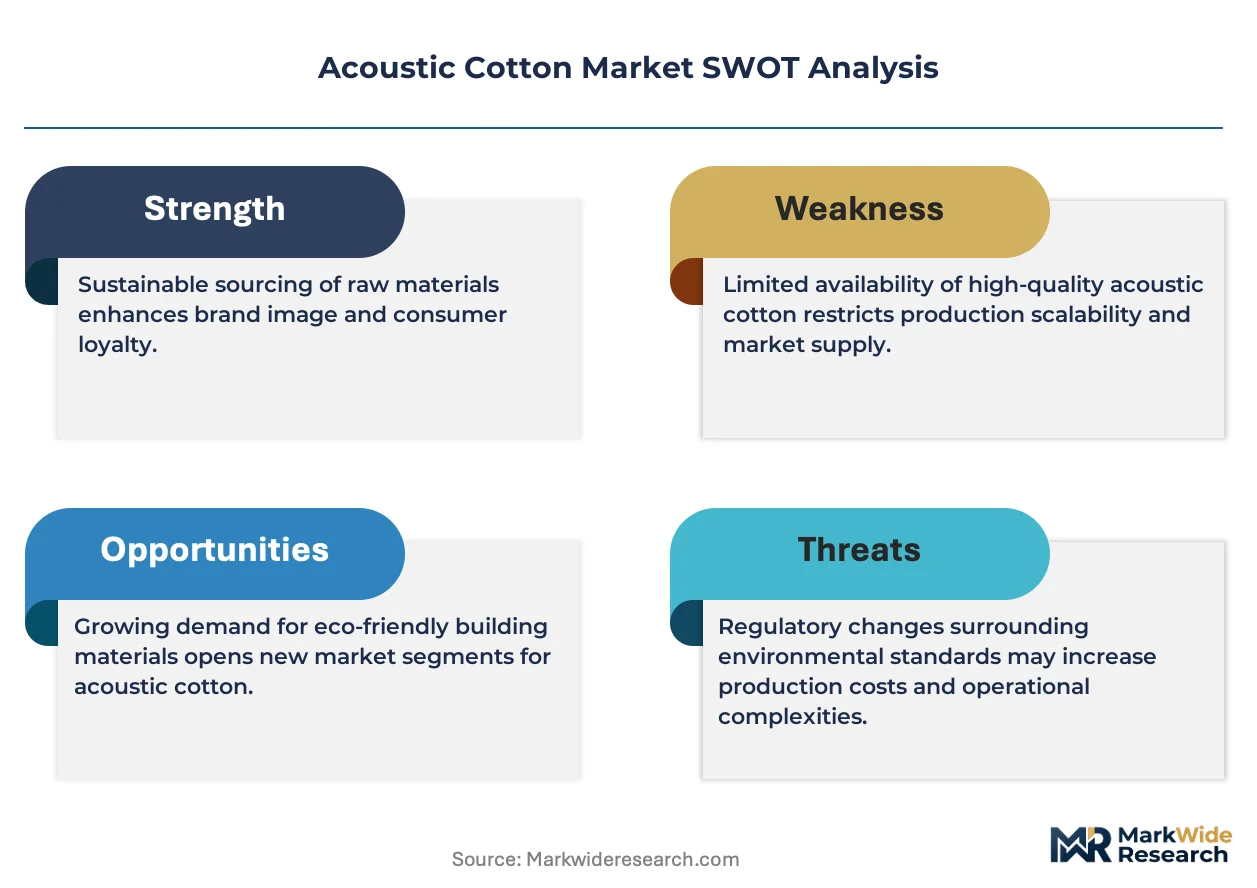
Multi-source procurement toward blended fiber suppliers is rebalancing supply chain risk across the acoustic cotton industry. Owens Corning leverages its mineral wool infrastructure to anchor North American distribution of cotton-blend acoustic products. Saint-Gobain competes through integrated building envelope expertise that extends into suspended ceiling systems. Bonded Logic specializes in recycled denim-based acoustic cotton, occupying a sustainability-driven niche with strong channel control in green building specification.
Acoustic cotton comprises natural or recycled cellulosic fibers engineered to density specifications between 48–96 kg/m³, delivering noise reduction coefficients of 0.70–1.05 across speech-frequency ranges for commercial and residential sound control. Panels dominate material volume due to standardized sizing for retrofit office installations, while baffles represent the fastest-growing product type as open-plan commercial architecture expands. Recycled fibers command expanding specification share under corporate sustainability mandates, though cotton-polyester blends retain margin pools in premium studio and auditorium applications where fire resistance ratings tighten.
The EPA oversees VOC emissions standards for indoor air quality that constrain adhesive and binder chemistries in acoustic cotton manufacturing, while OSHA workplace noise exposure limits directly mandate the material's end-use in industrial and commercial environments. CE marking under the EU Construction Products Regulation governs market access for European imports, testing reaction-to-fire performance that shapes product formulation decisions. Stakeholders must monitor evolving bio-based content certification schemes and building code harmonization between national fire safety and acoustic performance standards.
Market Dynamics
Recycled fiber specification mandates across commercial construction are compressing virgin cotton demand while elevating blended-fiber product premiums in retrofit building stock.
Growth Catalysts
- EU Green Deal embodied carbon caps:Building product procurement rules in member states now penalize high-carbon insulation alternatives, redirecting specification toward recycled denim and post-industrial cotton fiber treatments.
- Open-plan commercial architecture:Ceiling baffle demand from co-working space developers is accelerating replacement cycles in existing office inventory across Germany and the Netherlands.
- OSHA workplace noise enforcement:Industrial facility retrofits in the US Midwest are expanding acoustic treatment coverage to meet revised exposure limits in manufacturing floors.
Market Restraints
- Post-consumer denim supply volatility:Collection infrastructure gaps in North American textile recycling constrain feedstock availability for bonded fiber production.
- Reaction-to-fire certification costs:CE marking under the EU Construction Products Regulation requires expensive testing protocols that exclude smaller regional manufacturers from export markets.
- Mineral wool price competition:Owens Corning's mineral wool infrastructure delivers acoustic performance at lower installed cost in basic commercial applications.
Strategic Opportunities
- India commercial real estate build-out:Green building certification adoption in Mumbai and Bangalore office towers creates first-mover positioning for recycled fiber suppliers.
- Biomass binder chemistry:Bio-based adhesive formulations that eliminate formaldehyde meet emerging indoor air quality standards in California and the EU.
- Direct-to-developer digital specification:Building information modeling integration allows acoustic cotton producers to embed product data directly into architect workflow software.
Industry Challenges
- Acoustic engineer talent scarcity:Specialized expertise in speech-frequency range optimization remains concentrated among legacy building acoustics consultancies.
- Multi-certification timeline compression:Simultaneous pursuit of LEED, BREEAM, and WELL ratings extends product approval cycles for multinational construction projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Cotton Market |
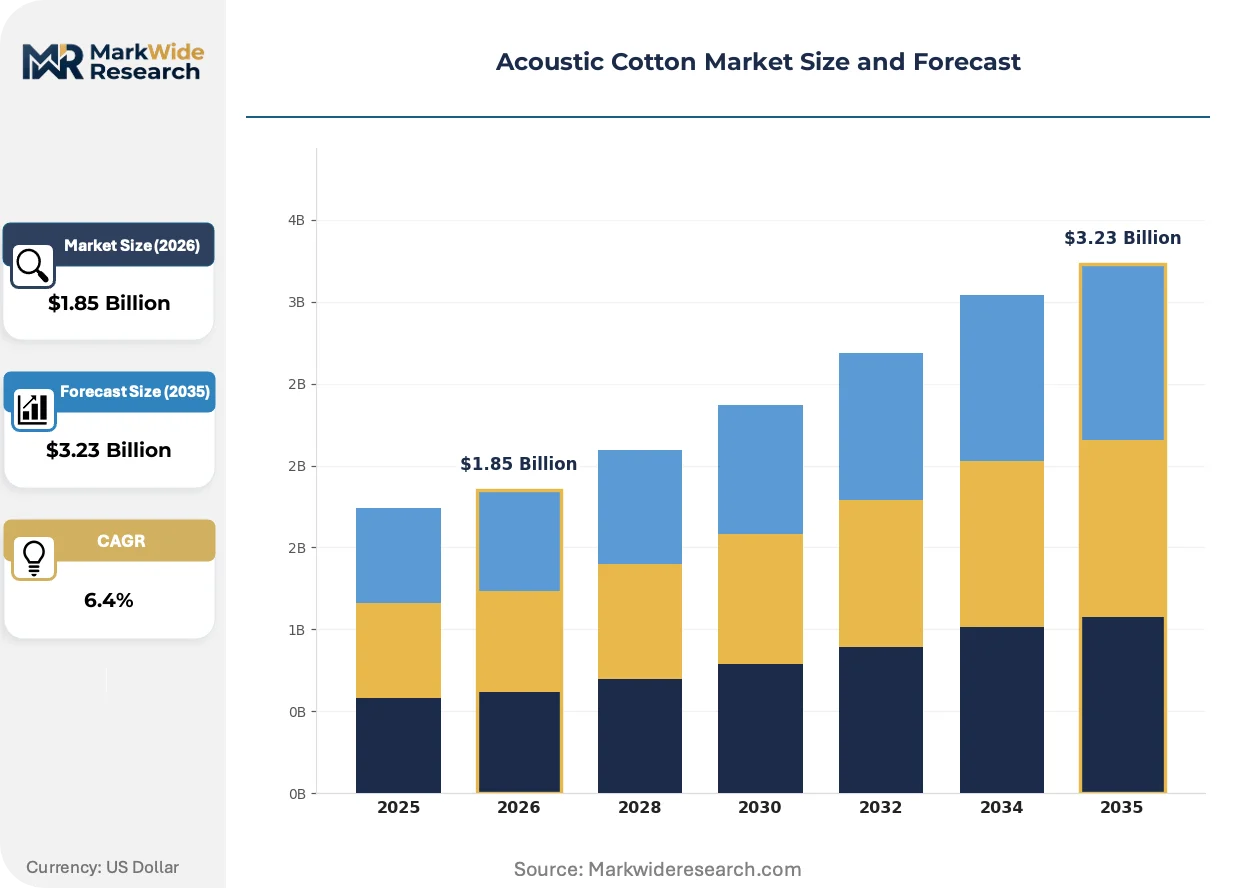
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panels, Tiles, Baffles, Sound Barriers Application: Commercial Spaces, Residential Areas, Studios, Auditoriums Material: Recycled Fibers, Polyester, Cotton, Blended Fabrics Installation Method: Suspended, Wall-Mounted, Free-Standing, Ceiling Tiles |
| Companies Covered | Owens Corning, Saint-Gobain, Johns Manville, Rockwool, Armstrong World Industries, Acoustical Surfaces, ATS Acoustics, Bonded Logic, SoundAway Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Cotton Market Emerging Trajectories
Digital specification tools and bio-based chemistry are compressing traditional channel structures while elevating performance transparency as a competitive differentiator in commercial building materials.
Automated density control systems using real-time fiber weight sensors are automating panel production consistency for retrofit office installations. Commercial ceiling contractors in Germany and the US Northeast are specifying these precision-manufactured products to meet guaranteed noise reduction coefficients. The technology is automating quality variance reduction that previously required manual batch testing.
REACH chemical restriction expansions are forcing reformulation of legacy flame retardant binders in European acoustic cotton imports. Manufacturers serving the suspended ceiling segment are accelerating bio-based phosphate ester adoption to maintain market access. German workplace noise directives are tightening enforcement timelines that compress product recertification windows.
Developer-led sustainability scorecards now mandate recycled content disclosure at the specification stage rather than post-bid verification. Architect and contractor procurement teams in the Netherlands and California are disqualifying products without third-party fiber origin certification. This behavioral shift concentrates volume with suppliers maintaining chain-of-custody documentation from textile collection through finished panel.
Acoustic Cotton Market Segmentation
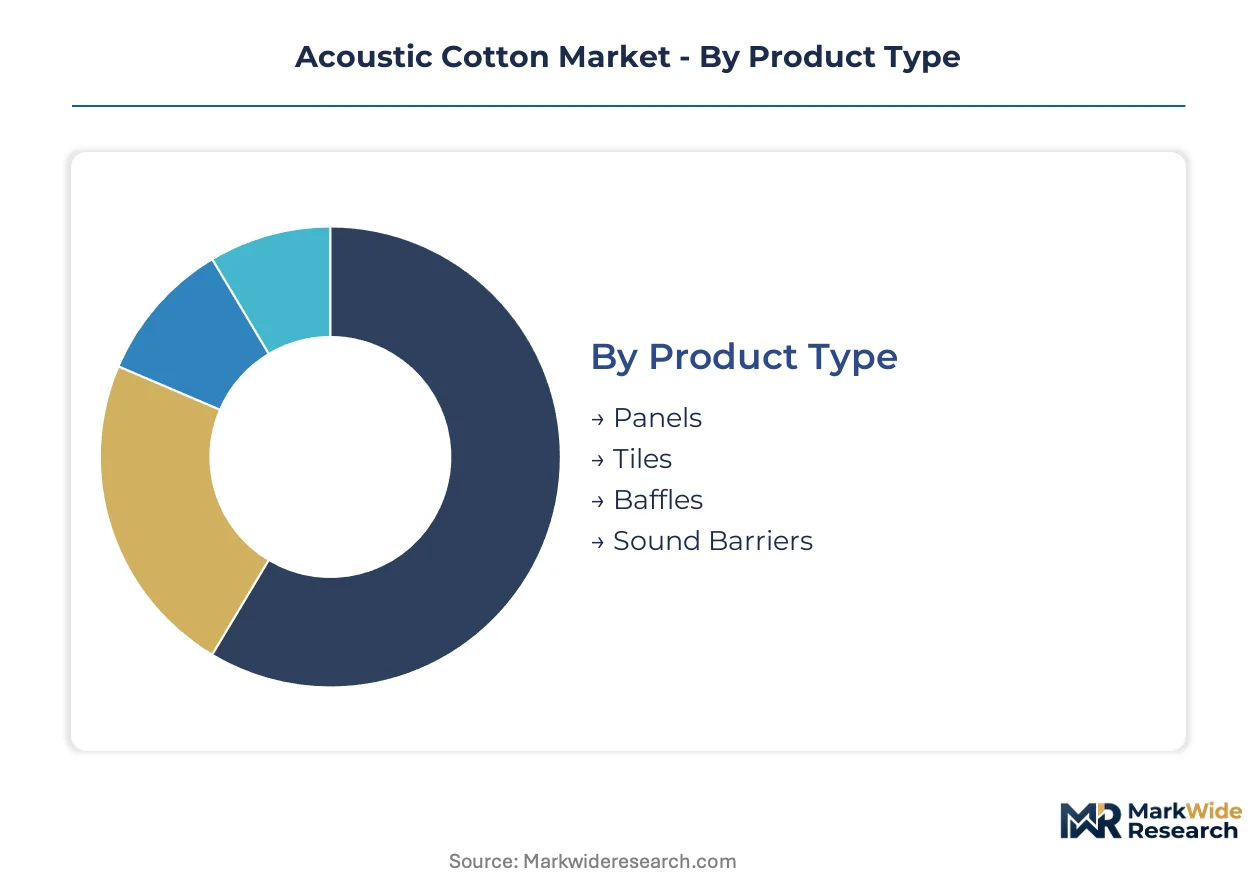
Segmentation in acoustic cotton reflects divergent paths between standardized retrofit solutions and architecturally integrated custom systems. Specification behavior varies sharply across installation complexity and material provenance, with sustainability mandates now filtering procurement decisions at every tier.
Product Type:
Standardized dimensions dominate volume flows while custom geometries command specification premiums in architecturally distinctive spaces.
- Panels:Engineered to density specifications between 48–96 kg/m³ with standardized 600×600 mm and 600×1200 mm dimensions. Demand concentrates in German office retrofit cycles driven by workplace noise directive enforcement and guaranteed noise reduction coefficient requirements.
- Baffles:Vertically suspended elements with variable depth profiles for open-plan ceiling treatments. Co-working space developers in the Netherlands and US Northeast specify these for speech-frequency control in exposed-structure architecture, accelerating replacement cycles in existing inventory.
- Tiles:Grid-compatible modules for suspended ceiling systems.
- Sound Barriers:High-mass composite assemblies for partition isolation.
Most installed capacity flows through Panels. Expansion is steepest in Baffles.
Application:
End-use concentration tracks construction cycle timing and regulatory enforcement intensity across building typologies.
- Commercial Spaces:Open-plan offices, co-working facilities, and corporate headquarters requiring speech privacy and HVAC noise control. US Midwest industrial retrofits under revised OSHA exposure limits are expanding treatment coverage in manufacturing floors adjacent to administrative zones.
- Studios:Recording and broadcast facilities demanding precise reverberation control across 125–4000 Hz. Premium cotton-polyester blends retain specification share where fire resistance ratings tighten in Los Angeles and Nashville production facilities.
- Residential Areas:Multi-family and single-family home theater and home office installations.
- Auditoriums:Performance and assembly venues with specialized acoustic design requirements.
Commercial Spaces absorb the majority of production volume. Studios show the steepest specification premium expansion.
Material:
Feedstock provenance now functions as a procurement filter with chain-of-custody documentation displacing post-bid verification.
- Recycled Fibers:Post-consumer denim and post-industrial cotton processed to engineered density. EU Green Deal embodied carbon caps in member states penalize high-carbon alternatives, redirecting specification toward certified recycled content with third-party fiber origin documentation.
- Blended Fabrics:Cotton-polyester combinations balancing acoustic performance with fire resistance. Premium studio and auditorium applications in California specify these for compliance with evolving indoor air quality standards while maintaining 0.70–1.05 noise reduction coefficients.
- Polyester:Virgin synthetic fiber with consistent mechanical properties.
- Cotton:Virgin natural fiber with established acoustic performance characteristics.
Recycled Fibers now dominate green building specifications. Blended Fabrics retain the highest margin pools.
Installation Method:
Mechanical integration complexity determines contractor specialization requirements and project timeline risk.
- Suspended:Cable- or rod-hung systems for vertical baffle and horizontal cloud installations. German ceiling contractors specify automated density control systems with real-time fiber weight sensors to meet guaranteed performance metrics in commercial retrofit timelines.
- Ceiling Tiles:Grid-compatible modules for conventional suspended ceiling systems. Standardized sizing enables rapid retrofit of existing office inventory across Dutch and Belgian commercial building stock with minimal structural modification.
- Wall-Mounted:Direct-adhered or mechanically fastened panel systems for vertical surfaces.
- Free-Standing:Movable partition and screen systems for flexible space division.
Ceiling Tiles carry the broadest contractor base. Suspended systems are climbing the fastest as open-plan architecture expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost gaps between jurisdictions are redirecting acoustic cotton manufacturing capacity toward regions with streamlined certification pathways and lower embodied-carbon compliance burdens.
Germany
Workplace noise directive enforcement accelerates retrofit cycles in existing commercial building stock across North Rhine-Westphalia. CE marking under the EU Construction Products Regulation mandates reaction-to-fire testing that shapes product formulation decisions for suspended ceiling systems. Frankfurt and Munich office clusters drive specification demand for automated density control panels with guaranteed noise reduction coefficients.
United States
OSHA workplace noise exposure limits mandate acoustic treatment coverage in industrial facility retrofits across the Midwest manufacturing belt. EPA VOC emissions standards constrain adhesive and binder chemistries in domestic manufacturing. Chicago and Detroit industrial corridors expand treatment installations in manufacturing floors adjacent to administrative zones.
Netherlands
Co-working space developers specify vertically suspended baffles for speech-frequency control in exposed-structure architecture. EU Green Deal embodied carbon caps penalize high-carbon insulation alternatives in public procurement. Amsterdam and Rotterdam commercial build-outs concentrate demand for certified recycled fiber content with third-party origin documentation.
India
Green building certification adoption in Mumbai and Bangalore office towers creates first-mover positioning for recycled fiber suppliers. BIS standards govern construction product quality while state-level building codes evolve. Maharashtra and Karnataka commercial real estate clusters drive specification of post-consumer denim-based acoustic treatments.
China
Dual carbon goals redirect building material procurement toward lower-impact insulation alternatives in tier-one city developments. GB standards for indoor environmental quality constrain formaldehyde emissions in finished products. Yangtze River Delta manufacturing zones concentrate domestic capacity for engineered density panels serving regional commercial construction.
Acoustic Cotton Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue sustainability-driven niches and digital specification integration. The vendor base spans mineral wool conglomerates with acoustic cotton line extensions, recycled fiber specialists with captive textile collection networks, and building envelope integrators with suspended ceiling system expertise. Strategic archetypes include scale-driven commodity suppliers, sustainability-certified niche players, and building systems integrators. Capacity expansion and bio-based binder chemistry licensing represent the dominant competitive moves reshaping positioning.
Within the recycled fiber specialist tier, Bonded Logic exemplifies sustainability-driven channel control through post-consumer denim sourcing infrastructure. Among diversified building materials conglomerates, Owens Corning and Saint-Gobain occupy positions that leverage mineral wool distribution networks and integrated envelope expertise respectively. These three anchors illustrate how scale, sustainability certification, and systems integration define competitive differentiation in commercial specification markets.
| Leading Market Players |
|---|
| Owens Corning |
| Saint-Gobain |
| Johns Manville |
| Rockwool |
| Armstrong World Industries |
| Acoustical Surfaces |
| ATS Acoustics |
| Bonded Logic |
| SoundAway Corporation |
| Others |
Supply Flow & Price Mechanics
Captive sourcing of post-consumer denim through controlled textile collection networks anchors both supply security and premium pricing power for recycled fiber specialists serving green building specifications. This backward integration shields margin pools from feedstock volatility while enabling third-party fiber origin certification that commands specification premiums in Dutch and California procurement.
Pricing Analysis
Distributor margin compression in standard panel tiers intensifies as Owens Corning's mineral wool infrastructure delivers acoustic performance at lower installed cost. Three-tier pricing structure across premium, standard, and economy levels separates certified recycled content with chain-of-custody documentation from basic commercial grades. Cost compression in economy tiers reflects mineral wool substitution pressure, while premium studio applications retain pricing power through fire resistance certification. Commercial retrofit contractors show highest price sensitivity; architect-specified custom systems show lowest.
Supply Chain Analysis
Reverse-logistics flows for post-consumer denim collection constrain bonded fiber production capacity across North American manufacturing. Primary supply concentrates in the United States, Germany, and China, with feedstock dependencies on textile recycling infrastructure, bio-based phosphate ester binders, and automated density control equipment. Single-source vulnerability in post-consumer denim collection creates bottleneck risk for recycled fiber specialists. Distribution runs through commercial ceiling contractors and building materials distributors serving retrofit office markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal embodied carbon caps create geographic-arbitrage potential between European markets penalizing high-carbon alternatives and North American markets with slower regulatory alignment.
For Market Incumbents: Deploy bio-based binder chemistry licensing to defend specification share against mineral wool substitution in basic commercial applications. Accelerate automated density control system deployment to meet guaranteed noise reduction coefficient requirements in German workplace noise directive retrofits. Threat: REACH chemical restriction expansions forcing legacy flame retardant reformulation. Lever: captive textile collection network expansion.
For New Entrants and Emerging Players: Begin with Mumbai and Bangalore commercial real estate build-outs where green building certification adoption creates first-mover positioning for certified recycled fiber suppliers. Target co-working space developers specifying vertically suspended baffles for open-plan architecture. Go-to-market: direct-to-developer digital specification through building information modeling integration.
For Investors and Strategic Acquirers: Consolidation pressure builds where CE marking costs exclude smaller regional manufacturers from European export markets. Long-term viability favors suppliers with integrated textile collection infrastructure and bio-based chemistry pipelines. Acquisition target: recycled fiber specialists with captive post-consumer denim sourcing. Signal to watch: BIS standards harmonization with EU reaction-to-fire protocols in Indian commercial construction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Textile Collection | Captive post-consumer denim sourcing secures feedstock for EU Green Deal-compliant production. |
| Bio-Based Binder Chemistry Licensing | REACH-compliant phosphate ester formulations maintain market access under evolving chemical restrictions. |
| Automated Density Control Deployment | Real-time fiber weight sensors guarantee noise reduction coefficients for German directive compliance. |
| Digital Specification Platform Integration | Building information modeling embedding captures architect workflow in commercial retrofit markets. |
| CE Marking Recertification Acceleration | Reaction-to-fire testing protocols preserve European market access for suspended ceiling systems. |
Methodological Framework
Multiple input streams — primary interviews with acoustic product manufacturers, commercial ceiling contractors, and green building specification consultants, alongside secondary validation through EPA VOC emissions filings, EU Construction Products Regulation documentation, and textile recycling trade data — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across product type, material provenance, installation method, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth trajectory analysis incorporating OSHA workplace noise enforcement timelines, EU embodied carbon procurement rule adoption curves, and commercial real estate cycle positioning throughout the forecast period.
Several conditions sit outside the modeled scope, including abrupt REACH chemical restriction expansions, post-consumer denim supply infrastructure collapse, and harmonization failures between national fire safety and acoustic performance standards. Practitioners should monitor BIS standards evolution, biomass binder cost curves, and architect procurement platform adoption for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
Cellulose Fiber Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Global Hemp Fiber Market
Natural Fibers
Organic Cotton Market
Natural Fibers
Green Fibers Market
Natural Fibers
Silk Mask Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Global Rattan Products Market
Natural Fibers
Cellulose Market
Natural Fibers
Silk Fabric Market
Natural Fibers
Jute Bags Market
Natural Fibers
Hessian Sacks Market
Natural Fibers
Silk Stocking Market