
 Textile Staples Market | 2026-2036
Textile Staples Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Staples Market Outlook
Polymer engineering talent scarcity is bifurcating the market into fiber innovators and commodity converters. Lenzing AG leverages its wood-based cellulosic expertise to anchor premium positioning in sustainable staples. Toray Industries sustains technology leadership through advanced polyester and nylon polymerization capabilities. Indorama Ventures controls massive PET recycling streams that extend cost advantages across Asian and European supply bases.
Textile staples are short discrete fibers, typically 25-150 millimeters in length, spun into yarn through carding and drawing processes for woven or knitted fabric construction. Cotton and polyester categories dominate volume, with cotton occupying heritage apparel channels while polyester leads technical applications requiring dimensional stability. The automotive end-use segment represents the fastest-growing demand pool as lightweight nonwoven interior panels displace heavier traditional materials. Upholstery applications command superior margin pools relative to commodity clothing staples due to performance certification requirements and shorter production runs.
REACH chemical registration in Europe, EPA industrial emissions standards in the United States, and China's MEE environmental compliance mandates collectively elevate capital requirements for staple manufacturing facilities. ISO 14001 environmental management certification and OEKO-TEX product safety standards increasingly function as market access prerequisites rather than optional differentiators. Stakeholders must monitor feedstock cost volatility between virgin petrochemicals and mechanically recycled polymers when committing to capacity expansion decisions.
Market Dynamics
EU Green Deal textile sustainability mandates are forcing staple producers to reengineer feedstock sourcing, compressing margins for virgin polyester converters while advantaging mechanical recyclers with established collection infrastructure.
Growth Catalysts
- Automotive Lightweighting Mandates:NHTSA fuel economy standards and EU CO2 fleet targets are accelerating nonwoven staple adoption for interior panels, door trim, and headliners in electric vehicle platforms.
- REACH Chemical Registration Expansion:ECHA's tightening SVHC candidate list is redirecting apparel brands toward OEKO-TEX certified staple suppliers with verified supply chain transparency.
- China's Integrated Spinning Clusters:Zhejiang and Jiangsu province megafacilities are capturing scale efficiencies through captive polymerization-to-yarn production, concentrating export-competitive volume.
Market Restraints
- Petrochemical Feedstock Volatility:Purified terephthalic acid and monoethylene glycol price swings compress converter margins when long-term apparel contracts fix staple pricing.
- Collection Infrastructure Gaps:Post-consumer polyester textile-to-textile recycling remains concentrated in European sorting facilities, limiting recycled staple feedstock availability in Asian manufacturing bases.
- Performance Certification Barriers:Automotive OEMs require 18-24 month validation cycles for new staple grades, freezing out smaller producers from technical textile margin pools.
Strategic Opportunities
- India Technical Textiles Push:PLI scheme incentives for geotextiles and agrotextiles are creating demand for high-tenacity polyester staples in infrastructure and agricultural applications.
- Bio-Based Cellulosic Convergence:Wood pulp and agricultural residue feedstocks combined with closed-loop solvent recovery are opening premium positioning beyond petroleum-dependent categories.
- Direct-to-Mill Digital Sourcing:Blockchain-tracked staple procurement platforms are disintermediating traditional trader networks, capturing margin for integrated manufacturers with verified sustainability credentials.
Industry Challenges
- Polymer Engineering Talent Scarcity:Melt spinning and bicomponent fiber expertise concentrates at legacy producers, constraining new entrant scale-up in advanced staple categories.
- Multi-Standard Compliance Burden:Simultaneous ISO 14001, OEKO-TEX, and GRS certification requirements extend facility qualification timelines and audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Staples Market |
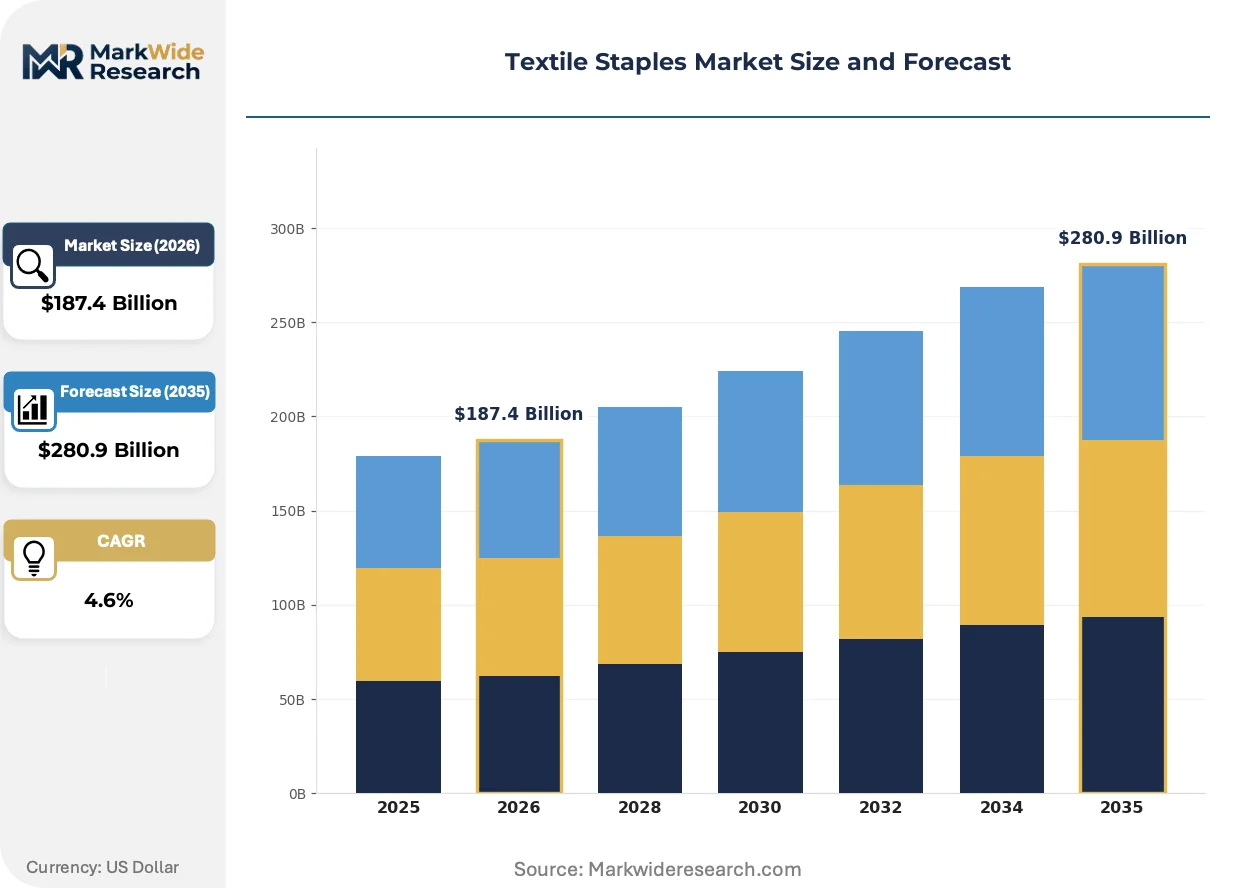
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $280.9 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Nylon, Wool End Use: Apparel, Home Textiles, Industrial, Automotive Distribution Channel: Online Retail, Specialty Stores, Wholesale, Supermarkets Application: Upholstery, Clothing, Filters, Nonwovens |
| Companies Covered | Lenzing AG, Toray Industries, Indorama Ventures, Reliance Industries, DuPont, Invista, International Fibers Group, W. Barnet GmbH & Co. KG, Aditya Birla Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Staples Market Strategic Shifts
Mechanical recycling technology advances and bio-based polymerization routes are compressing the cost gap between virgin and sustainable staples, while digital traceability systems reshape procurement verification requirements across automotive and apparel supply chains.
Microdenier bicomponent staple technology is miniaturizing fiber cross-sections to below 0.5 denier per filament, enabling ultrafine nonwoven surfaces for filtration and hygiene applications. Automotive air filtration suppliers and premium wipe manufacturers are adopting these grades at accelerated qualification paces. The technology is miniaturizing pore structures in meltblown media, displacing glass microfiber in HVAC and cabin air applications where weight reduction carries fuel economy credits.
EU Green Deal circular economy action plan textile strategy mandates extended producer responsibility schemes across France, Germany, and Netherlands by 2025. Separate collection and recycling targets for post-consumer textiles are forcing apparel brands to design for recyclability, specifying mono-material staple constructions. Premium outerwear and workwear segments are responding fastest, locking in multi-year supply agreements with verified recycled staple producers to secure compliance-ready inventory.
Automotive Tier 1 seating suppliers are consolidating staple procurement through certified sustainability scorecards rather than spot-market purchasing. Mill-direct relationships with polymerization assets are replacing distributor intermediaries for high-volume interior programs. This pattern is most visible in Germany and Czech Republic manufacturing corridors, where BMW, Volkswagen, and Skoda facilities enforce supplier consolidation to reduce audit burden and traceability cost.
Textile Staples Market Segmentation
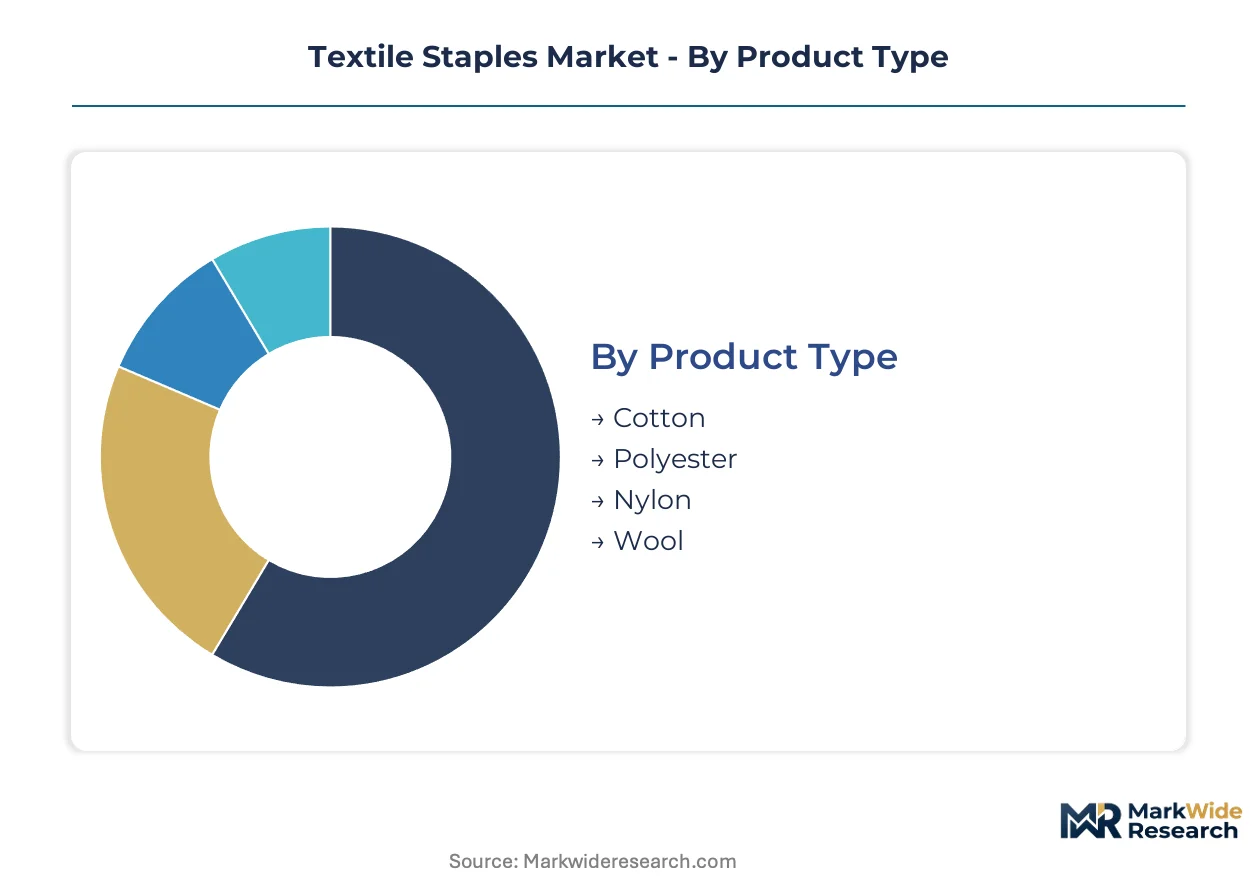
Segmentation in textile staples reveals how substitution pressures reshape procurement patterns across fiber categories and end-use specifications. Distinct technical requirements in automotive versus apparel channels create divergent margin structures that reward specialized production capabilities.
Product Type:
Polyester staples face intensifying displacement risk from mechanically recycled alternatives as EU Green Deal mandates tighten virgin polymer economics, while cotton confronts land-use competition from food crops and synthetic substitutes.
- Polyester:Petroleum-derived polymer staple dominates technical applications requiring dimensional stability and moisture resistance. Demand concentrates in Zhejiang province spinning clusters serving export-oriented apparel and automotive supply chains, with recycled feedstock qualification now mandatory for EU-bound volumes.
- Cotton:Cellulosic natural fiber retains heritage positioning in premium apparel channels despite water-intensive cultivation constraints. Indian and US agricultural bases supply ginning operations, though price volatility against synthetic alternatives compresses spinning margins in commodity clothing segments.
- Nylon:Polyamide staple delivers superior abrasion resistance for industrial belting and technical textiles.
- Wool:Keratin-based animal fiber commands niche positioning in cold-climate outerwear and luxury upholstery.
Polyester anchors the volume base while recycled-grade polyester gains share at the steepest rate.
End Use:
Application-driven cost tiers separate commodity apparel staples from certified automotive grades commanding 40-60% price premiums.
- Automotive:Nonwoven staple grades for interior panels, headliners, and seating substrates carry stringent OEM validation requirements. German and Czech manufacturing corridors concentrate procurement through direct mill relationships, with NHTSA fuel economy standards accelerating lightweight material substitution.
- Apparel:Yarn-spinning staple for woven and knitted fabrics spans mass-market to premium channels. Bangladesh and Vietnam garment factories drive polyester and cotton blend specifications, though OEKO-TEX certification now functions as a market access threshold for EU-bound production.
- Home Textiles:Bedding and furnishing staple demand emphasizes softness and dye affinity over structural performance.
- Industrial:Geotextiles, filtration media, and conveyor belting require high-tenacity engineered staples with defined elongation characteristics.
Apparel absorbs the greatest absolute volume while automotive applications climb the fastest on a percentage basis.
Distribution Channel:
Customer type determines procurement modality, with integrated manufacturers bypassing intermediaries while smaller converters rely on trader networks.
- Wholesale:Volume consolidation through fiber traders and distributor networks serves mid-scale spinning operations lacking direct polymerization access. Rotterdam and Hamburg trading hubs intermediate European flows, though blockchain-tracked procurement platforms now disintermediate traditional networks for sustainability-verified grades.
- Online Retail:Digital platforms enable small-batch staple sourcing for specialty yarn producers and technical textile startups. Alibaba and Indiamart marketplaces aggregate fragmented Asian supply, though quality consistency varies without mill-direct relationships.
- Specialty Stores:Regional fiber distributors stock certified grades for OEKO-TEX and GRS-compliant production.
- Supermarkets:Mass-market channels carry limited craft and hobby-grade staple assortments.
Wholesale retains dominant volume share while online retail expands most quickly among emerging technical textile entrants.
Application:
Functional maturity separates established clothing and upholstery staples from emerging filtration and nonwoven categories requiring advanced polymer engineering.
- Nonwovens:Thermally or chemically bonded staple webs serve disposable hygiene, medical, and industrial wipe applications. Microdenier bicomponent technology below 0.5 denier per filament enables ultrafine surfaces displacing glass microfiber in HVAC filtration, with automotive cabin air systems adopting these grades at accelerated qualification paces.
- Filters:Engineered staple media for liquid and air separation applications demand precise fiber diameter distribution and surface area optimization. Meltblown production lines in Germany and the United States supply EPA-regulated industrial emissions control and FDA-compliant pharmaceutical processing equipment.
- Upholstery:Furniture and automotive seating fabrics prioritize abrasion resistance and flame-retardant performance.
- Clothing:Traditional yarn-spinning staple for woven shirting and knitted knitwear maintains the largest installed base.
Clothing maintains the broadest installed base while nonwovens demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE environmental compliance mandates in China anchor the dominant geography, where integrated spinning clusters command export-competitive volumes. Zhejiang and Jiangsu province megafacilities concentrate captive polymerization-to-yarn production. Germany and Czech Republic manufacturing corridors enforce supplier consolidation through certified sustainability scorecards. India's PLI scheme incentives redirect technical textile demand toward infrastructure and agricultural applications.
China
Zhejiang province spinning clusters and Jiangsu province megafacilities drive polyester staple output for export-oriented apparel and automotive supply chains. MEE environmental compliance mandates elevate capital requirements for manufacturing facilities. Dual carbon goals accelerate feedstock reengineering toward mechanically recycled polymers.
Germany
BMW, Volkswagen, and Skoda facilities enforce supplier consolidation to reduce audit burden and traceability cost. EU Green Deal textile sustainability requirements push staple producers toward recycled feedstocks. Automotive Tier 1 seating suppliers in Czech Republic manufacturing corridors consolidate procurement through certified sustainability scorecards.
United States
NHTSA fuel economy standards accelerate nonwoven staple adoption for interior panels, door trim, and headliners in electric vehicle platforms. EPA industrial emissions standards elevate capital requirements for staple manufacturing facilities. Meltblown production lines supply EPA-regulated industrial emissions control equipment.
India
PLI scheme incentives for geotextiles and agrotextiles create demand for high-tenacity polyester staples in infrastructure and agricultural applications. BIS certification requirements function as market access thresholds. Maharashtra and Gujarat spinning operations capture domestic volume expansion.
Japan
Toray Industries sustains technology leadership through advanced polyester and nylon polymerization capabilities. METI industrial policy supports polymer engineering talent development. Technical textile R&D concentrates in Kanto and Kansai manufacturing belts.
Textile Staples Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where fiber innovators command premium positioning and commodity converters compete on scale. The vendor base fragments across integrated polymerization assets, mechanical recycling specialists, and regional trading intermediaries. Three archetypes dominate: wood-based cellulosic innovators, petrochemical polymerization leaders, and PET recycling stream controllers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure feedstock access and qualification relationships.
Within the fiber innovator tier, Lenzing AG represents wood-based cellulosic expertise anchoring premium positioning in sustainable staples. Toray Industries occupies a position exemplifying advanced polymerization capabilities. Indorama Ventures sits within the recycling stream controller archetype, with established collection infrastructure extending cost advantages across Asian and European supply bases.
| Leading Market Players |
|---|
| Lenzing AG |
| Toray Industries |
| Indorama Ventures |
| Reliance Industries |
| DuPont |
| Invista |
| International Fibers Group |
| W. Barnet GmbH & Co. KG |
| Aditya Birla Group |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month OEM validation cycles for automotive staple grades compress pricing power for unqualified suppliers while amplifying margin capture for certified producers with direct mill relationships in Germany and Czech manufacturing corridors.
Pricing Analysis
Geographic price spreads between Zhejiang province export-grade polyester staples and EU-bound OEKO-TEX certified grades reflect three-tier pricing structure across premium, standard, and economy levels. Certification tier and automotive OEM validation status drive price differentiation, with validated automotive grades commanding substantial premiums over commodity apparel staples. Pricing pressure stems from EU Green Deal mandates compressing virgin polyester margins as mechanically recycled alternatives gain procurement preference. Small-scale spinning operations in Bangladesh and Vietnam exhibit highest price sensitivity, while German Tier 1 seating suppliers prioritize traceability over unit cost.
Supply Chain Analysis
Inventory cycles extending beyond ninety days for post-consumer polyester textile-to-textile recycling feedstock expose supply chain fragility across Asian manufacturing bases. Supply concentrates in China, India, and Germany, with Zhejiang province polymerization assets and Czech Republic automotive corridors anchoring regional flows. Purified terephthalic acid, monoethylene glycol, and wood pulp feedstock dependencies create exposure to petrochemical volatility and agricultural commodity swings. Single-source vulnerability concentrates in European mechanical recycling infrastructure, limiting recycled staple availability for Asian converters. Distribution runs through Rotterdam and Hamburg trading hubs for wholesale volumes, though blockchain-tracked mill-direct procurement now disintermediates traditional trader networks for sustainability-verified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-tracked staple procurement platforms are reconfiguring this market toward platform-economics dynamics, where verified sustainability credentials function as interoperability standards that determine supplier inclusion in automotive and apparel procurement systems.
For Market Incumbents: Secure backward integration into mechanical recycling streams to defend margin position against EU Green Deal feedstock mandates that disadvantage virgin polyester converters. Capture capacity expansion in Jiangsu province spinning clusters to maintain scale advantages as Chinese domestic demand absorbs export-competitive volume. Invest in OEKO-TEX and GRS certification infrastructure to preserve market access as compliance thresholds tighten across European apparel channels.
For New Entrants and Emerging Players: Anchor in India's PLI scheme technical textiles incentives, where geotextile and agrotextile demand for high-tenacity polyester staples remains underpenetrated by established global suppliers. Target Maharashtra and Gujarat spinning operations with direct-to-mill digital sourcing platforms that bypass legacy trader networks. Lead with bio-based cellulosic convergence using agricultural residue feedstocks to differentiate from petroleum-dependent incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-infrastructure play because EU extended producer responsibility schemes and automotive lightweighting mandates create structural demand for verified recycled staple capacity that outstrips current supply. Acquisition targets should emphasize mechanical recycling specialists with established European collection infrastructure and automotive OEM qualification relationships. Monitor post-consumer textile collection rate acceleration in France, Germany, and Netherlands as the signal for recycled feedstock availability inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Streams | Captures margin compression from EU Green Deal virgin polymer displacement mandates. |
| Automotive OEM Qualification Investment | Unlocks eighteen-to-twenty-four-month validation cycles that freeze out smaller competitors. |
| Blockchain-Tracked Procurement Platform | Disintermediates Rotterdam and Hamburg trader networks for sustainability-verified grades. |
| Bio-Based Cellulosic Capacity Buildout | Opens premium positioning beyond petroleum-dependent polyester and nylon categories. |
| Joint Venture in Zhejiang Spinning Clusters | Accesses captive polymerization-to-yarn scale efficiencies in China's export-competitive corridor. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating polymer engineering directors at staple manufacturers, procurement leads at German automotive Tier 1 seating suppliers, spinning mill operations managers in Zhejiang and Jiangsu provinces, and sustainability compliance officers at European apparel brands. Secondary validation drew from ECHA SVHC candidate list updates, EU Green Deal textile strategy documentation, MEE environmental compliance filings, and OEKO-TEX certification registry data. Bottom-up volume modeling from individual facility capacities and top-down demand segmentation from end-use consumption patterns were triangulated to reconcile output ranges.
Across the analysis window, the forecasting framework modeled fiber type substitution dynamics, automotive lightweighting penetration rates, and recycled feedstock availability constraints. Segmentation dimensions included staple length specifications, polymer chemistry categories, end-use application tiers, and regional regulatory compliance clusters. CAGRs were derived from fitted trend extrapolation with cross-validation against historical capacity utilization and announced expansion timelines. Industry-specific inputs incorporated NHTSA fuel economy standard stringency trajectories and EU extended producer responsibility implementation schedules.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement, stable petrochemical feedstock pricing bands, and incremental mechanical recycling technology cost reduction; material deviation in any assumption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Woolen Textiles Market
Natural Fibers
Hessian Sacks Market
Natural Fibers
Gum Fiber Market
Natural Fibers
North America Cotton Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Global Rattan Products Market
Natural Fibers
Green Fibers Market
Natural Fibers
Silk Fabric Market
Natural Fibers
North America Alpaca Fiber Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Organic Cotton Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Down and Feather Market
Natural Fibers
Cellulose Market