
 North America Alpaca Fiber Market | 2026-2036
North America Alpaca Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alpaca Fiber Market Insights
Skilled alpaca husbandry and fiber grading expertise is bifurcating the North America Alpaca Fiber Market into artisan-scale producers and commercial-grade suppliers. Plymouth Yarn Company, Inc. leverages its vertical integration from raw fiber to finished yarn to control quality consistency. Zeilinger Wool Co. anchors its position through specialized scouring and processing infrastructure serving regional ranchers. The Alpaca Yarn Company differentiates via direct-to-crafter channels that bypass traditional wholesale tiers.
Alpaca fiber is a natural protein fiber harvested from domesticated camelids, with Huacaya varieties exhibiting a dense crimped structure averaging 20-40 microns in diameter and Suri fibers displaying a lustrous helical lock formation prized for draping applications. The fiber serves premium textile applications where thermal regulation, hypoallergenic properties, and moisture wicking outperform synthetic alternatives. Yarn and fabric segments command margin concentration due to value-added processing steps that ranchers cannot replicate in-house. Home decor applications sustain faster volume expansion than fashion brands as interior designers seek sustainable luxury materials with traceable provenance.
USDA organic certification requirements and state-level agricultural extension standards govern fiber labeling and animal welfare claims across US producing states. The Alpaca Owners Association, Inc. maintains breed registry protocols that influence genetic quality premiums and export eligibility to Canadian and Mexican textile mills. Stakeholders must monitor evolving biodegradable textile standards and carbon accounting methodologies that will determine access to premium pricing tiers in cross-border trade.
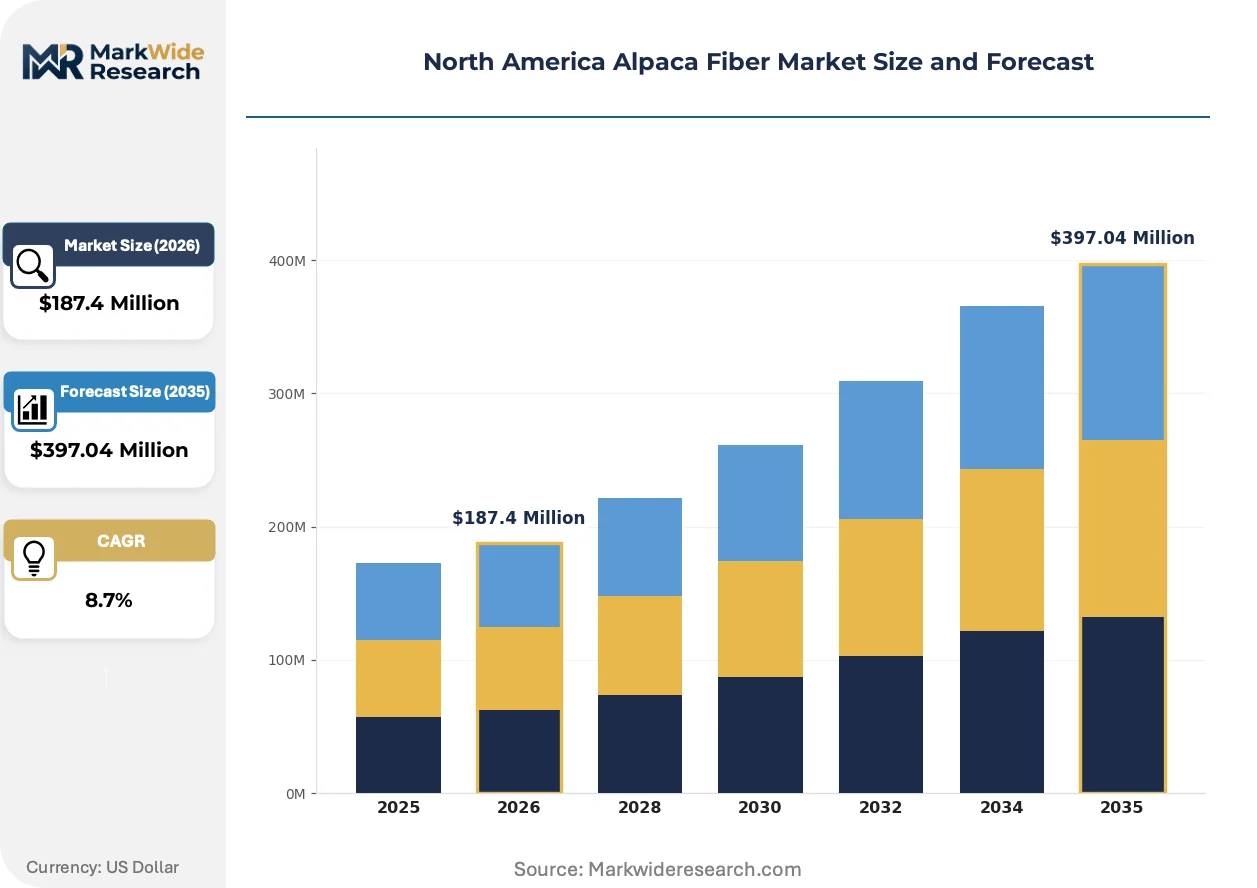
Market Dynamics
The North America Alpaca Fiber Market is experiencing structural pressure from USDA organic certification requirements that are fragmenting producer compliance costs across state-level agricultural extension networks. Small-scale ranchers face disproportionate audit burdens while commercial operators capture scale economies in certification maintenance.
Growth Catalysts
- Biodegradable textile mandates:State-level procurement policies in Colorado and Oregon favor natural fibers for public uniform contracts, creating guaranteed offtake volumes for certified producers.
- Huacaya genetic improvement programs:The Alpaca Owners Association's micron reduction protocols are expanding fiber fineness grades eligible for luxury apparel applications.
- Mountain West ranching corridor concentration:Clustered fiber pooling cooperatives in Utah and Idaho reduce per-unit scouring and sorting costs for artisan-scale producers.
Market Restraints
- Input cost volatility:Hay and supplemental feed prices fluctuate with drought cycles across the Intermountain West, compressing rancher margins during climate-stressed growing seasons.
- Substitution threat:Merino wool from Australian and New Zealand suppliers competes directly on micron count and price in premium knitwear segments.
- Regulatory friction:USDA organic textile standards require three-year pasture conversion timelines that lock prospective entrants into extended pre-revenue periods.
Strategic Opportunities
- Canadian cross-border processing:Alberta-based textile mills offer scouring capacity at lower labor rates than US Mountain West facilities, creating arbitrage for fiber pooling cooperatives.
- Carbon accounting methodologies:Emerging protocols for livestock methane offset crediting could unlock premium pricing tiers for fiber with verified negative carbon intensity.
- Direct-to-crafter platforms:E-commerce channels bypassing wholesale yarn distributors enable rancher-branded retail margins previously captured by intermediaries.
Industry Challenges
- Fiber grading expertise scarcity:Certified sorter training programs operate at insufficient throughput to replace retiring specialists in regional cooperative networks.
- Certification timeline compression:USDA organic audits face backlogs extending 18-24 months, delaying market access for conversion-stage ranchers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alpaca Fiber Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Fiber, Yarn, Fabric, Garments End User: Textile Manufacturers, Fashion Brands, Crafting, Home Decor Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Exporters Quality Grade: Suri, Huacaya, Grade A, Grade B |
| Companies Covered | Plymouth Yarn Company, Inc., Berroco, Inc., The Alpaca Yarn Company, Alpaca Warehouse, The Natural Fibre Company, Zeilinger Wool Co., Mary Maxim Inc., A & D Alpaca Fiber, Alpaca Owners Association, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alpaca Fiber Market Trends and Innovations
Sustainable luxury positioning is reshaping competitive differentiation in alpaca fiber, with traceability systems and carbon labeling displacing traditional quality-only purchasing criteria among premium textile buyers.
Mechanized shearing and fiber collection systems are bifurcating the North America Alpaca Fiber Market into precision-harvested lots with documented micron consistency and traditional hand-sheared batches with higher variability. Commercial-scale ranchers in Colorado and Utah are adopting pneumatic shearing equipment that reduces second-cut contamination and fiber breakage. This technology is compressing price premiums for artisan-processed fiber while enabling volume suppliers to meet textile mill specifications previously reserved for imported Merino.
USDA organic textile standards are tightening animal welfare documentation requirements for pasture access and veterinary treatment records. The regulation is forcing ranchers to invest in digital herd management systems for compliance audit trails. Small-scale producers in New Mexico and Arizona face the steepest adaptation costs, with many exiting certification programs rather than upgrading record-keeping infrastructure.
Interior designers are pivoting procurement toward fiber with verified provenance and ranch-specific branding for luxury residential projects. This specification pattern is displacing anonymous wholesale yarn purchases in the home decor segment. The shift is most visible in California and Pacific Northwest design markets, where project documentation requirements now mandate supplier transparency for sustainability scoring.
North America Alpaca Fiber Market Segmentation
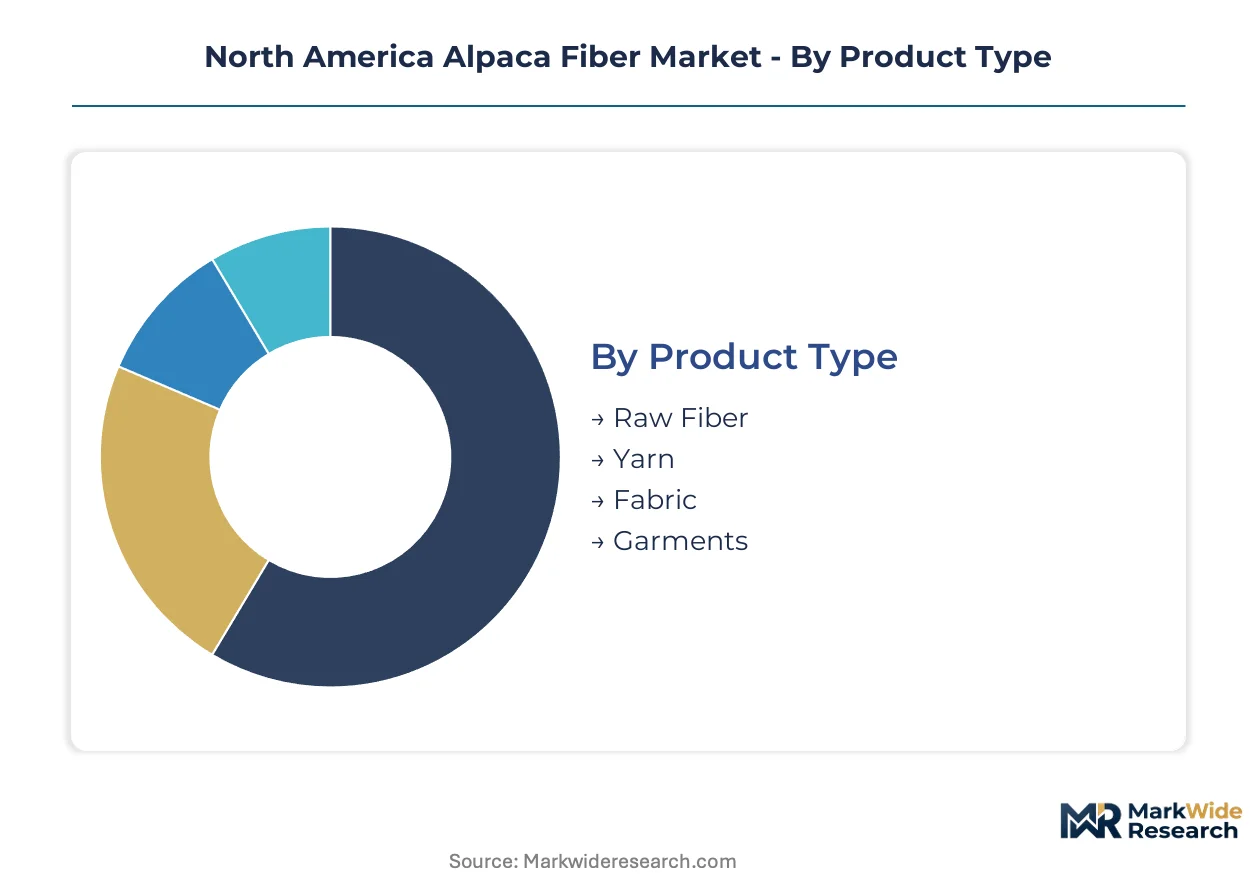
Segmentation in the North America Alpaca Fiber Market reveals how value capture shifts across processing stages and buyer sophistication tiers. Each dimension exposes different vulnerability to Merino wool substitution and synthetic alternatives.
Product Type:
Merino wool from Australian suppliers exerts the strongest substitution pressure on intermediate processing segments where micron parity matters most.
- Raw Fiber:Unprocessed fleece harvested from Huacaya and Suri animals, typically sold at shearing with basic sorting by color and handle. Ranchers in the US Mountain West corridor dominate supply, though drought-driven hay costs compress margins during climate-stressed seasons.
- Yarn:Spun fiber ready for knitting or weaving applications, commanding value-added premiums through ply construction and dye consistency. Demand concentrates among specialty textile manufacturers in Colorado and Utah seeking domestic alternatives to imported Merino.
- Fabric:Woven or knitted textiles for apparel and interior applications, requiring scouring and finishing infrastructure that few regional ranchers possess in-house.
- Garments:Finished consumer products including sweaters, accessories, and outerwear, where brand storytelling around provenance sustains price premiums against fast fashion alternatives.
Raw Fiber anchors the volume base while Yarn gains share at the steepest rate as regional pooling cooperatives invest in shared processing infrastructure.
End User:
Margin concentration follows the distance from commodity fiber trading toward proprietary design control.
- Textile Manufacturers:Industrial buyers purchasing scoured fiber and yarn for integration into broader fabric production, prioritizing micron consistency and lot uniformity for mechanized processing.
- Fashion Brands:Premium apparel labels sourcing traceable fiber for sustainability narratives, with California-based designers leading specification shifts toward ranch-specific branding.
- Crafting:Individual makers and small-batch producers purchasing through direct-to-crafter platforms, bypassing wholesale intermediaries to capture retail-equivalent margins.
- Home Decor:Interior designers specifying alpaca throws, rugs, and upholstery textiles for luxury residential projects, expanding faster than fashion applications as provenance documentation becomes mandatory for sustainability scoring.
Textile Manufacturers anchor the volume base while Home Decor climbs the fastest as Pacific Northwest design markets institutionalize supplier transparency requirements.
Distribution Channel:
Channel selection determines whether ranchers capture brand equity value or cede it to intermediaries.
- Online Retail:E-commerce platforms enabling direct rancher-to-consumer relationships, with fiber pooling cooperatives in Idaho and Utah leveraging this channel to bypass traditional wholesale tiers.
- Specialty Stores:Independent yarn shops and fiber arts retailers serving the crafting segment, where tactile evaluation drives purchase decisions and staff expertise substitutes for digital content.
- Wholesale Distributors:Aggregators purchasing bulk fiber for resale to textile mills and manufacturers, capturing economies of scale that individual ranchers cannot replicate.
- Exporters:Channels serving Canadian and Mexican textile processors, with Alberta-based mills offering scouring capacity at lower labor rates than US Mountain West facilities.
Wholesale Distributors anchor the volume base while Online Retail expands most quickly as digital herd management systems enable compliance documentation for direct sales.
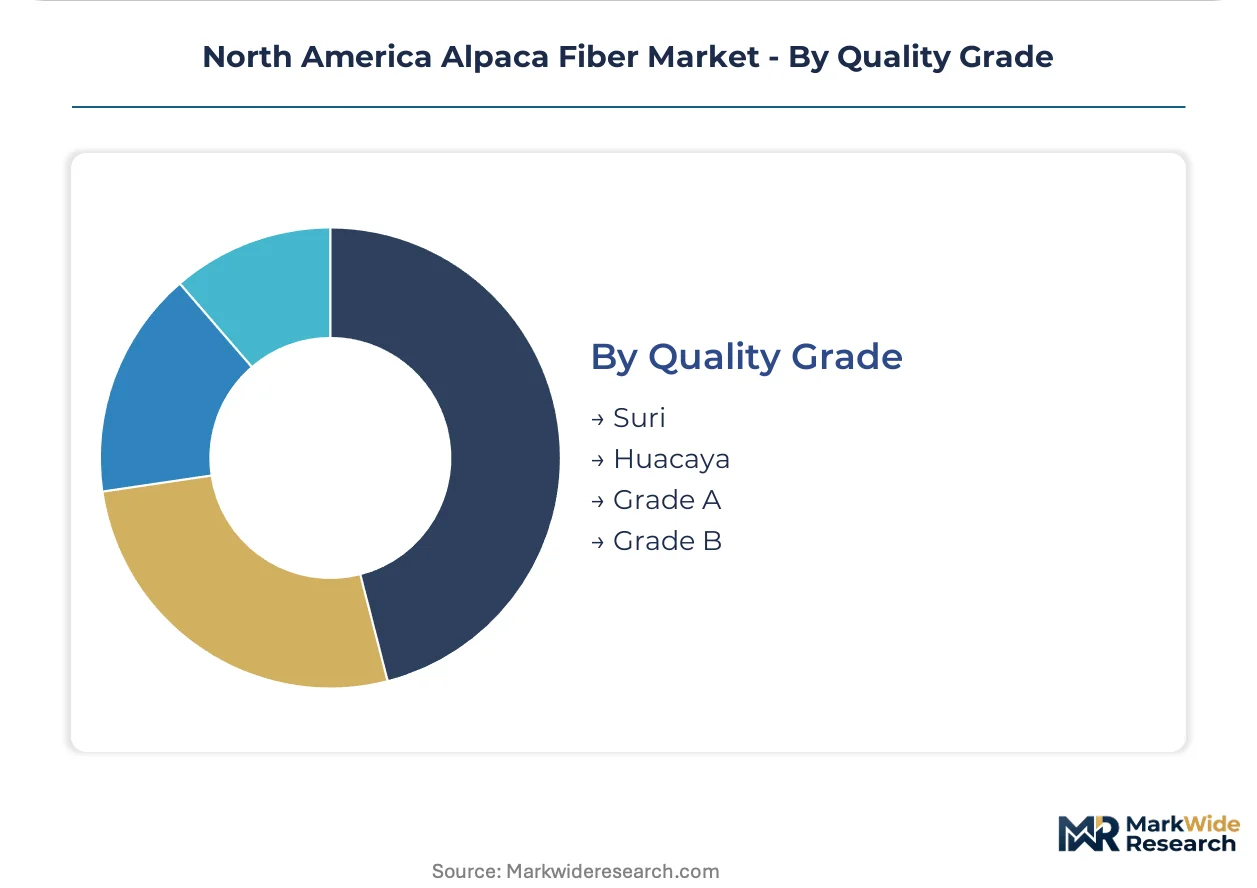
Quality Grade:
Genetic improvement investments are compressing the premium gap between heritage grades.
- Suri:Lustrous helical lock formation prized for draping applications in luxury apparel, with limited supply sustaining price premiums despite handling challenges in mechanized processing.
- Huacaya:Dense crimped structure averaging 20-40 microns, comprising the majority of North American production and benefiting from Alpaca Owners Association micron reduction protocols.
- Grade A:Premium classification for fiber under 27 microns with minimal guard hair contamination, eligible for luxury apparel applications where softness drives consumer preference.
- Grade B:Coarser fiber above 27 microns suited for outerwear, home textiles, and industrial applications where durability outweighs handle considerations.
Huacaya anchors the volume base while Grade A gains share at the steepest rate as genetic improvement programs expand fineness eligibility for premium textile specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA organic textile standards anchor fiber quality protocols across the North America Alpaca Fiber Market. State-level agricultural extension networks govern animal welfare compliance and certification timelines. Ranching activity concentrates in the Intermountain West corridor where elevation and aridity suit camelid husbandry.
United States
Colorado and Utah ranching cooperatives drive fiber pooling infrastructure investment. USDA organic certification requires three-year pasture conversion timelines that delay new entrant market access. The Mountain West corridor from Idaho to New Mexico hosts scouring facilities and sorting infrastructure serving artisan-scale producers.
Canada
Alberta-based textile mills attract cross-border fiber shipments with lower labor rates than US facilities. Health Canada textile labeling requirements govern fiber content disclosure for domestic retail distribution. Prairie Provinces ranchers participate in US pooling cooperatives to access Mountain West processing capacity.
Mexico
Central Mexican textile manufacturers source raw fiber for artisan weaving traditions and export yarn production. The country's national agricultural regulator oversees livestock health protocols for cross-border fiber movement. Bajío Region processors handle volume shipments from US cooperatives seeking cost-competitive scouring alternatives.
North America Alpaca Fiber Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America Alpaca Fiber Market. Vertically integrated yarn manufacturers control quality consistency through captive fiber supply, while specialized processors compete on scouring efficiency and lot uniformity. The vendor base separates into three strategic archetypes: integrated yarn spinners, regional fiber processors, and direct-to-crafter brands. Competitive moves concentrate on backward integration into raw fiber sourcing and geographic expansion through fiber pooling cooperative partnerships.
Among integrated yarn manufacturers, Plymouth Yarn Company, Inc. exemplifies vertical control from raw fiber to finished product. Zeilinger Wool Co. occupies a position within the specialized processing tier, anchoring regional infrastructure for scouring and fiber preparation. The Alpaca Yarn Company represents the direct-to-crafter archetype, bypassing wholesale intermediaries to capture retail-equivalent margins through digital channels.
| Leading Market Players |
|---|
| Plymouth Yarn Company, Inc. |
| Berroco, Inc. |
| The Alpaca Yarn Company |
| Alpaca Warehouse |
| The Natural Fibre Company |
| Zeilinger Wool Co. |
| Mary Maxim Inc. |
| A & D Alpaca Fiber |
| Alpaca Owners Association, Inc. |
| Others |
Pricing and Supply Chain Analysis
Merino wool substitution from Australian and New Zealand suppliers simultaneously compresses price premiums in the Mountain West corridor and redirects procurement toward cross-border Canadian processing facilities. This displacement dynamic forces US ranchers to absorb certification cost burdens while Alberta-based mills capture arbitrage margins on scoured fiber volumes.
Pricing Analysis
Price spreads between Colorado-Utah ranch gate values and Alberta mill-delivered fiber reflect labor rate differentials and USDA organic audit backlogs. Three-tier pricing structure across certified premium, transitional standard, and conventional economy levels segments buyers by provenance documentation requirements. Pricing pressure stems from drought-driven hay cost volatility that ranchers cannot pass through to textile manufacturers. Fashion brands exhibit lowest price sensitivity due to sustainability narrative requirements, while wholesale distributors face margin compression from pooled fiber commoditization.
Supply Chain Analysis
Inbound logistics costs from Intermountain West ranches to Alberta scouring facilities hinge on cross-border customs clearance efficiency and LTL carrier availability through Montana corridors. Raw fiber supply concentrates in Colorado, Utah, and Idaho where elevation and aridity suit camelid husbandry. The supply chain draws from hay inputs, veterinary services, and shearing equipment maintenance as critical cost components. Single-source vulnerability exists in certified fiber sorter training programs with insufficient throughput to replace retiring specialists. Distribution runs through fiber pooling cooperatives, direct-to-crafter platforms, and wholesale yarn distributors serving regional textile manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
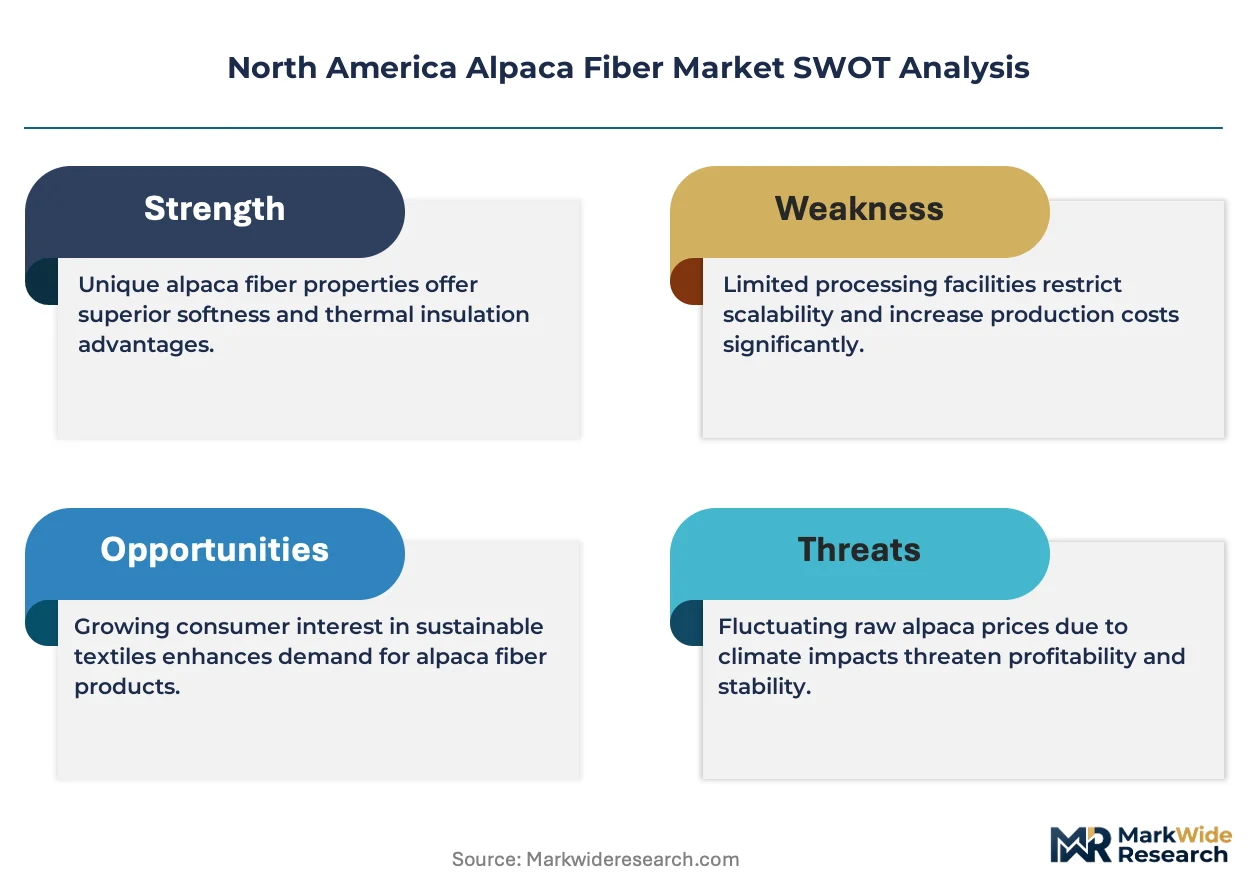
The North America Alpaca Fiber Market functions as a defensive-moat industry where USDA organic certification entrenchment creates three-year conversion timelines that lock out prospective entrants and protect incumbent rancher relationships with verified buyers.
For Market Incumbents: Shield market position by deepening backward integration into pneumatic shearing equipment that reduces second-cut contamination and meets textile mill specifications previously reserved for imported Merino. Prioritize certification maintenance investments to exploit audit backlog delays that prevent new entrant market access. Capture fiber pooling cooperative governance roles to control scouring capacity allocation and sort priority. For New Entrants and Emerging Players: Anchor in direct-to-crafter e-commerce channels where rancher-branded retail margins bypass wholesale intermediaries and provenance storytelling commands premium pricing. Target home decor applications in Pacific Northwest design markets where supplier transparency mandates create guaranteed specification demand. Pursue Canadian cross-border processing partnerships to access lower labor rate scouring capacity and reduce per-unit compliance costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fiber processors possessing specialized scouring infrastructure and cooperative network relationships but lacking digital herd management capabilities for USDA audit compliance. Long-term viability hinges on carbon accounting methodology adoption that could unlock methane offset crediting premiums. Monitor biodegradable textile mandate expansion across state procurement policies as inflection signal for certified fiber demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shearing Equipment | Pneumatic harvesting systems reduce fiber breakage and enable textile mill grade compliance. |
| Carbon Accounting Certification Program | Verified negative carbon intensity protocols unlock premium pricing tiers for methane-offset fiber. |
| Direct-to-Crafter Platform Launch | E-commerce channels bypass wholesale tiers and capture retail-equivalent margins for rancher brands. |
| Fiber Pooling Cooperative Partnership | Shared scouring infrastructure reduces per-unit processing costs for artisan-scale Mountain West producers. |
| USDA Organic Certification Investment | Three-year pasture conversion timelines create regulatory entrenchment against prospective market entrants. |
Research Methodology
Cross-validation between primary interviews with alpaca ranchers, fiber sorters, and textile mill procurement officers and secondary validation through USDA organic certification databases, Alpaca Owners Association registry protocols, and state agricultural extension records anchors the qualitative findings. Bottom-up triangulation from fiber pooling cooperative volume data and top-down reconciliation against Mountain West corridor production estimates ensures segmentation integrity.
Sensitivity analysis across micron grade, certification status, and distribution channel dimensions tests forecast robustness over the projection horizon. The analytical framework models product type, end user sophistication tier, quality grade, and geographic production cluster as core segmentation drivers. CAGRs derive from regression against historical fiber price spreads and substitution elasticity parameters for Merino wool competition. Drought severity indices and hay cost volatility curves serve as industry-specific forecast inputs.
Underlying assumptions cover sustained USDA organic textile standard enforcement and stable cross-border trade relations with Canadian processing facilities, with deviation risk concentrated in climate-driven feed cost spikes and biodegradable mandate adoption timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Global Hemp Fiber Market
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
Hessian Sacks Market
Natural Fibers
Silk Stocking Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
Silk Mask Market
Natural Fibers
Global Rattan Products Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Cellulose Market
Natural Fibers
Silk Textiles Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Green Fibers Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Cashmere Clothing Market