
 Abaca Fiber Market | 2026-2036
Abaca Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Abaca Fiber Market Intelligence
The distinction between high-grade, hand-stripped fiber for specialty applications and lower-grade, mechanically processed fiber for industrial use is hardening. Specialty Pulp Manufacturing, Inc. (SPMI) leverages its scale to supply the high-volume paper and pulp sector. Terranova Papers specializes in the production of high-value teabags and currency papers, requiring premium fiber grades. Yzen Handicraft Export Trading competes by focusing on the artisanal and textile segments with its curated supply chains.
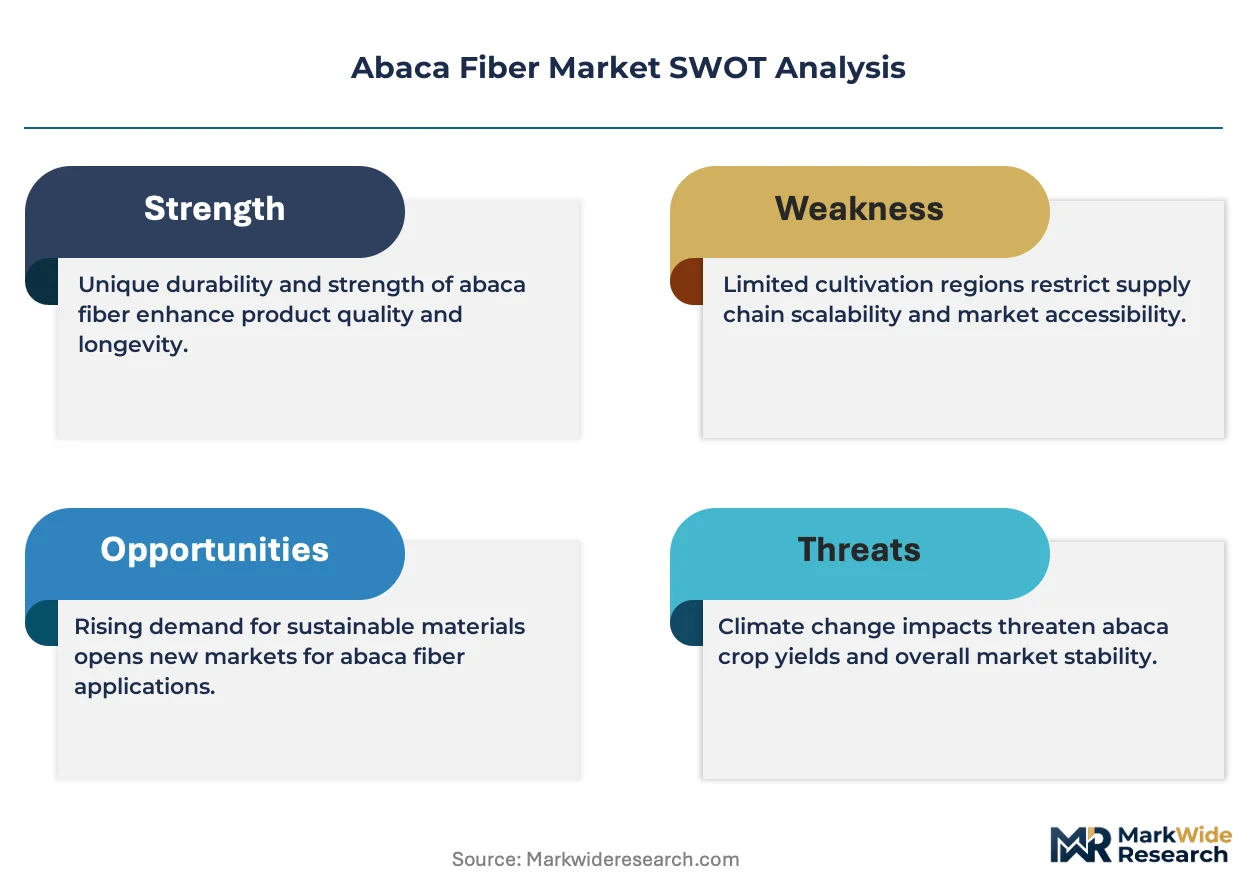
Abaca fiber is a natural leaf fiber extracted from the Musa textilis plant, a species native to the Philippines. Its composition provides exceptional tensile strength and resistance to saltwater, making it ideal for durable specialty papers and marine cordage. The paper segment, particularly for currency and filter applications, constitutes a high-value, established market. In contrast, composites for the automotive end-user represent an emerging application driven by the need for lightweighting materials.
The Philippine Fiber Industry Development Authority (PhilFIDA) governs quality grading and export standards, directly impacting supply consistency. In destination markets, compliance with frameworks like the EU's REACH and USDA organic standards is essential for accessing high-value textile and food-contact segments. Future profitability will hinge on producers' ability to navigate these diverse standards and invest in traceability systems to verify sustainability claims.
Market Dynamics
The central dynamic is a structural tension between geographically concentrated, climate-vulnerable supply from the Philippines and diversifying, sustainability-driven industrial demand from economies like Germany and Japan. This imbalance shapes pricing, quality standards, and investment in supply chain resilience across the entire market.
Growth Catalysts
- Automotive Lightweighting Mandates:Demand for natural fiber composites in Germany's automotive sector to reduce vehicle weight and meet emissions targets is a primary catalyst. Abaca offers a high strength-to-weight ratio for components like interior panels and underbody shields.
- Sustainable Material Policies:The European Union Green Deal promotes the use of biodegradable and renewable materials in manufacturing. This regulatory framework creates preferential market access for natural fibers like abaca over petroleum-based alternatives in packaging and consumer goods.
- Specialty Paper Demand:Established demand from Japan for high-performance papers, including currency, teabags, and medical filters, provides a stable, high-value consumption base. These applications require the premium fiber grades that command higher prices.
Market Restraints
- Supply Concentration Risk:Extreme dependence on the Philippines for raw fiber creates significant vulnerability to typhoons, plant diseases like bunchy top virus, and domestic policy shifts from the Philippine Fiber Industry Development Authority (PhilFIDA).
- Substitution from Synthetics:In applications like marine cordage and general-purpose ropes, lower-cost synthetic fibers such as nylon and polypropylene present a persistent substitution threat. These substitutes offer high durability and are produced at a much larger industrial scale.
- High Labor Costs:The production of high-grade fiber requires manual stripping and sorting, a labor-intensive process. This results in a significant cost differential compared to mechanically processed lower grades, limiting its use in price-sensitive, high-volume applications.
Strategic Opportunities
- Biocomposite Development:Combining abaca fibers with bio-resins like polylactic acid (PLA) opens opportunities for fully biodegradable composites. These materials can target new applications in sustainable construction, electronics casings, and premium consumer goods.
- Food-Contact Certification:Achieving compliance with standards like the USDA's organic regulations or the EU's food-contact material frameworks can unlock premium market segments. This is particularly relevant for applications such as specialty teabags, coffee filters, and food packaging.
- Geographic Diversification:Cultivation efforts in other regions, such as Ecuador and Costa Rica, present an opportunity to de-risk the supply chain. Establishing processing capabilities in these new geographies can create alternative supply sources for North American and European buyers.
Industry Challenges
- Traceability and Certification Costs:Implementing robust traceability systems to meet the demands of frameworks like the EU's REACH is a significant operational challenge. The cost of verification and certification for sustainability claims falls heavily on producers and processors.
- Quality Standardization:A lack of universally adopted standards for mechanically processed fiber grades creates friction for industrial end-users. Inconsistent fiber length, strength, and purity complicates large-scale adoption in automated manufacturing processes like injection molding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abaca Fiber Market |
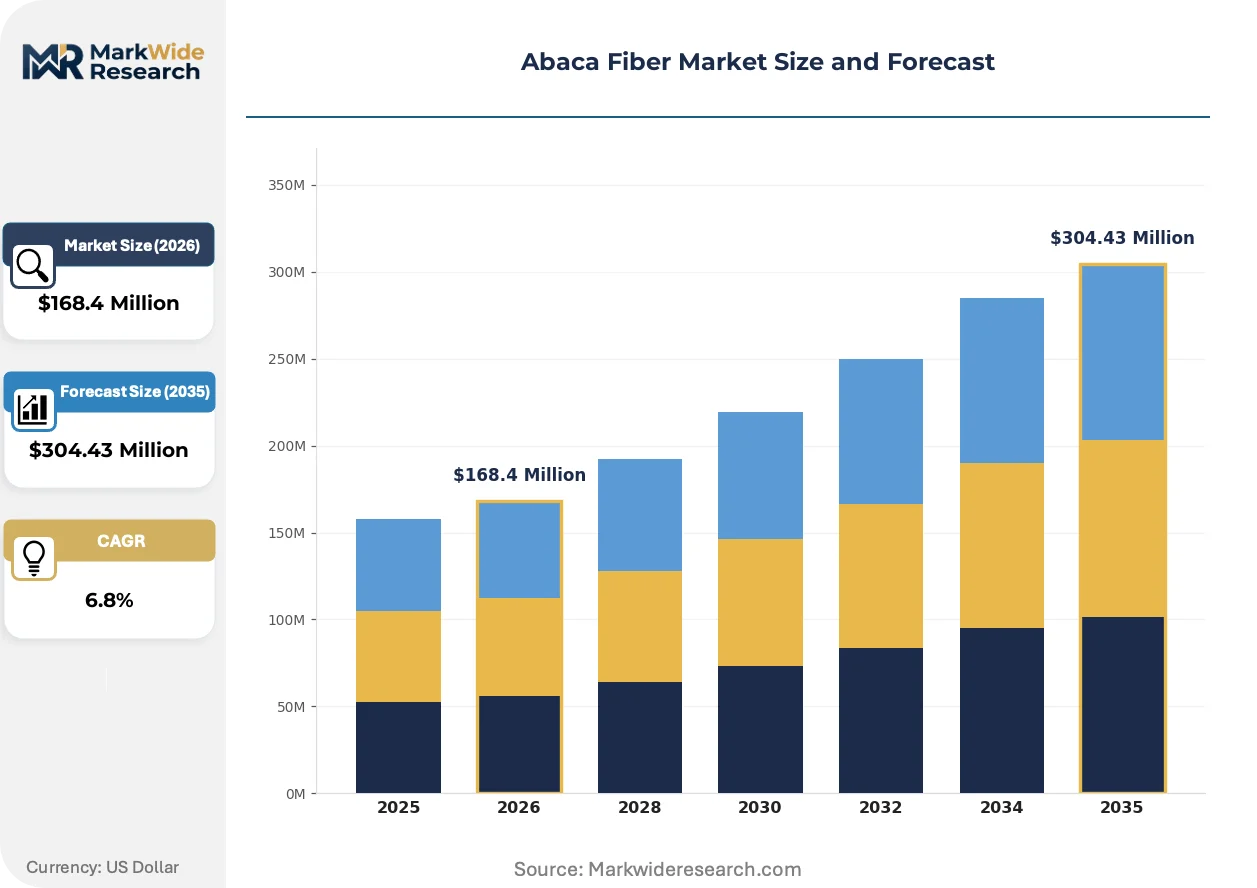
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $304.43 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textiles, Paper, Composites, Cordage End User: Fashion Industry, Automotive, Packaging, Construction Application: Upholstery, Knitting, Crafting, Building Materials Quality Grade: Standard, Premium, Organic, Industrial |
| Companies Covered | Yzen Handicraft Export Trading, Sellinrail International Trading Company, Specialty Pulp Manufacturing, Inc. (SPMI), Terranova Papers, DGL Global Ventures LLC, Ching Bee Trading Corporation, Peral Enterprises, Chandra Prakash and Co., M.A.P. Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abaca Fiber Market Strategic Shifts & Innovations
Processing innovations and digital traceability are transforming abaca from a traditional agricultural commodity into a standardized industrial input. This shift enables its use in sectors requiring verifiable performance and sustainability.
Advanced refining techniques, including enzymatic and mechanical processing, create specific pulp grades from raw abaca. Specialty paper and composite manufacturers are the primary adopters of these refined inputs for their targeted performance. This development is modularizing the fiber supply, enabling producers to engineer tailored characteristics for specific end-uses like filtration media or automotive panels, rather than offering a one-size-fits-all raw fiber.
The European Union's Corporate Sustainability Reporting Directive (CSRD) compels large companies to report on supply chain sustainability. This forces European automotive and specialty goods importers to demand verifiable traceability from abaca suppliers in the Philippines. Consequently, investment in digital tracking and third-party certification is increasing to secure access to these high-value markets.
A shift from bulk, unverified fiber purchasing toward long-term offtake agreements tied to specific quality grades is occurring. This practice displaces spot-market transactions for high-value industrial buyers who now engage directly with large processors. The trend is most visible in Germany's automotive supply chain and Japan's currency paper sector, where supply security and material consistency are paramount.
Abaca Fiber Market Segmentation
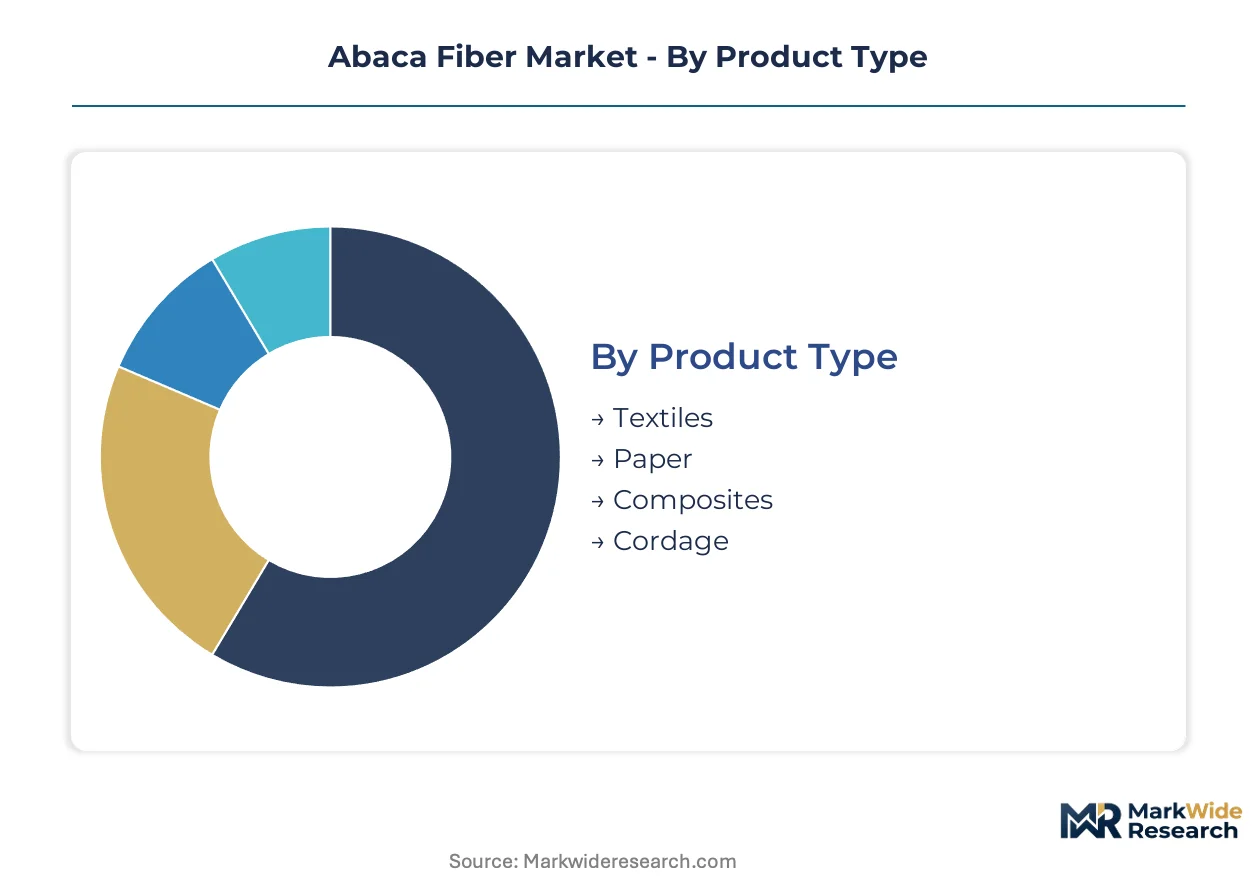
Understanding the Abaca Fiber Market through distinct segments reveals how diverse end-use requirements shape material specifications and processing methods. This segmentation highlights the varying value propositions and growth trajectories across different applications for this natural fiber.
Product Type:
The market categorizes product types by their integration depth, from raw fiber to finished components, indicating the level of processing and value addition. Each product type serves specific functional roles across industries.
- Paper:This segment includes specialty papers like currency, tea bags, and filter media, leveraging abaca's exceptional wet strength and porosity. Demand from Japan's financial sector and food & beverage industry remains consistently high for these premium applications.
- Composites:Abaca fibers are integrated into bio-resins for lightweight, high-strength materials, primarily targeting automotive interior panels and structural components. Germany's automotive industry drives innovation in this segment, seeking sustainable alternatives for vehicle lightweighting.
- Textiles:Abaca fiber is woven into fabrics for apparel, home furnishings, and artisanal products, valued for its durability and unique texture. The fashion industry increasingly seeks sustainable natural fibers for eco-conscious collections.
- Cordage:Traditional applications include marine ropes, fishing nets, and industrial twines, where abaca's resistance to saltwater and high tensile strength are critical. This segment provides foundational demand, particularly in maritime regions.
Volume placements concentrate in Cordage; the faster expansion belongs to Composites.
End User:
End-user segmentation reflects the primary industries consuming abaca fiber, each driven by distinct material requirements and regulatory pressures. These industries dictate the scale and quality of fiber procurement.
- Automotive:This sector utilizes abaca for lightweight biocomposites in interior trim, underbody shields, and non-structural components, driven by emissions reduction targets. European manufacturers, particularly in Germany, lead the adoption of natural fiber composites.
- Packaging:Abaca finds use in specialty packaging, such as high-strength paper bags, food-contact materials, and sustainable protective wrapping. Consumer demand for eco-friendly solutions and EU Green Deal initiatives boost this segment.
- Fashion Industry:Abaca fibers create durable and sustainable textiles for clothing, accessories, and footwear, appealing to brands focused on natural and ethical sourcing. Artisanal markets and niche designers value its unique aesthetic and strength.
- Construction:Abaca is explored for its potential in bio-based insulation, non-structural panels, and reinforcement in sustainable building materials. This emerging application aligns with green building certifications and reduced environmental impact.
The Automotive segment drives consistent demand, while Packaging shows significant future potential.
Application:
The application segment details the specific uses of abaca fiber within various products, highlighting the functional properties most valued in each context. Each application leverages distinct characteristics of the fiber.
- Building Materials:Abaca fiber enhances the mechanical properties of biocomposites and serves as a sustainable reinforcement in non-load-bearing construction elements. This application reduces reliance on synthetic materials and improves product sustainability.
- Crafting:Artisanal products, handmade papers, and decorative items utilize abaca for its unique texture, strength, and natural aesthetic. This niche market supports traditional weaving and paper-making techniques.
- Upholstery:Abaca provides durable and breathable fabrics for furniture covering, offering a natural and robust alternative to synthetic materials. Its strength ensures longevity in high-wear applications.
- Knitting:Specialty yarns made from abaca are used in textiles requiring high strength, breathability, and natural feel. This application often targets niche apparel or home goods markets.
While Upholstery remains a foundational application, Building Materials is gaining traction due to sustainability mandates.
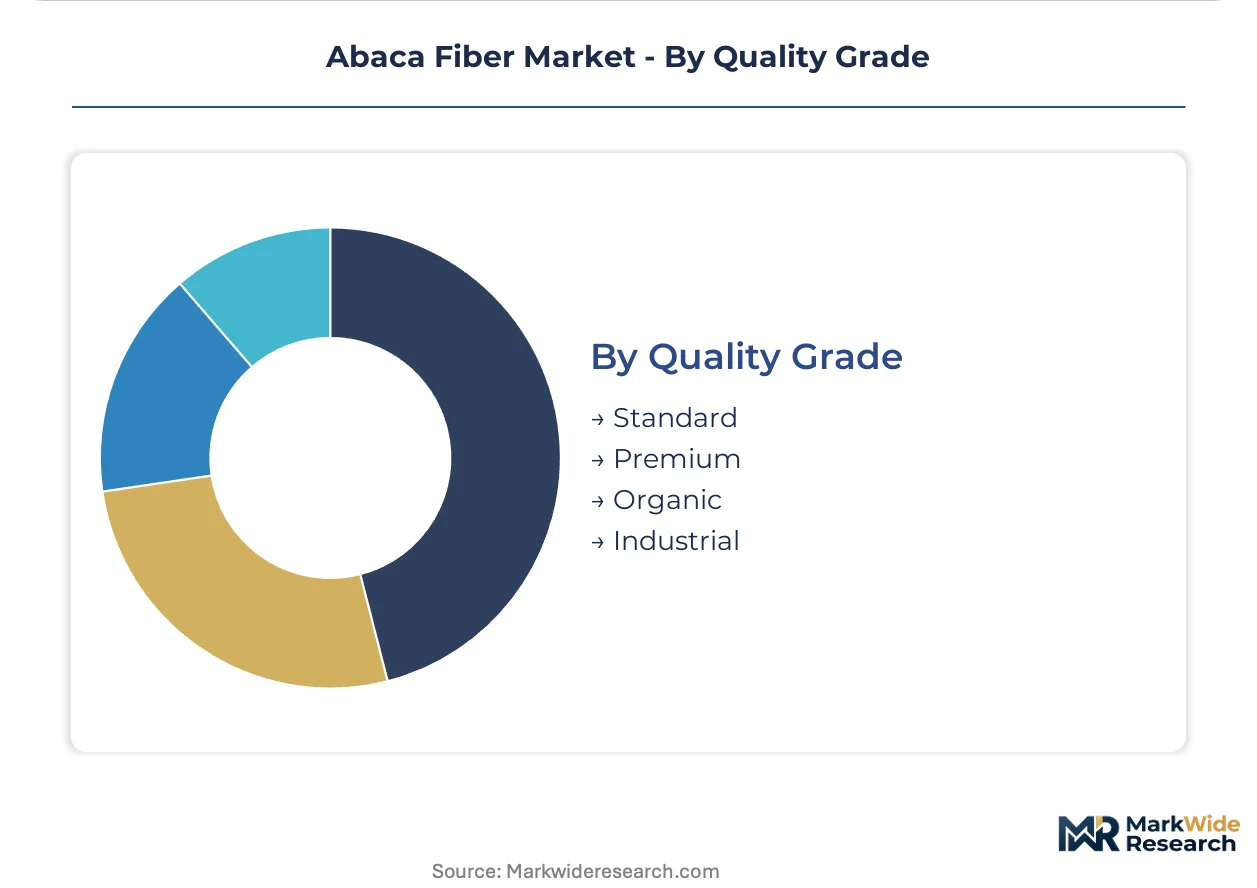
Quality Grade:
Quality grade segmentation reflects the varying levels of fiber processing, purity, and consistency, directly influencing pricing and suitability for different end-uses. This differentiation addresses specific industrial and specialty requirements.
- Premium:Characterized by hand-stripped, long, and clean fibers with superior tensile strength, ideal for currency paper, tea bags, and high-performance textiles. This grade commands top prices due to its labor-intensive production and critical performance attributes.
- Industrial:Mechanically processed, shorter, and less uniform fibers suitable for high-volume applications like composite reinforcement, pulp for standard papers, and cordage. This grade focuses on cost-effectiveness and consistent supply for manufacturing.
- Standard:Represents a balanced grade of machine-stripped or partially hand-processed fiber, offering good strength and consistency for general-purpose papers and some textile applications. This grade serves a broad market seeking a balance of quality and cost.
- Organic:Fibers certified to organic standards, ensuring cultivation without synthetic pesticides or fertilizers, primarily targeting food-contact applications and eco-conscious textile brands. This grade appeals to markets with strict environmental and health regulations.
Producers are increasingly differentiating offerings based on Industrial requirements, with Premium commanding higher price points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's automotive sector spearheads demand for abaca fiber, particularly in lightweight composite applications, reflecting Europe's broader sustainability mandates. This global market sees diverse regional contributions, ranging from critical supply hubs to established high-value consumption centers for specialty papers and emerging markets for biocomposites.
Germany
German automotive manufacturers are primary drivers for abaca composites, seeking to reduce vehicle weight and meet emissions targets. The European Union Green Deal strongly encourages sustainable and biodegradable materials in manufacturing. Key automotive clusters in Stuttgart and Munich actively integrate natural fiber solutions into their supply chains.
Japan
Japan maintains a stable, high-value consumption base for abaca in specialty papers, including currency, teabags, and medical filters. The Ministry of Economy, Trade and Industry (METI) supports the development of high-performance materials. Tokyo and Osaka remain critical centers for the paper and pulp industry, requiring premium abaca grades.
Philippines
The Philippines serves as the dominant global supplier of raw abaca fiber, facing unique supply concentration risks. The Philippine Fiber Industry Development Authority (PhilFIDA) governs quality grading and export standards for the fiber. Major cultivation and processing areas in Davao and Bicol are central to global supply consistency.
Ecuador
Ecuador presents an opportunity for geographic diversification of abaca cultivation, reducing reliance on a single source. Local environmental regulations promote sustainable agricultural practices for fiber production. Guayaquil and other coastal regions are developing as alternative supply points for North American and European markets.
Costa Rica
Costa Rica is exploring abaca cultivation to further de-risk the global supply chain and expand sustainable material sourcing. The country's strong environmental protection laws align with the demand for eco-friendly fibers. San José and surrounding agricultural areas are investing in new processing capabilities for abaca fiber.
Abaca Fiber Market Key Industry Players
Premium-margin players sit above commodity-margin players across the abaca fiber value chain, driven by processing depth and quality grade. The market structure differentiates between specialized suppliers focusing on high-value applications and larger entities catering to industrial volumes. Strategic archetypes include high-grade specialty fiber producers, volume pulp manufacturers, and artisanal segment suppliers. Investment in traceability systems and biocomposite research and development are common competitive moves.
Within the high-volume industrial tier, Specialty Pulp Manufacturing, Inc. (SPMI) leverages its scale to supply the paper and pulp sector. Terranova Papers exemplifies a premium-tier player, specializing in high-value teabags and currency papers that demand superior fiber grades. Yzen Handicraft Export Trading occupies a niche, focusing on curated supply chains for the artisanal and textile segments.
| Leading Market Players |
|---|
| Yzen Handicraft Export Trading |
| Sellinrail International Trading Company |
| Specialty Pulp Manufacturing, Inc. (SPMI) |
| Terranova Papers |
| DGL Global Ventures LLC |
| Ching Bee Trading Corporation |
| Peral Enterprises |
| Chandra Prakash and Co. |
| M.A.P. Enterprises |
| Others |
Cost & Logistics Intelligence
Manual stripping and sorting in the Philippines, a labor-intensive process, creates significant labor-cost differentials that directly influence pricing spreads between premium and industrial abaca fiber grades. This structural cost component underpins the market's tiered pricing architecture.
Pricing Analysis
Yield and purity of processed fiber anchor the value-based pricing model in the abaca market. Pricing stratifies across premium, standard, and industrial tiers, driven by quality grade and certification level, such as USDA organic standards for food-contact applications. Pricing pressure stems from the persistent substitution threat of lower-cost synthetic fibers in commodity applications like marine cordage. Automotive and specialty paper manufacturers demonstrate lower price sensitivity due to stringent performance and consistency requirements.
Supply Chain Analysis
Direct long-term offtake agreements for high-value industrial buyers increasingly characterize the distribution model for premium abaca fiber. Geographic supply concentration in the Philippines, with emerging cultivation in Ecuador and Costa Rica, underpins the raw material flow from Musa textilis plants. Single-source vulnerability due to climate events and plant diseases like bunchy top virus in the Philippines presents a significant supply chain risk. Procurement patterns are shifting towards verifiable traceability and specific quality grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The abaca fiber market is undergoing a technology-transition phase, as advanced refining techniques and digital traceability replace traditional bulk commodity trading. This shift enables its integration into high-performance industrial applications.
For Market Incumbents:Cement long-term offtake agreements with key automotive and specialty paper manufacturers to secure consistent demand. Invest in advanced processing technologies to engineer specific fiber grades, mitigating the threat from synthetic substitution in price-sensitive segments. Pursue certification for compliance with frameworks like the EU's REACH to maintain access to high-value European markets.
For New Entrants and Emerging Players:The European Union Green Deal in Europe opens a window for new entrants focusing on sustainable and biodegradable materials. Target the biocomposite development segment for construction and electronics casings, leveraging abaca's strength-to-weight ratio. Establish certified organic supply chains to capture premium demand in food-contact packaging applications, offering a clear go-to-market angle.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized abaca processors and biocomposite developers given the increasing demand for sustainable materials in automotive and packaging. Long-term viability is strong, driven by regulatory tailwinds and diversification into high-value applications. A signal to watch is the increasing adoption rate of abaca-based components by Tier 1 automotive suppliers in Germany, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Digital Traceability | Enhances supply chain transparency for European automotive and specialty goods importers. |
| Develop Biocomposite Formulations | Unlocks new applications in sustainable construction and electronics casings for abaca fiber. |
| Geographic Cultivation Diversification | Reduces single-country supply concentration risk from the Philippines for global buyers. |
| Expand Food-Contact Certifications | Accesses premium market segments such as specialty teabags and food packaging. |
| Establish Long-Term Offtake Agreements | Secures stable demand and consistent pricing for high-grade abaca fiber producers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with PhilFIDA representatives, automotive engineers, specialty paper manufacturers, and textile designers. This approach ensured a robust bottom-up and top-down triangulation of market data. Industry association publications and academic research on biocomposites further validated market trends and dynamics.
Granularity at the product type, end-user, application, quality grade, and geographic region levels informed the analytical framework across the analysis window. Compound annual growth rates were derived from historical trends, market drivers, and expert projections. Automotive lightweighting mandates and EU sustainability policies served as key industry-specific forecast inputs for future growth projections.
The model assumes a particular technology adoption path; alternative pathways for advanced processing techniques and biocomposite integration would alter the outlook. Forecasts reflect assumptions regarding climate stability in key growing regions and the pace of new synthetic fiber developments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
North America Cotton Market
Natural Fibers
Silk Textiles Market
Natural Fibers
Textile Staples Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Cellulose Market
Natural Fibers
Silk Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market
Natural Fibers
Cellulose Fiber Market
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
Silk Stocking Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Jute Bags Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Down and Feather Market