
 Sugarcane Fiber Bowls Market | 2026-2036
Sugarcane Fiber Bowls Market Size, Share, and Industry Trends Forecast 2026-2036
Sugarcane Fiber Bowls Market Analysis
Foodservice procurement is shifting toward fiber-based alternatives as quick-service chains and institutional caterers phase out petroleum-derived disposables. Eco-Products, Inc. leverages its vertically integrated North American manufacturing footprint to secure national distribution contracts with major restaurant groups. Huhtamaki Group anchors European supply through its molded fiber production network, while Vegware Ltd. competes aggressively on compostability certification breadth across the United Kingdom and Ireland.
Sugarcane fiber bowls are molded from bagasse pulp, the fibrous residue remaining after juice extraction, typically processed with water-based binders and pressed into rigid forms that withstand temperatures up to 200 degrees Fahrenheit for hot food service. The biodegradable product type dominates current volume as municipal composting programs in the United States and European Union expand acceptable feedstock lists. Medium-capacity bowls lead restaurant segment adoption, matching standard entrée portions, while wholesale distribution channels capture the largest margin pools through direct foodservice contracts that bypass retail markups.
The United States Environmental Protection Agency classifies bagasse products as renewable feedstocks under federal procurement guidelines, while the European Union's Packaging and Packaging Waste Regulation mandates recyclability and compostability benchmarks that sugarcane fiber bowls already meet. California's SB 54 and New York's expanded polystyrene prohibitions create state-level enforcement mechanisms that accelerate buyer migration. Stakeholders must monitor composting infrastructure buildout rates, as regional gaps between product compostability and actual facility availability will determine which geographic markets sustain premium pricing versus commodity compression.
Market Dynamics
Single-use plastic bans across multiple jurisdictions are compressing substitution timelines for foodservice disposables, forcing procurement departments to validate fiber-based alternatives against performance benchmarks previously satisfied by petroleum-derived serveware. This regulatory compression is accelerating supplier qualification cycles and reshaping contract structures.
Growth Catalysts
- Extended Producer Responsibility frameworks:California's SB 54 mandates producer accountability for packaging end-of-life, redirecting institutional procurement toward compostable bagasse alternatives that satisfy post-consumer recovery obligations.
- Quick-service restaurant sustainability mandates:Corporate net-zero commitments by major chains are embedding plant-based serveware into supply agreements, with fiber bowls specified in national distribution contracts.
- Municipal composting infrastructure expansion:United States cities including Seattle, San Francisco, and Austin have expanded curbside organics collection to accept bagasse products, validating premium pricing for certified compostable serveware.
Market Restraints
- Pulp input cost volatility:Sugarcane bagasse supply concentrates in Brazil and India, exposing converters to agricultural commodity cycles and harvest-season price swings.
- Moisture barrier limitations:Unlined fiber bowls exhibit performance degradation beyond four hours with high-fat content foods, restricting application in certain catering and delivery formats.
- Per-unit cost premium:Molded fiber production requires higher capital intensity than expanded polystyrene thermoforming, compressing margins for mid-volume foodservice operators.
Strategic Opportunities
- India foodservice modernization:Quick-service penetration in tier-two Indian cities is outpacing local molded fiber supply, creating entry points for bagasse bowl exporters with BIS certification.
- PFAS-free barrier coatings:Fluoropolymer-free oil and moisture barriers are converging with fiber molding technology, opening premium positioning in health-conscious institutional segments.
- Direct-to-caterer digital platforms:Foodservice e-procurement portals are disintermediating traditional distribution, enabling bowl manufacturers to capture margin pools previously allocated to wholesale intermediaries.
Industry Challenges
- Compostability certification timelines:BPI and TÜV Austria OK Compost HOME verification processes extend 8-14 months, delaying product launches and contract awards.
- Hot-fill structural integrity:Maintaining bowl rigidity above 200 degrees Fahrenheit without plastic liners requires proprietary fiber blends and pressing parameters that remain closely guarded.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugarcane Fiber Bowls Market |
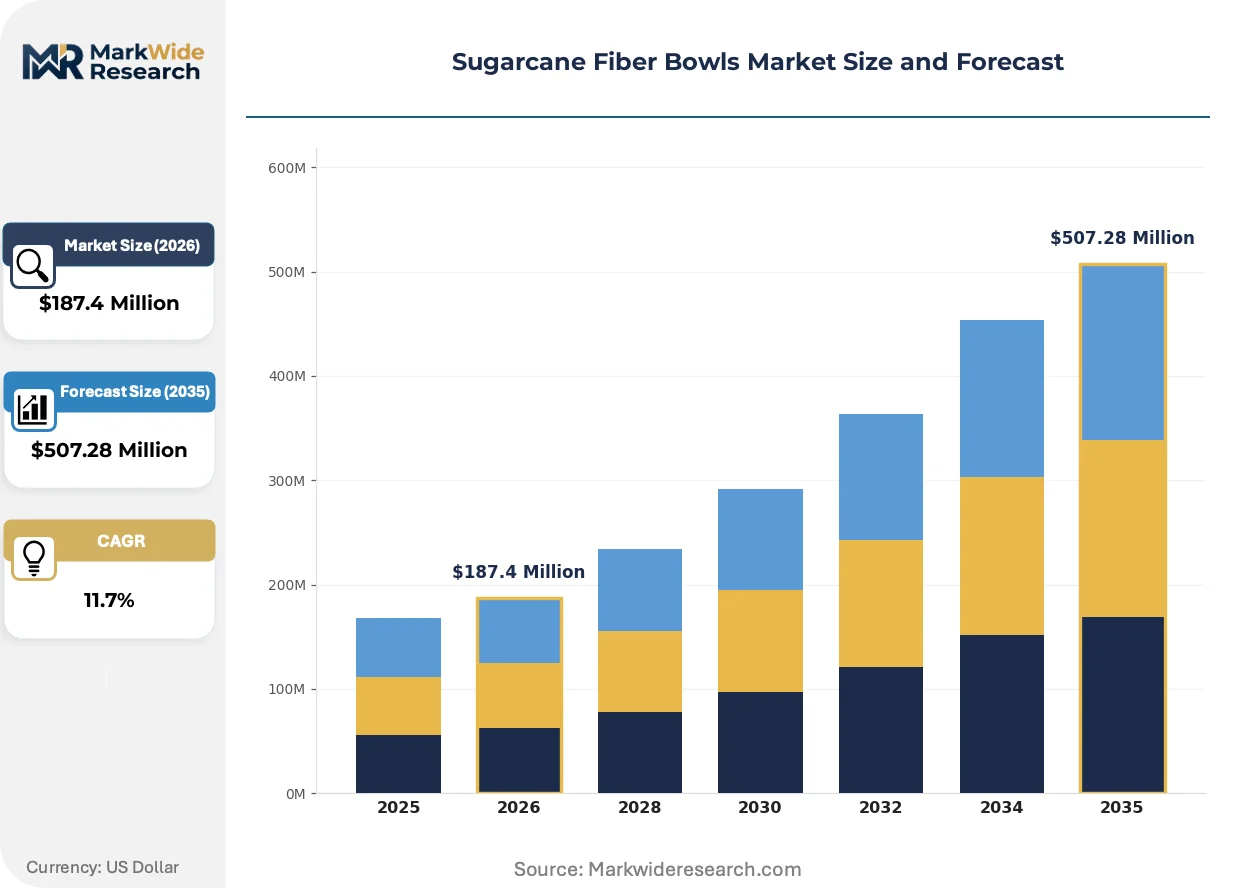
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Biodegradable, Durable End User: Restaurants, Cafes, Catering Services, Food Trucks Capacity: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Eco-Products, Inc., Huhtamaki Group, Vegware Ltd., Dine Earth, Green Paper Products, Pappco Greenware, BioPak, World Centric, Bio Futura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugarcane Fiber Bowls Market Emerging Trajectories
Bagasse fiber processing is advancing through precision molding and barrier integration, collapsing the performance gap between plant-based serveware and conventional plastics. These developments are compressing buyer evaluation cycles and expanding addressable application spaces.
Advanced pulp refining technology is unifying fiber distribution and binder integration to achieve consistent wall thickness and heat tolerance. Quick-service chains in the United States are specifying these grades for hot soup and rice bowl applications. The technology is unifying previously separate performance tiers, enabling single-SKU procurement across temperature requirements.
The European Union's Packaging and Packaging Waste Regulation mandates recyclability and compostability benchmarks that bagasse bowls already satisfy. Industrial consequence includes accelerated phase-out of multi-material laminates that cannot meet single-stream recovery standards. Foodservice operators in Germany and France are responding by consolidating supplier bases around certified fiber alternatives.
Corporate sustainability reporting requirements under CSRD are embedding serveware emissions into scope-three calculations. Procurement departments are displacing traditional cost-per-unit metrics with lifecycle assessment scoring, favoring suppliers with verified carbon footprints. This recalibration is most visible in Nordic countries and the Netherlands, where municipal procurement guidelines prioritize climate impact over upfront price.
Sugarcane Fiber Bowls Market Segmentation
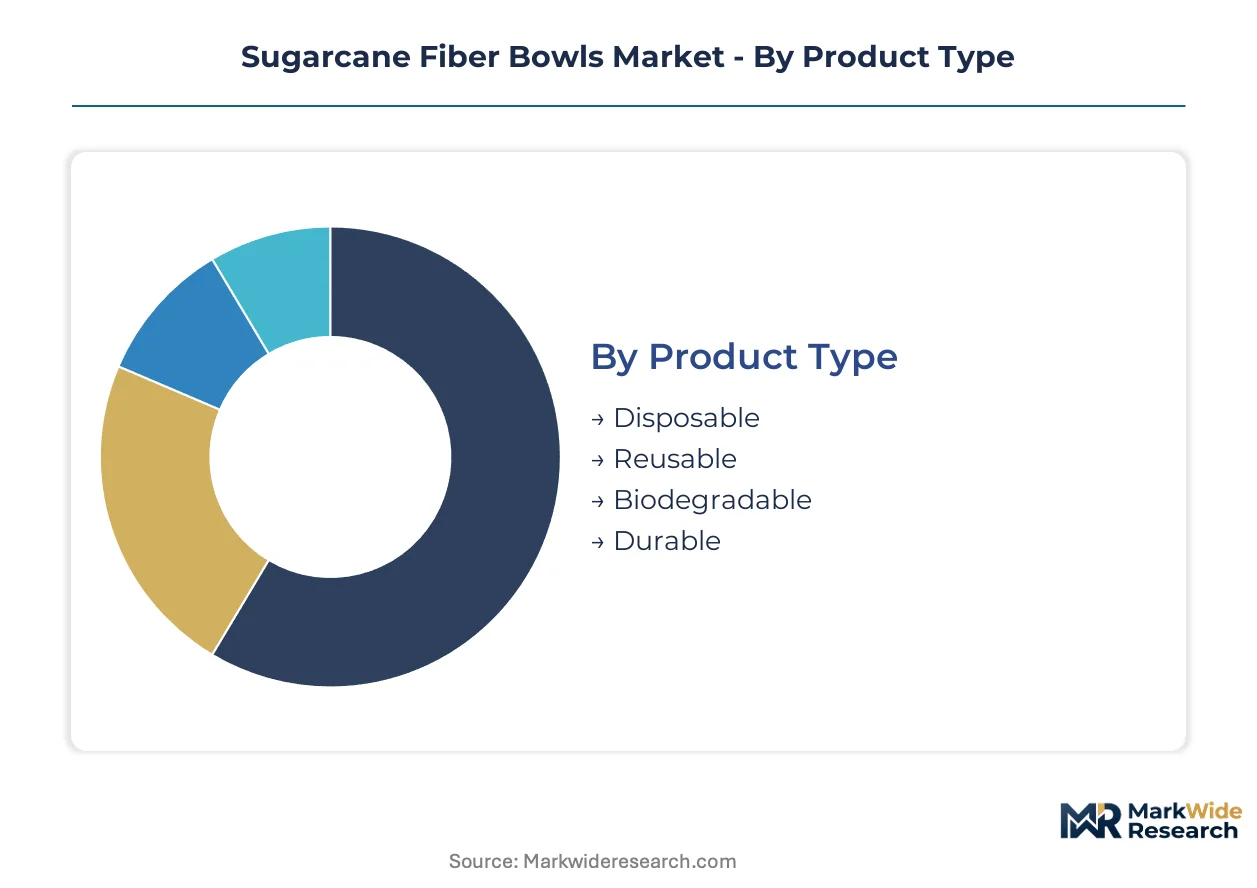
Sugarcane fiber bowls command distinct price premiums and performance expectations across buyer categories. Procurement departments evaluate segments against composting infrastructure access, food temperature requirements, and contract volume scales.
Product Type:
Buyers differentiate primarily by disposal pathway availability and reuse frequency mandates.
- Biodegradable:These bowls decompose within commercial composting cycles through unlined bagasse pulp construction with water-based binders. Quick-service chains in Seattle, San Francisco, and Austin specify this grade for municipal organics collection compliance.
- Disposable:Single-use bagasse bowls dominate current foodservice procurement, engineered for 200-degree Fahrenheit hot-fill applications without structural failure. California SB 54 enforcement is redirecting institutional buyers from expanded polystyrene toward this certified compostable alternative.
- Reusable:Thicker-walled variants withstand 50+ wash cycles in commercial dishwashers.
- Durable:Reinforced fiber blends target catering equipment rental pools.
Biodegradable leads volumes today; reusable is gaining share fastest.
End User:
Operational scale and menu thermal profile determine procurement specifications across buyer types.
- Restaurants:Full-service and quick-service operators specify medium-capacity bowls for entrée portions, with hot-soup applications demanding certified 200-degree Fahrenheit tolerance. Corporate net-zero commitments are embedding plant-based serveware into national distribution contracts.
- Catering Services:Event caterers prioritize stackability and transport stability for off-premise service, with four-hour moisture barrier performance limiting high-fat menu applications.
- Cafes:Coffeehouse chains source smaller capacities for grain bowls and breakfast applications.
- Food Trucks:Mobile operators favor lightweight disposables with space-efficient nesting.
Restaurants anchor procurement volumes; catering services are expanding most quickly.
Capacity:
Portion standardization and menu engineering drive capacity selection patterns.
- Medium:16-20 ounce bowls match standard entrée portions across quick-service rice and noodle concepts. United States foodservice distributors stock this capacity as the default SKU, capturing the largest margin pools through direct contracts.
- Large:24-32 ounce variants serve family-style and shared-plate formats, with structural rigidity requirements intensifying for loaded configurations. European institutional caterers in Germany and France are consolidating supplier bases around certified fiber alternatives in this capacity tier.
- Small:8-12 ounce sizes target dessert and side-dish applications.
- Extra Large:40+ ounce bowls address buffet and catering bulk service.
Medium capacity dominates current procurement; large is climbing the fastest.
Distribution Channel:
Margin capture and buyer relationship intensity separate channel strategies.
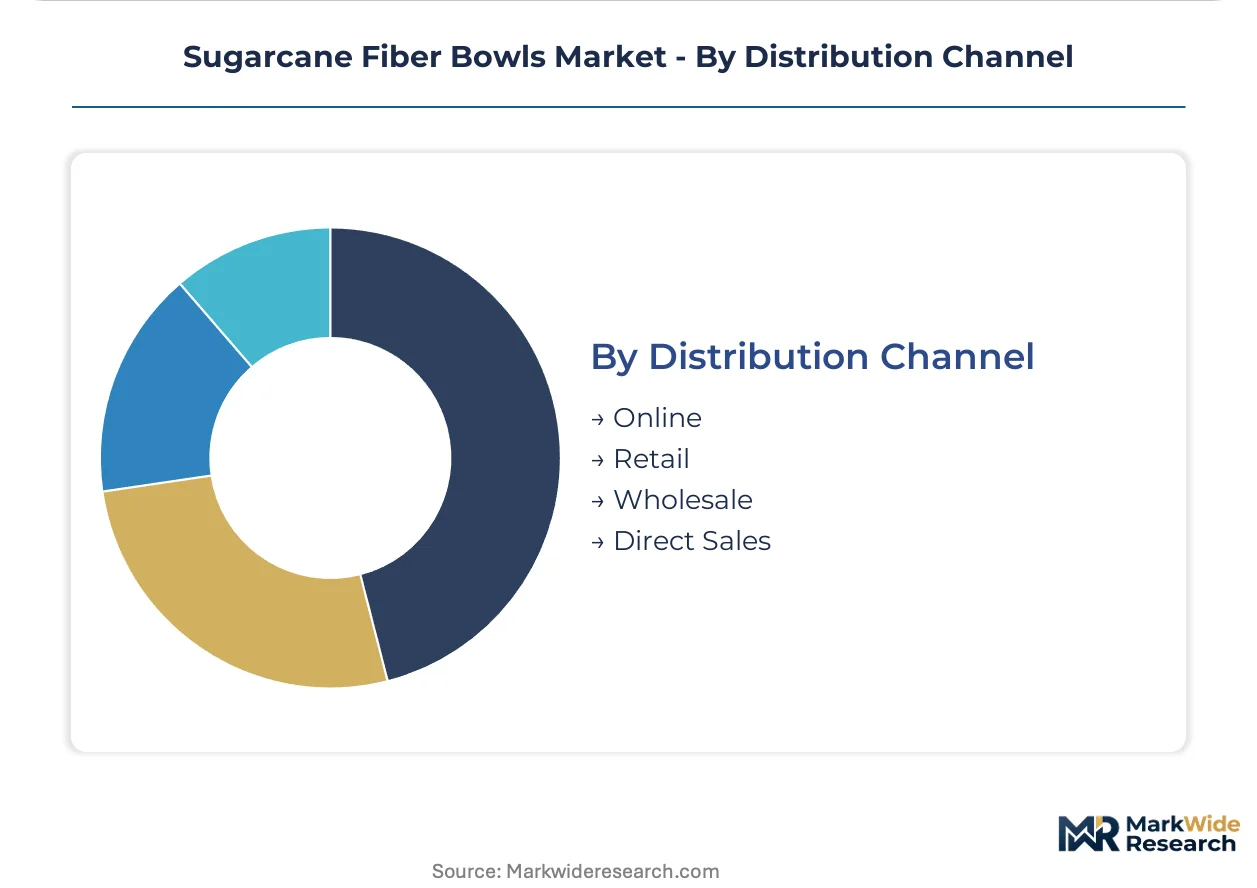
- Wholesale:Foodservice distributors capture premium margin pools through direct contracts with restaurant groups, bypassing retail markups. Eco-Products and Huhtamaki leverage vertically integrated manufacturing to secure national wholesale agreements.
- Online:E-procurement portals are disintermediating traditional distribution, enabling manufacturers to capture margins previously allocated to intermediaries. Vegware competes aggressively through digital platforms across the United Kingdom and Ireland.
- Retail:Club stores and restaurant supply outlets serve independent operators.
- Direct Sales:Manufacturer field teams manage enterprise accounts.
Wholesale channels lead transaction volumes; online is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting sugarcane fiber bowl production toward jurisdictions with lower compliance costs and expanding composting infrastructure. Brazil and India concentrate raw bagasse supply, while the United States and European Union absorb premium volumes through municipal procurement mandates.
United States
Quick-service restaurant chains are embedding plant-based serveware into national distribution contracts as corporate net-zero commitments harden. The Environmental Protection Agency classifies bagasse products as renewable feedstocks under federal procurement guidelines. Seattle, San Francisco, and Austin have expanded curbside organics collection to accept bagasse products, validating premium pricing for certified compostable serveware in these metropolitan clusters.
Germany
Institutional caterers are consolidating supplier bases around certified fiber alternatives as the Packaging and Packaging Waste Regulation mandates recyclability benchmarks. The country's national environmental regulator enforces strict compostability verification through TÜV Austria OK Compost HOME certification. Foodservice operators in Bavaria and North Rhine-Westphalia are responding by phasing out multi-material laminates that fail single-stream recovery standards.
India
Quick-service penetration in tier-two cities is outpacing local molded fiber supply, creating entry points for bagasse bowl exporters. The Bureau of Indian Standards certification requirement filters import competition while domestic capacity scales. Maharashtra and Gujarat host the primary agricultural processing corridors where bagasse pulp concentrates before conversion.
United Kingdom
Coffeehouse chains and grab-and-go operators are sourcing smaller-capacity bowls for grain bowl and breakfast applications. The Environment Agency enforces extended producer responsibility frameworks that redirect procurement toward compostable alternatives. Vegware competes aggressively through digital platforms across England and Ireland, capturing margin pools previously allocated to wholesale intermediaries.
Brazil
Sugarcane harvesting cycles in São Paulo and Minas Gerais generate the dominant share of global bagasse pulp feedstock. Agricultural commodity price swings expose converters to harvest-season volatility that compresses margin stability. Local processors are expanding downstream into molded fiber conversion to capture value previously exported as raw pulp.
Sugarcane Fiber Bowls Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers scale precision molding lines to meet compressed substitution timelines from single-use plastic bans. The vendor base stratifies between vertically integrated pulp-to-bowl operators and specialized converters dependent on third-party fiber supply. Three archetypes occupy distinct positions: North American integrated manufacturers, European sustainability-certified specialists, and Asia-Pacific export-oriented fabricators. M&A activity and geographic licensing agreements represent the dominant competitive moves as players secure feedstock access and distribution reach.
Among North American integrated manufacturers, Eco-Products, Inc. exemplifies the vertically controlled archetype through captive supply agreements and national distribution contracts. Huhtamaki Group anchors European positioning through molded fiber production networks that satisfy EU compostability mandates. Vegware Ltd. occupies the certification-breadth specialist tier, competing aggressively on compostability verification across the United Kingdom and Ireland. These three companies represent the strategic positioning vectors that other market participants must match or circumvent.
| Leading Market Players |
|---|
| Eco-Products, Inc. |
| Huhtamaki Group |
| Vegware Ltd. |
| Dine Earth |
| Green Paper Products |
| Pappco Greenware |
| BioPak |
| World Centric |
| Bio Futura |
| Others |
Supply Flow & Price Mechanics
Captive pulp-to-bowl manufacturing in São Paulo and Minas Gerais anchors both supply security and pricing power for converters serving North American and European buyers. This backward integration shields dominant producers from harvest-season agricultural commodity swings while enabling premium positioning against third-party fiber dependent competitors.
Pricing Analysis
Distributor margin layers compress most acutely in wholesale channels where Eco-Products and Huhtamaki leverage direct foodservice contracts to bypass intermediary markups. Three-tier pricing structure across certified compostable premium, standard BPI-verified, and economy unlined grades differentiates buyers by volume scale and certification breadth. Cost compression in the economy tier is intensifying because Brazilian pulp export pricing tracks ethanol market arbitrage. Quick-service restaurant procurement departments exhibit highest price sensitivity; institutional caterers with CSRD reporting mandates show lowest.
Supply Chain Analysis
Regional distribution centers in São Paulo state feed hub-and-spoke patterns radiating through Santos port infrastructure toward Atlantic shipping lanes. Raw bagasse pulp concentrates in Brazil and India; water-based binder chemistries source from German and Chinese specialty chemical producers. Supply chain risk centers on single-source vulnerability for PFAS-free barrier coatings where approved suppliers remain limited. Distribution runs through foodservice distributor networks in the United States and digital procurement platforms across the United Kingdom and Ireland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in sugarcane fiber bowls rests on PFAS-free barrier coating cost curves flattening and certified compostable premiums widening against conventional plastic alternatives.
For Market Incumbents: Acquire captive bagasse pulp processing capacity in Maharashtra or Gujarat to secure feedstock access as Indian quick-service demand outstrips local molded fiber supply. Deepen TÜV Austria OK Compost HOME certification breadth to defend against Vegware's verification advantage in European institutional segments. Prioritize hot-fill structural integrity R&D above 200 degrees Fahrenheit to maintain performance differentiation against emerging Asian converters. For New Entrants and Emerging Players: Foodservice e-procurement portals offer the most penetrable channel wedge for bypassing established distributor relationships. Target tier-two Indian cities where quick-service penetration exceeds local bagasse bowl supply and BIS certification filters import competition. Lead with PFAS-free barrier coating partnerships to capture health-conscious institutional segments in Nordic countries and the Netherlands. For Investors and Strategic Acquirers: Roll-up economics work for regional molded fiber converters because compostability certification timelines extend 8-14 months and create acquisition windows before product launch delays erode target valuations. Focus on mid-cap specialists with existing BPI or TÜV Austria verification and captive pulp agreements in Brazil or India. Monitor municipal composting infrastructure buildout rates in United States metropolitan clusters as the inflection signal for sustained premium pricing versus commodity compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Pulp | Eco-Products' São Paulo supply agreements shield margin stability from harvest-season volatility. |
| PFAS-Free Barrier Certification | TÜV Austria OK Compost HOME verification opens premium positioning in CSRD-mandated procurement. |
| Direct-to-Caterer Digital Platform | Vegware's e-procurement capture disintermediates wholesale margin pools across the United Kingdom. |
| Hot-Fill Structural Integrity R&D | Proprietary fiber blends above 200 degrees Fahrenheit defend quick-service rice bowl specifications. |
| Municipal Composting Infrastructure Partnership | Seattle and San Francisco curbside organics collection validates premium pricing for certified grades. |
Methodological Framework
Multiple input streams — primary interviews with foodservice procurement directors, molded fiber plant managers, and composting facility operators; secondary validation through EPA renewable feedstock guidelines, EU Packaging and Packaging Waste Regulation filings, and BPI certification databases — were reconciled through bottom-up production capacity modeling and top-down demand segmentation triangulation.
Data-stream reconciliation across product type, capacity tier, end-use application, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume buildups cross-referenced against substitution timelines from single-use plastic bans. Industry-specific forecast inputs included municipal composting infrastructure buildout rates and quick-service restaurant net-zero commitment disclosure frequencies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PFAS-free coating supplier expansion and Brazilian agricultural commodity cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Thailand Textile Market
Natural Fibers
Down and Feather Market
Natural Fibers
Silk Fabric Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Silk Stocking Market
Natural Fibers
Textile Staples Market
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Cellulose Fiber Market
Natural Fibers
Gum Fiber Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
North America Alpaca Fiber Market
Natural Fibers
Sugarcane Fiber Market