
 Zinc Gluconate Market | 2026-2036
Zinc Gluconate Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Gluconate Market Outlook
REACH compliance and the EU Green Deal is broadening the sustainability requirements for mineral excipient sourcing across European pharmaceutical supply chains. Jost Chemical leverages its US-based manufacturing footprint to serve North American nutraceutical formulators with high-purity grades. Fuso Chemical anchors its position through specialized fermentation-derived production capabilities in Japan. Global Calcium competes on scale across multiple mineral salt categories including zinc gluconate for international export markets.
Zinc gluconate is the zinc salt of gluconic acid, typically containing approximately 14% elemental zinc by weight, produced through the reaction of zinc oxide or zinc carbonate with gluconic acid for use as a bioavailable mineral supplement and pharmaceutical excipient. Tablet and capsule formats dominate volume consumption due to established dosing precision and consumer familiarity in both prescription and over-the-counter channels. E-commerce distribution is expanding fastest as direct-to-consumer supplement brands bypass traditional wholesale structures, while pharmacy channels retain margin concentration through clinician-endorsed immune health positioning.
FDA regulations govern dietary supplement Good Manufacturing Practices and labeling claims for zinc content in the United States, while EFSA oversees health claim substantiation and maximum permitted levels across European member states. India's CDSCO and FSSAI frameworks are tightening quality standards for imported mineral premixes used in domestic pharmaceutical production. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional purity specifications to maintain formulation eligibility and avoid batch rejection at customs checkpoints.
Market Dynamics
Pharmaceutical-grade mineral sourcing is tightening under pharmacopeial purity mandates, forcing zinc gluconate suppliers to revalidate excipient specifications against USP-NF and EP monograph revisions while expanding analytical testing capacity.
Growth Catalysts
- Immune health positioning:Post-pandemic consumer retention of zinc supplementation habits sustains demand pull through pharmacy and direct-to-consumer channels. Formulators cite elemental zinc bioavailability as the primary selection criterion over alternative mineral salts.
- REACH and EU Green Deal alignment:Sustainability disclosure requirements for pharmaceutical supply chains favor fermentation-derived production methods with verifiable carbon footprints. European manufacturers prioritize suppliers with EMAS-registered facilities.
- Tablet compression advances:High-speed rotary press compatibility with zinc gluconate granulations enables contract manufacturers to achieve throughput rates matching calcium carbonate formulations. This process innovation reduces per-unit conversion costs for nutraceutical brands.
Market Restraints
- Gluconic acid feedstock concentration:Fermentation-based production relies on corn-derived glucose streams concentrated in North American and Brazilian agricultural processing regions. Climate volatility in these supply zones transmits price instability to zinc gluconate contract negotiations.
- Zinc oxide purity grade bifurcation:Technical-grade zinc oxide from electrothermal processes fails pharmaceutical impurity specifications, forcing reliance on electrolytic or SHG zinc sources with limited smelter availability. This input constraint elevates working capital requirements for qualified inventory.
- Bioequivalence documentation burden:Generic pharmaceutical filers must demonstrate dissolution profile equivalence against reference-listed drugs containing zinc gluconate. FDA bioequivalence study costs deter market entry for commoditized oral dosage forms.
Strategic Opportunities
- Pediatric formulation expansion:Orally dispersible tablet and liquid suspension formats remain underdeveloped relative to adult solid dosage forms. Zinc gluconate's neutral taste profile versus zinc sulfate creates formulation advantages for pediatric indication extensions.
- India CDSCO quality convergence:Domestic pharmaceutical manufacturers upgrading to ICH Q7 compliance standards seek qualified mineral salt suppliers with DMF Type II filings. Early DMF submission creates preferred supplier positioning as import substitution accelerates.
- Clean label certification stacking:Non-GMO Project verification, NSF Certified for Sport, and Informed Sport accreditation command 15-30% price premiums in specialty channels. Certification infrastructure investment differentiates commodity producers from premium-positioned competitors.
Industry Challenges
- Analytical method transfer complexity:Atomic absorption spectroscopy protocols for elemental zinc assay require cross-laboratory validation when sourcing from multiple production sites. Method equivalency failures trigger batch release delays and inventory stockouts.
- Excipient master file coordination:Zinc gluconate suppliers must maintain synchronized USP-NF, EP, and JP monograph compliance across regulatory reference standards. Pharmacopeial revision cycles create specification drift requiring proactive customer notification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Gluconate Market |
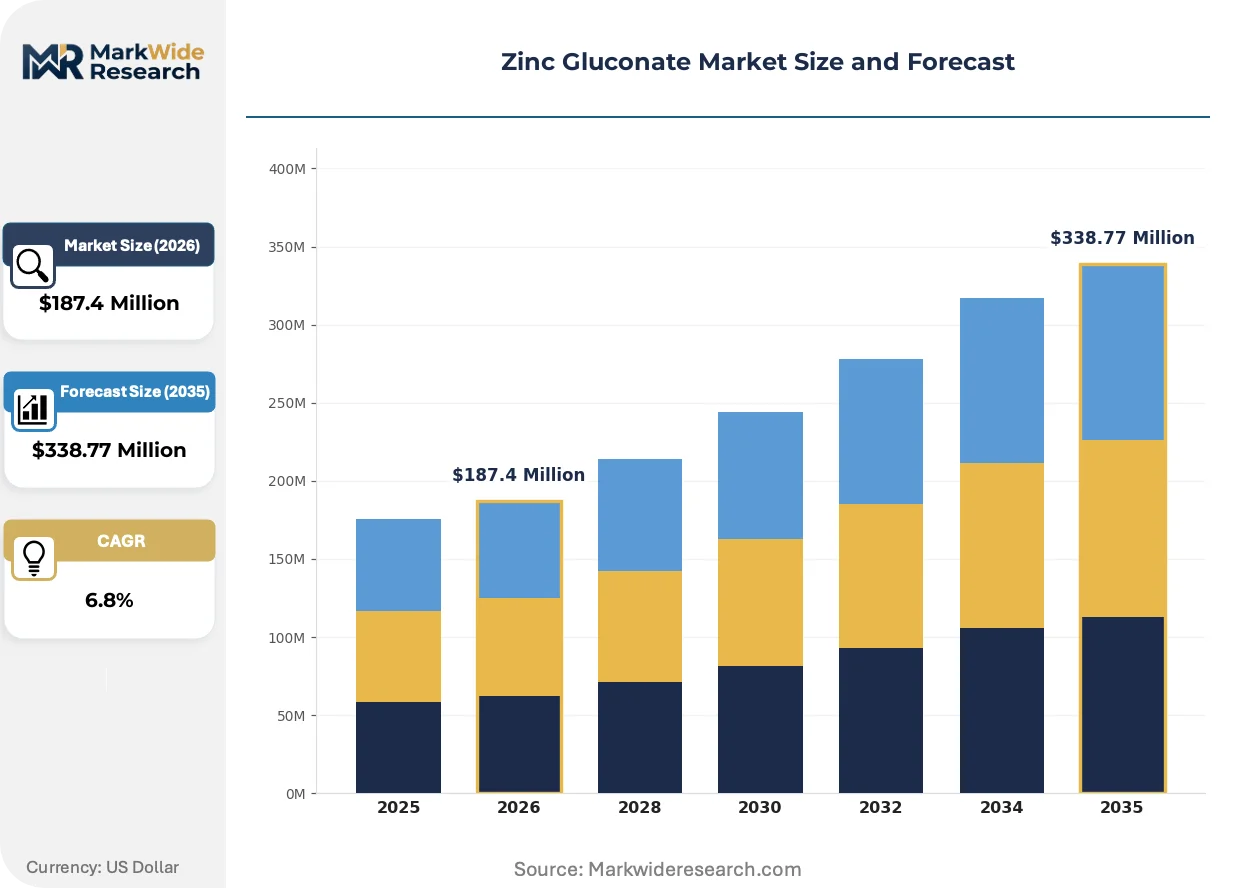
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powder, Liquid Formulation: Organic, Inorganic, Chewable, Effervescent End User: Pharmacies, Hospitals, Health Stores, Online Retailers Distribution Channel: Direct Sales, Wholesale, E-commerce, Specialty Stores |
| Companies Covered | Jost Chemical, Global Calcium, Ferro chem Industries, Tomita Pharmaceutical, Aditya Chemicals, Fuso Chemical, Kelatron, Fuqiang Food Chemical, Xingzhou Medicine Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Gluconate Market Strategic Shifts
Continuous manufacturing integration and real-time release testing are compressing quality assurance timelines, while regulatory disclosure requirements reshape supplier-customer data exchange protocols across mineral excipient value chains.
Direct compression-grade zinc gluconate with optimized particle size distribution is modularizing traditional wet granulation workflows. Nutraceutical contract manufacturers in Germany and the United States are adopting pre-granulated excipient systems to eliminate in-house processing steps. This technology compression reduces batch-to-batch variability while accelerating product development cycles for immune-support formulations.
EFSA's tightened health claim substantiation requirements under Regulation 1924/2006 are forcing zinc supplement marketers to retreat from specific immune function claims toward generic mineral adequacy positioning. The industrial consequence is reduced marketing differentiation and intensified price competition at retail shelf. German and French pharmacy chains are responding by consolidating supplier bases to manufacturers with established EFSA claim rejection appeal experience.
Subscription-based replenishment models are displacing traditional retail replenishment for zinc supplements. Direct-to-consumer brands bypass wholesale distribution markups through automated fulfillment infrastructure. This channel disintermediation concentrates demand among e-commerce-native formulators with integrated supply chain visibility, most visible in United States and United Kingdom metropolitan markets where same-day delivery expectations have normalized.
Zinc Gluconate Market Segmentation
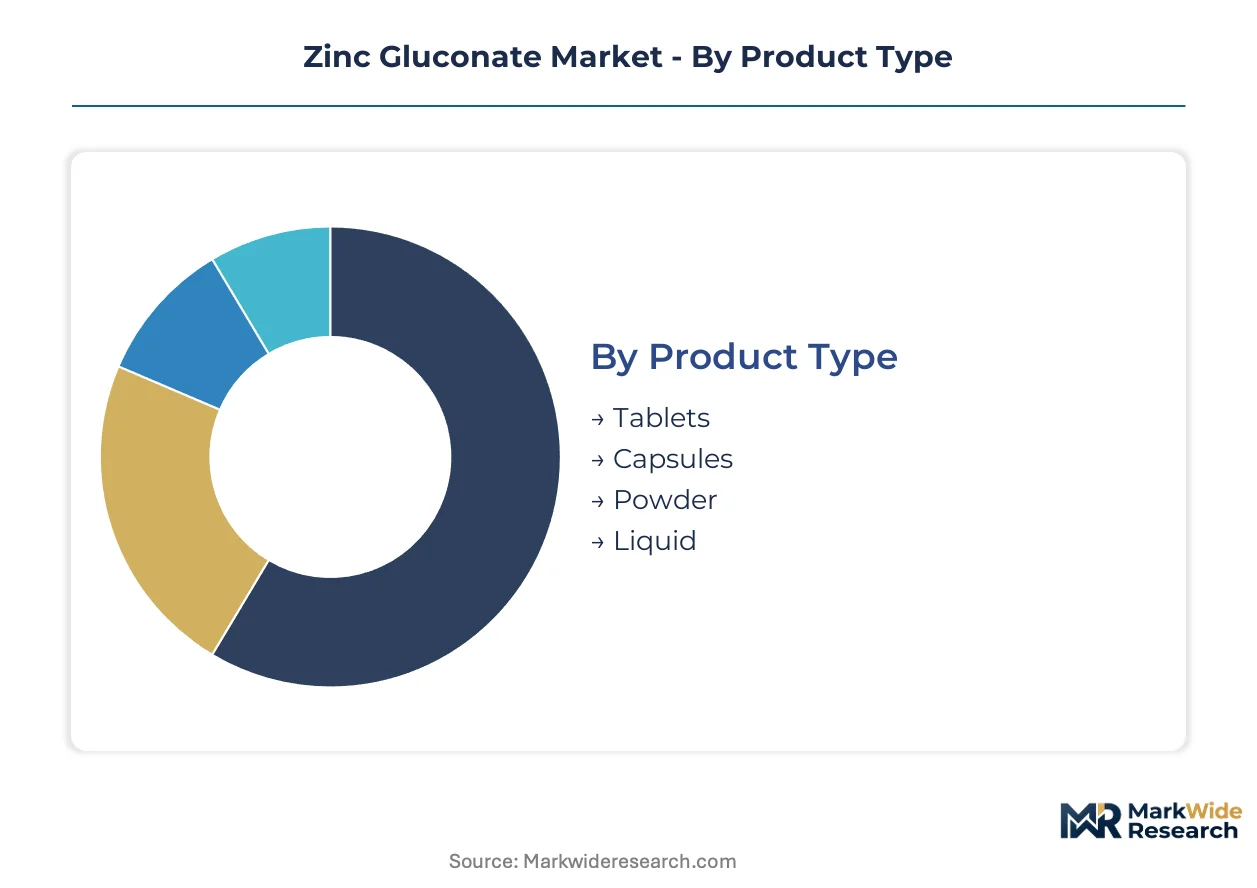
Zinc gluconate demand fragments across delivery formats, production methods, and procurement channels. Each segmentation axis reveals distinct margin profiles and regulatory exposure for suppliers navigating pharmaceutical versus nutraceutical customer bases.
Product Type:
Tablet and capsule specifications dominate pharmaceutical procurement due to dissolution profile standardization and compression compatibility with high-speed rotary equipment.
- Tablets:Direct-compression grades with optimized particle size distribution enable contract manufacturers to match calcium carbonate throughput rates. German and United States nutraceutical formulators drive specification tightening for friability and disintegration standards.
- Capsules:Hard gelatin and HPMC shell compatibility requires low-moisture zinc gluconate grades with residual gluconic acid below pharmacopeial limits. United States pharmacy chains favor capsule formats for clinician-endorsed immune health positioning.
- Powder:Bulk mineral premix applications in functional food manufacturing favor spray-dried agglomerates with enhanced flow properties.
- Liquid:Pediatric and geriatric indication expansion favors neutral-taste zinc gluconate solutions over astringent zinc sulfate alternatives.
Tablets lead on scale; liquid formats lead on momentum.
Formulation:
Cost tier stratification separates fermentation-derived organic grades from chemically synthesized alternatives, with certification premiums commanding 15-30% price spreads in specialty channels.
- Organic:Fermentation-derived production using corn glucose feedstock carries EMAS-registered facility requirements under EU Green Deal sourcing mandates. REACH compliance documentation elevates supplier qualification barriers for European pharmaceutical manufacturers.
- Inorganic:Direct reaction of electrolytic zinc oxide with synthetic gluconic acid serves commodity nutraceutical segments with lower purity tolerances.
- Chewable:Taste-masked granulations with compressibility optimized for pediatric dosing require specialized excipient binding systems.
- Effervescent:Acid-base reaction compatibility demands anhydrous zinc gluconate grades with strict moisture specifications to prevent premature effervescence.
Organic formulations command premium positioning; effervescent formats are gaining share fastest.
End User:
Customer type determines regulatory scrutiny intensity, with hospital procurement requiring pharmacopeial-grade documentation versus relaxed specifications for health store channels.
- Pharmacies:Clinician endorsement protocols in Germany and France require EFSA-compliant health claim substantiation, forcing retreat from specific immune function claims toward generic mineral adequacy positioning.
- Hospitals:Parenteral nutrition and therapeutic zinc repletion protocols demand USP-NF injectable-grade specifications with endotoxin and heavy metal testing beyond oral-grade requirements.
- Health Stores:Independent retailers in United States metropolitan markets prioritize clean label certification stacking including Non-GMO Project and NSF Certified for Sport verification.
- Online Retailers:Subscription-based replenishment models displace traditional wholesale distribution, concentrating demand among e-commerce-native formulators with integrated supply chain visibility.
Pharmacies dominate volume concentration; online retailers show steepest expansion trajectory.
Distribution Channel:
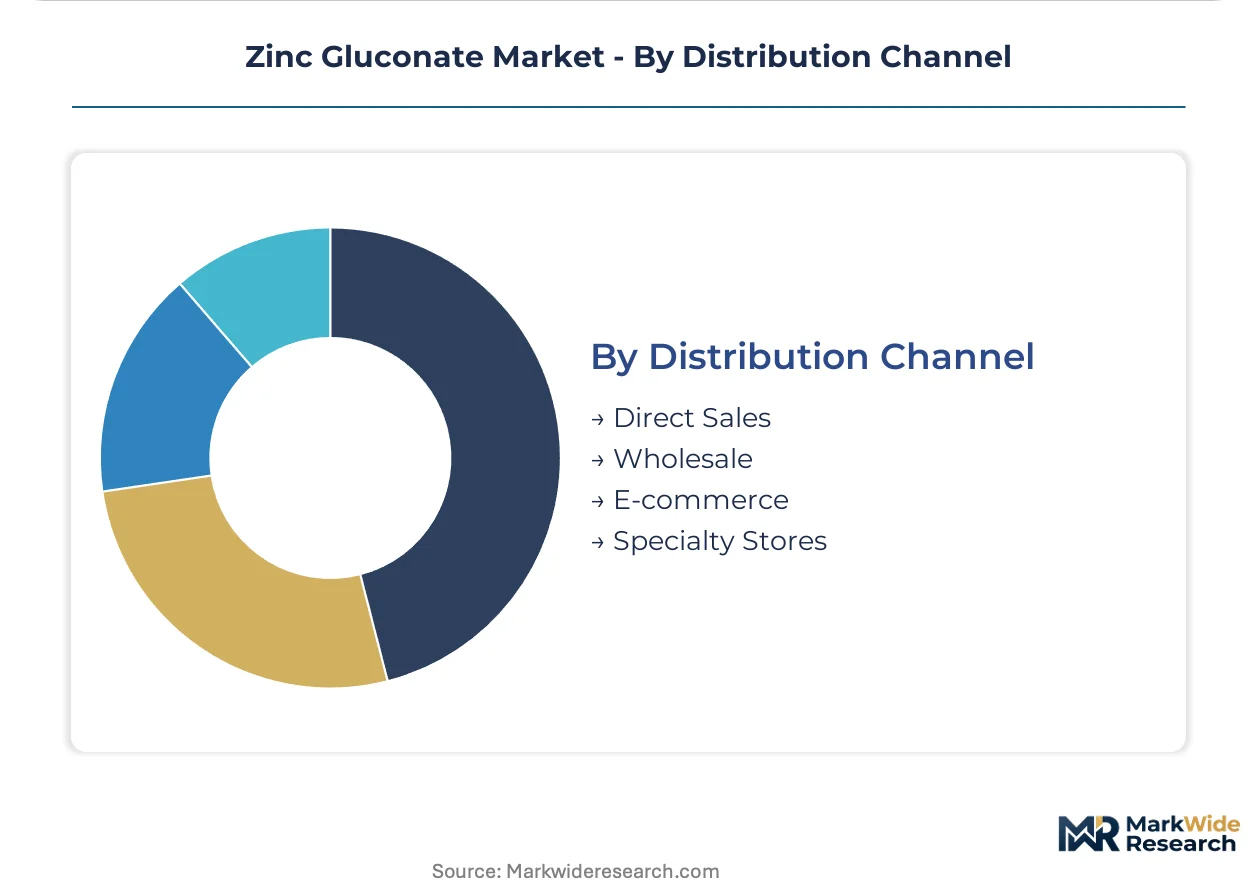
Channel configuration determines working capital requirements and margin capture, with direct sales offering price control at the cost of customer acquisition overhead.
- Direct Sales:Long-term supply agreements with pharmaceutical manufacturers lock in specification-validated inventory with quarterly price adjustment clauses tied to zinc oxide commodity indices.
- Wholesale:Traditional distributor networks retain relevance for pharmacy chain consolidation in Western Europe, though margin compression from generic competition limits growth.
- E-commerce:Direct-to-consumer brands bypass wholesale markups through automated fulfillment infrastructure, with same-day delivery expectations normalizing in United Kingdom and United States urban markets.
- Specialty Stores:Sports nutrition and premium wellness retailers command certification-stacked products with batch-level traceability documentation for athlete safety protocols.
Wholesale channels anchor current volume; e-commerce is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zinc gluconate manufacturing traces its industrial roots to post-war Japanese fermentation technology, later adopted by European and North American pharmaceutical suppliers seeking bioavailable mineral salts for therapeutic applications.
United States
Pharmaceutical-grade demand concentrates in New Jersey and Pennsylvania contract manufacturing corridors serving immune-support supplement brands. FDA dietary supplement GMP enforcement tightened elemental zinc labeling tolerances, forcing reformulation audits across nutraceutical portfolios. Direct-to-consumer subscription brands in Austin and San Francisco metro areas bypass wholesale distribution through vertically integrated fulfillment networks.
Germany
EFSA health claim substantiation requirements under Regulation 1924/2006 constrain immune-specific marketing claims, compressing margin structures for pharmacy-distributed zinc formulations. REACH compliance documentation and EU Green Deal sustainability disclosures favor EMAS-registered suppliers with verifiable carbon footprints. The Rhine-Ruhr industrial cluster hosts specialized mineral salt processors serving Benelux and French pharmaceutical formulators.
Japan
Fermentation-derived production capabilities anchor output in the Kansai region, where gluconic acid expertise from traditional food additive manufacturing transfers to pharmaceutical-grade mineral synthesis. PMDA pharmacopeial standards exceed USP-NF specifications for residual moisture and heavy metal content, creating export qualification barriers. Osaka-based suppliers supply Southeast Asian generic pharmaceutical manufacturers upgrading to ICH Q7 compliance.
India
CDSCO and FSSAI quality convergence drives import substitution for mineral premixes previously sourced from Chinese suppliers. Gujarat and Maharashtra pharmaceutical manufacturing zones seek DMF Type II-qualified zinc gluconate for domestic tablet and capsule production. Hyderabad's active pharmaceutical ingredient cluster expands backward integration into excipient-grade mineral salts to reduce customs dependency.
China
Shandong and Jiangsu provinces concentrate chemically synthesized zinc gluconate capacity serving commodity nutraceutical export markets. NMPA pharmacopeial revisions align with USP-NF and EP standards, elevating analytical testing requirements for international shipment eligibility. Qingdao port logistics infrastructure supports bulk mineral salt distribution to Southeast Asian and Latin American formulators.
Zinc Gluconate Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade stratification, with fermentation-derived organic grades commanding 15-30% price spreads over chemically synthesized alternatives. The supplier base organizes into three functional tiers: multinational mineral salt specialists with pharmacopeial dossier depth, regional chemical processors serving generic nutraceutical volume, and fermentation-technology anchors with EMAS-registered European facilities. Consolidation pressure intensifies through DMF Type II filing races in India and capacity expansion for direct-compression-grade specifications in Germany and the United States.
Within the multinational specialist tier, Jost Chemical and Global Calcium exemplify divergent geographic anchoring strategies—Jost leveraging US-based manufacturing for North American nutraceutical formulators, Global Calcium competing on scale across multiple mineral salt export categories. Fuso Chemical occupies a position representing fermentation-technology heritage, its Kansai-region production capabilities aligning with EU Green Deal sustainability mandates. These three entities illustrate how supplier qualification depth, rather than unit production cost, determines preferred vendor status in pharmaceutical-grade procurement channels.
| Leading Market Players |
|---|
| Jost Chemical |
| Global Calcium |
| Ferro chem Industries |
| Tomita Pharmaceutical |
| Aditya Chemicals |
| Fuso Chemical |
| Kelatron |
| Fuqiang Food Chemical |
| Xingzhou Medicine Foods |
| Others |
Value Chain & Pricing Dynamics
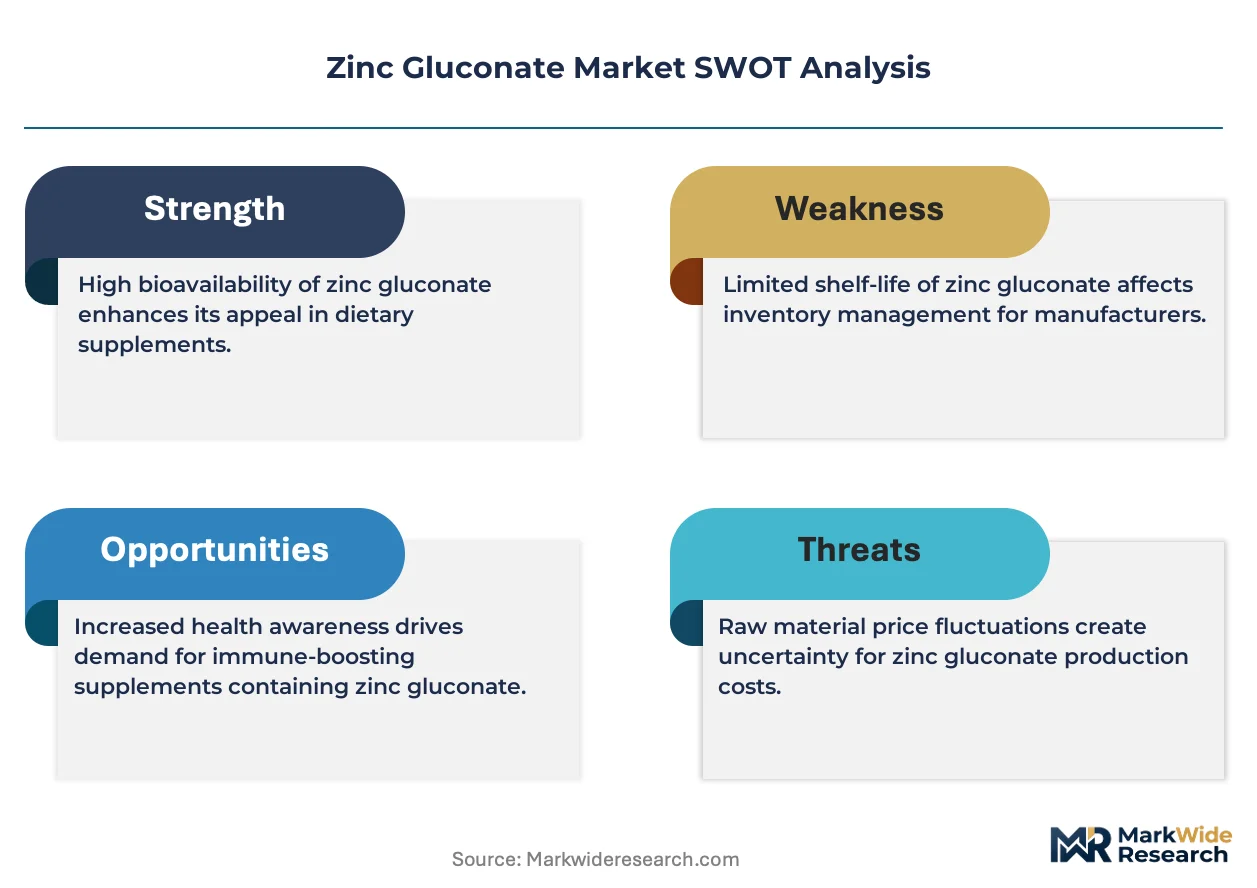
Pharmaceutical-grade purity mandates from USP-NF and EP monograph revisions are forcing contract manufacturers to requalify zinc gluconate suppliers, compressing procurement timelines and elevating working capital requirements for inventory holding. This specification tightening concentrates purchasing power among EMAS-registered fermentation producers with DMF Type II filings, widening price spreads against commodity chemical synthesis alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived organic grades with EMAS certification from electrolytic zinc-based standard grades and chemically synthesized economy tiers. Price differentiation hinges on pharmacopeial dossier depth and clean label certification stacking including Non-GMO Project verification. Cost compression in the economy tier is intensifying because Shandong and Jiangsu capacity expansion outpaces quality-upgraded demand growth. Pharmacy chains and hospital procurement groups exhibit lowest price sensitivity; generic nutraceutical formulators sourcing through wholesale distributors show highest elasticity.
Supply Chain Analysis
Direct sales channels serving pharmaceutical manufacturers with long-term offtake agreements handle volume concentration, while e-commerce-native formulators bypass traditional distribution layers. Production gravity centers on Japan's Kansai fermentation corridor, Germany's Rhine-Ruhr mineral processing cluster, and China's Shandong chemical synthesis zone. Raw material supply draws from corn-derived glucose streams in North America and Brazil, electrolytic zinc oxide from limited smelter sources, and gluconic acid from specialized fermentation capacity. Single-source vulnerability in qualified zinc oxide feedstock creates supply chain risk. Distribution runs through port logistics at Qingdao, Osaka, and Rotterdam for Asia-Pacific, European, and North American downstream markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zinc gluconate functions as a stable compounder anchored by persistent immune health supplementation habits retained from pandemic-era consumer behavior. Post-pandemic zinc retention patterns create predictable demand baselines across pharmacy and direct-to-consumer channels.
For Market Incumbents: Acquire DMF Type II filing capabilities in India to preempt CDSCO quality convergence requirements. Backward integration into electrolytic zinc oxide sourcing defends margin position against feedstock purity grade bifurcation. Jost Chemical and Global Calcium illustrate how pharmacopeial dossier depth, rather than unit production cost, determines preferred vendor status in pharmaceutical-grade procurement channels. EMAS-registered facility expansion secures EU Green Deal alignment premiums. For New Entrants and Emerging Players: E-commerce subscription infrastructure offers the lowest barrier route for direct-to-consumer zinc supplement brands bypassing wholesale markups. Pediatric liquid suspension formats remain underdeveloped relative to adult solid dosage forms, creating white-space expansion potential. Clinician-endorsed immune health positioning through pharmacy chains in Germany and France requires EFSA claim rejection appeal experience as a go-to-market prerequisite. Certification stacking including NSF Certified for Sport unlocks specialty channel access. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-technology specialists with verifiable carbon footprints under EU Green Deal sourcing mandates. The five-to-ten-year viability window favors suppliers with synchronized USP-NF, EP, and JP monograph compliance infrastructure. Target acquisition archetype: EMAS-registered European facilities with DMF Type II filings and direct-compression-grade particle size optimization capabilities. Watch for pharmacopeial revision cycles triggering specification drift and customer notification system failures as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| DMF Type II Filing Acceleration | CDSCO quality convergence in India creates preferred supplier positioning for early filers. |
| Fermentation Capacity Expansion | EMAS-registered Kansai-region facilities align with EU Green Deal sustainability mandates. |
| Direct-Compression Grade Development | Optimized particle size distribution enables throughput matching calcium carbonate formulations. |
| Clean Label Certification Stacking | Non-GMO Project and NSF Certified for Sport verification commands specialty channel premiums. |
| Backward Integration into Zinc Oxide | Captive supply of electrolytic-grade feedstock mitigates purity grade bifurcation risk. |
Study Parameters
Bottom-up pharmaceutical and nutraceutical formulation modeling reconciled against top-down mineral salt production tracking forms the analytical core of this study. Primary interviews with regulatory affairs directors at excipient suppliers, procurement managers at German and United States contract manufacturers, and pharmacy chain category buyers in France and the United Kingdom provided demand-side validation. Secondary sources include USP-NF and EP pharmacopeial monograph revisions, CDSCO import substitution policy circulars, EFSA health claim substantiation databases, and customs trade data for zinc gluconate shipments through Rotterdam, Osaka, and Qingdao ports. Cross-referencing bottom-up dosage form demand against top-down production capacity estimates ensures statistical coherence.
Input-output matrices mapping corn glucose feedstock availability, electrolytic zinc oxide smelter output, and fermentation-derived gluconic acid capacity to finished zinc gluconate production anchor the forecast framework. Segmentation dimensions span product type (tablet, capsule, powder, liquid), formulation grade (organic fermentation-derived, inorganic chemical synthesis), end user (pharmacy, hospital, health store, online retailer), and distribution channel (direct sales, wholesale, e-commerce, specialty store). CAGRs derive from elasticity-adjusted demand projections across these dimensions, incorporating tablet compression technology adoption curves and subscription-based replenishment model penetration rates.
The model assumes a particular technology adoption path; alternative pathways for continuous manufacturing integration with real-time release testing would alter the outlook. Forecasts reflect assumptions regarding REACH compliance timeline adherence, EFSA health claim substantiation stringency, and CDSCO quality convergence implementation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Immunity Boosting Food Market
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Asia-Pacific Dietary Supplement Market
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
Raspberry Ketones Market
Nutritional Supplements
Canada Whey Protein Market