
 United States Botanical Supplements Market | 2026-2036
United States Botanical Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
United States Botanical Supplements Market Analytics
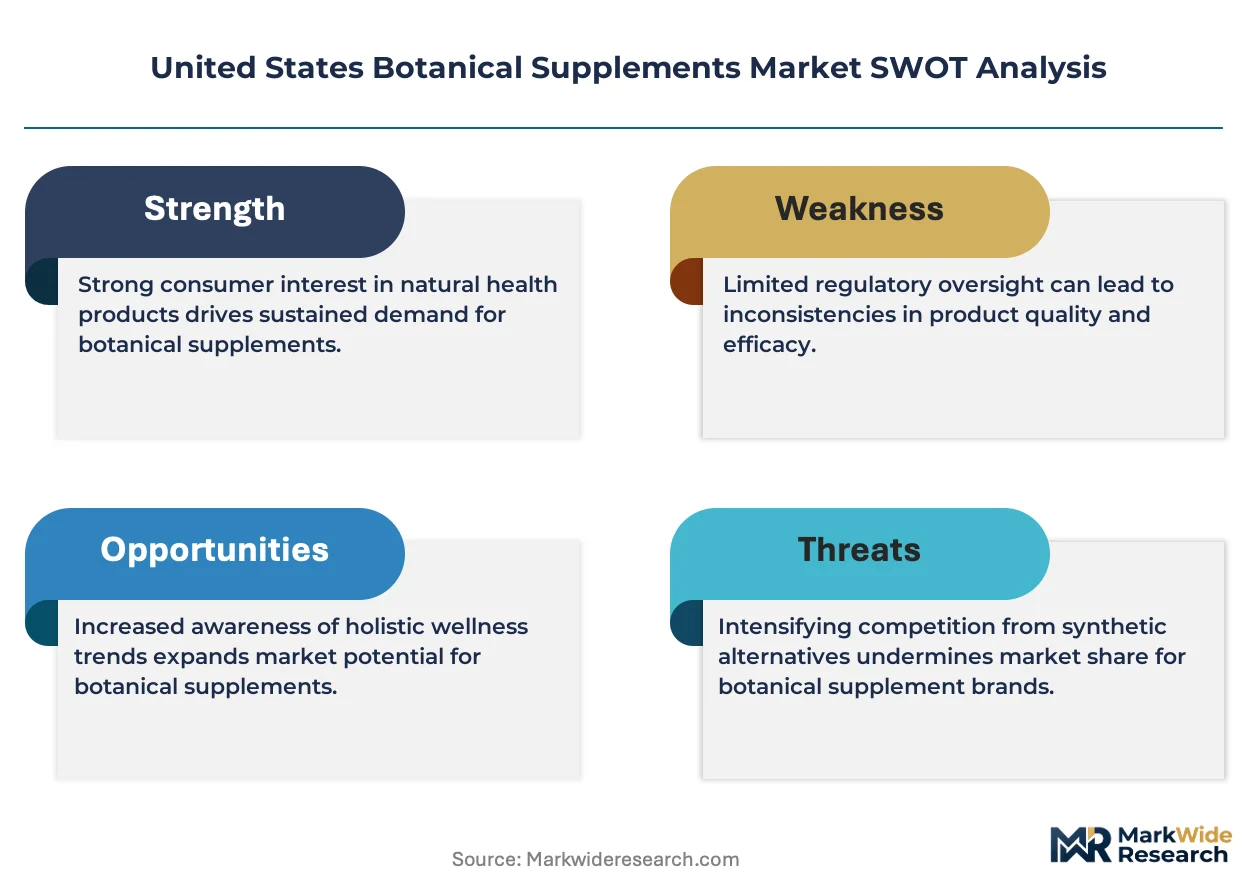
DSHEA modernization momentum is hardening quality expectations across the botanical supply chain. NOW Foods anchors its position through vertical integration from raw herb sourcing to finished capsule production. Gaia Herbs differentiates via organic farm partnerships and seed-to-shelf traceability systems. GNC Holdings competes through extensive retail storefront networks and practitioner channel relationships.
United States botanical supplements encompass plant-derived preparations standardized for bioactive compound content, including alkaloids, polyphenols, and terpenoids extracted through solvent, supercritical CO2, or cold-press methods, serving therapeutic, preventive, and functional wellness applications. Capsules dominate volume due to dosing precision and consumer convenience, while tinctures capture premium positioning among health professionals seeking rapid bioavailability. Online retail channels are expanding fastest as telehealth referrals and subscription models reshape how wellness centers and retail consumers replenish specialized botanical formulations.
FDA cGMP enforcement, USDA Organic certification, and United States Pharmacopeia verification standards collectively elevate barriers for unqualified entrants while rewarding documented quality systems. The FTC actively monitors structure-function claims, forcing brands to substantiate marketing language with clinical evidence or reformulate positioning. Stakeholders must monitor how FDA's anticipated pre-market notification framework for new dietary ingredients reshapes innovation pipelines and capital allocation decisions.
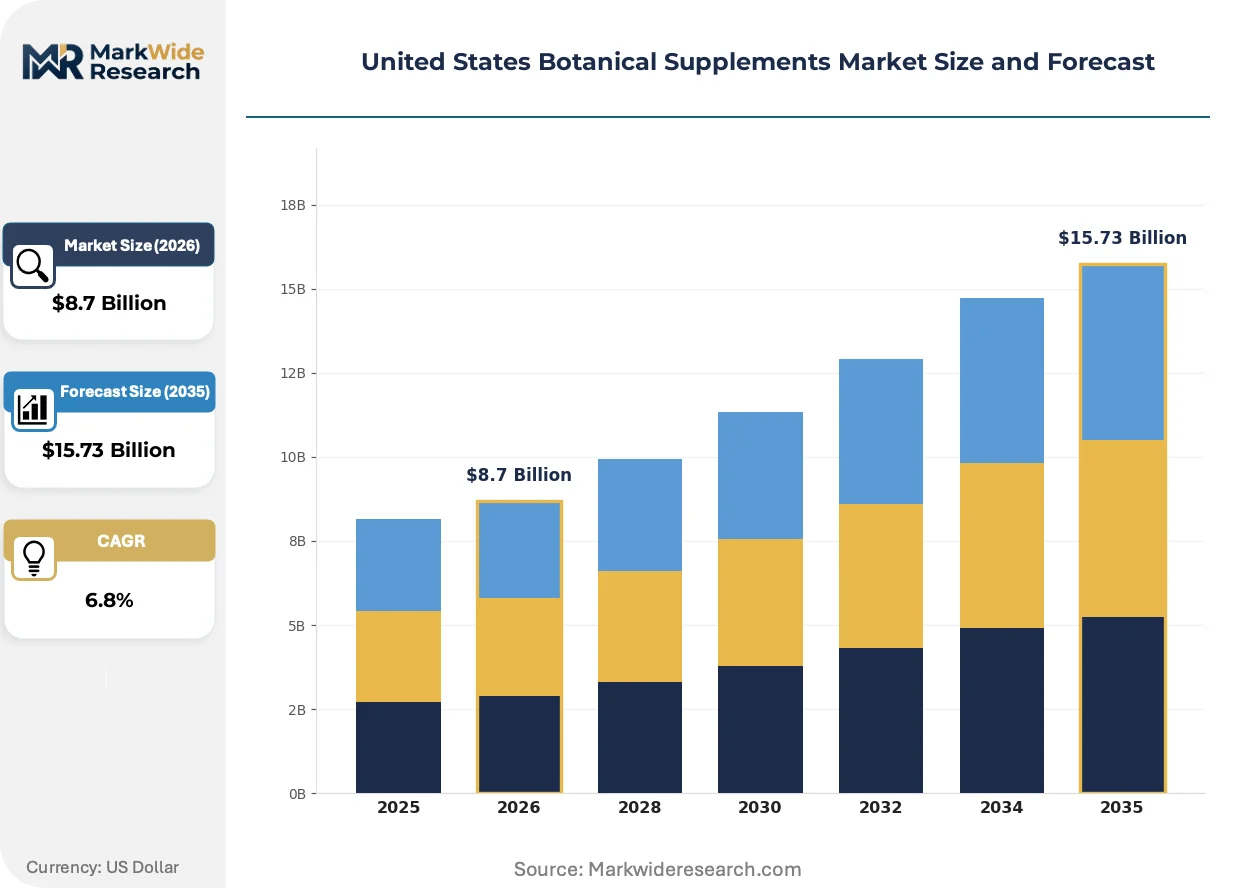
Market Dynamics
DSHEA modernization momentum is hardening quality expectations across the botanical supply chain, forcing manufacturers to reallocate capital from marketing toward documented quality systems and analytical validation infrastructure.
Growth Catalysts
- Wellness center integration:Functional medicine practitioners in California and New York are incorporating standardized botanical protocols into preventive care programs, creating institutional demand pull.
- FTC enforcement clarity:The FTC's active monitoring of structure-function claims is rewarding brands that invest in clinical substantiation, compressing competitive differentiation around evidence quality.
- Telehealth referral networks:Licensed naturopathic physicians operating through virtual platforms are directing patients toward verified botanical formulations with USP certification.
Market Restraints
- Raw material volatility:Climate-sensitive harvests of adaptogenic roots from Pacific Northwest growing regions create input cost instability for domestic formulators.
- cGMP compliance burden:The FDA's intensified facility inspections and analytical testing requirements are elevating fixed costs for small-scale manufacturers without captive laboratories.
- Pharmaceutical substitution:Prescription anxiolytics and sleep aids with established reimbursement pathways compete directly with valerian and passionflower supplements in managed care populations.
Strategic Opportunities
- Subscription direct-to-consumer models:Telehealth-integrated replenishment platforms targeting perimenopausal women in Texas and Florida bypass traditional retail markup structures.
- USDA Organic certification tailwind:The National Organic Program's updated handling standards create preference premiums for certified growers in Vermont and Oregon.
- Practitioner channel digitization:Electronic health record integrations enabling point-of-care botanical recommendations are penetrating functional medicine clinics in Arizona and Colorado.
Industry Challenges
- Analytical chemist scarcity:Validated methods development for complex botanical matrices requires specialized phytochemical expertise concentrated in academic institutions rather than commercial laboratories.
- New dietary ingredient notification timelines:The FDA's pending pre-market framework creates uncertainty around innovation pipeline planning and R&D capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Botanical Supplements Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Teas, Essential Oils, Tinctures, Capsules End User: Retail Consumers, Health Professionals, Pharmacies, Wellness Centers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Form: Liquid, Powder, Pellet, Extract |
| Companies Covered | NOW Foods, GNC Holdings Inc., Nestlé S.A. (Nature's Bounty), Otsuka Pharmaceutical Co., Ltd., Gaia Herbs, Inc., Amway Corporation, Dr. Willmar Schwabe GmbH & Co. KG, Swanson Health Products, Herbalife International of America, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Botanical Supplements Market Evolving Landscape
Technological advancement in extraction and verification systems is compressing the gap between traditional herbal preparation and pharmaceutical-grade standardization, reshaping how quality is demonstrated and priced.
Supercritical CO2 extraction technology is converging with advanced chromatographic fingerprinting to enable solvent-free concentration of heat-sensitive terpenoids. Mid-sized manufacturers in Colorado and Oregon are adopting these systems to serve practitioner channels demanding batch-to-batch consistency. The capital intensity of this dual-technology integration is compressing the supplier base toward operations with in-house analytical capabilities.
The FDA's anticipated pre-market notification framework for new dietary ingredients is forcing reformulation of innovation pipelines around GRAS-affirmed constituents rather than novel botanical actives. Manufacturers are redirecting R&D spend toward clinical validation of existing ingredients rather than exotic sourcing. This regulatory friction most acutely affects companies dependent on international ethnobotanical discoveries from Southeast Asian supply networks.
Telehealth-integrated subscription replenishment is displacing pharmacy and health food store purchasing among chronically managed conditions. Licensed naturopathic physicians in Washington and Connecticut are embedding botanical recommendations into patient portal workflows with automated 90-day resupply triggers. This channel shift concentrates demand fulfillment with vertically integrated brands possessing compounding pharmacy licenses.
United States Botanical Supplements Market Segmentation
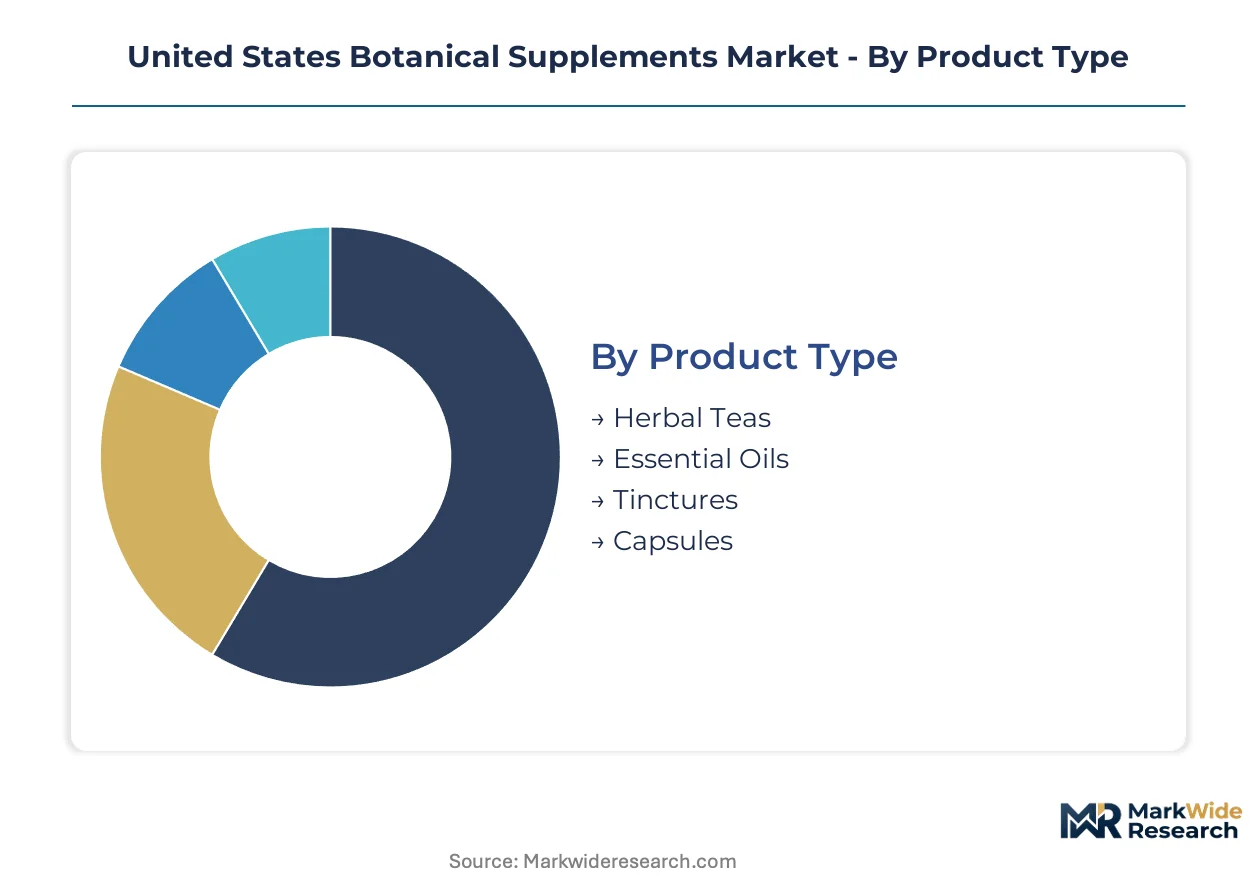
Segmentation in the United States botanical supplements market reveals how formulation choices, professional endorsement, and channel access create distinct competitive arenas. Each dimension carries regulatory and margin implications that reshape capital allocation across the value chain.
Product Type:
Volume concentrates in convenience-oriented formats, while premium positioning attaches to bioavailability-optimized delivery systems.
- Capsules:Gelatin and vegetable-based shells containing standardized powdered extracts enable precise dosing and extended shelf stability. Demand clusters around functional medicine practitioners in California and New York who require documented potency for clinical protocols. The FTC's structure-function claim enforcement elevates brands with USP verification.
- Tinctures:Alcohol or glycerin-based liquid extracts concentrate bioactive compounds for sublingual absorption. Wellness centers in Austin and Denver favor these for rapid onset in stress management applications. Cold-press and percolation methods differentiate quality tiers.
- Herbal Teas:Dried leaf and flower preparations for infusion serve entry-level consumers seeking ritual wellness experiences.
- Essential Oils:Steam-distilled volatile compounds target aromatherapy practitioners and home-use applications with concentrated aromatic profiles.
Mature deployment sits with capsules. Newer deployment is concentrated in tinctures.
End User:
Professional gatekeeping versus direct access defines how clinical evidence and marketing claims must align.
- Wellness Centers:Functional medicine clinics and integrative health facilities incorporate botanical protocols into preventive care programs. Licensed naturopathic physicians in Washington and Connecticut drive institutional procurement through electronic health record integrations. FDA cGMP compliance and batch traceability are non-negotiable entry requirements.
- Health Professionals:Individual practitioners including herbalists and acupuncturists recommend verified formulations with USP or NSF certification. Telehealth platforms in Arizona and Colorado enable virtual consultations with automated replenishment triggers.
- Retail Consumers:Self-directed purchasers through online and physical channels respond to subscription models and influencer validation.
- Pharmacies:Compounding pharmacies and retail chains with natural health sections stock practitioner-grade lines alongside mass-market SKUs.
Institutional adoption concentrates with wellness centers. Individual practitioner digitization is climbing the fastest.
Distribution Channel:
Channel selection determines margin capture, customer data access, and regulatory exposure for structure-function claims.
- Online Retail:Direct-to-consumer platforms and marketplace listings bypass traditional retail markups while enabling subscription replenishment. Telehealth-integrated portals in Texas and Florida target perimenopausal women with automated 90-day resupply cycles. The FTC monitors digital advertising claims with particular scrutiny.
- Specialty Stores:Independent health food retailers and regional chains provide education-intensive environments for complex botanical formulations.
- Supermarkets:Mass-market placement requires price competitiveness and simplified messaging for self-service shoppers.
- Direct Sales:Multi-level marketing and practitioner-exclusive lines maintain margin through relationship-based distribution.
Traditional strength rests with specialty stores. Digital expansion is gaining share fastest.
Form:
Physical state determines extraction method compatibility, stability requirements, and end-use flexibility.
- Extract:Concentrated preparations standardized for specific marker compounds enable precise therapeutic dosing. Supercritical CO2 and solvent extraction facilities in Colorado and Oregon serve practitioner channels demanding batch-to-batch consistency. Chromatographic fingerprinting validates chemical profiles.
- Liquid:Aqueous and hydro-alcoholic solutions accommodate flexible dosing and rapid absorption requirements.
- Powder:Dried and milled botanical material supports bulk compounding and encapsulation operations.
- Pellet:Compressed granules offer intermediate convenience between powders and finished capsules.
Standardized manufacturing dominates extracts. Pellet formulations show emerging adoption in compounding pharmacy workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles and San Francisco anchor United States botanical supplement demand through dense clusters of functional medicine practitioners and direct-to-consumer brands. Wellness center procurement concentrates in these coastal metros, while regulatory enforcement from FDA and FTC shapes manufacturer compliance investments across state lines.
California
Functional medicine clinics in Los Angeles and San Francisco drive institutional demand for standardized botanical protocols. The California Department of Public Health enforces Proposition 65 labeling requirements for herbal products sold within state boundaries. Santa Cruz and Humboldt County organic farms supply certified raw material to vertically integrated manufacturers seeking USDA Organic premiums.
New York
Integrative health facilities in Manhattan and Brooklyn incorporate plant-based preparations into preventive care programs. The New York State Department of Health oversees dietary supplement distribution through licensed healthcare practitioners. Buffalo-area analytical laboratories serve East Coast manufacturers requiring chromatographic fingerprinting for batch verification.
Texas
Telehealth-integrated subscription platforms target perimenopausal women in Houston and Dallas with automated replenishment models. The Texas Department of State Health Services regulates compounding pharmacies that formulate custom botanical preparations. Austin wellness centers favor alcohol-based tinctures for rapid bioavailability in stress management applications.
Colorado
Supercritical CO2 extraction facilities in Denver and Boulder serve practitioner channels demanding solvent-free terpenoid concentration. The Colorado Department of Public Health and Environment monitors cannabis-adjacent botanical processing under state hemp regulations. Fort Collins analytical chemists develop validated methods for complex adaptogenic root matrices.
Oregon
Organic herb cultivation in the Willamette Valley supplies domestic formulators seeking climate-resilient raw material alternatives. The Oregon Department of Agriculture administers National Organic Program certification for handling operations. Portland manufacturers integrate chromatographic fingerprinting with extraction systems to guarantee batch-to-batch consistency for West Coast distribution.
United States Botanical Supplements Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and traceability dimensions, with USP verification and organic farm partnerships commanding pricing power. The vendor base spans vertically integrated herb growers, retail network operators, and telehealth-integrated direct-to-consumer platforms. Three archetypes dominate: seed-to-shelf traceability specialists, multi-channel retail consolidators, and subscription-based wellness platforms. Capacity expansion in analytical validation infrastructure and strategic partnerships with licensed naturopathic physicians represent the dominant competitive moves reshaping market position.
Within the traceability-focused tier, Gaia Herbs and NOW Foods exemplify divergent approaches to supply chain control, with the former emphasizing organic farm partnerships and the latter anchoring position through captive raw material sourcing and finished production. GNC Holdings occupies a position as a multi-channel retail consolidator with extensive storefront networks and practitioner channel relationships. Among internationally headquartered parents, Nestlé S.A. and Otsuka Pharmaceutical Co., Ltd. represent diversified nutrition and pharmaceutical conglomerates that have acquired positions in the botanical supplement space through subsidiary structures.
| Leading Market Players |
|---|
| NOW Foods |
| GNC Holdings Inc. |
| Nestlé S.A. (Nature's Bounty) |
| Otsuka Pharmaceutical Co., Ltd. |
| Gaia Herbs, Inc. |
| Amway Corporation |
| Dr. Willmar Schwabe GmbH & Co. KG |
| Swanson Health Products |
| Herbalife International of America, Inc. |
| Others |
Value Network & Pricing Analysis
USP verification and organic certification tiers split the botanical supplements market into divergent pricing power zones, with certified manufacturers commanding 40-60% premiums over commodity-grade competitors while raw material sourcing constraints force smaller players toward contract manufacturing arrangements that compress margins.
Pricing Analysis
Value-based pricing anchored to clinical substantiation quality separates premium botanical brands from mass-market alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with USP-verified and USDA Organic products capturing institutional procurement contracts from wellness centers while uncertified SKUs compete on shelf price in supermarket channels. Pricing pressure stems from FDA cGMP compliance investments that elevate fixed costs for small manufacturers. Retail consumers exhibit highest price sensitivity, whereas functional medicine practitioners prioritize batch consistency over unit cost.
Supply Chain Analysis
Phytochemical analyst scarcity in Colorado and Oregon extraction hubs constrains capacity expansion for supercritical CO2 facilities serving practitioner channels. Domestic supply draws from California organic farms, Pacific Northwest adaptogenic root cultivation, and imported raw materials from Indian and Chinese herb processing centers. Single-source vulnerability concentrates in climate-sensitive harvests of ashwagandha and rhodiola from high-altitude growing regions. Distribution runs through telehealth-integrated subscription platforms, specialty retail networks, and direct practitioner sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States botanical supplements market operates as a vertical-integration race where control over analytical validation infrastructure and licensed practitioner relationships determines margin capture and channel access.
For Market Incumbents: Lock in practitioner channel loyalty through electronic health record integrations that embed botanical recommendations into clinical workflows. Deepen captive supply of certified organic raw material from Santa Cruz and Humboldt County farms to insulate against climate-driven harvest volatility. Defensive priority centers on analytical chemist recruitment from Fort Collins and Boulder academic programs before competitors exhaust this specialized talent pool. For New Entrants and Emerging Players: Telehealth platforms represent the most penetrable channel partner type for bypassing established retail markups and accessing perimenopausal women in Texas and Florida through automated replenishment models. White-space targets include USDA Organic certified pellet formulations for compounding pharmacy workflows and solvent-free terpenoid concentrates for Colorado wellness centers. Go-to-market execution should prioritize naturopathic physician licensing partnerships in Washington and Connecticut. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified nutrition conglomerates seeking practitioner-channel access and telehealth integration capabilities. Long-term viability over the next decade hinges on regulatory navigation of FDA's pending pre-market notification framework for new dietary ingredients. Acquisition target archetype: mid-sized manufacturers with in-house chromatographic fingerprinting and existing USP verification. Signal to watch: DSHEA modernization legislation advancing through Congressional committees.| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Investment | FDA cGMP enforcement rewards documented quality systems with institutional procurement access from California wellness centers. |
| Organic Farm Partnership | USDA Organic certification premiums create preference separation from commodity-grade competitors in Vermont and Oregon markets. |
| Telehealth Platform Integration | Licensed naturopathic physician portals in Washington enable automated 90-day replenishment cycles for chronic condition management. |
| Supercritical CO2 Capacity Expansion | Solvent-free extraction systems in Colorado serve practitioner channels demanding batch-to-batch terpenoid consistency. |
| Analytical Chemist Recruitment | Validated methods development expertise from academic institutions addresses critical phytochemical testing bottlenecks. |
Research Methodology
Independent corroboration across FDA warning letter databases, USDA Organic certification records, and FTC enforcement actions underwrites the qualitative findings on regulatory pressure direction. Primary interviews with functional medicine practitioners, licensed naturopathic physicians, dietary supplement formulators, and analytical laboratory directors combined with secondary validation from USP verification databases, cGMP inspection records, and National Organic Program handling operation registries. Bottom-up demand modeling from wellness center procurement patterns triangulates against top-down market sizing from channel shipment data.
Comparable-period anchoring to historical FDA enforcement intensity and DSHEA legislative activity frames the projection horizon. Segmentation modeling spans product format, end-user archetype, distribution channel, and certification tier dimensions. CAGRs derive from regression analysis against wellness center expansion rates, telehealth platform penetration, and organic certification adoption curves. Industry-specific inputs include climate volatility indices for Pacific Northwest growing regions and FTC structure-function claim enforcement frequency.
Caveats apply where FDA pre-market notification rulemaking, DSHEA modernization passage, or climate-driven raw material shortages could materially shift the outlook. Forecasts reflect assumptions around regulatory timeline stability and practitioner channel digitization velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Omega 3 Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
Garcinia Cambogia Extract Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market