
 Calcium Malate Market | 2026-2036
Calcium Malate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Malate Market Analysis
Technical-grade formulation services is consolidating around value-added mineral premix offerings that bundle chelation expertise with regulatory documentation. Jost Chemical Co. leverages its US-based FDA-registered manufacturing to dominate pharmaceutical-grade supply chains. Jungbunzlauer Suisse AG anchors European demand through its Swiss fermentation-derived organic acid platform. Dr. Paul Lohmann GmbH KG specializes in ultra-pure mineral salts for infant nutrition and clinical applications.
Calcium malate is a calcium salt of malic acid with a 23% elemental calcium content by weight, typically produced through controlled neutralization of malic acid with calcium carbonate or hydroxide for superior intestinal absorption compared to inorganic calcium sources. The compound serves primarily as a bioavailable mineral fortifier in dietary supplements, functional foods, and pharmaceutical dosage forms where gastric tolerability determines consumer compliance. Powder formulations occupy the largest volume share due to bulk ingredient flexibility across contract manufacturing, while chewable tablets command premium positioning among elderly end users seeking palatability-driven compliance. Pharmaceutical applications sustain the strictest purity and documentation requirements, creating margin pools that favor suppliers with drug master file capabilities.
The FDA's New Dietary Ingredient notification pathway and USP monograph standards govern market access for calcium malate in US dietary supplements, while EFSA health claim authorization under EU Regulation 1924/2006 shapes permissible marketing in European nutraceuticals. India's FSSAI fortification guidelines and CDSCO drug approval processes are expanding the addressable market for pharmaceutical-grade calcium malate in generic formulations. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards to anticipate qualification burdens that will determine supplier switching costs.
Market Dynamics
The calcium malate market pivots on tightening pharmacopeial harmonization between USP, EP, and JP standards, which is elevating documentation burdens and consolidating supplier qualification around drug master file capabilities.
Growth Catalysts
- EFSA health claim authorization:EU Regulation 1924/2006 enables substantiated marketing of bioavailability claims, expanding permissible positioning for chelated mineral formulations in European nutraceuticals.
- Infant nutrition fortification:Ultra-pure mineral salt demand from specialized clinical applications is pulling pharmaceutical-grade calcium malate into high-margin pediatric and geriatric dosage forms.
- Fermentation-derived organic acid platforms:Swiss and German production clusters are scaling malic acid supply through biotechnology routes, securing feedstock for premium chelate manufacturing.
Market Restraints
- Malic acid feedstock volatility:Petrochemical and bio-based route competition for organic acid precursors creates input cost instability for chelation chemistry.
- Supplier concentration in Alpine corridor:Jungbunzlauer Suisse AG and Dr. Paul Lohmann GmbH KG anchor European malate supply, creating geographic single-point vulnerability.
- Carbonate and citrate substitution:Lower-cost inorganic and organic calcium salts compete on price in mass-market dietary supplements where bioavailability differentiation is undervalued.
Strategic Opportunities
- FSSAI fortification mandates:India's food safety regulator is expanding micronutrient requirements for staple foods, opening pharmaceutical-grade demand for generic tablet formulations.
- CDSCO abbreviated approval pathways:India's drug controller is streamlining generic mineral salt qualifications, reducing timeline friction for export-oriented manufacturers.
- Direct-to-practitioner distribution:Functional medicine clinicians are bypassing retail channels for compounded chelate therapies, creating high-margin bypass routes.
Industry Challenges
- Analytical chemistry skill scarcity:ICP-MS and chelation assay expertise required for USP monograph compliance is concentrating in contract laboratories, elongating in-house qualification timelines.
- Multi-pharmacopeial dossier maintenance:Simultaneous USP, EP, and JP certification updates demand dedicated regulatory affairs bandwidth that mid-scale suppliers struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Malate Market |
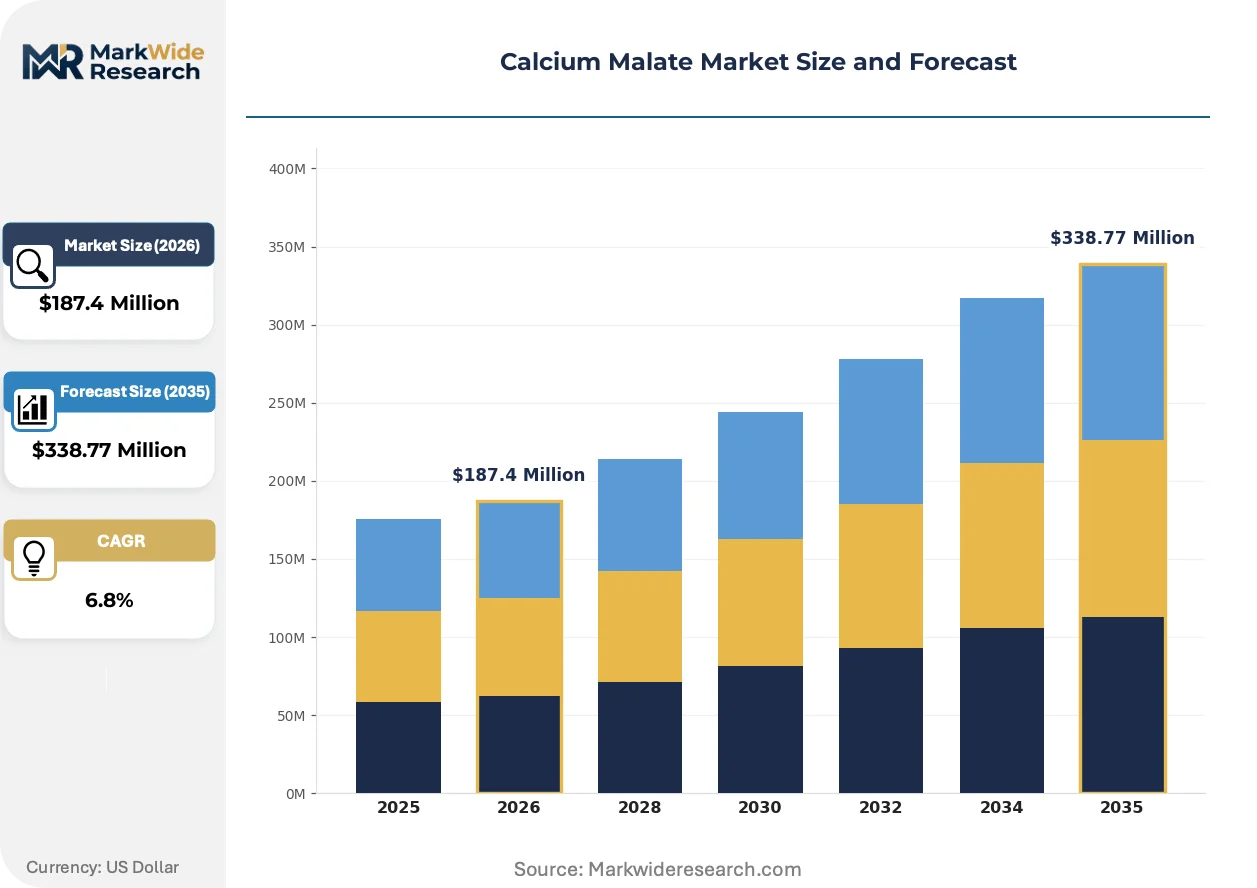
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Malate Powder, Calcium Malate Capsules, Calcium Malate Tablets, Calcium Malate Chewables Application: Dietary Supplements, Food Additives, Pharmaceutical Products, Nutraceuticals End User: Health-conscious Consumers, Athletes, Elderly Individuals, Pregnant Women Distribution Channel: Online Retail, Health Food Stores, Pharmacies, Supermarkets |
| Companies Covered | Jost Chemical Co., Jungbunzlauer Suisse AG, Dr. Paul Lohmann GmbH KG, Gadot Biochemical Industries Ltd., Glanbia Nutritionals, Panvo Organics Pvt Ltd, Akesiss, Klaire Labs, Albion Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Malate Market Emerging Trajectories
Controlled-release formulation engineering and precision fermentation are reshaping how calcium malate achieves differentiation in a market where elemental content alone no longer commands premium positioning.
Microencapsulation technology using lipid and polymer matrices is absorbing gastric pH variability concerns that have historically limited calcium malate adoption in enteric-sensitive populations. Pediatric and geriatric supplement formulators are accelerating uptake of taste-masked, sustained-release granules. This absorption of tolerability engineering into core product architecture is compressing the addressable market for uncoated powder grades.
REACH authorization requirements for malic acid derivatives are forcing European manufacturers to consolidate substance volume tracking and exposure scenario documentation. The industrial consequence is a bifurcation between integrated producers with in-house toxicology dossiers and toll manufacturers dependent on upstream data sharing. Pharmaceutical-grade suppliers with pre-registered intermediates are capturing share from commodity mineral salt traders.
Practitioner-channel preference for third-party tested, certificate-of-analysis-transparent sourcing is displacing traditional bulk ingredient procurement through distributors. Compounding pharmacies and integrative medicine clinics are establishing direct qualification relationships with GMP-certified manufacturers. This channel compression is most visible in Germany and Switzerland, where pharmacy-level mineral therapy customization is reimbursable under complementary medicine frameworks.
Calcium Malate Market Segmentation
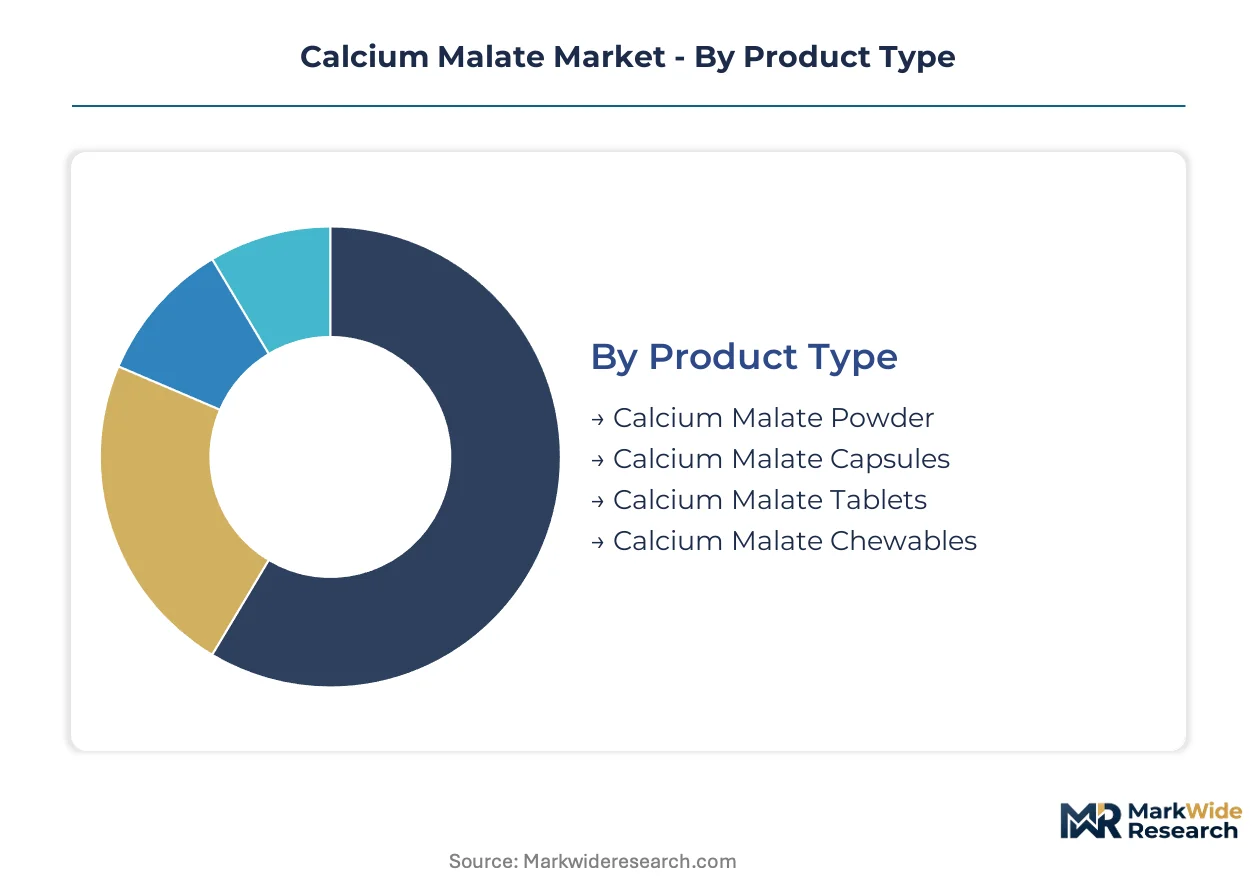
Calcium malate's bioavailability positioning creates distinct formulation requirements across dosage forms, while regulatory pathways fragment demand between pharmaceutical-grade documentation and commodity supplement supply. Understanding segment-specific qualification burdens and channel economics determines supplier margin capture in this chelated mineral market.
Product Type:
Customization intensity varies sharply across this category, from bulk powder commodity supply to finished dosage forms requiring taste-masking and controlled-release engineering.
- Calcium Malate Powder:Unformulated bulk ingredient serving contract manufacturers and compound pharmacies with flexibility for custom blending. Demand concentrates in Germany's nutraceutical cluster where Albion Laboratories and Dr. Paul Lohmann integrate powder supply into premix services, driven by pharmaceutical-grade documentation requirements for infant nutrition applications.
- Calcium Malate Tablets:Compressed dosage forms with standardization around USP dissolution specifications and film-coating options for gastric tolerability. Volume leadership reflects pharmacy-channel preference for shelf-stable, precision-dosed mineral supplementation in reimbursable healthcare frameworks.
- Calcium Malate Capsules:Encapsulated powder or granule formulations targeting practitioner-direct distribution channels with vegetarian shell options. Expanding most quickly among functional medicine clinicians seeking compounded chelate therapies.
- Calcium Malate Chewables:Palatability-engineered formats with flavor masking and binder systems for elderly compliance. Growing fastest: chewables. Leading by volume: powder.
Leading the category by volume: Calcium Malate Powder. Growing fastest: Calcium Malate Chewables.
Application:
Margin architecture separates this category into documentation-intensive pharmaceutical qualifications versus marketing-driven nutraceutical positioning.
- Dietary Supplements:Bioavailability-claim positioning under FDA NDI notification or EFSA health claim authorization, with formulation flexibility for multi-mineral stacking. Demand concentrates in US direct-to-consumer channels where elemental calcium content competes against carbonate and citrate alternatives on price-per-dose metrics.
- Pharmaceutical Products:Drug master file-governed supply for generic mineral salt formulations with USP, EP, and JP monograph compliance. CDSCO abbreviated approval pathways in India are expanding addressable demand for export-oriented manufacturers with multi-pharmacopeial dossiers.
- Food Additives:Fortification applications in functional foods and beverages requiring FSSAI compliance in India and GRAS self-affirmation in the United States.
- Nutraceuticals:Positioning between food and drug categories with health claim substantiation under EU Regulation 1924/2006.
Highest margin capture: Pharmaceutical Products. Steepest expansion trajectory: Dietary Supplements.
End User:
Physiological absorption efficiency and tolerability concerns stratify demand across life-stage and activity-level segments.
- Elderly Individuals:Gastric acid decline drives preference for chelated mineral forms with demonstrated bioavailability independent of stomach pH, supporting premium positioning for malate over carbonate.
- Pregnant Women:Obstetrician-recommended prenatal formulations with elemental calcium dosing precision and heavy metal testing documentation.
- Health-conscious Consumers:General wellness positioning with price sensitivity to elemental calcium cost-per-milligram comparisons.
- Athletes:Sports nutrition integration with electrolyte balance and bone density maintenance claims in endurance training contexts.
Largest addressable base: Health-conscious Consumers. Gaining share fastest: Elderly Individuals.
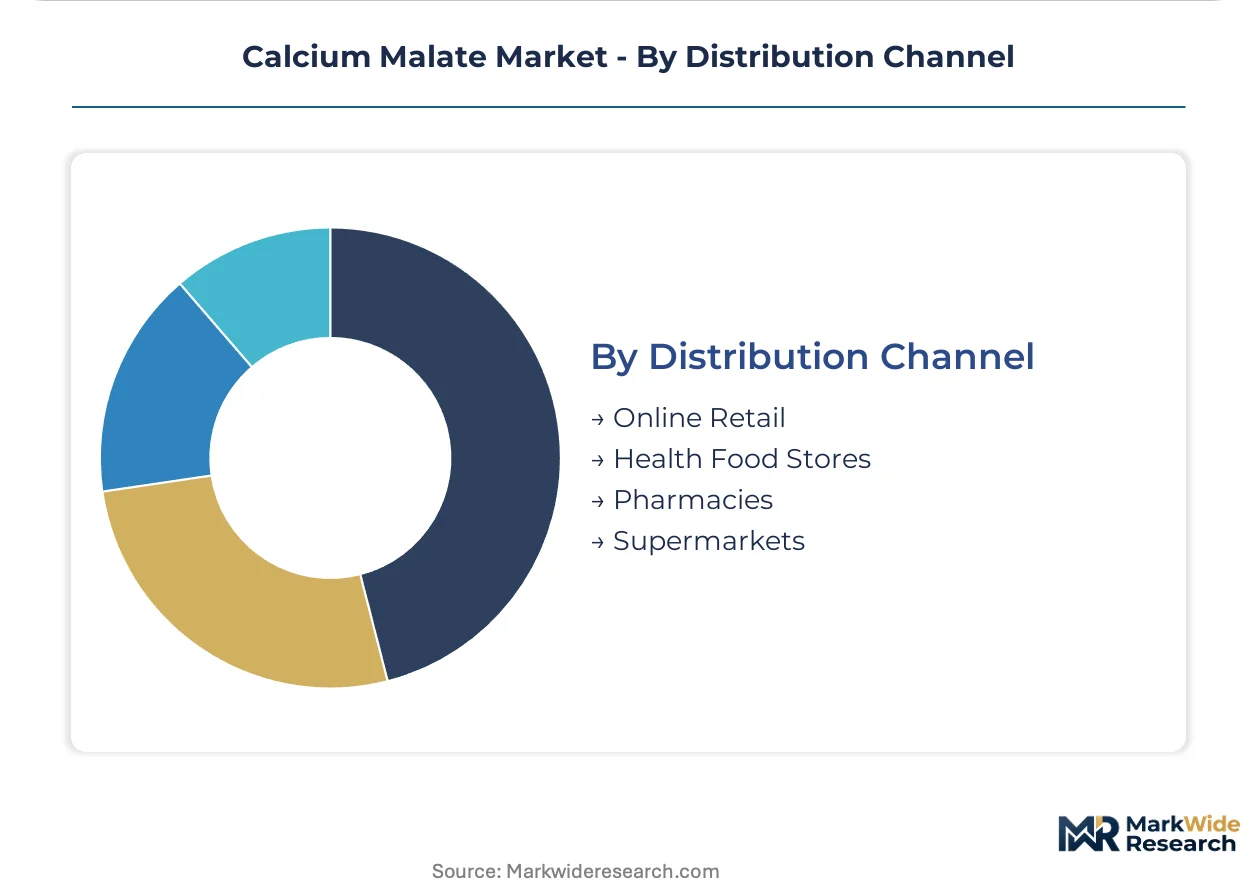
Distribution Channel:
Channel economics reflect documentation transparency requirements and the compression of traditional distributor margins by direct manufacturer relationships.
- Pharmacies:Reimbursable mineral therapy frameworks in Germany and Switzerland support pharmacy-level customization with certificate-of-analysis transparency requirements.
- Online Retail:Direct-to-consumer growth with third-party testing verification and subscription model economics for compliance-driven replenishment.
- Health Food Stores:Staff-assisted selection environment favoring branded bioavailability claims and multi-mineral combination products.
- Supermarkets:Mass-market penetration with price-competitive positioning against carbonate and citrate alternatives in mainstream supplement aisles.
Dominant volume channel: Pharmacies. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Albion Laboratories and Dr. Paul Lohmann maintain specialized production facilities in Germany's nutraceutical cluster, anchoring European calcium malate supply chains with pharmaceutical-grade documentation capabilities.
United States
Dietary supplement manufacturers drive demand through FDA New Dietary Ingredient notification pathways for enhanced bioavailability formulations. USP monograph standards govern market access with strict dissolution specifications. Jost Chemical Co. leverages FDA-registered manufacturing in St. Louis to dominate pharmaceutical-grade supply chains serving generic tablet producers.
Germany
Pharmacy-level mineral therapy customization operates under reimbursable complementary medicine frameworks. EFSA health claim authorization under EU Regulation 1924/2006 enables substantiated bioavailability marketing. The Krefeld-Leverkusen industrial corridor concentrates ultra-pure mineral salt production for infant nutrition applications.
Switzerland
Fermentation-derived organic acid platforms secure malic acid feedstock through biotechnology routes. Swissmedic pharmaceutical regulations enforce multi-pharmacopeial dossier requirements for mineral salt approvals. Jungbunzlauer Suisse AG anchors Basel-region production with integrated fermentation-to-chelate manufacturing.
India
FSSAI fortification mandates expand micronutrient requirements for staple foods into pharmaceutical-grade demand. CDSCO abbreviated approval pathways streamline generic mineral salt qualifications for export-oriented manufacturers. Mumbai-Pune pharmaceutical belt concentrates contract manufacturing for tablet and capsule formulations targeting regulated markets.
Calcium Malate Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the calcium malate value chain, creating a tiered structure where integrated manufacturers with captive malic acid supply face formulation specialists purchasing feedstock on contract. The market consolidates around three strategic archetypes: fermentation-integrated organic acid producers, pharmaceutical-grade mineral salt specialists with drug master file capabilities, and contract manufacturers serving branded supplement houses. Dominant competitive moves include backward integration into malic acid fermentation and geographic expansion through multi-pharmacopeial dossier filing.
Within the pharmaceutical-grade tier, Jost Chemical Co. and Dr. Paul Lohmann GmbH KG exemplify the documentation-intensive positioning required for infant nutrition and clinical applications, while Jungbunzlauer Suisse AG represents the fermentation-integrated model securing feedstock cost advantages through biotechnology platforms.
| Leading Market Players |
|---|
| Jost Chemical Co. |
| Jungbunzlauer Suisse AG |
| Dr. Paul Lohmann GmbH KG |
| Gadot Biochemical Industries Ltd. |
| Glanbia Nutritionals |
| Panvo Organics Pvt Ltd |
| Akesiss |
| Klaire Labs |
| Albion Laboratories, Inc. |
| Others |
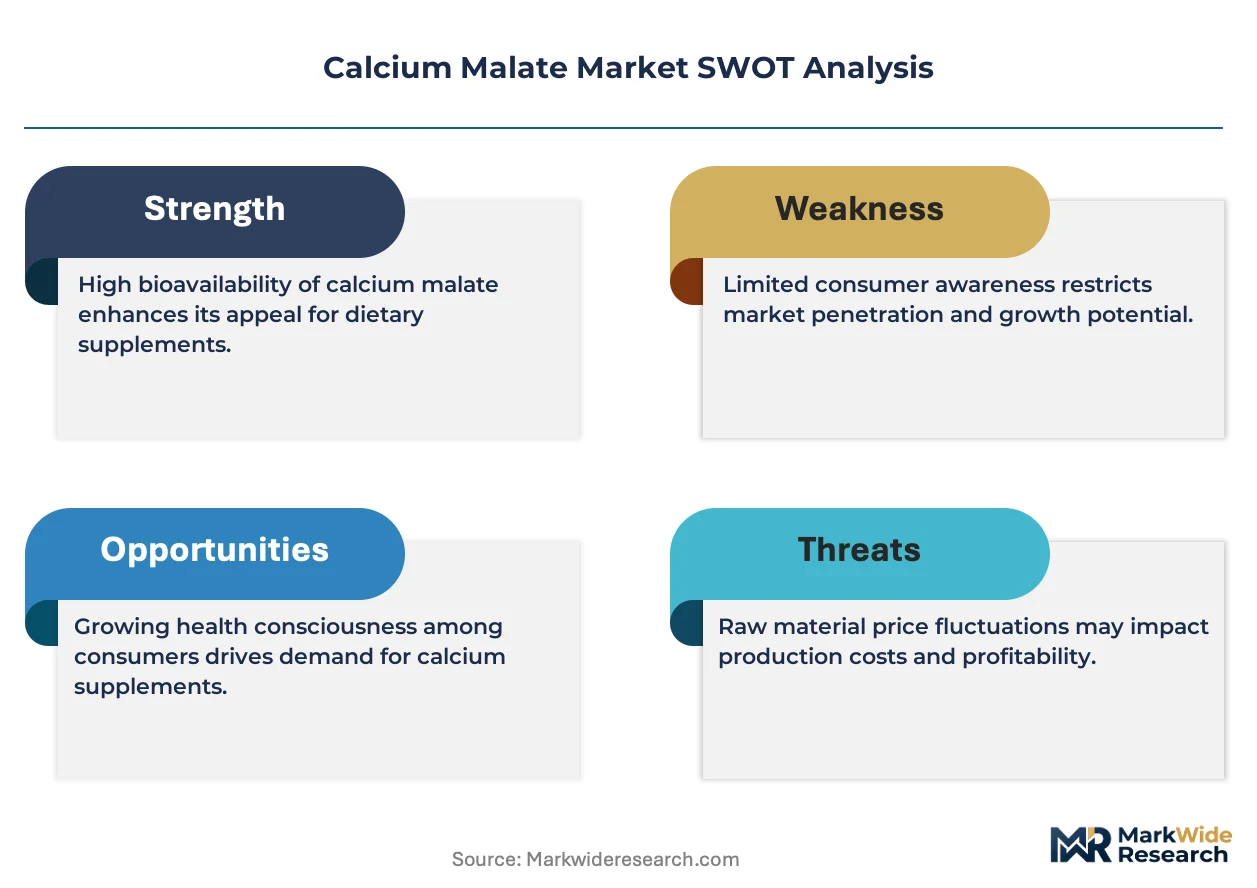
Supply Flow & Price Mechanics
Fermentation-derived malic acid production is displacing petrochemical routes across Swiss and German manufacturing clusters, compressing feedstock costs for integrated chelate producers while stranding toll manufacturers dependent on spot organic acid markets. This biotechnology transition concentrates margin capture among producers with captive fermentation capacity, forcing price discipline on powder-grade suppliers without upstream integration.
Pricing Analysis
USP monograph compliance and drug master file documentation anchor value-based pricing premiums for pharmaceutical-grade calcium malate, separating infant nutrition-qualified supply from commodity dietary supplement grades. Price differentiation hinges on heavy metal testing thresholds and multi-pharmacopeial dossier completeness, with Jost Chemical Co. and Dr. Paul Lohmann commanding structural premiums over unregistered traders. Cost compression in standard powder grades intensifies as carbonate and citrate substitutes capture mass-market volume, leaving elderly-directed chewable formats as the least price-sensitive segment due to palatability-driven compliance requirements.
Supply Chain Analysis
Freight cost exposure from Alpine corridor concentration elevates landed costs for North American and Asian buyers sourcing from Jungbunzlauer Suisse AG and Dr. Paul Lohmann facilities in Switzerland and Germany. Raw material supply draws from fermentation-derived malic acid platforms, calcium carbonate or hydroxide precursors, and chelation catalyst systems, with feedstock volatility tethered to bio-based versus petrochemical organic acid route competition. Single-source vulnerability concentrates in Basel-region fermentation capacity, while distribution runs through direct manufacturer relationships with compounding pharmacies and GMP-certified contract manufacturers displacing traditional bulk distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcium malate market functions as a vertical-integration race where fermentation-to-chelate manufacturing control and multi-pharmacopeial dossier filing speed determine competitive survival. Players are pursuing backward integration into malic acid supply as the decisive upstream lever.
For Market Incumbents: Deploy drug master file expansion to capture CDSCO abbreviated approval pathways in India before generic mineral salt qualification timelines compress. Consolidate position by acquiring toll manufacturers lacking REACH pre-registration for malic acid derivatives, neutralizing the threat of regulatory documentation bottlenecks that favor integrated producers with in-house toxicology dossiers. For New Entrants and Emerging Players: The mid-tier pricing gap between pharmaceutical-grade documentation-heavy supply and unregistered commodity powder creates entry space for FSSAI-compliant manufacturers targeting India's fortified staple food programs. Penetrate the food additive segment through direct qualification with Mumbai-Pune pharmaceutical belt contract manufacturers, using certificate-of-analysis transparency as the primary go-to-market angle against opaque bulk traders. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by fermentation-integrated organic acid producers seeking downstream chelation capabilities. Long-term viability favors targets with pre-registered REACH intermediates and existing USP monograph compliance, as pharmacopeial harmonization burdens accelerate supplier consolidation. Watch for EFSA health claim authorization expansion as the inflection signal for European nutraceutical premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Malic Acid Fermentation | Jungbunzlauer Suisse AG's Basel-platform model secures feedstock cost advantages against petrochemical route volatility. |
| Multi-Pharmacopeial Dossier Filing | Simultaneous USP, EP, and JP qualification reduces switching costs for generic tablet producers in regulated markets. |
| Direct-to-Practitioner Distribution Buildout | Compounding pharmacy relationships in Germany's reimbursable complementary medicine frameworks capture premium positioning. |
| Microencapsulation Technology Investment | Lipid and polymer matrix engineering addresses gastric pH variability concerns limiting adoption in elderly populations. |
| FSSAI Fortification Compliance Certification | India's food safety regulator mandates create pharmaceutical-grade demand for staple food fortification applications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with dietary supplement formulators, pharmaceutical procurement managers, GMP-certified manufacturing directors, and regulatory affairs specialists. FDA New Dietary Ingredient notifications, EFSA health claim submissions, CDSCO abbreviated approval records, and FSSAI fortification compliance databases provided structured validation. Bottom-up volume modeling across powder, tablet, capsule, and chewable dosage forms triangulated against top-down mineral salt consumption estimates from national pharmacopeial authorities.
Data-stream reconciliation between contract manufacturing intake records, malic acid fermentation capacity disclosures, and finished goods trade flows enabled segmentation-level calibration. The analytical framework modeled demand across dietary supplements, pharmaceutical products, food additives, and nutraceuticals, with end-user stratification by elderly, pregnant, health-conscious, and athlete segments. CAGRs were derived from fitted growth curves incorporating pharmacopeial harmonization timelines, FSSAI mandate implementation schedules, and practitioner-channel penetration rates for compounded chelate therapies.
Underlying measurement precision varies by segment; pharmaceutical-grade documentation-intensive supply carries tighter precision than commodity powder grades where unregistered trader activity obscures volume visibility. Forecasts reflect assumptions about EFSA health claim authorization velocity, CDSCO pathway streamlining, and REACH substance volume tracking compliance costs. Stakeholders should weight assumptions against their own operating context and regulatory filing bandwidth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Inflammation Supplements Market
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Vegetable Capsules Market
Nutritional Supplements
North America Whey Protein Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Spirulina Extract Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Global Protein Market