
 DDR RAM Market | 2026-2036
DDR RAM Market Size, Share, and Industry Trends Forecast 2026-2036
DDR RAM Market Insights
EU F-Gas Regulation and emerging carbon border adjustments are shifting procurement criteria toward lower-voltage memory architectures across European server deployments. Samsung Electronics leverages vertical integration from wafer fabrication to module assembly, sustaining cost advantages in high-density DIMM production. SK Hynix anchors supply for hyperscale cloud providers through advanced process node leadership in DDR5 yield ramp. Micron Technology competes on technology specialization in automotive-grade LPDDR4 for edge computing and autonomous systems.
DDR RAM comprises dynamic random-access memory modules that store each data bit in separate capacitors within integrated circuits, operating through periodic refresh cycles at standardized voltages ranging from 1.1V for DDR5 to 1.5V for DDR3. These modules serve as primary working memory in computing systems where bandwidth and latency determine system responsiveness. DDR5 DIMM variants command expanding share in enterprise server refresh cycles due to doubled burst length and on-die error correction features that reduce system-level power overhead. SO-DIMM form factors dominate notebook and embedded applications where space constraints intersect with thermal limitations, while RDIMM architectures retain structural importance in financial services and telecommunications infrastructure requiring registered signal integrity.
FCC equipment authorization requirements in the United States intersect with REACH substance restrictions in Europe to shape module substrate materials and flame-retardant specifications across export-bound production. China's GB standards and MIIT energy efficiency certifications create parallel compliance pathways for memory modules entering data center procurement channels. JEDEC solid-state technology association specifications govern interoperability thresholds that determine supplier qualification timelines for major OEM integrations. Stakeholders must monitor evolving JEDEC DDR6 roadmap disclosures and foundry capex allocations to calibrate capacity commitments against technology transition risks.
Market Dynamics
The DDR RAM market pivots on JEDEC specification transitions that compress supplier qualification timelines while hyperscale cloud operators consolidate procurement around fewer qualified vendors capable of DDR5 volume ramp.
Growth Catalysts
- MIIT dual carbon mandates:China's energy efficiency certifications accelerate data center transitions from DDR4 to DDR5 architectures, pulling module demand toward lower-voltage platforms.
- AI training workload expansion:Hyperscale cloud operators deploy high-density DIMM configurations to support large language model training clusters, expanding memory-per-server ratios.
- On-die error correction (ODECC):DDR5's integrated signal integrity features reduce system-level power overhead, creating pull from enterprise server refresh cycles seeking operational cost reduction.
Market Restraints
- Advanced process node concentration:Sub-1alpha DRAM fabrication capacity concentrates in South Korea's manufacturing corridor, creating geographic supply vulnerability.
- Substrate material cost volatility:Ajinomoto Build-up Film (ABF) and high-layer-count PCB laminates face pricing pressure from competing advanced packaging demand.
- JEDEC interoperability thresholds:Stringent signal integrity specifications extend OEM qualification timelines, delaying volume procurement commitments.
Strategic Opportunities
- Automotive edge computing:LPDDR4X and LPDDR5 modules for autonomous driving systems remain underpenetrated relative to server applications, offering white space for specialized suppliers.
- EU F-Gas Regulation alignment:European carbon border adjustments create preference for lower-voltage memory architectures in server deployments, favoring DDR5 module suppliers.
- SO-DIMM thermal optimization:Notebook and embedded applications require advanced heat spreader integration, opening channel innovation for thermal management specialists.
Industry Challenges
- Signal integrity engineering talent scarcity:DDR5's doubled data rates demand specialized high-speed digital design expertise that outpaces university pipeline output.
- Legacy DDR3 infrastructure integration:Industrial and telecommunications segments maintain extended lifecycle commitments, forcing module suppliers to sustain multi-generation test equipment and firmware stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DDR RAM Market |
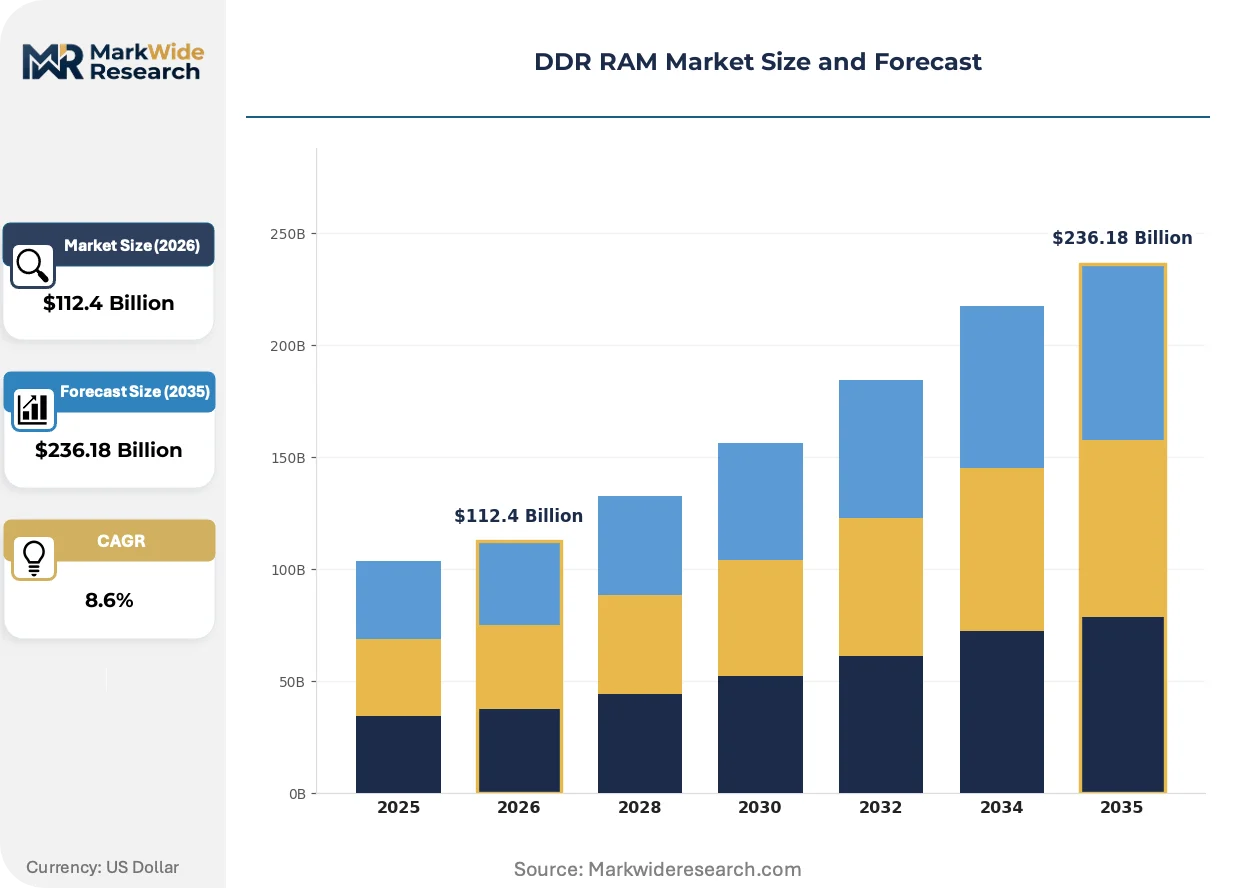
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $236.18 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDR3, DDR4, DDR5, LPDDR4 End User: Consumer Electronics, Servers, Workstations, Gaming Systems Form Factor: DIMM, SO-DIMM, RDIMM, LRDIMM Technology: DRAM, SDRAM, SRAM, Others |
| Companies Covered | Intel Corporation, Transcend Information, SK Hynix, Apacer, Innodisk, Samsung Electronics, Kingston Technology, GigaDevice, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DDR RAM Market Trends and Innovations
Memory architecture evolution is compressing supplier margins while regulatory pressure on embodied carbon reshapes procurement criteria across enterprise and cloud segments.
On-die power management integrated circuits (PMICs) in DDR5 DIMMs are automating voltage rail optimization at the module level. Hyperscale operators deploying these modules report reduced board-level power distribution complexity. This integration is automating thermal management decisions previously executed at the system BIOS level, compressing time-to-stable-operation in dense server configurations.
REACH substance restrictions intersect with FCC equipment authorization requirements to mandate halogen-free substrate materials and revised flame-retardant chemistries. Module suppliers serving European data center operators now face dual compliance pathways. Server OEMs with European manufacturing footprints are qualifying alternative laminates ahead of stricter ECHA substance candidate list expansions.
Certification-driven procurement now dominates enterprise server channel decisions, displacing pure price-per-gigabyte evaluation. IT asset managers at financial services institutions prioritize JEDEC-qualified supplier lists over spot-market module sourcing. This behavioral shift is most visible in Frankfurt and London financial infrastructure deployments where operational risk frameworks override cost optimization.
DDR RAM Market Segmentation
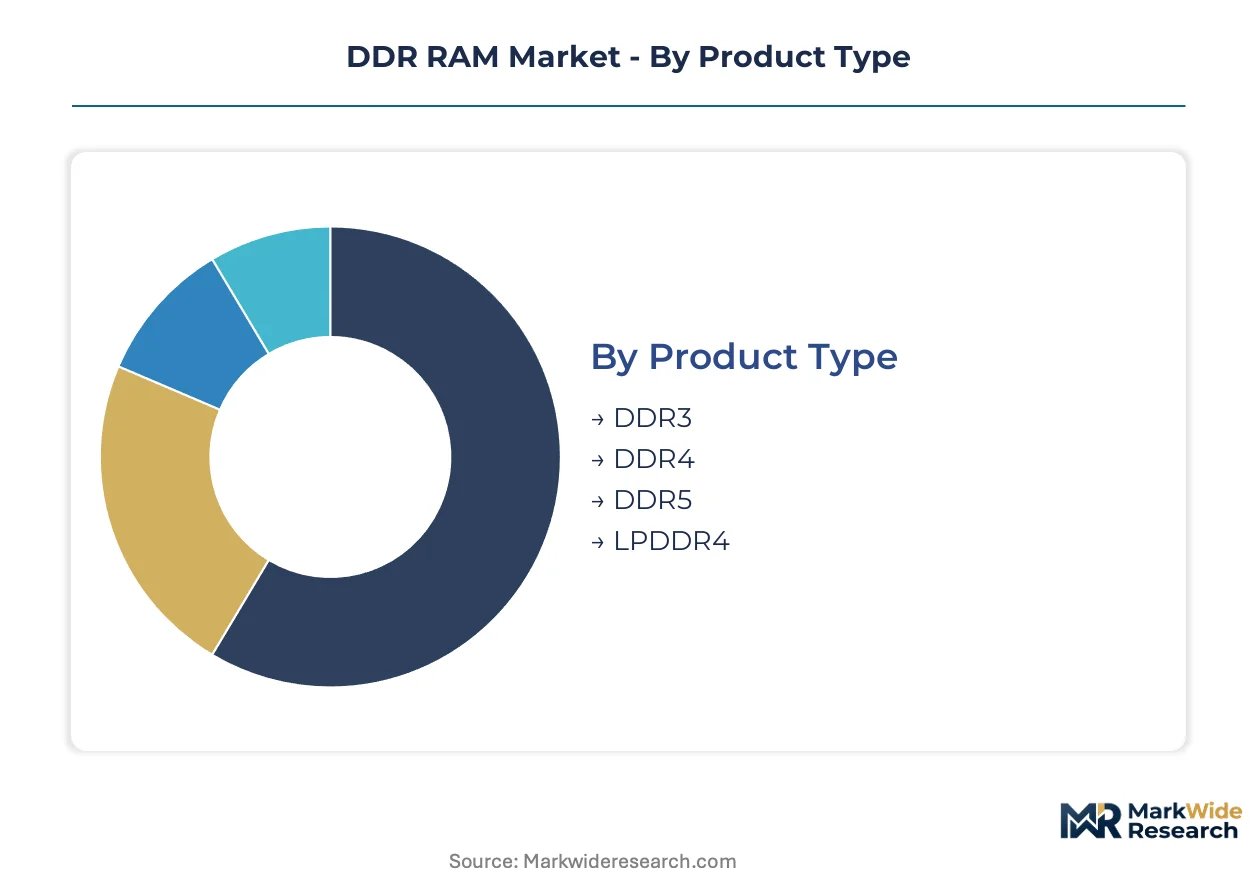
DDR RAM segmentation reveals how JEDEC specification transitions and thermal constraints reshape procurement patterns across computing tiers. Module suppliers calibrate die allocation and substrate investments against divergent margin profiles and qualification timelines.
Product Type:
DDR5 commands premium positioning through on-die power management and doubled burst length, while DDR4 retains volume dominance in cost-sensitive enterprise refresh cycles.
- DDR5:Operates at 1.1V with integrated PMICs and on-die error correction, reducing system-level power overhead. Demand concentrates in hyperscale cloud data centers where MIIT dual carbon mandates accelerate transitions from legacy architectures.
- DDR4:Mature 1.2V specification with established qualification pathways across OEM server portfolios. Volume concentrates in Chinese and European enterprise infrastructure where extended depreciation schedules delay DDR5 migration.
- DDR3:1.5V legacy modules sustaining industrial automation and telecommunications equipment with decade-long lifecycle commitments.
- LPDDR4:Low-power variants optimized for mobile and automotive edge computing with aggressive voltage scaling and reduced standby current.
Today's leader: DDR4. Tomorrow's challenger: DDR5.
End User:
Server deployments drive die allocation priority through high-density DIMM configurations, while automotive edge computing emerges as a margin sanctuary.
- Servers:Hyperscale operators deploy 512GB+ configurations per socket for AI training clusters, pulling module demand toward RDIMM and LRDIMM form factors with registered signal integrity.
- Consumer Electronics:Notebook and desktop applications favor SO-DIMM and standard DIMM modules where thermal constraints intersect with cost optimization.
- Workstations:Professional visualization and simulation workloads demand ECC-capable modules with stringent JEDEC qualification thresholds.
- Gaming Systems:Enthusiast segment prioritizes XMP overclocking profiles and aesthetic heat spreader integration over raw density specifications.
Server procurement anchors foundry capacity commitments. Automotive edge computing climbs fastest as autonomous driving systems expand memory-per-vehicle ratios.
Form Factor:
Thermal envelope and signal integrity requirements determine module architecture selection across device categories.
- DIMM:Standard desktop and server modules with direct motherboard mounting and passive heat spreader compatibility.
- SO-DIMM:Compact 260-pin modules dominating notebook deployments where space constraints mandate reduced z-height and integrated thermal solutions.
- RDIMM:Registered modules with data buffer chips enabling higher rank counts for financial services and telecommunications infrastructure requiring signal integrity at scale.
- LRDIMM:Load-reduced architectures with distributed data buffers supporting maximum capacity per channel in dense compute configurations.
RDIMM maintains structural importance in enterprise. LRDIMM gains share in AI training clusters.
Technology:
Process node leadership concentrates in DRAM cell architectures while SRAM retains niche positioning.
- DRAM:Capacitor-based dynamic memory with periodic refresh cycles, fabricated at sub-1alpha nodes in South Korea's manufacturing corridor.
- SDRAM:Synchronous interface protocols governing timing alignment with system bus clocks across all DDR generations.
- SRAM:Static cell architectures with higher bit cost and lower density, deployed in cache hierarchies and specialized embedded applications.
- Others:Emerging resistive and magnetoresistive technologies in pre-commercial evaluation for specific workload acceleration.
DRAM commands absolute volume dominance. SRAM defends cache application strongholds.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized process engineers concentrate in South Korea's semiconductor corridor, with additional talent pools forming around Dresden's silicon ecosystem and Hsinchu's foundry cluster. These concentrations anchor DRAM fabrication capacity and module assembly operations.
South Korea
Hyperscale cloud operators pull high-density DIMM supply from Samsung Electronics and SK Hynix fabrication complexes near Seoul. The Ministry of Trade, Industry and Energy enforces carbon-neutral manufacturing mandates through K-ETS compliance pathways. Pyeongtaek's sub-1alpha DRAM foundries are expanding cleanroom capacity to meet DDR5 yield ramp targets.
China
Domestic data center operators accelerate memory procurement under MIIT dual carbon certification requirements. GB standards and MIIT energy efficiency mandates create parallel compliance frameworks for module substrate materials. Yangtze Memory Technologies anchors fabrication investment in Wuhan's optoelectronics cluster alongside downstream module assembly in Dongguan.
United States
Financial services institutions in New York and Chicago drive RDIMM demand through stringent operational risk frameworks. FCC equipment authorization intersects with emerging SEC climate disclosure rules to shape procurement criteria. Micron Technology's Boise headquarters coordinates with Manassas, Virginia fabrication for automotive-grade LPDDR qualification.
Germany
Frankfurt and London financial infrastructure deployments prioritize JEDEC-qualified supplier lists over spot-market sourcing. ECHA REACH substance restrictions and EU F-Gas Regulation mandate halogen-free substrate materials in server modules. Dresden's silicon cluster hosts advanced packaging research linking wafer fabrication to European data center supply chains.
Japan
Automotive OEMs in Toyota City and Yokohama expand LPDDR5 procurement for autonomous driving systems. METI semiconductor revitalization subsidies support DRAM process node advancement at Kioxia-aligned research consortia. Hiroshima's materials science institutes develop alternative ABF substrates to reduce module laminate cost volatility.
DDR RAM Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in DDR module supply. Foundry-dependent players anchor wafer supply through captive or contracted DRAM fabrication, while fabless module assemblers compete on qualification speed and thermal integration specialization. Three archetypes dominate: vertically integrated memory conglomerates controlling wafer-to-module production, specialized module assemblers sourcing commodity dies, and automotive-focused suppliers certifying extended-temperature variants. Capacity expansion and strategic die allocation commitments represent the dominant competitive moves as DDR5 yield ramps compress available supply.
Among integrated memory producers, Samsung Electronics and SK Hynix occupy positions exemplifying foundry-to-module control, while Micron Technology represents the technology-specialization archetype in automotive and edge computing segments. Kingston Technology anchors the module-assembly tier through volume scale in consumer and enterprise channels. These named entities illustrate how competitive positioning stratifies across fabrication ownership, application focus, and qualification depth rather than product differentiation alone.
| Leading Market Players |
|---|
| Intel Corporation |
| Transcend Information |
| SK Hynix |
| Apacer |
| Innodisk |
| Samsung Electronics |
| Kingston Technology |
| GigaDevice |
| Micron Technology |
| Others |
Pricing and Supply Chain Analysis
ABF substrate spot pricing cascades through DDR module manufacturing tiers, compressing margins for fabless assemblers while vertically integrated producers capture cost advantages through captive laminate sourcing. South Korea's manufacturing corridor anchors wafer supply, concentrating pricing power among foundry-integrated suppliers serving hyperscale cloud operators under MIIT dual carbon procurement mandates.
Pricing Analysis
Bundled PMIC integration versus unbundled legacy architectures defines the pricing split across DDR generations. Three-tier pricing structure across JEDEC-qualified premium, enterprise-standard, and spot-market economy levels reflects certification depth and volume commitment scale. Cost compression in fabless assembly tiers is intensifying because ABF laminate demand from advanced packaging competes for limited substrate capacity. Hyperscale cloud operators exhibit lowest price sensitivity due to total-cost-of-ownership optimization, while industrial DDR3 replacement buyers remain most margin-constrained.
Supply Chain Analysis
JEDEC qualification gates create 12-18 month supplier onboarding timelines that protect incumbent positions against rapid substitution. Wafer fabrication concentrates in South Korea, Taiwan, and the United States, with module assembly distributing across China, Vietnam, and Malaysia. Raw material dependencies span ABF substrates from Japan, high-purity silicon wafers from Germany and Japan, and specialty gases from the United States and France. Single-source vulnerability runs through sub-1alpha DRAM foundry equipment constrained to ASML EUV lithography systems. Distribution runs through direct OEM qualification channels for enterprise servers and distributor networks for consumer and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between South Korea's carbon-neutral manufacturing mandates under K-ETS and China's MIIT dual carbon certification requirements, with regulatory compliance cost differentials reshaping foundry location decisions.
For Market Incumbents: Anticipate margin compression from Chinese domestic module suppliers qualifying under GB standards by securing captive ABF substrate capacity through backward integration into laminate manufacturing or long-term offtake agreements with Japanese suppliers. SK Hynix and Samsung Electronics should accelerate Pyeongtaek cleanroom expansion ahead of DDR6 JEDEC disclosure timelines to defend yield leadership against emerging Chinese fabrication investment. For New Entrants and Emerging Players: Begin with automotive-grade LPDDR5 certification for autonomous driving systems, where extended temperature range requirements and AEC-Q100 testing create qualification barriers that favor specialized entrants over commodity server module suppliers. Target Japanese automotive OEMs in Toyota City and Yokohama through METI-subsidized research consortia partnerships, leveraging Hiroshima materials science institutes for alternative substrate development. For Investors and Strategic Acquirers: Asymmetric upside sits with automotive-focused module specialists certifying extended-temperature LPDDR variants, where content-per-vehicle expansion in autonomous systems supports long-term viability across a 5-10 year electrification window. Acquisition targets should demonstrate existing AEC-Q100 qualification pipelines and established relationships with Tier 1 automotive suppliers. The signal to watch as inflection indicator is JEDEC DDR6 roadmap disclosure timing and foundry capex allocation shifts toward sub-7nm DRAM process nodes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into ABF Substrate Manufacturing | Captive laminate supply insulates margin structures from advanced packaging demand competition. |
| JEDEC DDR6 Qualification Pre-Positioning | Early specification alignment compresses OEM onboarding timelines ahead of volume ramp. |
| Automotive AEC-Q100 Certification Investment | Extended-temperature qualification opens LPDDR5 procurement from Toyota and Yokohama OEMs. |
| MIIT Dual Carbon Compliance Pathway Development | GB standards alignment unlocks Chinese data center procurement under energy efficiency mandates. |
| Direct Hyperscale Cloud Operator Contracting | Long-term offtake agreements with AWS, Azure, or GCP anchors foundry capacity commitments. |
Research Methodology
Direct dialogue with DRAM process engineers, data center procurement officers at hyperscale cloud operators, JEDEC standards committee participants, and automotive Tier 1 supplier quality managers grounded qualitative assessment in operational reality. Secondary validation drew from SEC 10-K filings of publicly traded memory producers, MIIT energy efficiency certification databases, ECHA REACH substance restriction updates, and hyperscaler capex disclosure transcripts. Bottom-up die allocation modeling and top-down server shipment projections were cross-referenced to calibrate volume estimates.
Bottom-up segment analysis traced module demand through server refresh cycles, automotive platform launches, and consumer device production schedules, while top-down macro constraints incorporated foundry capacity ceilings and JEDEC transition timelines. Segmentation dimensions spanned DDR generation, form factor architecture, end-use application, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical price-band trajectories and elasticity-adjusted demand curves, with inputs from DRAM spot market indices and OEM qualification pipeline visibility.
Several conditions sit outside the modeled scope, including geopolitical disruption to South Korean fabrication corridors, breakthrough emergence of resistive or magnetoresistive memory alternatives, and abrupt shifts in AI training workload architecture affecting memory-per-socket ratios. Forecasts reflect assumptions about JEDEC specification adherence timelines and foundry yield ramp trajectories. A model refresh is warranted upon material change in MIIT dual carbon enforcement intensity or ASML EUV equipment export control expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Magnetoresistive Random Access Memory (MRAM) Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Memory Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
MRAM Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Embedded Non-Volatile Memory Market
Memory Chips
DRAM Market
Memory Chips
Memristor Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Global Standalone Memory Market
Memory Chips
ECC Memory Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Japan Flash Memory Market