
 Methyl Isopropyl Ketone Market | 2026-2036
Methyl Isopropyl Ketone Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Isopropyl Ketone Market Outlook
Modular solvent bundling is pivoting procurement patterns across the Methyl Isopropyl Ketone value chain as buyers seek pre-blended formulations rather than single-species purchases. The Dow Chemical Company leverages its integrated acetone derivative network to control feedstock costs across multiple geographies. Royal Dutch Shell Plc anchors its position through refinery-chemical synergies that sustain steady ketone output. Eastman Chemical Company differentiates via specialized high-purity grades targeting electronics and pharmaceutical intermediates.
Methyl Isopropyl Ketone, also known as 3-methyl-2-butanone, is a colorless liquid ketone with the molecular formula C5H10O, manufactured primarily through acid-catalyzed dehydrogenation of methyl isobutyl carbinol and valued for its medium evaporation rate and strong solvency power in coating systems. The solvent segment dominates volume as paints and coatings manufacturers consume bulk quantities for viscosity control and film formation in industrial applications. The intermediate segment registers the fastest structural expansion as pharmaceutical and agrochemical syntheses demand higher-purity ketone feedstocks. Direct sales channels capture the largest margin pools by bypassing distributor markups for committed offtake agreements with automotive OEMs and large coatings formulators.
REACH compliance in Europe mandates registration and hazard communication for ketone solvent emissions, pushing reformulation toward lower-toxicity alternatives or containment systems. EPA regulations in the United States govern volatile organic compound thresholds in industrial coatings, directly constraining open-use applications of methyl isopropyl ketone in automotive refinishing. China's MEE enforces air quality standards around the Yangtze River Delta that pressure solvent users toward recovery systems or substitute chemistries. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with emerging compliance boundaries rather than legacy specifications.
Market Dynamics
Modular solvent bundling is restructuring procurement across the methyl isopropyl ketone value chain as buyers abandon single-species purchasing for pre-blended formulations that reduce inventory complexity and mixing labor.
Growth Catalysts
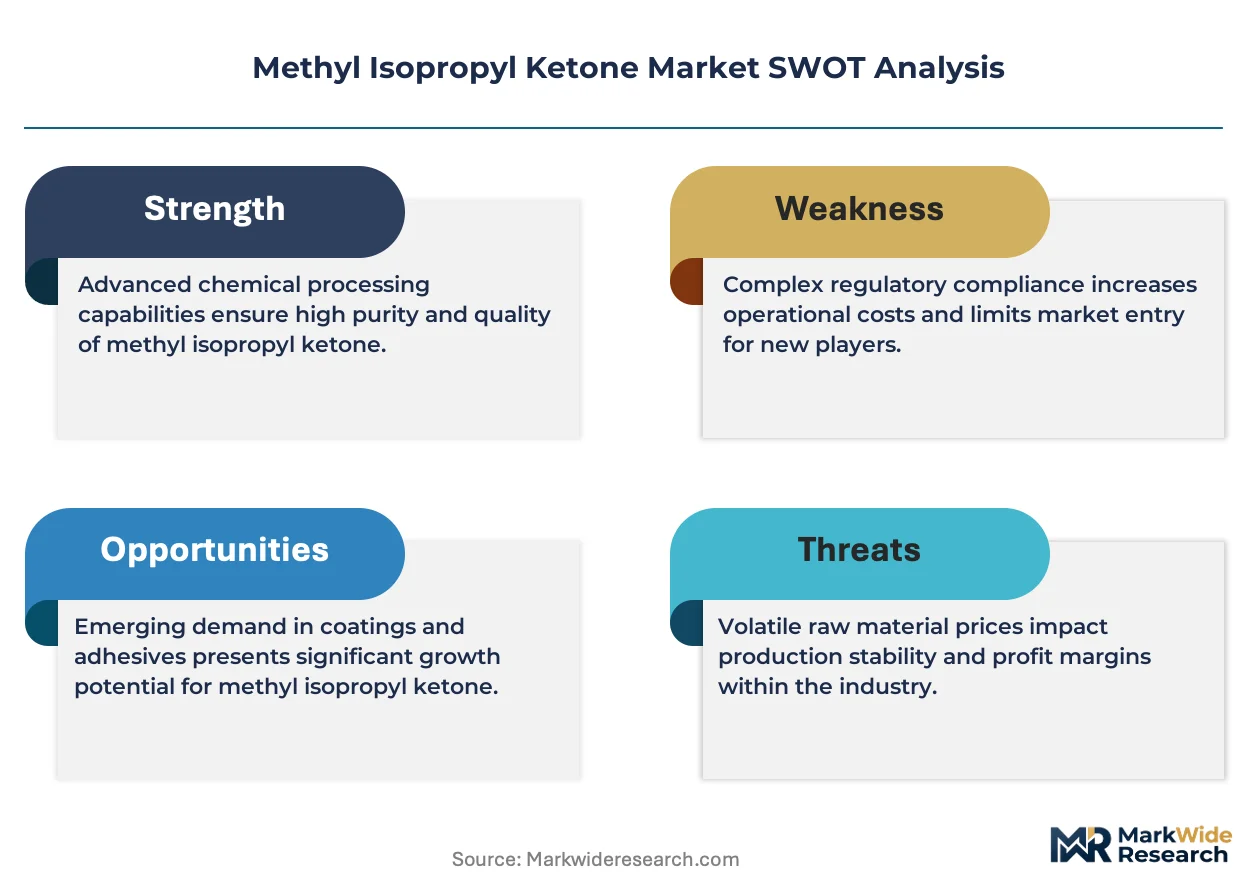
- REACH Phase-Down Schedules:European coatings formulators are accelerating ketone purchases ahead of restricted substance list revisions, building strategic solvent reserves.
- Industrial Coatings Clustering:Production concentration around Shanghai and Guangdong province generates sustained bulk demand from integrated paint manufacturing parks.
- Pharmaceutical Synthesis Expansion:Active pharmaceutical ingredient producers are diversifying ketone feedstock sources for chiral intermediate production.
Market Restraints
- Acetone Price Volatility:Feedstock cost swings from propylene supply disruptions compress ketone producer margins unpredictably.
- MEE Air Quality Enforcement:China's Ministry of Ecology and Environment is restricting open solvent use in Yangtze River Delta manufacturing zones.
- Aqueous Coating Substitution:Waterborne epoxy and polyurethane systems are capturing share in light industrial applications previously served by solvent-grade ketones.
Strategic Opportunities
- High-Purity Electronics Grades:Semiconductor solvent cleaning applications demand sub-ppm impurity specifications that command premium positioning.
- Recovery System Integration:Closed-loop solvent recycling mandates in German automotive OEM paint shops create service-anchored supply contracts.
- Agrochemical Intermediate Channels:Pyrethroid and fungicide synthesis lines in India offer underdeveloped offtake potential for specialty ketone purities.
Industry Challenges
- Process Safety Certification:ATEX and IECEx compliance for ketone handling infrastructure extends facility commissioning timelines.
- Specialized Logistics Coordination:Hazmat transport capacity constraints between European production sites and coatings clusters complicate just-in-time delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Isopropyl Ketone Market |
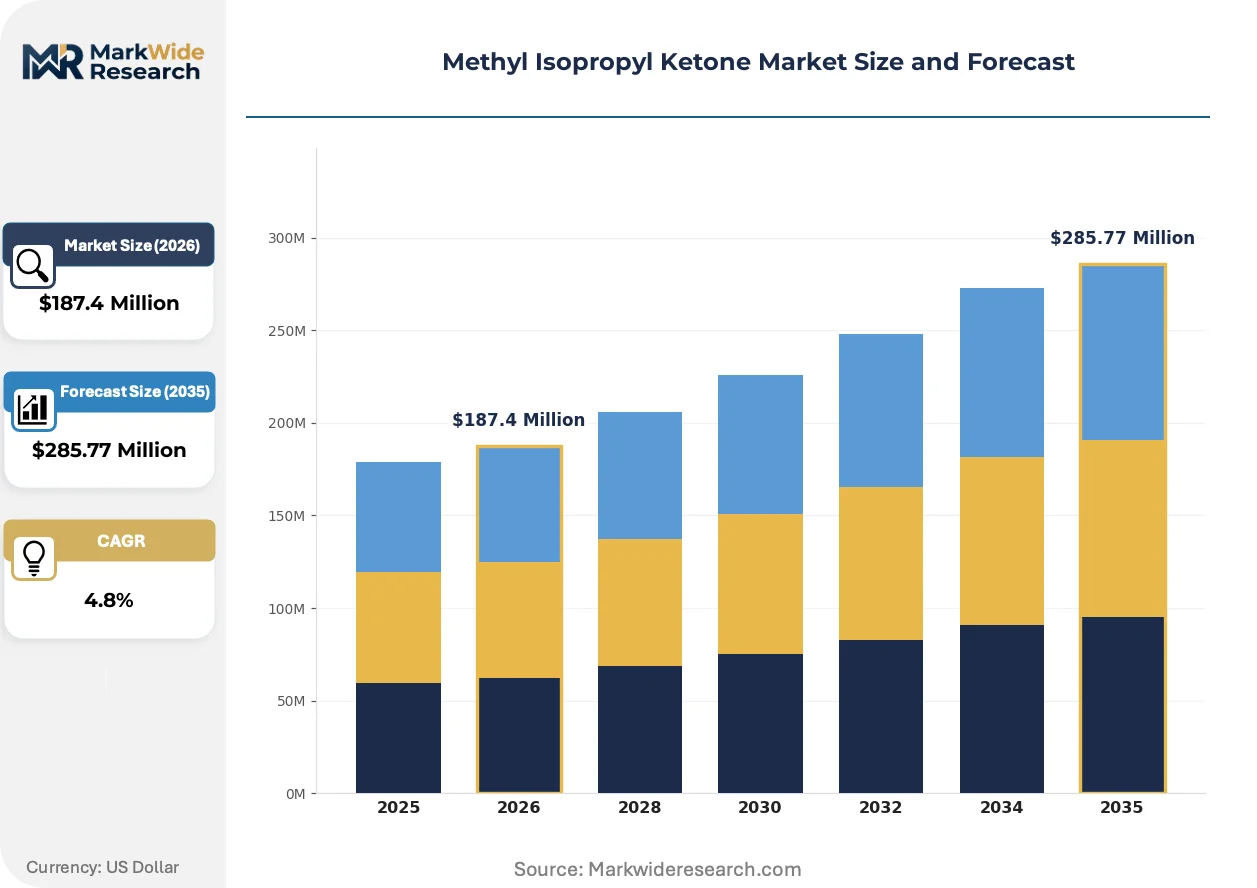
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Additive, Chemical Reagent End Use Industry: Paints, Coatings, Adhesives, Automotive Application: Industrial, Commercial, Household, Research Distribution Channel: Direct Sales, Distributors, Online Retailers, Others |
| Companies Covered | The Dow Chemical Company, Royal Dutch Shell Plc, Kumho P&B Chemicals Inc., Lee Chang Yung Chemical, Celanese Corporation, Eastman Chemical Company, Mitsubishi Chemical Corporation, Mitsui Chemicals, Inc., Monument Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Isopropyl Ketone Market Strategic Shifts
Digital formulation platforms are compressing solvent selection cycles as coatings developers simulate evaporation profiles and solubility parameters before physical testing.
Continuous dehydrogenation reactor technology is decentralizing methyl isopropyl ketone production economics. Mid-scale coatings formulators in the US Midwest and Northern Italy are adopting modular skid-mounted units that bypass traditional merchant supply chains. This distributed manufacturing model is compressing lead times from weeks to days for regional solvent demand.
EPA volatile organic compound thresholds for industrial maintenance coatings are forcing reformulation across automotive refinishing and aerospace MRO segments. The regulatory pressure is accelerating ketone substitution with exempt solvents in low-temperature cure applications. California's South Coast Air Quality Management District is extending these constraints through localized rulemaking that exceeds federal baselines.
Direct mill supply contracts are displacing distributor intermediation in volume coatings procurement. Large automotive OEMs and industrial paint formulators in Germany and Japan are negotiating multi-year offtake agreements that lock in specification consistency and bypass traditional chemical distribution markups. This channel consolidation is most pronounced in solvent purchases exceeding annual thresholds.
Methyl Isopropyl Ketone Market Segmentation
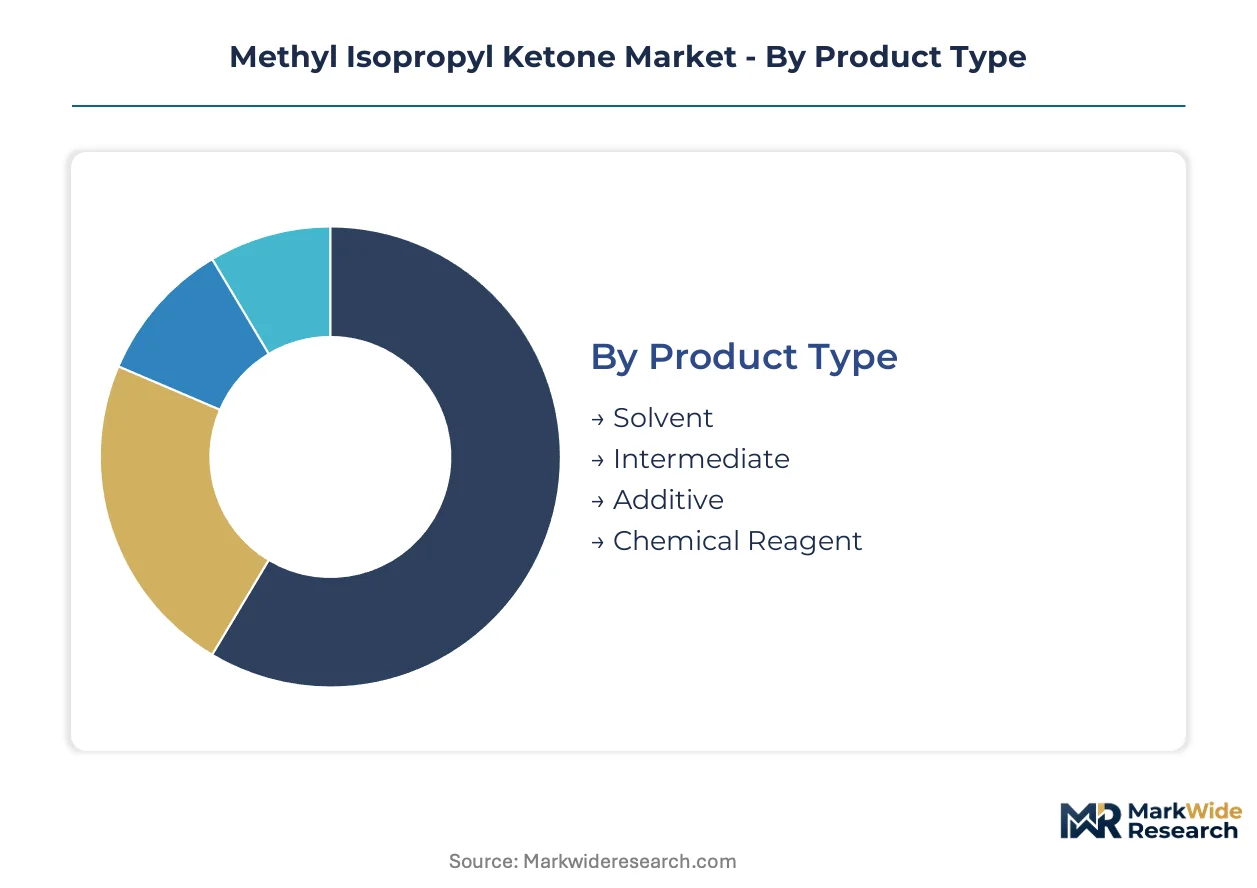
Segmentation in methyl isopropyl ketone markets determines capital allocation priorities, as product purity grades and channel structures carry vastly different equipment and certification costs. Buyers across coatings and pharmaceutical verticals sort procurement by technical specification rather than commodity pricing alone.
Product Type:
Solvent grades demand continuous distillation infrastructure and VOC containment systems, while intermediate grades require pharmaceutical-grade reactor trains and GMP validation suites.
- Solvent:Technical-grade material with medium evaporation rate serves viscosity control in industrial coating systems. Demand concentrates in Shanghai and Guangdong province manufacturing clusters as China's MEE enforces air quality standards that pressure users toward recovery systems.
- Intermediate:Higher-purity ketone feedstocks with sub-ppm impurity tolerances enable chiral synthesis for active pharmaceutical ingredients. Pharmaceutical producers in Germany and Japan are diversifying sourcing channels to secure specification consistency for regulatory filings.
- Additive:Formulation-enhancing grades modify cure rates and surface properties in specialty coatings.
- Chemical Reagent:Laboratory-scale quantities support analytical chemistry and research protocols.
Solvent absorbs the bulk of installed capacity; intermediate is expanding most quickly.
End Use Industry:
Volume concentration varies sharply by customer scale, with automotive OEMs commanding dedicated supply contracts while smaller coatings formulators rely on distributor networks.
- Paints:Architectural and decorative coatings consume bulk solvent volumes for film formation and flow control. Industrial paint manufacturing parks in Northern Italy and the US Midwest are adopting modular skid-mounted production units that bypass traditional merchant supply chains.
- Coatings:Protective and industrial finishes require precise evaporation profile matching for humidity-sensitive applications. REACH compliance mandates in Europe are accelerating ketone purchases ahead of restricted substance list revisions.
- Adhesives:Pressure-sensitive and structural bonding formulations utilize ketone solvency for substrate wetting.
- Automotive:OEM paint shops and refinishing operations drive specification-grade demand with closed-loop recycling mandates.
Coatings command the largest volume commitments; automotive exhibits the steepest specification escalation.
Application:
Regulatory exposure scales inversely with end-use sophistication, as research applications face minimal EPA or REACH constraints while industrial open-use faces maximum compliance burden.
- Industrial:Heavy-duty maintenance and manufacturing applications consume solvent-grade material in uncontrolled environments. EPA volatile organic compound thresholds are forcing reformulation across automotive refinishing and aerospace MRO segments.
- Commercial:Professional installation and service applications balance performance with workplace exposure limits.
- Household:Consumer-accessible products face the tightest toxicity labeling and packaging requirements.
- Research:Laboratory and analytical applications demand highest-purity grades with full certification documentation.
Industrial absorbs the bulk of volume throughput; research commands the steepest premium escalation.
Distribution Channel:
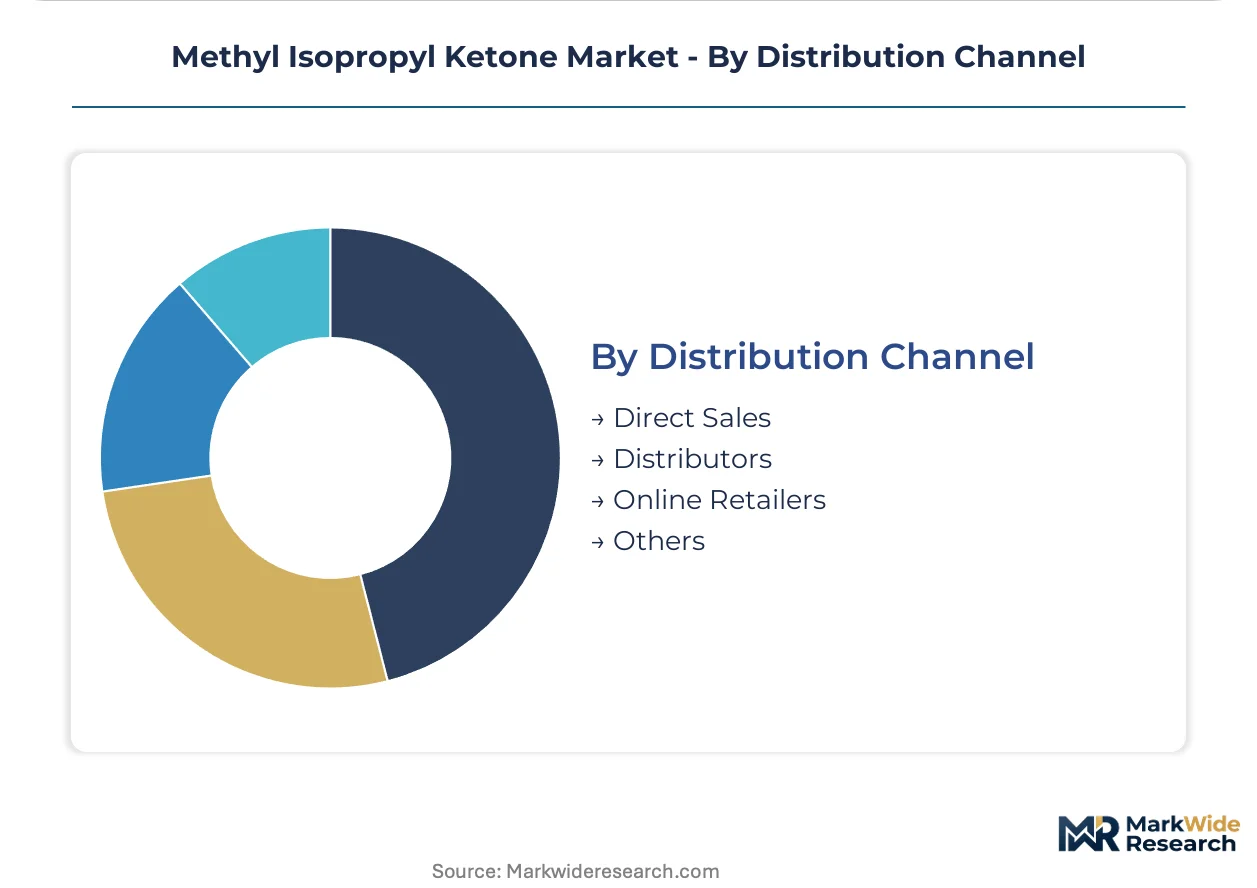
Margin capture depends on bypass depth, with direct contracts eliminating distributor markups but requiring dedicated logistics infrastructure.
- Direct Sales:Multi-year offtake agreements with large automotive OEMs and industrial paint formulators lock in specification consistency. German and Japanese manufacturers are negotiating these arrangements to bypass traditional chemical distribution markups.
- Distributors:Regional chemical distributors provide inventory pooling and technical support for mid-scale formulators.
- Online Retailers:E-commerce platforms serve small-volume research and specialty chemical procurement with rapid fulfillment.
- Others:Brokered arrangements and spot market transactions serve residual demand swings.
Direct sales anchors the largest margin pools; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Northeast Asia and the US Gulf Coast, while consumption tilts toward industrial coatings clusters in Eastern China and automotive manufacturing belts across Germany and the US Midwest.
China
Industrial coatings manufacturers around Shanghai and Guangdong province drive bulk solvent demand as MEE air quality enforcement tightens across the Yangtze River Delta. The Ministry of Ecology and Environment mandates solvent recovery systems in manufacturing zones. Paint production parks in Jiangsu and Zhejiang provinces are retrofitting closed-loop infrastructure to maintain operating permits.
United States
Automotive OEM paint shops and aerospace MRO operations sustain specification-grade ketone consumption despite EPA VOC threshold pressure. The Environmental Protection Agency constrains open-use applications in industrial maintenance coatings. Gulf Coast petrochemical corridors near Houston anchor domestic production capacity with integrated acetone derivative networks.
Germany
Pharmaceutical intermediate producers demand high-purity grades for chiral synthesis applications as ECHA reviews restricted substance list revisions under REACH. The European Chemicals Agency accelerates registration timelines for ketone solvent emissions. Automotive paint shops in Bavaria and Baden-Württemberg operate closed-loop recycling mandates that create service-anchored supply contracts.
Japan
Electronics-grade solvent cleaning applications for semiconductor fabrication command premium positioning with sub-ppm impurity specifications. METI industrial standards shape chemical handling protocols for ketone distribution. Manufacturing clusters in Kansai and Chubu regions source through multi-year offtake agreements that bypass distributor markups.
India
Agrochemical synthesis lines for pyrethroid and fungicide production offer underdeveloped offtake potential for specialty ketone purities. The Central Pollution Control Board enforces air quality standards around chemical manufacturing zones. Gujarat and Maharashtra industrial corridors attract import-dependent formulators seeking alternative feedstock channels.
Methyl Isopropyl Ketone Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the methyl isopropyl ketone value chain. The vendor base stratifies into three tiers: integrated petrochemical majors with captive feedstock security, mid-scale regional producers with flexible batch capabilities, and specialty chemical houses targeting pharmaceutical and electronics grades. Strategic moves center on backward integration into acetone supply and modular skid-mounted production units that compress regional lead times.
Within the integrated petrochemical tier, The Dow Chemical Company and Royal Dutch Shell Plc occupy positions shaped by refinery-chemical synergies and derivative network control. Eastman Chemical Company exemplifies the specialty-grade archetype, anchoring high-purity positioning for electronics and pharmaceutical intermediate channels. Kumho P&B Chemicals Inc. represents Northeast Asian production scale with Korean industrial chemical heritage.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| Royal Dutch Shell Plc |
| Kumho P&B Chemicals Inc. |
| Lee Chang Yung Chemical |
| Celanese Corporation |
| Eastman Chemical Company |
| Mitsubishi Chemical Corporation |
| Mitsui Chemicals, Inc. |
| Monument Chemical |
| Others |
Value Chain & Pricing Dynamics
Modular solvent bundling from coatings manufacturers in Shanghai and Guangdong province is compressing single-species procurement volumes, forcing ketone producers to reconfigure batch sizes and accept lower per-unit realizations to retain offtake commitments.
Pricing Analysis
Margin tightening in solvent-grade tiers reflects acetone feedstock volatility from propylene supply disruptions across Gulf Coast petrochemical corridors. Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and technical solvent levels separates specification tolerances and certification costs. Cost-down pressure on intermediate-grade material accelerates because API producers in Germany and Japan are consolidating supplier panels. Small coatings formulators exhibit highest price sensitivity; semiconductor fabricators in Kansai and Chubu regions show lowest.
Supply Chain Analysis
Skilled technician availability constraints in Jiangsu and Zhejiang province paint production parks are extending commissioning timelines for closed-loop recovery infrastructure. Supply concentrates in China, the United States, and Germany, with Northeast Asian capacity anchored in Korean industrial chemical networks. Feedstock draws from acetone derivative streams, methyl isobutyl carbinol dehydrogenation catalysts, and refinery-chemical integration outputs. Single-source vulnerability to MEE air quality enforcement in Yangtze River Delta zones threatens operating permit continuity. Distribution runs through direct mill supply contracts for automotive OEMs and regional chemical distributors for mid-scale formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acid-catalyzed dehydrogenation reactor capacity constraints in merchant supply chains are sustaining pricing power for integrated producers with captive feedstock security.
For Market Incumbents: Extend backward integration into acetone supply networks to buffer propylene cost swings, and expand high-purity reactor train capacity for electronics-grade specifications before semiconductor solvent cleaning demand escalates. Waterborne coating substitution in light industrial applications threatens solvent-grade volume; GMP validation suites for pharmaceutical intermediate channels offer margin defense. For New Entrants and Emerging Players: Launch via modular skid-mounted production units serving regional coatings clusters in the US Midwest and Northern Italy, bypassing established merchant supply chains with compressed lead times. Agrochemical synthesis lines in Gujarat and Maharashtra industrial corridors represent the most penetrable white-space target; specialty ketone purities for pyrethroid production face limited domestic competition. For Investors and Strategic Acquirers: The window for entry favors mid-scale regional producers with flexible batch capabilities and existing ATEX certification infrastructure. Long-term viability hinges on positioning for closed-loop solvent recycling mandates in German automotive OEM paint shops. Watch ECHA restricted substance list revisions under REACH as the signal for ketone demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acetone supply from Gulf Coast petrochemical corridors buffers margin compression from propylene volatility. |
| High-Purity Capacity Expansion | Sub-ppm impurity specifications for semiconductor cleaning in Kansai commands premium positioning. |
| Modular Production Deployment | Skid-mounted units in Northern Italy compress lead times from weeks to days for regional coatings demand. |
| Recovery System Partnerships | Closed-loop infrastructure retrofits in Jiangsu province secure operating permits under MEE enforcement. |
| Long-term Offtake Agreements | Multi-year contracts with Bavarian automotive OEMs bypass distributor markups and lock specification consistency. |
Study Parameters
Document review covered SEC 10-K filings, customs and trade data, and European Chemicals Agency registration databases, complemented by interviews with plant managers at ketone production facilities, procurement leads at coatings OEMs, distribution channel partners, and technical R&D directors. Bottom-up volume estimates from individual facility capacities were triangulated against top-down demand assessments from end-use industry consumption patterns.
Segment-level value outputs across the analysis window were generated through modeling of grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from regression analysis of historical price-volume relationships and projected feedstock cost trajectories. Key inputs included EPA VOC threshold enforcement timelines, MEE air quality standard implementation schedules, and semiconductor fabrication capacity expansion announcements.
Feedstock cost volatility, regulatory divergence between REACH and EPA frameworks, and aqueous coating substitution rates are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Hydrocarbon Solvents Market
Solvents
Tetraethyl Benzene Market
Solvents
Sugar Dissolvers Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Global Droppers Market
Solvents
2-Butanone Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
India High Purity Solvents Market
Solvents
Dihydromyrcene Market
Solvents
Mono Propylene Glycol Market
Solvents
Mixed Xylene Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Dimethyl Ether (DME) Market
Solvents
Mineral Turpentine Market
Solvents
GCC Acetonitrile Market
Solvents
6-Xylenol Market