
 Global Ethyl Lactate Market | 2026-2036
Global Ethyl Lactate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ethyl Lactate Market Analysis
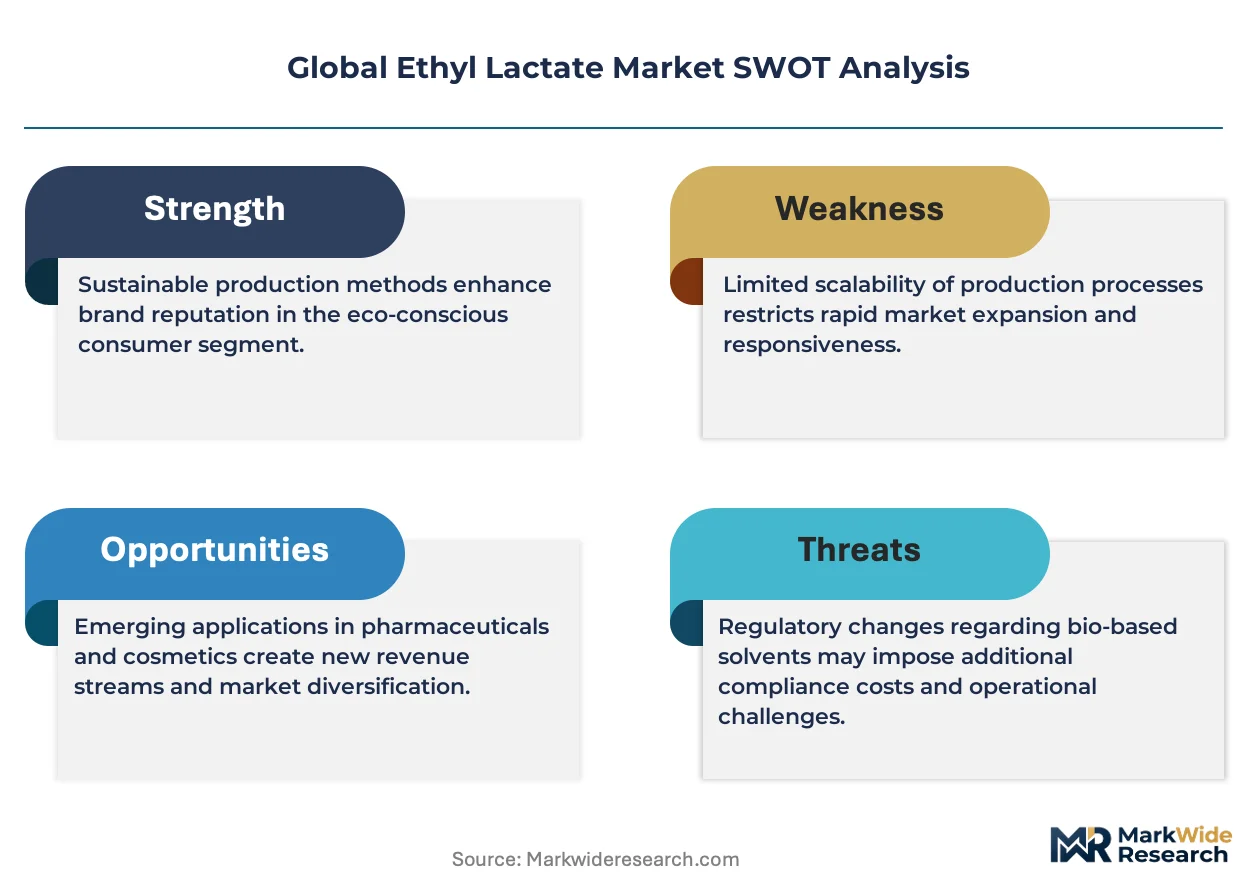
ISO 9001 certification is bifurcating the supplier base into qualified pharmaceutical-grade producers and commodity solvent vendors. Corbion N.V. leverages its integrated fermentation platform to secure lactic acid feedstock security across European and North American plants. Godavari Biorefineries Ltd. anchors its position through cane-sugar-derived lactic acid, giving it distinct feedstock economics against petrochemical rivals. Vertec BioSolvents Inc. specializes in bio-based solvent formulations, competing on sustainability credentials rather than volume scale.
Ethyl lactate is an ester synthesized from lactic acid and ethanol, typically exhibiting a boiling point near 154°C and miscibility with most organic solvents, which positions it as a biodegradable replacement for halogenated and aromatic solvents in precision cleaning and coatings. The solvent segment dominates current volume flows, though pharmaceutical-grade 99% purity grades command disproportionate margin pools due to stringency in residual impurity limits. Food end-use applications sustain steady offtake, particularly as carriers for flavor compounds where GRAS status applies.
EPA oversight of volatile organic compound emissions shapes solvent substitution patterns in US industrial cleaning, while REACH registration requirements in Europe filter out non-compliant import streams. China's SAMR enforces GB standards for food-contact chemicals, creating a separate compliance pathway for domestic versus export-oriented producers. Stakeholders must monitor how biorefinery capacity expansions in lactic acid reshape ethyl lactate feedstock economics and regional cost curves.
Market Dynamics
Pharmaceutical-grade certification requirements are compressing the supplier base into two tiers—qualified producers capable of meeting residual impurity limits below 0.1% and commodity solvent vendors serving industrial cleaning applications. This bifurcation is redistributing margin pools toward fermentation-integrated manufacturers with captive lactic acid supply.
Growth Catalysts
- EPA VOC emission limits:Industrial cleaning operators in the United States face escalating compliance costs with halogenated solvents, accelerating substitution toward ethyl lactate in precision electronics and aerospace degreasing.
- Pharmaceutical green chemistry mandates:Drug manufacturers pursuing ESG targets specify bio-based solvents in active pharmaceutical ingredient synthesis, pulling ethyl lactate into reaction media and crystallization steps.
- China's lactic acid feedstock expansion:Domestic fermentation capacity in Shandong and Henan provinces is lowering ethyl lactate production costs relative to petrochemical ester alternatives.
Market Restraints
- Feedstock cost volatility:Corn and cane sugar prices fluctuate with agricultural commodity cycles, squeezing margins for fermentation-based producers without long-term supply contracts.
- Technical performance gaps:Ethyl lactate exhibits lower solvency power for certain high-molecular-weight resins compared to aromatic hydrocarbons, limiting penetration in industrial coatings reformulation.
- REACH registration friction:European importers face extended compliance timelines and testing costs for purity documentation, filtering out smaller traders from the regional supply base.
Strategic Opportunities
- India specialty chemicals growth:Contract research and manufacturing organizations in Hyderabad and Ahmedabad are adopting green solvents for export-oriented pharmaceutical intermediates.
- Semiconductor wet processing:Advanced packaging facilities require ultra-high-purity solvents for photoresist stripping, opening specification windows for 99.9% grade ethyl lactate.
- Bio-based content mandates:Corporate renewable carbon targets and EU Green Deal procurement rules favor esters with verified biogenic carbon content.
Industry Challenges
- ISO 9001 and EXCiPACT certification timelines:Pharmaceutical-grade qualification requires 18-24 months of stability data and audit cycles, delaying market entry for new fermentation assets.
- Analytical method standardization:Discrepancies between HPLC and GC-MS protocols for residual ethanol and lactic acid detection create batch release disputes between suppliers and drug manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ethyl Lactate Market |
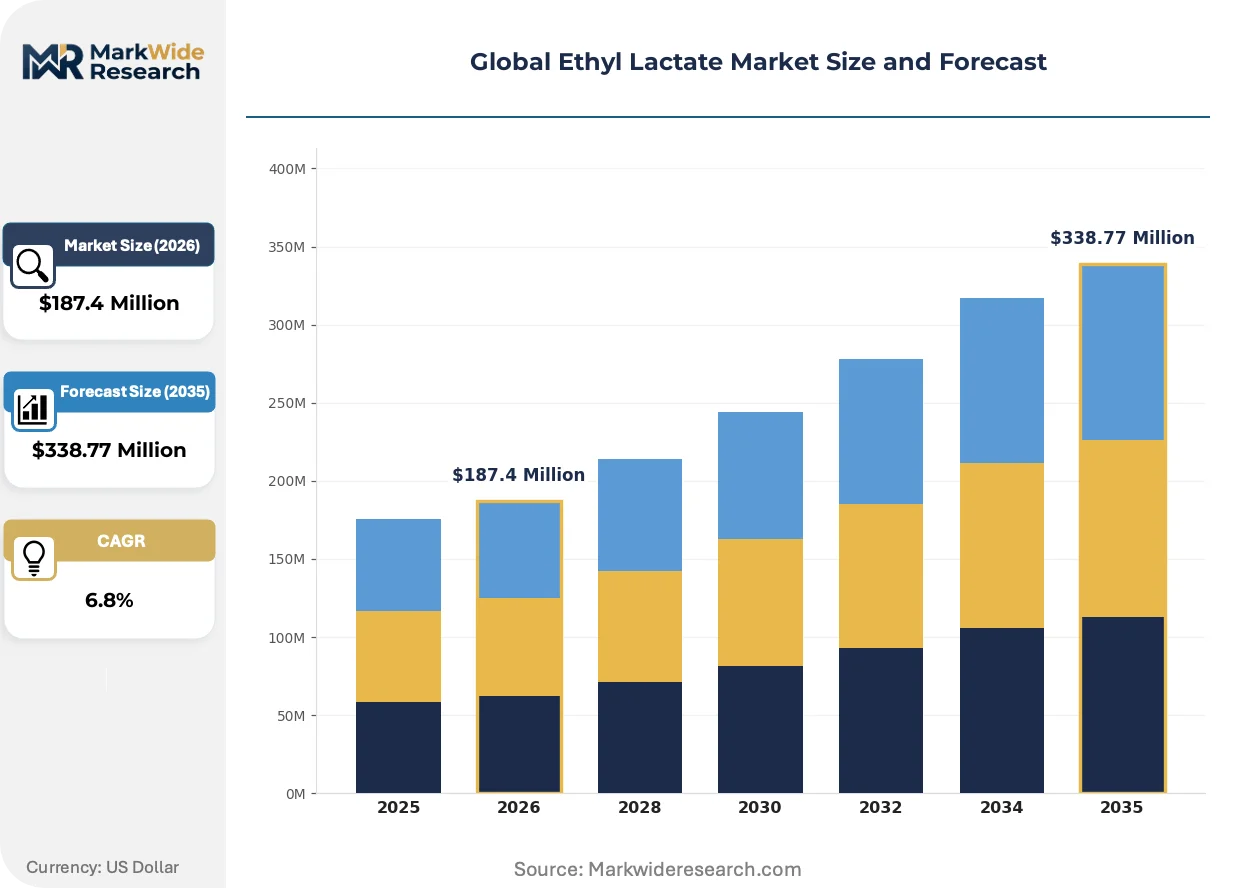
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Coating, Cleaner, Fragrance End Use Industry: Food, Pharmaceuticals, Cosmetics, Paints Distribution Channel: Online, Specialty Stores, Distributors, Supermarkets Purity Grade: 95%, 98%, 99%, Others |
| Companies Covered | Corbion N.V., Merck KGaA, Godavari Biorefineries Ltd., Henan Jindan Lactic Acid Technology Co., Ltd., Musashino Chemical Laboratory Ltd., Vertec BioSolvents Inc., Galactic, Stepan Company, Archer-Daniels-Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ethyl Lactate Market Emerging Trajectories
Continuous processing technology and advanced purification systems are reshaping how ethyl lactate achieves pharmaceutical-grade specifications. These developments compress capital intensity while tightening impurity control.
Membrane filtration coupled with molecular sieve dehydration is bifurcating the production landscape. Facilities deploying these integrated systems achieve water content below 0.05% without energy-intensive azeotropic distillation. Pharmaceutical excipient manufacturers in Germany and Switzerland are prioritizing suppliers with these capabilities. The technology is compressing cost structures for high-purity grades while marginalizing conventional batch producers.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and other reproductive toxicants are redirecting formulators toward ethyl lactate in paint stripping and graffiti removal applications. Industrial coatings manufacturers face reformulation deadlines in 2025-2026. The solvent segment in France and Benelux is responding fastest, with distributors building dedicated bio-based solvent blending capacity.
Specification-driven procurement is consolidating buyer power among pharmaceutical multinationals. These firms now mandate supplier qualification through centralized global purchasing, replacing fragmented regional sourcing. The shift is visible in consolidated tender volumes from Basel and Boston headquarters locations. Smaller regional traders are losing access to preferred supplier lists without certification investments.
Global Ethyl Lactate Market Segmentation
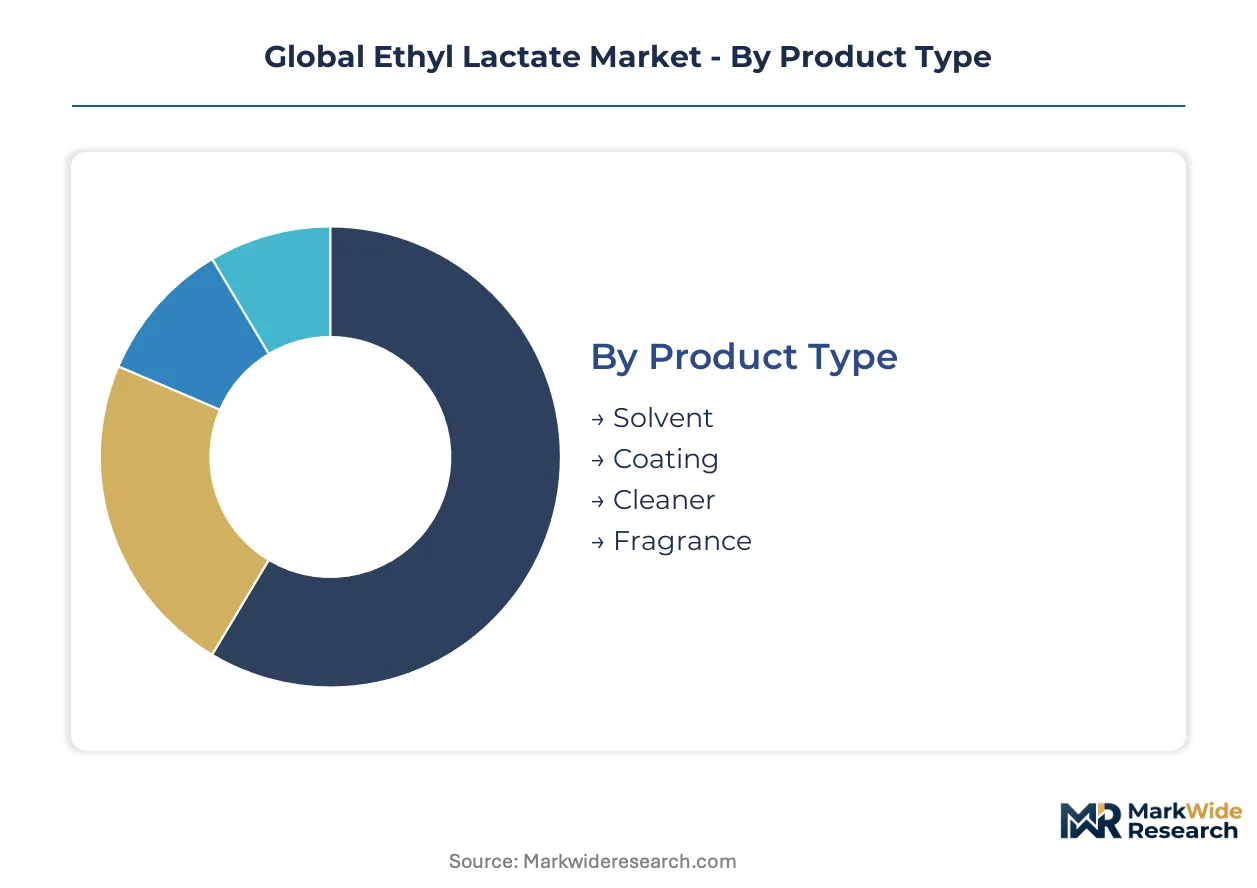
Ethyl lactate's dual identity as commodity solvent and pharmaceutical excipient fragments demand across incompatible procurement channels. Specification requirements bifurcate supply chains, with industrial buyers prioritizing volume throughput and drug manufacturers demanding batch-level documentation.
Product Type:
Solvent-grade volumes flow through bulk chemical distributors serving industrial cleaning and coatings formulators, while pharmaceutical and fragrance grades command specialized logistics with temperature-controlled handling.
- Solvent:The largest-volume application, ethyl lactate solvent replaces halogenated hydrocarbons in precision degreasing for electronics and aerospace. EPA VOC compliance deadlines in the United States are accelerating substitution from perchloroethylene and trichloroethylene in metal finishing operations across Ohio and Michigan manufacturing clusters.
- Coating:Lower solvency power versus aromatic hydrocarbons limits penetration in high-solids industrial coatings, though waterborne system compatibility sustains niche adoption. European coatings manufacturers in Germany and the Netherlands are reformulating decorative paints ahead of REACH Annex XVII restrictions on N-methylpyrrolidone.
- Cleaner:Biodegradability credentials position ethyl lactate in institutional and consumer cleaning products where aquatic toxicity regulations apply. Concentrated formulations for graffiti removal are gaining shelf space in French and Belgian retail channels.
- Fragrance:GRAS status and low odor threshold enable use as a carrier solvent for natural and synthetic fragrance compounds in personal care applications.
By volume, Solvent leads. By growth pace, Coating is climbing the fastest as regulatory deadlines force reformulation.
End Use Industry:
Cost tiers separate commodity food and paint applications from premium pharmaceutical specifications, with certification requirements determining supplier eligibility.
- Food:GRAS-listed ethyl lactate functions as a flavor carrier and solvent for food-grade colorants. Chinese food additive manufacturers in Guangdong province are expanding domestic ethyl lactate offtake for processed food exports to Southeast Asia.
- Pharmaceuticals:99% purity grades with residual impurity limits below 0.1% qualify as excipients for oral and topical drug delivery. EXCiPACT certification requirements in Europe and FDA Type II Drug Master File submissions in the United States filter supplier access to multinational drug manufacturers.
- Cosmetics:Bio-based content claims drive specification in European natural cosmetic formulations, where ISO 16128 standards define renewable carbon thresholds.
- Paints:Industrial maintenance coatings and decorative paints represent steady offtake, though technical performance gaps versus traditional aromatic solvents constrain share gains in high-build applications.
Pharmaceuticals commands the steepest margin expansion trajectory. Food sustains the most stable volume base.
Distribution Channel:
Customer type determines channel selection, with multinational pharmaceutical buyers consolidating procurement through direct supplier relationships while industrial solvent users rely on distributor networks.
- Online:E-commerce platforms serve small-volume buyers in research laboratories and specialty manufacturing, offering rapid fulfillment for technical-grade material without minimum order constraints.
- Specialty Stores:Regional chemical distributors with technical service capabilities support coatings formulators and industrial cleaners with formulation guidance and blended product offerings.
- Distributors:Bulk chemical distributors dominate solvent-grade volume flows, leveraging tank storage and just-in-time delivery infrastructure across manufacturing corridors.
- Supermarkets:Consumer-facing retail channels carry diluted cleaner formulations for household applications, representing minimal ethyl lactate volume but high brand visibility.
Distributors handle the largest tonnage. Online channels are expanding most quickly for laboratory and pilot-scale procurement.
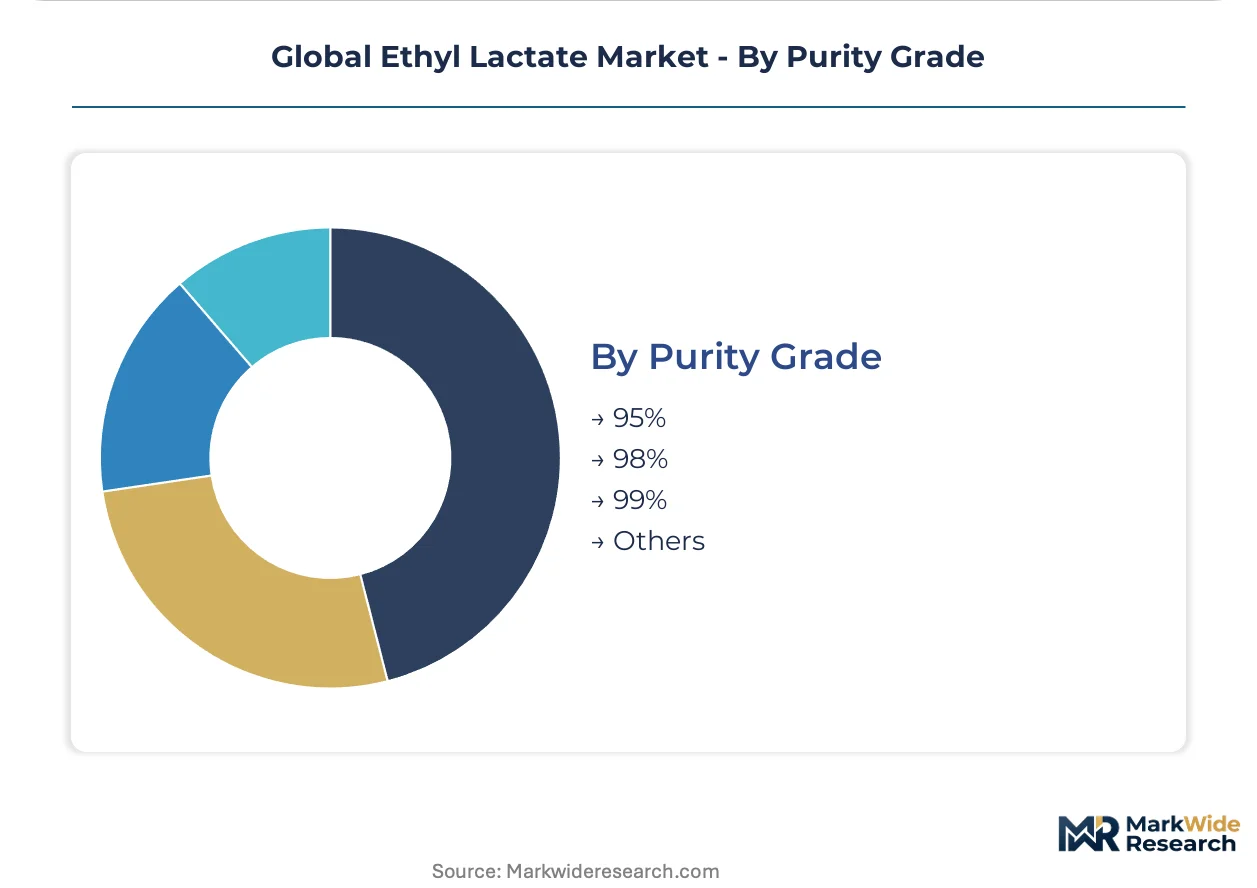
Purity Grade:
Application maturity separates established industrial grades from emerging pharmaceutical specifications, with supply concentration tightening at the highest purity levels.
- 95%:Standard technical grade serves industrial cleaning and coatings applications where residual water and ethanol are tolerable. Chinese fermentation-based producers in Shandong province dominate cost positioning for this specification.
- 98%:Intermediate purity bridges industrial and food-grade applications, with membrane filtration technology enabling cost-competitive production versus azeotropic distillation.
- 99%:Pharmaceutical-grade material requires molecular sieve dehydration and analytical documentation for residual impurities. German and Swiss excipient manufacturers prioritize suppliers with integrated continuous processing capabilities.
- Others:Custom specifications for semiconductor wet processing and electronic-grade applications command premium pricing with ultra-low metal ion content requirements.
95% grade dominates current volume. 99% grade is gaining share fastest as pharmaceutical green chemistry mandates tighten specification windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA VOC emission limits and REACH Annex XVII restrictions on reproductive toxicants are redirecting solvent procurement toward bio-based esters across manufacturing corridors in the United States, Germany, and China.
United States
Industrial cleaning operators in Ohio and Michigan face escalating compliance costs with halogenated solvents, accelerating substitution toward ethyl lactate in precision electronics and aerospace degreasing. EPA oversight of volatile organic compound emissions shapes solvent substitution patterns in metal finishing operations. Manufacturing clusters across the Midwest are reformulating ahead of 2025-2026 regulatory deadlines.
Germany
Pharmaceutical excipient manufacturers prioritize suppliers with integrated continuous processing capabilities for 99% purity grades. REACH registration requirements filter out non-compliant import streams, consolidating procurement among qualified fermentation-integrated producers. Industrial coatings formulators in North Rhine-Westphalia are building dedicated bio-based solvent blending capacity ahead of N-methylpyrrolidone restrictions.
China
Domestic fermentation capacity in Shandong and Henan provinces is lowering ethyl lactate production costs relative to petrochemical ester alternatives. SAMR enforces GB standards for food-contact chemicals, creating separate compliance pathways for domestic versus export-oriented producers. Food additive manufacturers in Guangdong province are expanding offtake for processed food exports to Southeast Asia.
Switzerland
Swissmedic oversight of pharmaceutical-grade materials tightens specification windows for residual impurities below 0.1%. Basel-headquartered multinationals now mandate supplier qualification through centralized global purchasing, replacing fragmented regional sourcing. Excipient manufacturers prioritize membrane filtration capabilities for water content below 0.05%.
India
Contract research and manufacturing organizations in Hyderabad and Ahmedabad are adopting green solvents for export-oriented pharmaceutical intermediates. CDSCO alignment with ICH guidelines accelerates qualification timelines for fermentation-derived excipients. Domestic lactic acid feedstock expansions in Gujarat and Maharashtra reshape regional cost curves.
Global Ethyl Lactate Market Vendor Landscape
Player mix skews toward fermentation-integrated specialists with captive lactic acid supply and diversified chemical conglomerates with solvent distribution networks. Three archetypes dominate: integrated biorefinery operators controlling upstream feedstock, pharmaceutical-grade purity specialists with EXCiPACT certification, and industrial solvent distributors with bulk logistics infrastructure. Capacity expansion and strategic partnerships represent the dominant competitive vectors, with membrane filtration technology licensing emerging as a secondary axis.
Among fermentation-integrated specialists, Corbion N.V., Godavari Biorefineries Ltd., and Vertec BioSolvents Inc. occupy positions defined by feedstock security and sustainability credentials. Corbion represents the European integrated platform archetype with lactic acid fermentation assets. Godavari Biorefineries exemplifies cane-sugar-derived feedstock economics against petrochemical rivals. Vertec BioSolvents sits within the bio-based formulation specialist tier, competing on verified biogenic carbon content rather than volume scale.
| Leading Market Players |
|---|
| Corbion N.V. |
| Merck KGaA |
| Godavari Biorefineries Ltd. |
| Henan Jindan Lactic Acid Technology Co., Ltd. |
| Musashino Chemical Laboratory Ltd. |
| Vertec BioSolvents Inc. |
| Galactic |
| Stepan Company |
| Archer-Daniels-Midland Company |
| Others |
Supply Flow & Price Mechanics
Petrochemical ester displacement by fermentation-based alternatives simultaneously redraws production geography toward Shandong and Henan provinces while compressing cost curves for commodity grades. This substitution dynamic concentrates pricing power among lactic acid-integrated operators capable of serving both industrial solvent buyers and pharmaceutical excipient manufacturers.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and commodity solvent tiers, with EXCiPACT and ISO 9001 documentation commanding substantial premia over technical grades. Three-tier pricing structure across premium, standard, and economy levels reflects purity gradients from 99% down to 95%, with volume scale and geographic delivery cost as secondary differentiation factors. Cost compression in the standard tier is intensifying because Chinese fermentation capacity expansions are flooding industrial solvent channels. Small-volume laboratory buyers exhibit highest price sensitivity, while Basel-headquartered pharmaceutical multinationals prioritize supply security over unit cost.
Supply Chain Analysis
Lactic acid feedstock security functions as the dominant chokepoint, with captive fermentation capacity determining supplier viability across all grade tiers. Production gravity centers on China, the Netherlands, and India, where corn and cane sugar processing infrastructure anchors upstream supply. Raw material flows draw from agricultural commodity markets, ethanol refining networks, and molecular sieve dehydration equipment. Single-source vulnerability runs through Shandong province fermentation clusters, where concentrated capacity creates disruption exposure. Distribution runs through bulk chemical distributors for industrial grades and direct supplier relationships for pharmaceutical specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs durable defensive moats in this market, as EXCiPACT and FDA Type II Drug Master File qualification timelines extend 18-24 months and effectively cap new entrant inflows into premium tiers.
For Market Incumbents: Shield pharmaceutical-grade margin pools by accelerating membrane filtration technology deployment and securing long-term cane sugar supply contracts in Maharashtra and Gujarat. Emerging Chinese fermentation operators threaten commodity solvent pricing, making backward integration into lactic acid feedstock the critical defensive lever for European and North American producers.
For New Entrants and Emerging Players: EXCiPACT certification fast-track programs in India and Switzerland open accessible pathways into pharmaceutical excipient supply chains without competing directly against integrated biorefinery scale. Semiconductor wet processing represents the most penetrable white-space target, where 99.9% purity specifications and ultra-low metal ion requirements remain undersupplied. Position through technical service partnerships with advanced packaging facilities in Taiwan and South Korea.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fermentation-integrated mid-caps with captive feedstock and existing pharmaceutical qualifications. Long-term viability over the coming decade hinges on biogenic carbon verification capabilities and continuous processing technology ownership. Watch for inflection when REACH Annex XVII restrictions on N-methylpyrrolidone trigger accelerated industrial coatings reformulation across Benelux manufacturing corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Feedstock | Captive fermentation capacity in Shandong and Henan secures cost positioning against petrochemical rivals. |
| Continuous Processing Technology Deployment | Membrane filtration systems achieve water content below 0.05% without energy-intensive azeotropic distillation. |
| EXCiPACT Certification Investment | Pharmaceutical-grade qualification opens access to Basel and Boston headquarters procurement consolidation. |
| Long-term Supply Agreement with Cane Sugar Processors | Godavari Biorefineries demonstrates feedstock economics advantages through Maharashtra agricultural partnerships. |
| Semiconductor Grade Purity Development | 99.9% specification capabilities target photoresist stripping demand from advanced packaging facilities. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fermentation plant managers, pharmaceutical procurement leads, coatings formulators, and distribution channel partners; and secondary validation through customs trade databases, SEC filings from listed chemical producers, ECHA REACH registration records, and GB standards documentation from SAMR. Bottom-up capacity modeling across Shandong, Henan, and Gujarat production sites triangulated against top-down demand segmentation by end-use industry and purity grade.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented approaches spanning solvent grade tier, end-use industry vertical, regional production hub concentration, and pharmaceutical certification status. CAGRs emerged from iterative reconciliation between feedstock cost curve projections and substitution elasticity estimates for halogenated solvent displacement under EPA VOC compliance deadlines. Key inputs included agricultural commodity price volatility indices and regulatory timeline assumptions for REACH Annex XVII implementation.
Decision-makers should treat outputs as directional under sustained pharmaceutical green chemistry mandates and stable fermentation feedstock economics; material deviation in corn or cane sugar pricing would warrant model refresh. Practitioners should keep alternative scenarios live as EPA enforcement intensity and EU Green Deal procurement rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Nitroglycerin Market
Solvents
Hexylene Glycol Market
Solvents
Meta-Xylene Market
Solvents
Piperylene Market
Solvents
1, 1-Difluoroethane Market
Solvents
Hydrocarbon Solvents Market
Solvents
Tetraethyl Benzene Market
Solvents
Methyl Diethanolamine Market
Solvents
Ionic Liquids Market
Solvents
2 - Ethyl Anthraquinone Market
Solvents
Mesitylene Market
Solvents
Trifluoroethanol Market
Solvents
Hydrofluoroether Market
Solvents
Methyl Formate Market
Solvents
Toluene Derivatives Market
Solvents
Alpha-Methylstyrene Market