
 North America Tomato Seed Market | 2026-2036
North America Tomato Seed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tomato Seed Market Analytics
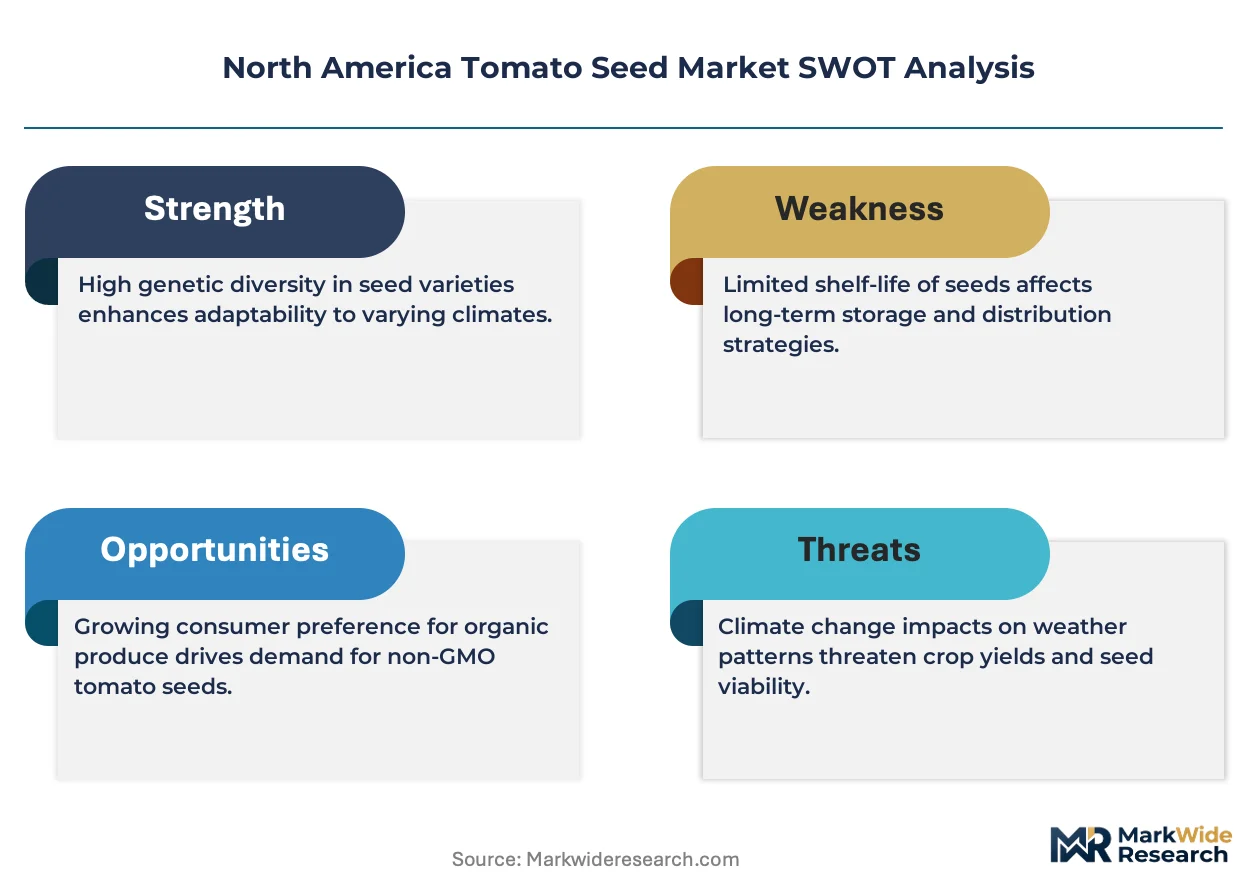
Subscription-based trait licensing is hardening as the dominant commercial model in the North America tomato seed market. Bayer AG leverages its vegetable seeds division to anchor premium hybrid portfolios across California and Florida growing regions. Syngenta Group sustains R&D intensity in disease-resistant germplasm, competing directly with BASF SE's specialized tomato genetics programs. Groupe Limagrain differentiates through regional breeding stations that adapt varieties to Mexican greenhouse conditions.
Tomato seeds constitute sexually propagated planting material containing embryonic tissue, nutrient reserves, and protective seed coats, typically processed through priming, pelleting, or film-coating to enhance germination uniformity and mechanical sowing compatibility. Their primary commercial purpose is to establish genetically standardized tomato crops for fresh market and processing supply chains. Hybrid seeds command the dominant margin pool due to proprietary trait stacks and grower lock-in, while heirloom seeds occupy premium niche channels targeting specialty retailers and restaurant procurement. Greenhouse end-use represents the fastest-expanding demand segment as controlled-environment operators in the United States and Mexico seek determinate and indeterminate varieties optimized for high-wire cultivation systems.
The USDA's Plant Variety Protection Office and Mexico's National Service for Agri-Food Health and Safety (SENASICA) jointly shape seed certification, phytosanitary clearance, and cross-border varietal approval pathways between the two countries. EPA registration requirements for seed treatment chemistries and state-level organic certification standards in California and Washington further constrain product formulation and market access. Stakeholders must monitor evolving federal biotechnology disclosure rules and state pollinator protection policies that could restrict neonicotinoid-based seed coatings across major tomato-producing jurisdictions.
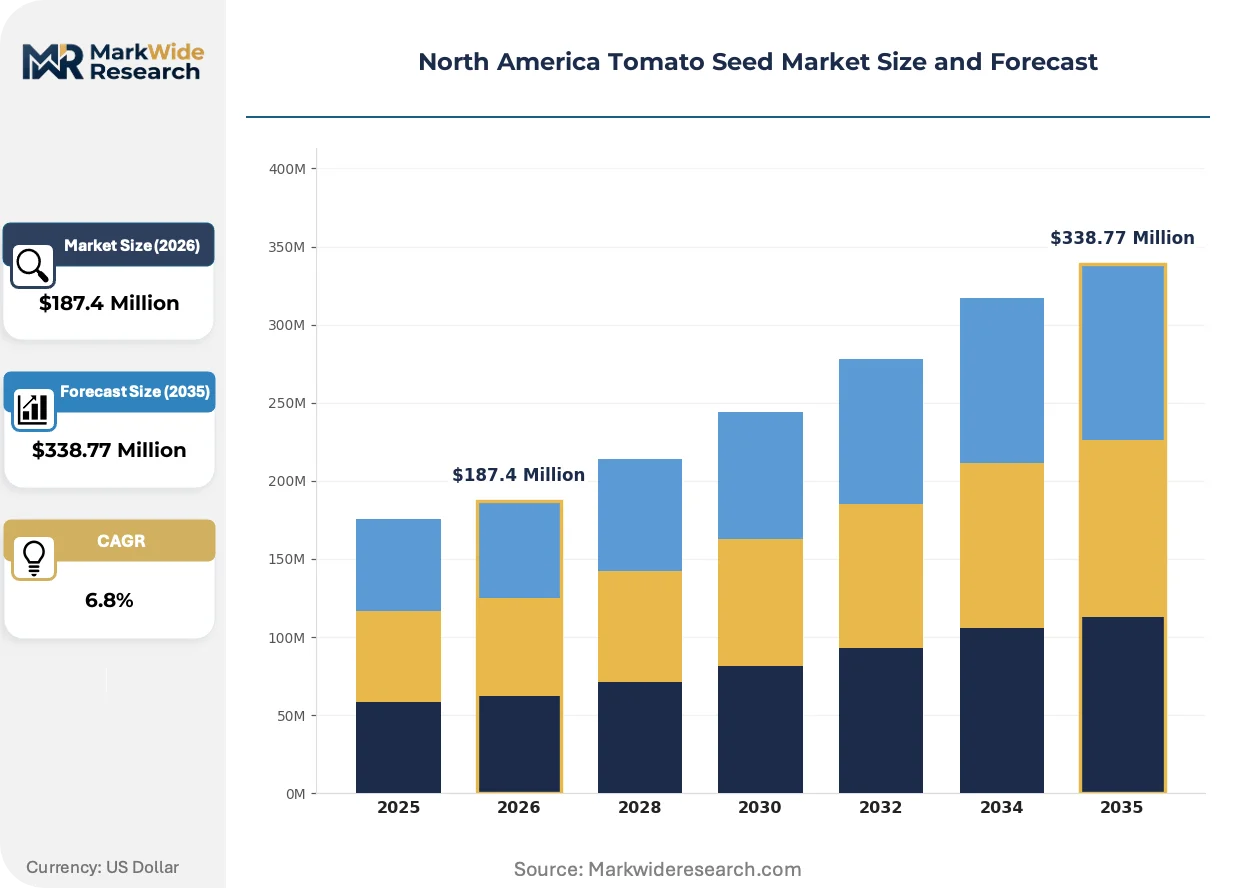
Market Dynamics
Greenhouse operators across the United States and Mexico are consolidating procurement around proprietary hybrid portfolios, compressing breeding timelines and locking in trait-licensing relationships with major seed developers.
Growth Catalysts
- USDA Plant Variety Protection Act:This framework accelerates investment in proprietary germplasm development by securing intellectual property rights for novel hybrid varieties, incentivizing private R&D expenditure.
- Controlled-environment agriculture:Greenhouse operators in California's Central Valley and Mexico's Sinaloa corridor are scaling year-round tomato production, creating sustained demand for determinate and indeterminate seed varieties optimized for high-wire systems.
- Film-coating and priming technologies:Advanced seed processing methods enhance germination uniformity and mechanical sowing compatibility, reducing labor costs for large-scale greenhouse operators.
Market Restraints
- Hybrid seed cost structure:Proprietary trait stacks command premium pricing that squeezes margin for mid-scale greenhouse operators, particularly in Mexico's emerging production zones.
- Input concentration risk:Three seed developers control dominant hybrid portfolios, creating supply vulnerability for growers dependent on specific disease-resistant germplasm lines.
- Neonicotinoid regulatory friction:EPA registration requirements and state-level pollinator protection policies in California and Washington constrain seed treatment chemistries, limiting formulation options.
Strategic Opportunities
- Heirloom niche channels:Specialty retailers and restaurant procurement networks in California and Florida represent underpenetrated demand for premium non-hybrid varieties with distinct flavor profiles.
- Organic certification standards:State-level organic frameworks in Washington and California create regulatory tailwinds for untreated seed formulations and biological coating alternatives.
- Cross-border varietal approval:Streamlined pathways between USDA's Plant Variety Protection Office and Mexico's SENASICA reduce time-to-market for new hybrid releases across both jurisdictions.
Industry Challenges
- Phytosanitary compliance timelines:Cross-border seed shipments between the United States and Mexico face inspection bottlenecks at SENASICA clearance points, delaying planting schedules.
- Germplasm licensing complexity:Stacked trait royalties and sublicensing agreements between seed developers create opaque cost structures for greenhouse operators negotiating multi-year supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tomato Seed Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Heirloom Seeds, Open-Pollinated Seeds, Grafting Seeds End Use: Agricultural Production, Home Gardens, Greenhouses, Commercial Cultivation Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesale Distributors Packaging Type: Bulk Packaging, Retail Packs, Seed Tapes, Eco-friendly Packs |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Groupe Limagrain, Rijk Zwaan Zaadteelt en Zaadhandel B.V., Enza Zaden, PanAmerican Seed, Sakata Seed Corporation, Jung Seed Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tomato Seed Market Evolving Landscape
Gene editing platforms and digital phenotyping tools are compressing breeding cycles while regulatory frameworks on both sides of the border adapt to accelerated varietal approval timelines.
CRISPR-based gene editing is overtaking traditional marker-assisted selection for disease resistance traits in tomato germplasm development. Greenhouse operators in California and Florida are adopting CRISPR-derived varieties at accelerating pace as seed developers commercialize powdery mildew and tomato spotted wilt virus resistance. This technology is overtaking conventional backcrossing methods by reducing trait introgression timelines from eight years to three.
EPA registration requirements for seed treatment chemistries are tightening under evolving federal biotechnology disclosure rules. The industrial consequence is a forced migration toward biological coating agents and non-neonicotinoid alternatives for greenhouse tomato seed formulations. California and Washington state regulators are most affected, with organic certification standards now prohibiting synthetic seed treatments across major production counties.
Subscription-based trait licensing is displacing perpetual seed purchase agreements among large greenhouse operators. Major controlled-environment facilities in Mexico's Sinaloa corridor are negotiating multi-year access contracts that bundle germplasm, technical support, and trait upgrades. This model is most visible in high-wire tomato operations exceeding fifty hectares, where growers prioritize varietal refresh cycles over capital ownership of seed inventory.
North America Tomato Seed Market Segmentation
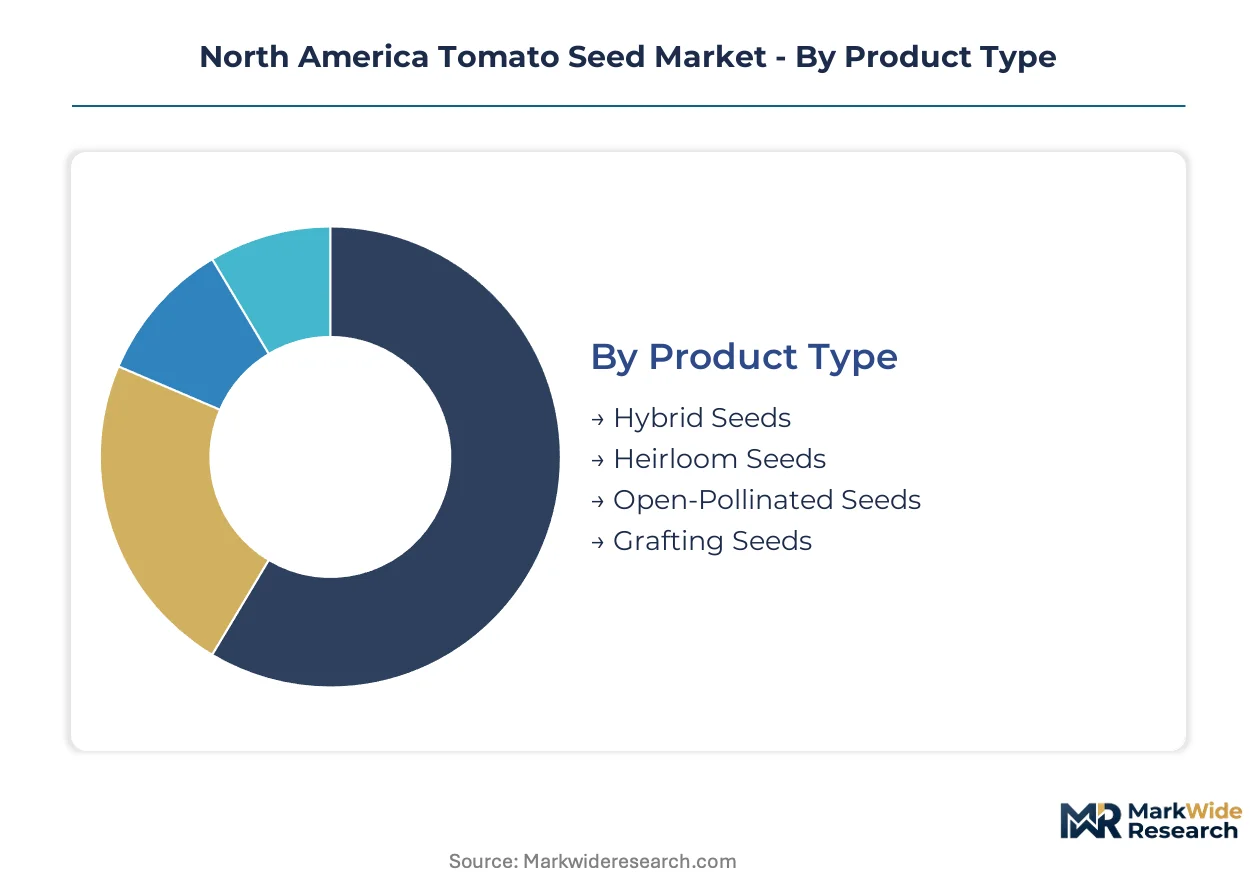
Seed procurement patterns across North America stratify sharply by production scale and technical sophistication. Greenhouse operators demand precision-engineered hybrids with trait licensing, while home gardeners and smallholders prioritize accessibility and heritage genetics.
Product Type:
Variety replacement cycles accelerate as CRISPR-edited germplasm shortens trait introgression timelines from eight years to three.
- Hybrid Seeds:Proprietary trait stacks combine disease resistance, yield uniformity, and shelf-life extension through controlled pollination of inbred parental lines. California's Central Valley greenhouse operators lock in multi-year licensing agreements with developers like Bayer and Syngenta, prioritizing powdery mildew and tomato spotted wilt virus resistance. Premium pricing reflects R&D amortization and grower lock-in effects.
- Heirloom Seeds:Open-pollinated varieties preserve genetic diversity through generational seed-saving, delivering distinct flavor profiles and morphological characteristics lost in hybrid standardization. Demand concentrates in California and Florida specialty retail channels supplying farm-to-table restaurants and organic CSA networks. Premium positioning offsets lower yields and disease susceptibility.
- Open-Pollinated Seeds:Genetically stable varieties breed true-to-type without controlled crossing, serving cost-conscious agricultural producers in Mexico's Sinaloa corridor.
- Grafting Seeds:Rootstock-scion combinations confer soil-borne disease tolerance and vigor advantages for intensive greenhouse systems.
Volume placements concentrate in Hybrid Seeds; the faster expansion belongs to Heirloom Seeds.
End Use:
Production environment dictates varietal specification intensity, with controlled-environment facilities demanding the most sophisticated germplasm engineering.
- Greenhouses:High-wire cultivation systems in California's Central Valley and Mexico's Sinaloa corridor require determinate and indeterminate varieties optimized for year-round production, light interception, and labor-efficient harvesting. Film-coated seeds with priming treatments ensure germination uniformity for mechanical sowing. Trait licensing subscriptions displace perpetual purchase agreements among operators exceeding fifty hectares.
- Agricultural Production:Open-field growers in Florida and Baja California prioritize heat-set capability, crack resistance, and mechanical harvest compatibility for processing and fresh-market supply chains. Seasonal planting windows compress procurement cycles.
- Commercial Cultivation:Mid-scale operations blend greenhouse and field techniques, creating hybrid demand for transitional climate management.
- Home Gardens:Small-plot consumers in urban California and Pacific Northwest markets favor compact determinate varieties and heritage collections through retail and digital channels.
Revenue concentration sits with Greenhouses; Agricultural Production captures the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and inventory velocity needs across the procurement spectrum.
- Direct Sales:Seed developers maintain dedicated agronomist relationships with major greenhouse operators, bundling germplasm access with technical support and trait upgrade pathways. Multi-year contracts lock in volume commitments and pricing structures for California and Mexico's largest controlled-environment facilities.
- Wholesale Distributors:Regional agricultural supply houses aggregate inventory for mid-scale growers across Texas, Arizona, and northern Mexico, offering credit terms and localized delivery logistics.
- Online Platforms:Digital procurement channels serve dispersed home gardeners and small commercial operators with heritage variety access and subscription replenishment.
- Retail Stores:Big-box garden centers and independent nurseries stock consumer-oriented packet sizes for seasonal planting demand.
Transaction value clusters in Direct Sales; Online Platforms are climbing the fastest.
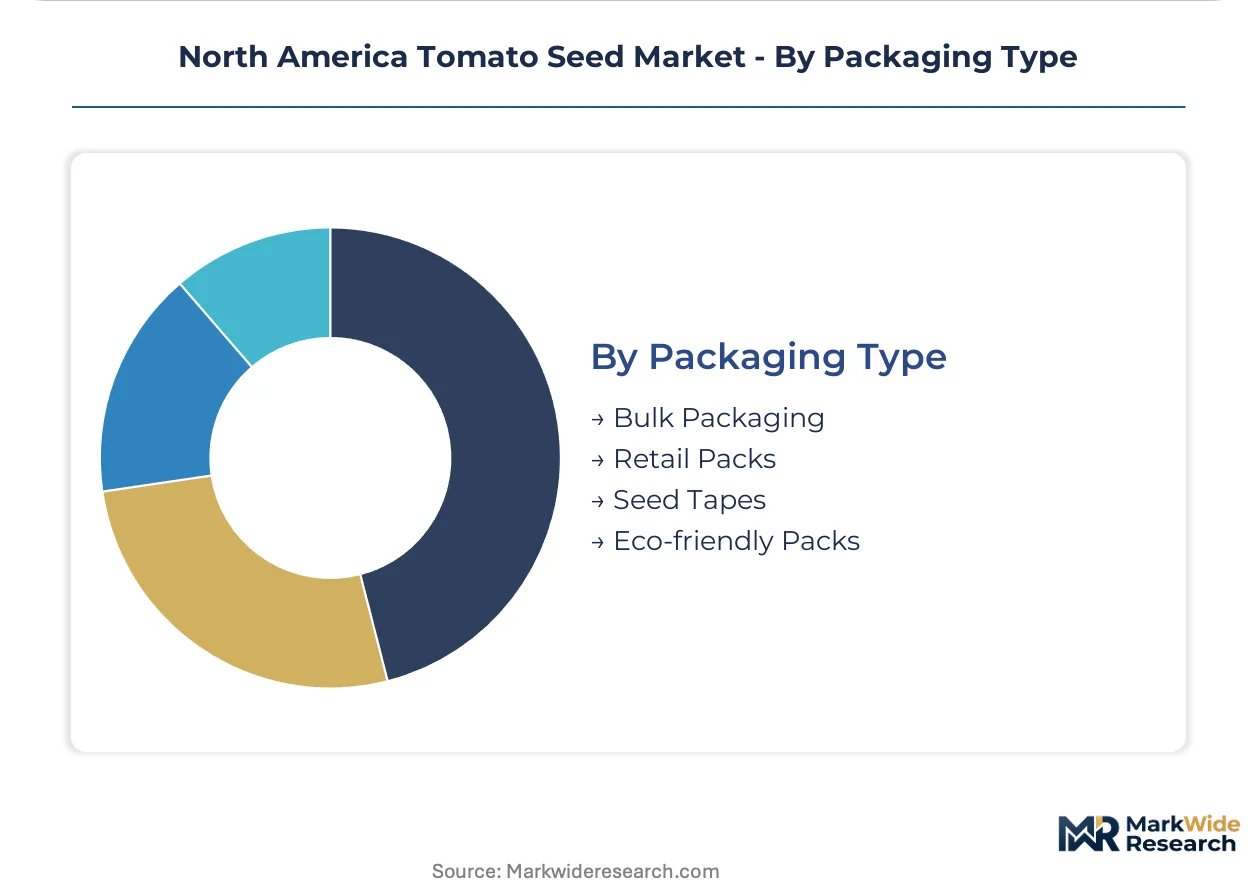
Packaging Type:
Packaging specification aligns with mechanization level, sustainability mandates, and inventory turnover velocity.
- Bulk Packaging:Large-volume containers serve greenhouse operators sowing hundreds of thousands of seeds annually, minimizing per-unit handling costs and enabling custom priming and pelleting workflows. California's largest controlled-environment facilities specify hermetically sealed bulk units with humidity indicators.
- Eco-friendly Packs:Compostable and recyclable materials address organic certification requirements in Washington and California, where state-level frameworks prohibit synthetic packaging components for certified operations.
- Retail Packs:Branded consumer units with germination guarantees dominate home garden channels.
- Seed Tapes:Pre-spaced embedded seeds eliminate thinning labor for precision gardeners.
Shipment tonnage favors Bulk Packaging; Eco-friendly Packs gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley anchors North American tomato seed demand, with Fresno and Merced counties hosting the continent's densest concentration of controlled-environment greenhouse operations.
United States
California's Central Valley and Florida's Immokalee region drive hybrid seed procurement for year-round production. The USDA's Plant Variety Protection Office secures intellectual property for novel varieties, accelerating private R&D investment. Fresno County greenhouse operators now contract directly with seed developers for multi-year trait licensing agreements.
Mexico
Sinaloa's Culiacán-Mazatlán corridor scales high-wire tomato cultivation, creating sustained demand for determinate and indeterminate varieties. SENASICA phytosanitary clearance requirements shape cross-border seed shipment timelines. Guanajuato's Bajío region emerges as a secondary greenhouse cluster, with operators negotiating subscription-based germplasm access.
Canada
Leamington's greenhouse district in southwestern Ontario concentrates protected tomato cultivation, sourcing hybrid varieties adapted to lower-light conditions. Health Canada and the Pest Management Regulatory Agency regulate seed treatment chemistries and biotechnology disclosure. The region's operators prioritize disease-resistant germplasm for extended winter production cycles.
Florida
Immokalee and Palmetto-Ruskin districts sustain open-field and greenhouse tomato production for eastern US fresh markets. State-level pollinator protection policies constrain neonicotinoid seed coating formulations. Miami-Dade greenhouse operators experiment with CRISPR-derived varieties for tropical pest resistance.
Texas
Winter Garden and Lower Rio Grande Valley districts supply processing and fresh-market tomatoes, with seed procurement concentrated in pre-planting windows. The Texas Department of Agriculture administers organic certification standards affecting untreated seed demand. Pharr-McAllen greenhouse operators import Mexican-adapted varieties for cross-border production integration.
North America Tomato Seed Market Competitive Landscape
Capital-heavy integrated seed developers compete with specialized germplasm licensors across North American tomato markets. Three multinational agrochemical conglomerates control dominant hybrid portfolios, while regional breeding stations and independent specialists occupy niche adaptation segments. Strategic archetypes separate integrated R&D-to-distribution platforms, regional variety specialists, and open-pollinated heritage curators. Competitive dynamics center on trait licensing subscription models and accelerated varietal approval pathways.
Within the integrated platform tier, Bayer AG and BASF SE anchor proprietary hybrid development through vegetable seeds divisions with established California and Mexico breeding infrastructure. Syngenta Group occupies a comparable position, sustaining R&D intensity in disease-resistant germplasm. Groupe Limagrain represents the regional adaptation archetype, with breeding stations targeting Mexican greenhouse conditions. Rijk Zwaan and Enza Zaden exemplify specialized Dutch-based vegetable genetics firms competing through regional variety portfolios.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Groupe Limagrain |
| Rijk Zwaan Zaadteelt en Zaadhandel B.V. |
| Enza Zaden |
| PanAmerican Seed |
| Sakata Seed Corporation |
| Jung Seed Company |
| Others |
Value Network & Pricing Analysis
Parental line development costs cascade through hybrid seed pricing tiers, with R&D amortization in Bayer's and Syngenta's California breeding stations concentrating premium value capture among greenhouse operators exceeding fifty hectares.
Pricing Analysis
Yield-per-hectare guarantees anchor value-based pricing for subscription trait licensing. Three-tier pricing structure across premium, standard, and economy levels reflects germplasm sophistication, with CRISPR-edited disease resistance commanding top tier. Cost compression in economy-tier open-pollinated varieties is intensifying because Mexican Sinaloa corridor growers face margin pressure from hybrid royalty stacks. Mid-scale greenhouse operators show highest price sensitivity; integrated platforms with captive breeding capacity exhibit lowest.
Supply Chain Analysis
Seed treatment returns and coating reformulation flows create reverse-logistics complexity as California and Washington organic certification standards prohibit synthetic chemistries. Production concentrates in the Netherlands, the United States, and Mexico, with Dutch genetics firms Rijk Zwaan and Enza Zaden anchoring germplasm innovation. Raw material dependencies include proprietary inbred parental lines, biological coating agents, and priming substrates. Single-source vulnerability runs through three multinational developers controlling dominant hybrid portfolios. Distribution runs through direct developer relationships with major greenhouse operators, supplemented by regional agricultural supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proprietary germplasm development timelines stretching eight years to three with gene editing have not eliminated supply scarcity, as SENASICA clearance bottlenecks and stacked trait licensing complexity prop pricing power for integrated seed developers.
For Market Incumbents: To counter CRISPR-enabled breeding cycle compression from specialized Dutch genetics firms, Bayer and Syngenta should deepen backward integration into Mexican Sinaloa corridor breeding infrastructure and secure exclusive multi-year subscription contracts with operators exceeding fifty hectares. Certification investment in Washington and California organic-compliant coating formulations locks out reformulation-dependent competitors. For New Entrants and Emerging Players: The price-point gap between premium hybrid licensing and economy open-pollinated seeds creates entry space for biological coating specialists targeting mid-scale greenhouse operators in Mexico's emerging Guanajuato Bajío cluster. Heirloom seed curation for California farm-to-table restaurant procurement networks offers the most penetrable white-space, with direct digital subscription replenishment as the go-to-market angle. For Investors and Strategic Acquirers: Accelerating adoption of CRISPR-derived powdery mildew resistance varieties by California Central Valley operators is the leading indicator that gene editing platforms will displace marker-assisted selection within the projection horizon. Long-term viability favors vertically integrated developers with captive Mexican breeding capacity and SENASICA pre-clearance relationships. Monitor EPA neonicotinoid restriction enforcement intensity as inflection signal for biological coating agent demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mexican Breeding Infrastructure | Captive Sinaloa corridor development capacity reduces SENASICA clearance dependency for Bayer and Syngenta. |
| Biological Coating Agent Certification | Washington and California organic compliance locks in regulatory-mandated formulation switching. |
| Heirloom Germplasm Curation Partnership | California specialty retail channel access captures restaurant procurement network premiums. |
| Cross-Border Varietal Approval Streamlining | USDA-SENASICA pathway acceleration reduces time-to-market for CRISPR-edited releases. |
| Subscription Licensing Platform Expansion | Multi-year trait access contracts convert capital expenditure to recurring revenue for integrated developers. |
Research Methodology
Independent corroboration across seed developer R&D directors, SENASICA phytosanitary inspectors, and California greenhouse procurement managers underwrites the qualitative findings. Primary interviews with breeding station agronomists, trait licensing contract negotiators, and organic certification auditors combined with secondary validation from USDA Plant Variety Protection Office filings, SENASICA clearance records, and California Department of Food and Agriculture organic framework documentation. Bottom-up volume triangulation across greenhouse operator seed procurement volumes and top-down value aggregation from developer licensing revenue streams were reconciled.
Comparable-period anchoring to historical hybrid adoption curves and CRISPR commercialization timelines structured the projection horizon. Segmentation modeling spanned product type, end-use environment, distribution channel, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation of breeder investment intensity and controlled-environment agriculture expansion rates. Industry-specific forecast inputs included SENASICA clearance velocity assumptions and EPA seed treatment chemistry registration pathway timelines.
Inputs from developer licensing disclosure patterns and greenhouse operator procurement records were available through the study window; gaps in precise royalty stacking arrangements introduce uncertainty bands around margin structure estimates. Forecasts reflect documented assumptions regarding gene editing regulatory acceptance and cross-border varietal approval harmonization. Practitioners should monitor EPA pollinator protection policy enforcement and SENASICA digital clearance platform deployment for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Forage Sorghum Seed Market
Seeds
North America Maize Seed Treatment Market
Seeds
Philippines Seed Market
Seeds
North America Quinoa Seeds Market
Seeds
South America Chia Seeds Market
Seeds
Chamomile Seeds Market
Seeds
Buckwheat Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Pasture Seeds Market
Seeds
Myanmar Rice Seed Market
Seeds
Tallow Tree Seed Market
Seeds
Psyllium Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
South and Southeast Asia Seed Market
Seeds
Caraway Seeds Market
Seeds
Global Packaged Chia Seeds Market