
 Musical Instruments Market | 2026-2036
Musical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Musical Instruments Market Intelligence
CITES regulations governing the trade of endangered tonewoods like rosewood is recalibrating the material sourcing costs for acoustic instrument manufacturers. C.F. Martin & Co. Inc. leverages its brand heritage while pioneering the use of alternative, sustainable materials. Yamaha Corporation sustains a dominant market position through its extensive product portfolio spanning acoustic and electronic categories. Fender Musical Instruments Corporation differentiates through its focus on iconic American-made electric guitars and amplifiers.
Musical instruments are devices engineered to produce sound through various physical mechanisms, including the vibration of strings, air columns, or membranes. Their primary commercial purpose is to facilitate artistic expression, education, and entertainment. The string instruments category, including guitars and violins, represents a mature but high-value segment. Electronic instruments, driven by innovations in music production applications, show significant growth potential.
Compliance with the EU's RoHS directive on hazardous substances is mandatory for electronic instrument makers selling into Europe. In the United States, consumer product safety standards overseen by the CPSC affect materials used in instruments intended for children. Navigating the complex landscape of intellectual property for digital sounds and software integrations is a critical decision point for manufacturers of electronic instruments.
Market Dynamics
The musical instruments market is defined by a fundamental tension between the preservation of traditional artisanship and the rapid integration of digital technologies. This dynamic is intensified by global regulations like CITES, which constrain material sourcing for acoustic instruments while innovation in software accelerates.
Growth Catalysts
- Expanded Music Education:Government initiatives promoting arts education in public schools, particularly in markets like India, are creating a sustainable pipeline of new student musicians and driving demand for entry-level instruments.
- Therapeutic Music Applications:The integration of music-based interventions in healthcare and corporate wellness programs is opening new, non-traditional channels for instruments like keyboards and percussion used in therapeutic settings.
- Sustainable Material Innovation:Research into alternative materials, including high-pressure laminates and thermally-treated domestic woods, provides a viable path for manufacturers to reduce dependency on restricted tonewoods and appeal to environmentally conscious consumers.
Market Restraints
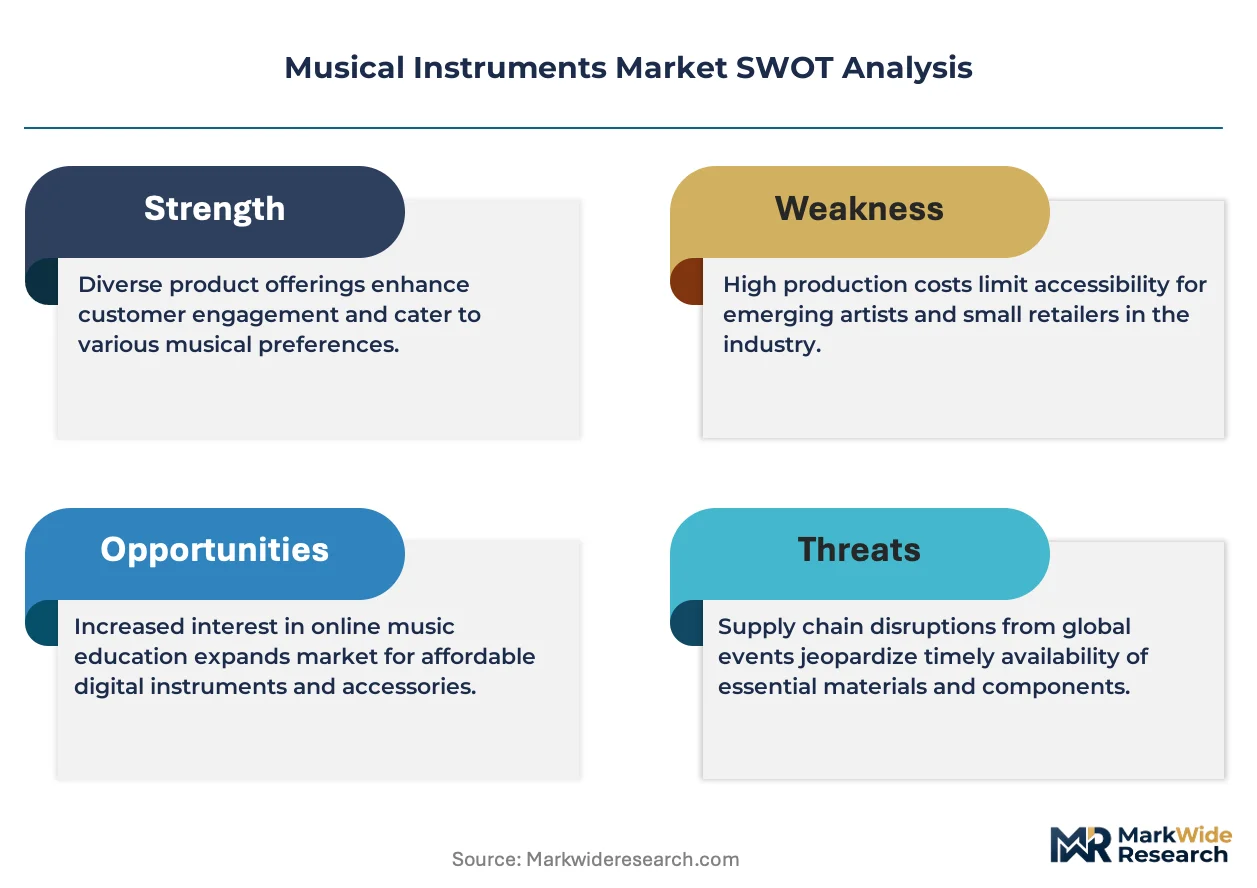
- Tonewood Scarcity and Cost:CITES trade restrictions on traditional materials like rosewood and ebony create significant input cost volatility and supply chain uncertainty for manufacturers of high-end acoustic and string instruments.
- Digital Substitution:The increasing sophistication and accessibility of digital audio workstations (DAWs) and virtual instrument software (VSTs) present a potent substitution threat to physical electronic and acoustic instruments.
- Component Supply Concentration:A heavy reliance on a few East Asian suppliers for critical electronic components, such as semiconductors and processors, exposes manufacturers of digital pianos, synthesizers, and effects pedals to geopolitical and logistical risks.
Strategic Opportunities
- Emerging Market Penetration:A growing middle class in countries like China and Brazil with increasing disposable income and exposure to global music trends represents a significant opportunity for both entry-level and aspirational instrument brands.
- Hybrid Instrument Development:There is a clear market opening for instruments that merge acoustic sound generation with digital capabilities, such as acoustic guitars with built-in USB audio interfaces or traditional pianos with silent-play technology.
- Direct-to-Consumer Channels:Online sales platforms empower boutique and specialized instrument makers to bypass traditional retail gatekeepers, build direct customer relationships, and access a global niche audience for custom and high-end products.
Industry Challenges
- Intellectual Property Complexity:Navigating the intricate licensing for digital sound libraries, embedded software, and patented synthesis techniques is a major operational hurdle for developers of electronic instruments and music production hardware.
- Artisan Skill Scarcity:The declining population of highly skilled luthiers and craftspeople trained in traditional instrument-making techniques poses a long-term threat to the production of premium, handcrafted acoustic and orchestral instruments.
- Multi-regional Compliance:Manufacturers of electronic instruments must manage a complex web of regulations, including the EU's RoHS directive on hazardous substances and FCC standards for electromagnetic interference in the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Musical Instruments Market |
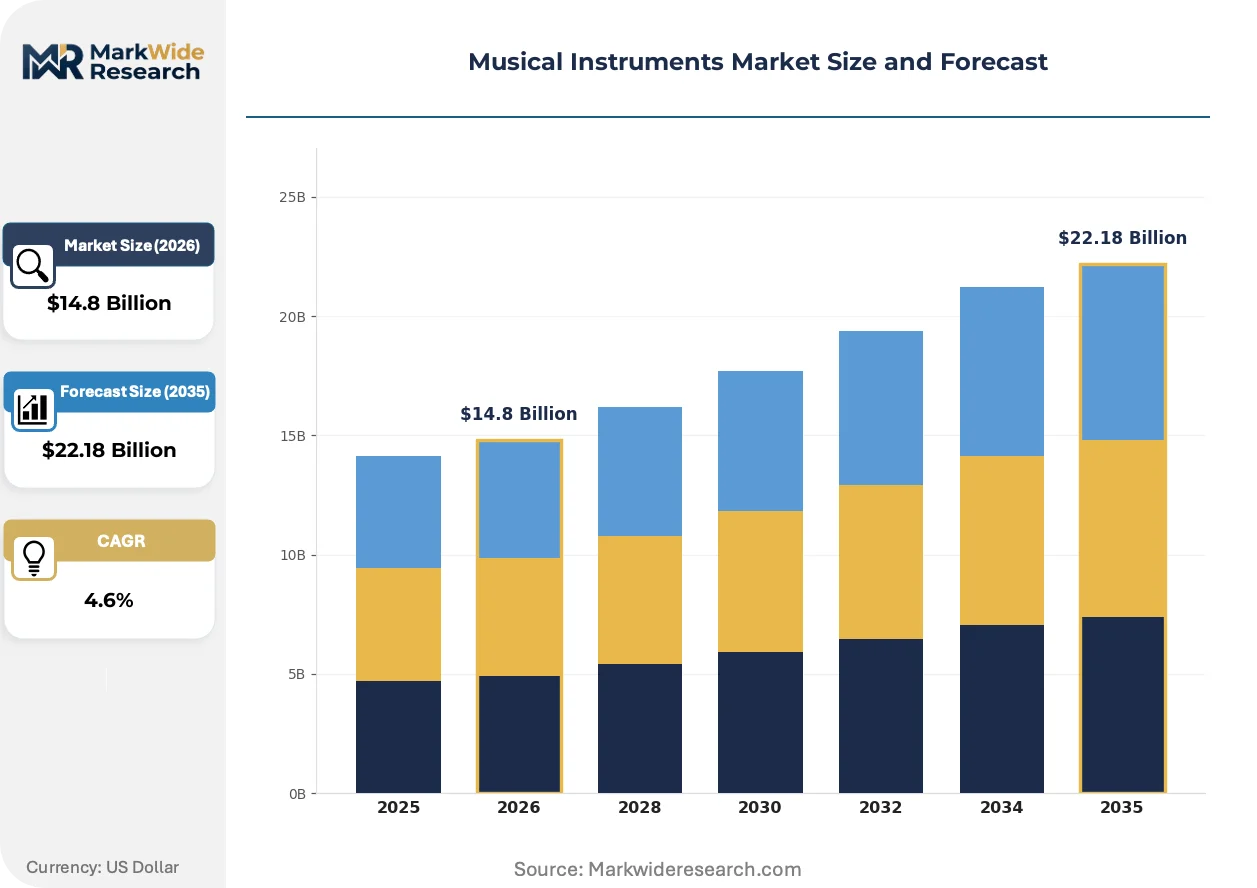
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Instrument Type: String, Percussion, Keyboard, Wind, Electronic Application: Live Performance, Music Production, Education, Therapy, Recreation End User: Professional Musicians, Music Educators, Students, Recording Studios, Hobbyists Sales Channel: Specialty Stores, Online Retailers, Music Schools, Concert Venues, Rental Services |
| Companies Covered | Gibson Brands, Steinway & Sons, Yamaha Corporation, C.F. Martin & Co. Inc., Casio Computer Co., Ltd., Roland Corporation, Kawai Musical Instruments, Guangzhou Pearl River Piano Group Co. Ltd., Fender Musical Instruments Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Musical Instruments Market Strategic Shifts & Innovations
The market is bifurcating into two distinct ecosystems: one centered on heritage, acoustic authenticity, and material science, and another driven by digital integration, software-defined sound, and mobile music creation. This split influences everything from product design to distribution strategy for all manufacturers.
Advanced composite materials, including carbon fiber and various high-pressure laminates, serve as engineered alternatives to traditional tonewoods. Both mass-market producers and specialized luthiers are adopting these materials for their consistency, durability, and resistance to environmental changes. This adoption is rewriting the industry's historical reliance on a narrow and increasingly regulated portfolio of exotic woods for achieving specific acoustic properties.
The Convention on International Trade in Endangered Species (CITES) directly governs the cross-border movement of materials like rosewood, a cornerstone of acoustic guitar manufacturing. This regulatory pressure is forcing a fundamental reassessment of supply chains and prompting significant investment in material traceability and alternative sourcing. The acoustic string instrument segment, particularly guitars and members of the violin family, is most affected and is responding by promoting instruments built from certified or non-restricted woods.
A behavioral shift toward self-contained home production, often termed the "bedroom producer" movement, is altering demand patterns for recording equipment. This trend de-emphasizes large, expensive studio hardware in favor of compact, versatile, and affordable devices like USB microphones, audio interfaces, and MIDI controllers. This change is most visible in North American and European markets, where platforms like YouTube and TikTok provide a direct distribution channel for independently produced music.
Musical Instruments Market Segmentation
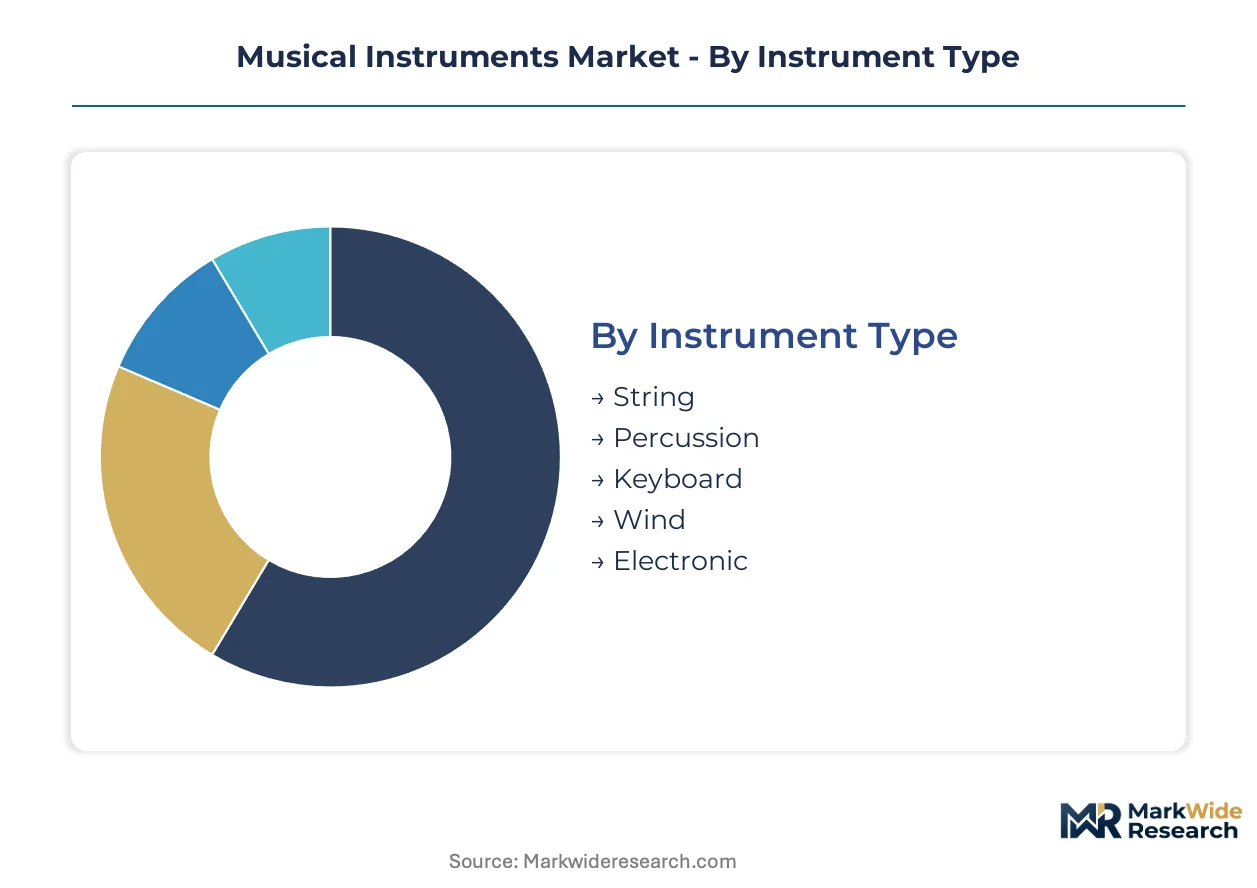
Market segmentation clarifies distinct user needs and purchasing behaviors, enabling manufacturers to tailor product development and distribution strategies. Understanding these segments helps companies identify specific growth opportunities and address diverse consumer demands across the musical instruments landscape.
Instrument Type:
The musical instruments market spans a wide spectrum from highly standardized mass-produced items to bespoke, artisanal creations within each instrument type.
- Electronic:These instruments generate sound through digital or analog circuitry, often incorporating synthesizers, digital pianos, and drum machines. Demand concentrates in music production studios and home recording setups, driven by innovation in software integration.
- String:This category includes guitars, violins, cellos, and basses, producing sound through vibrating strings. This segment is a high-value category, with demand concentrating among professional musicians and students in established music education programs.
- Percussion:Instruments like drums, cymbals, and xylophones create sound through striking or shaking.
- Keyboard:Acoustic pianos, organs, and accordions fall into this category, relying on keys to produce sound.
- Wind:Flutes, clarinets, saxophones, and trumpets are examples of wind instruments, where sound is produced by vibrating air columns.
Most installed capacity flows through String instruments. Expansion is steepest in Electronic instruments.
Application:
Application categories delineate the primary functional contexts where instruments are deployed, ranging from professional stages to educational settings.
- Education:Instruments utilized in schools, private lessons, and academic music programs to teach musical theory and performance. This application sees significant demand from government initiatives promoting arts education in countries like India.
- Music Production:Instruments primarily used in recording studios, home studios, and for creating original musical compositions. The "bedroom producer" movement in North American and European markets drives demand for versatile devices.
- Live Performance:Instruments designed and used for concerts, gigs, and public musical events.
- Therapy:Instruments integrated into healthcare and wellness programs for therapeutic interventions.
- Recreation:Instruments purchased for personal enjoyment, casual playing, and hobbyist activities.
Music production applications drive significant revenue. Education applications are gaining traction across emerging markets.
End User:
End-user segmentation reveals distinct purchasing patterns influenced by skill level, professional requirements, and recreational intent.
- Hobbyists:Individuals who play instruments for personal enjoyment, often without formal training or professional aspirations. Demand from this segment is concentrating in markets like China and India, fueled by increasing disposable income.
- Students:Individuals enrolled in music lessons, schools, or academic programs learning to play an instrument. Government initiatives in public schools create a sustainable pipeline of new student musicians, driving entry-level instrument sales.
- Professional Musicians:Individuals who earn their living primarily through playing, teaching, or performing music.
- Music Educators:Teachers and instructors who use instruments as part of their pedagogical practice.
- Recording Studios:Commercial or private facilities that utilize instruments for professional audio recording and production.
Hobbyists represent a substantial volume segment. Students are a consistent source of new demand.
Sales Channel:
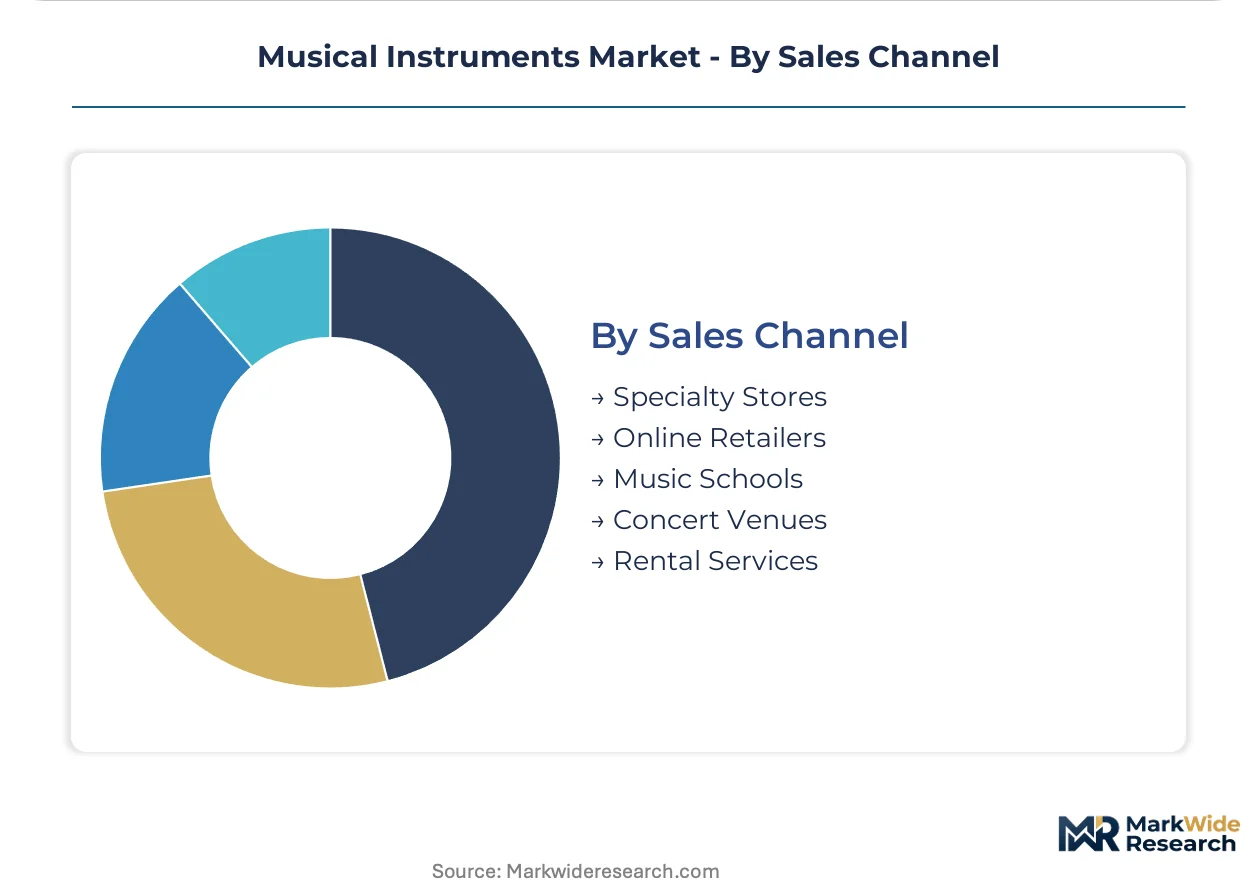
Sales channels reflect diverse distribution strategies, from traditional brick-and-mortar outlets to modern digital platforms.
- Online Retailers:E-commerce platforms and brand websites that sell instruments directly to consumers. Direct-to-consumer channels empower specialized instrument makers to access a global niche audience for custom products.
- Specialty Stores:Dedicated brick-and-mortar shops focusing exclusively on musical instruments and related accessories. These stores often provide expert advice and hands-on testing for high-value instruments.
- Music Schools:Institutions that sell or rent instruments to their students as part of their educational programs.
- Concert Venues:Locations that may offer instrument rentals or sales for performers or events.
- Rental Services:Businesses that provide instruments for temporary use, often catering to students or event organizers.
Online retailers are rapidly expanding their reach. Specialty stores maintain a strong presence for high-value instruments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The musical instruments market historically scaled through European and North American craftsmanship, evolving from traditional workshops to industrial production. This foundation now supports a global industry, with innovation centers emerging across various continents. The market's diverse regional dynamics reflect local cultural preferences and economic development.
United States
Demand for electric guitars and electronic music production tools remains high among hobbyists and professional musicians. The CPSC oversees safety standards for instruments, particularly those intended for children's use. Los Angeles, California, hosts a significant concentration of music production studios and instrument manufacturers.
Germany
European demand for acoustic pianos and orchestral instruments sustains a heritage segment. Compliance with the EU's RoHS directive is mandatory for electronic instrument makers selling into Europe. Markneukirchen, Saxony, maintains its historical role as a center for traditional instrument craftsmanship.
China
Expanding music education initiatives drive significant demand for entry-level instruments. Government policies, including the PLI scheme, support domestic manufacturing capabilities for electronic devices. Guangzhou, Guangdong, is a major production base for pianos and string instruments.
India
Government initiatives promoting arts education create a sustainable pipeline of new student musicians. The BIS sets quality standards for various consumer products, including musical instruments. Chennai, Tamil Nadu, is emerging as a center for music education and instrument retail.
Japan
Innovation in digital pianos and synthesizers drives demand from music producers. METI promotes industrial competitiveness and technological development across manufacturing sectors. Hamamatsu, Shizuoka, is globally recognized as a manufacturing hub for leading musical instrument brands.
Musical Instruments Market Key Industry Players
The competitive structure tilts toward a tiered landscape, balancing established heritage brands with innovative digital instrument manufacturers. This market features a mix of large diversified corporations and specialized boutique producers. Strategic archetypes include traditional acoustic instrument makers, electronic music technology innovators, and mass-market entry-level providers. Companies engage in portfolio diversification and strategic partnerships to expand their market reach.
Specialists in acoustic instrument manufacturing include C.F. Martin & Co. Inc., known for its brand heritage and pioneering use of alternative materials to maintain production quality. Yamaha Corporation occupies a position as a large diversified corporation with an extensive product portfolio spanning acoustic and electronic categories, serving a broad customer base globally. Guangzhou Pearl River Piano Group Co. Ltd. represents a significant player in the global piano manufacturing segment, anchoring production for both educational institutions and professional markets, particularly in Asia.
| Leading Market Players |
|---|
| Gibson Brands |
| Steinway & Sons |
| Yamaha Corporation |
| C.F. Martin & Co. Inc. |
| Casio Computer Co., Ltd. |
| Roland Corporation |
| Kawai Musical Instruments |
| Guangzhou Pearl River Piano Group Co. Ltd. |
| Fender Musical Instruments Corporation |
| Others |
Cost & Logistics Intelligence
CITES-regulated tonewood prices cascade through the acoustic instrument supply chain, influencing pricing tiers from premium handcrafted models to mass-produced entry-level guitars. This dynamic reflects both material scarcity and the cost of compliance in global trade.
Pricing Analysis
Value-based pricing governs the musical instruments market, differentiating products by craftsmanship, brand heritage, and material quality. Price differentiation further occurs through digital feature integration and after-sales service bundles. Pricing pressure stems from digital substitution in the entry-level electronic segment. Professional musicians exhibit lower price sensitivity for high-performance instruments, while hobbyists and students are highly price-sensitive for beginner models.
Supply Chain Analysis
Skilled artisan availability in Germany and Japan significantly impacts the supply of high-end orchestral and acoustic instruments. The supply chain concentrates heavily in China for electronic components, including semiconductors and processors. CITES trade restrictions on traditional tonewoods like rosewood present a structural risk. Distribution runs through online retailers and specialized brick-and-mortar stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The musical instruments market acts as a stable compounder, with sustained growth driven by expanding global music education initiatives. This fundamental demand underpins long-term industry stability.
For Market Incumbents:Lock in existing customer bases by investing in sustainable material research and development for acoustic instruments. C.F. Martin & Co. Inc. leverages brand equity to counter digital substitution threats from virtual instrument software. Diversifying product portfolios into hybrid instruments provides a critical lever against evolving consumer preferences. Strategic capacity additions in key manufacturing geographies can mitigate supply chain risks.
For New Entrants and Emerging Players:Capture white-space opportunities by developing hybrid instruments that merge acoustic and digital capabilities for the "bedroom producer" movement. Emerging markets like India and China represent penetrable geographies for entry-level and aspirational instrument brands. Direct-to-consumer online platforms provide a cost-effective go-to-market angle for specialized product offerings. Focus on innovative software integrations within physical hardware.
For Investors and Strategic Acquirers:Asymmetric upside sits with niche technology innovators and specialized material science firms within the musical instruments market. Long-term viability over a five-to-ten-year window favors companies with strong intellectual property in digital sound and sustainable materials. Acquisition targets include boutique manufacturers pioneering alternative tonewoods or advanced electronic instrument interfaces. Growth in hybrid instrument sales serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Material Innovation R&D | Reduces dependency on restricted tonewoods, ensuring CITES compliance for acoustic instrument production. |
| Digital Integration Partnerships | Enhances electronic instrument capabilities, meeting demand from music production applications. |
| Emerging Market Channel Expansion | Accesses hobbyist and student demand in high-growth regions like China and India. |
| Direct-to-Consumer Platform Development | Empowers specialized instrument makers to reach global niche audiences for custom products. |
| Artisan Skill Training Programs | Addresses the scarcity of skilled luthiers, preserving premium acoustic instrument craftsmanship. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative data analysis — were reconciled to form a comprehensive market view. Industry stakeholders included instrument manufacturers' R&D heads, music educators, retail channel managers, and professional musicians. Secondary sources encompassed CITES trade data, national arts education reports, and company financial filings. This approach utilized both bottom-up and top-down triangulation.
Historical trends cross-referenced with expert panel input informed the analytical framework over the projection horizon. Segmentation dimensions modeled included instrument type, application, end-user, sales channel, and regional market maturity. Compound Annual Growth Rates were derived from historical data and validated through industry projections. Key forecast inputs included music education enrollment data and digital audio workstation user growth.
Geopolitical disruptions, sudden shifts in music consumption trends, and new regulatory mandates are the dominant revision risks for market forecasts. These projections reflect documented assumptions regarding technological evolution and economic stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Global Smart Luggage and Tracking Technologies Market
Consumer Goods
Makeup Egg Market
Consumer Goods
Dog Pillow Market
Consumer Goods
Europe Home Appliances Market
Consumer Goods
Self-Lacing Shoes Market
Consumer Goods
India Vegan Cosmetics Market
Consumer Goods
India Gaming Headset Market
Consumer Goods
Frozen and Freeze-Dried Pet Food Market
Consumer Goods
Luxury Handbag Market
Consumer Goods
Mexico Major Home Appliance Market
Consumer Goods
Cat Massage Comb Market
Consumer Goods
Baby Cradles Market
Consumer Goods
Waterproof Shoe Covers Market
Consumer Goods
Air Care Market
Consumer Goods
Global Mobile Barber Shop Market
Consumer Goods
South Korea Beauty and Personal Care Products Market