
 Cosmetic Serum Market | 2026-2036
Cosmetic Serum Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Serum Market Analysis
Premium clinical-grade formulations is redrawing competitive boundaries in the cosmetic serum landscape. New Look Cosmetics leverages its manufacturing scale to serve private-label clients across North America. BO International anchors its position through backward integration into active ingredient sourcing. Trilogy Laboratories specializes in small-batch custom formulations for dermatology-aligned brands.
A cosmetic serum denotes a concentrated, low-viscosity topical delivery system containing actives at concentrations typically exceeding standard moisturizers, engineered for targeted dermal penetration via aqueous or lipid-based carriers. These formulations serve the primary commercial purpose of addressing specific skin concerns—hydration, photodamage repair, or barrier restoration—through controlled release of functional molecules. Anti-aging serums containing retinol and peptides command the deepest margin pools due to clinical efficacy claims and premium positioning. Brightening formulations with vitamin C represent the fastest-expanding active ingredient category, propelled by pigmentation concerns across diverse phototypes. Hydrating serums built on hyaluronic acid matrices occupy a mature, high-volume tier where differentiation hinges on molecular weight fractionation.
The US FDA exercises oversight through cosmetic labeling requirements under the Federal Food, Drug, and Cosmetic Act, while the EU enforces REACH compliance for chemical substances and mandates animal-testing prohibitions under the Cosmetics Regulation. China's NMPA requires registration of imported cosmetics with full ingredient disclosure and safety assessments, creating a bifurcated compliance burden for multinational suppliers. Stakeholders must monitor evolving preservative restrictions and green chemistry mandates as formulation flexibility becomes the decisive capability separating compliant exporters from market-locked competitors.
Market Dynamics
Professional salon channels are expanding serum adoption as post-treatment homecare protocols, while the EU Cosmetics Regulation (EC) No 1223/2009 elevates formulation compliance costs across the value chain.
Growth Catalysts
- REACH compliance:The EU's chemical safety framework is accelerating investment in green chemistry alternatives, creating first-mover advantages for compliant formulators.
- Multi-step skincare routines:South Korea's ritualized consumption patterns are diffusing into Western markets through digital education and influencer demonstration.
- Retinol-peptide combinations:Clinical-grade actives are commanding premium positioning through dermatology channel validation and efficacy documentation.
Market Restraints
- Hyaluronic acid supply concentration:Fermentation-derived sodium hyaluronate production clusters in select biotech hubs, exposing formulators to input volatility.
- NMPA registration timelines:China's full ingredient disclosure requirements create 18-24 month market entry delays for imported serum portfolios.
- Preservative restrictions:ECHA's tightening stance on phenoxyethanol and paraben alternatives is compressing formulation flexibility for legacy product lines.
Strategic Opportunities
- India's urban tier-2 expansion:Rising disposable incomes in secondary cities are outpacing organized retail penetration for clinical skincare.
- Vitamin C stabilization patents:Ethyl ascorbic acid and amphiphilic derivatives are opening white space in brightening formulations previously limited by oxidation sensitivity.
- Professional channel integration:Medical aesthetic clinics are building captive retail protocols that lock in recurring serum replenishment.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in liposomal encapsulation and nanoemulsion stability commands premium compensation and extended recruitment cycles.
- Animal-testing prohibitions:The EU Cosmetics Regulation's marketing ban is forcing alternative validation investments that extend R&D timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Serum Market |
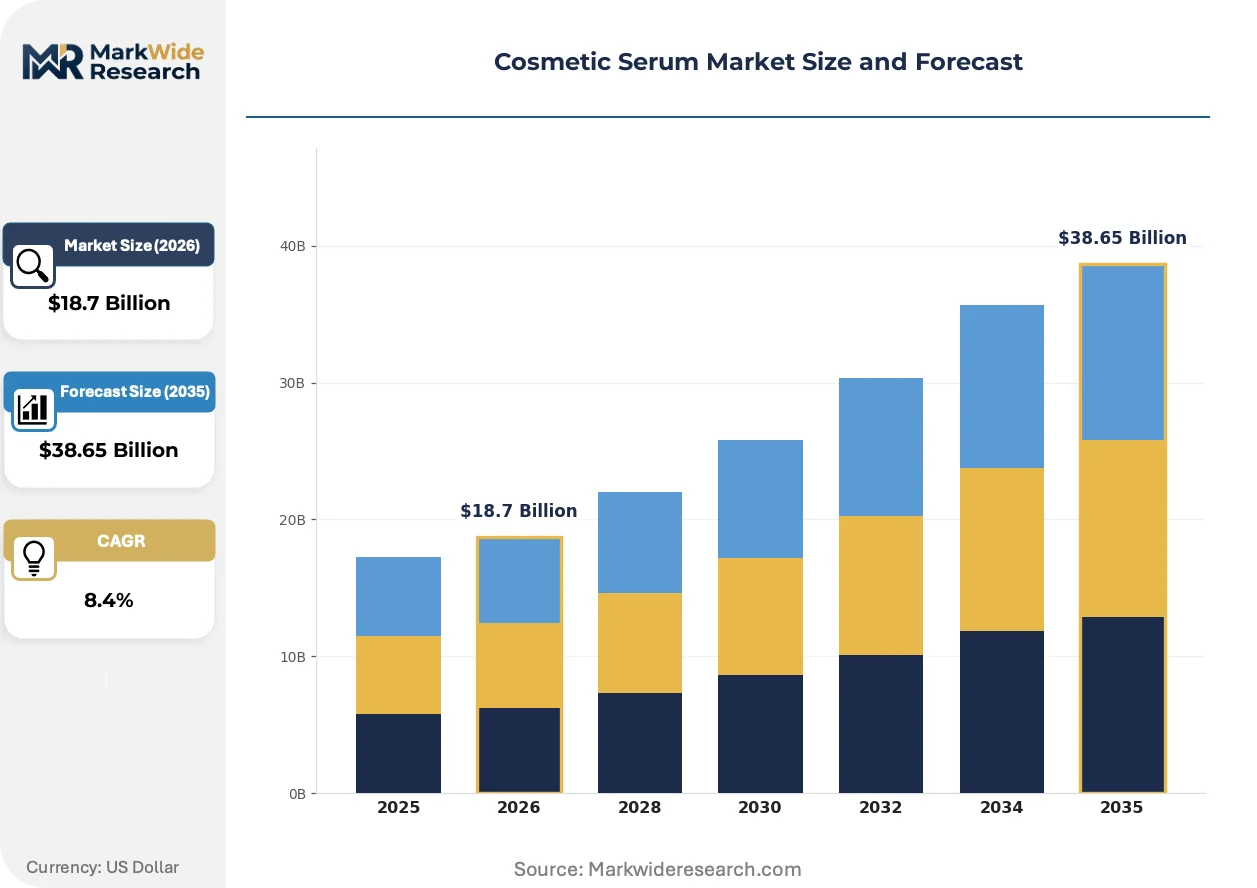
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating, Brightening, Anti-aging, Acne Treatment Active Ingredient: Vitamin C, Hyaluronic Acid, Retinol, Peptides Packaging Type: Dropper Bottles, Airless Pumps, Sachets, Jars Distribution Channel: Online Retail, Specialty Stores, Department Stores, Salons |
| Companies Covered | New Look Cosmetics, Trilogy Laboratories, Global Cosmetics, Biocrown, BO International, Xiran Skincare, RainShadow Labs, Arielcosmetic, Evora Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Serum Market Emerging Trajectories
Biofermentation-derived actives and precision delivery systems are compressing the performance gap between professional and retail-grade formulations.
Encapsulated retinol using porous silica microspheres is displacing traditional oil-soluble delivery in anti-aging serums. Dermatology-aligned brands are adopting this technology at accelerated rates to mitigate irritation profiles. The shift is displacing conventional ester-based retinol formulations from premium positioning tiers.
REACH authorization requirements for CMR substances are forcing reformulation of long-standing preservative systems. Manufacturers are redirecting R&D spend toward biotic-derived alternatives and hurdle technology. The impact concentrates in preservative-dependent aqueous serums targeting EU distribution.
Subscription-based replenishment models are capturing recurring revenue from serum consumers previously served through episodic retail purchase. Direct-to-consumer platforms are replacing department store counters as the primary discovery channel. This pattern is most pronounced in North American urban markets with established logistics infrastructure.
Cosmetic Serum Market Segmentation
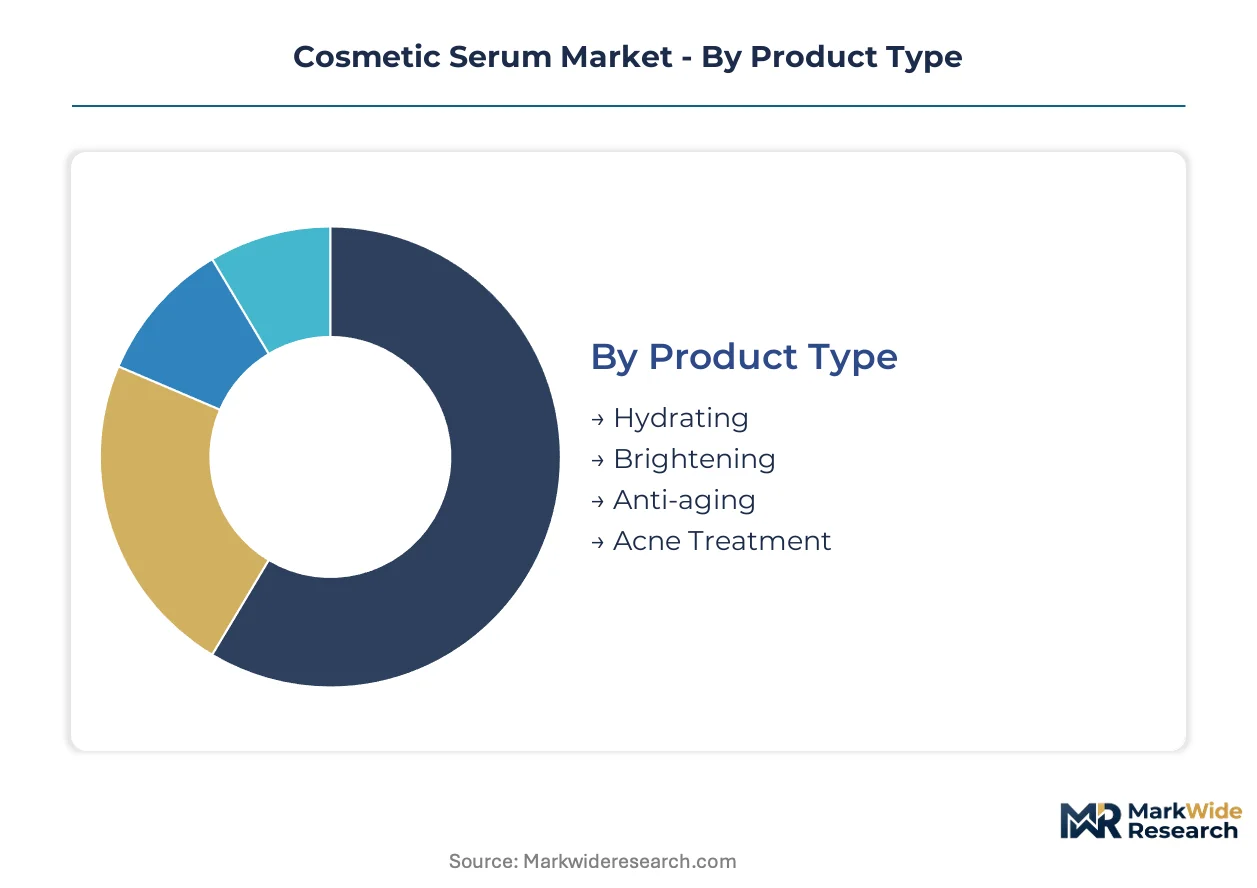
Cosmetic serum segmentation maps directly to margin architecture and channel access. Product type and active ingredient combinations determine regulatory pathway complexity, while packaging format and distribution channel shape replenishment economics and consumer lifetime value.
Product Type:
Channel-mix patterns vary sharply across serum categories, with professional protocols driving premium positioning for clinical-grade formulations while mass retail captures high-frequency replenishment.
- Hydrating:Hyaluronic acid matrices at varying molecular weights form the technical core. Demand clusters in South Korea's multi-step routines and China's tier-2 urban expansion, where barrier repair claims resonate with pollution-exposed consumers. Hydrating serums dominate installed base. Anti-aging is where expansion concentrates.
- Brightening:L-ascorbic acid and ethyl ascorbic acid derivatives target melanin pathway modulation. Pigmentation concerns across diverse phototypes in India and Brazil are accelerating clinical validation investments for stabilized vitamin C formats. Brightening formulations are gaining share fastest among prestige launches.
- Anti-aging:Retinol-peptide combinations command the deepest margin pools through dermatology channel endorsement. Professional salon protocols in Germany and the United States anchor post-treatment homecare adoption with documented efficacy claims.
- Acne Treatment:Niacinamide and salicylic acid blends serve oily and combination skin profiles. Younger demographics in Indonesia and Mexico drive volume through accessible price points and social media discovery.
Anti-aging dominates installed base. Brightening is where expansion concentrates.
Active Ingredient:
Cost tier stratification follows ingredient sourcing complexity and stability requirements, with fermentation-derived and synthetic retinoids occupying opposite ends of the manufacturing investment spectrum.
- Vitamin C:Ethyl ascorbic acid and amphiphilic derivatives solve oxidation sensitivity that plagued L-ascorbic acid formulations. Patent-protected stabilization technologies in Japan and Switzerland are opening premium white space previously limited by shelf-life constraints.
- Hyaluronic Acid:Fermentation-derived sodium hyaluronate from Shandong and Zhejiang biotech clusters supplies global formulators. Molecular weight fractionation—low for penetration, high for surface film—differentiates commodity from clinical-grade positioning.
- Retinol:Encapsulated delivery using porous silica microspheres mitigates irritation profiles that restricted prescription-to-OTC migration. Porous silica encapsulation is displacing conventional ester-based retinol from premium tiers.
- Peptides:Signal peptides and carrier peptides support collagen synthesis claims with lower irritation risk than retinoids. Biotechnology suppliers in Denmark and California command captive relationships with dermatology-aligned brands.
Hyaluronic acid dominates installed base. Vitamin C is where expansion concentrates.
Packaging Type:
Volume economics and contamination risk shape format selection, with airless systems commanding 3-4x unit cost premiums that amortize across high-actives formulations.
- Dropper Bottles:Glass pipette systems remain standard for prestige positioning despite oxidation exposure during use. European and North American heritage brands maintain this format for ritualistic application aesthetics.
- Airless Pumps:Vacuum-dispense technology extends shelf life for oxidation-sensitive actives like vitamin C and retinol. Korean and Chinese manufacturers are scaling domestic airless component supply to reduce import dependency.
- Sachets:Single-use sachets serve trial-size distribution and travel retail in Southeast Asian markets with lower per-capita serum penetration.
- Jars:Wide-mouth containers persist for hybrid serum-cream textures in body and décolletage applications where finger application is preferred.
Dropper bottles dominate installed base. Airless pumps are where expansion concentrates.
Distribution Channel:
Customer type and purchase occasion fragmentation is reshaping channel investment, with subscription platforms capturing recurring revenue previously captured by department store counter relationships.
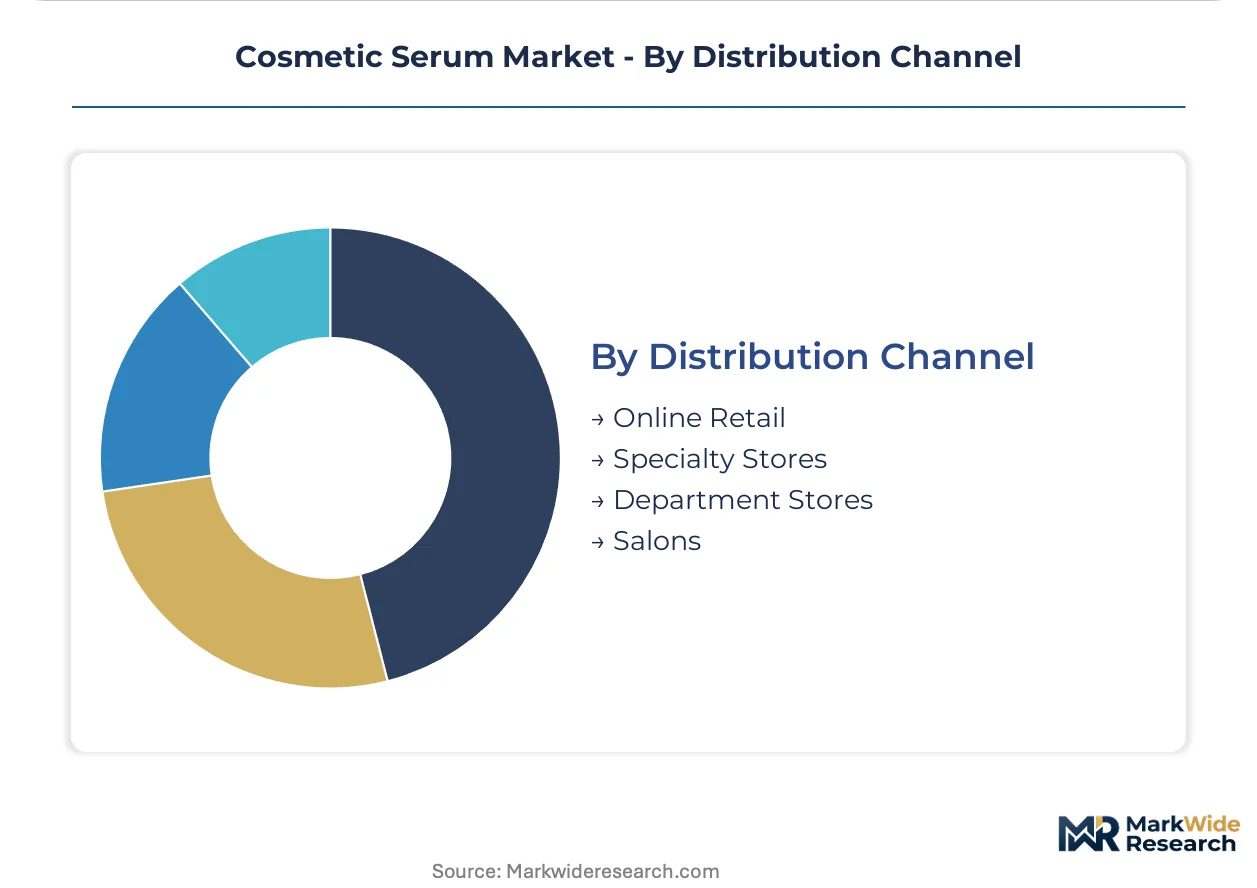
- Online Retail:Direct-to-consumer platforms and marketplace storefronts aggregate discovery and replenishment. Urban logistics infrastructure in the United States and United Kingdom supports same-day and next-day serum delivery that locks in subscription adoption.
- Specialty Stores:Sephora, Ulta Beauty, and Douglas operate as curated discovery environments with in-store sampling. Staff training investments in skin-type diagnostics justify premium positioning versus mass retail.
- Department Stores:Heritage counter models in Japan's Isetan and France's Galeries Lafayette retain high-net-worth consumers through personalized consultation. Foot traffic erosion is compressing SKU breadth to hero products.
- Salons:Medical aesthetic clinics and professional spas build captive retail protocols. Post-treatment homecare mandates in Germany and Australia lock in recurring serum replenishment with protocol-specific SKUs.
Specialty stores dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Germany exhibit low price elasticity for clinical-grade formulations, while consumers in India and Brazil remain highly sensitive to unit cost in mass-market brightening and hydrating categories.
South Korea
Multi-step skincare rituals anchor per-capita serum consumption rates among the world's highest. MFDS regulates functional cosmetics claims through pre-market notification requirements that elevate documentation burdens for brightening and anti-aging SKUs. Seoul's Gangnam district clusters medical aesthetic clinics that prescribe captive homecare protocols.
Germany
Professional salon channels drive post-treatment serum adoption through documented efficacy protocols. ECHA's REACH framework enforces CMR substance restrictions that force preservative system reformulations. Hamburg anchors private-label manufacturing capacity serving North European distribution networks.
United States
Dermatology channel validation commands premium positioning for retinol-peptide combinations in anti-aging segments. FDA cosmetic labeling requirements under the Federal Food, Drug, and Cosmetic Act mandate ingredient disclosure without pre-market approval. New Jersey's contract manufacturing corridor supplies scale production for direct-to-consumer brands.
China
Tier-2 urban expansion outpaces organized retail penetration for clinical skincare in secondary cities. NMPA registration requirements for imported cosmetics impose 18-24 month market entry delays with full ingredient disclosure mandates. Shandong and Zhejiang biotech clusters dominate fermentation-derived sodium hyaluronate production.
India
Rising disposable incomes in urban tier-2 markets accelerate brightening serum demand across diverse phototypes. CDSCO regulates cosmetic imports through registration requirements that favor domestic contract manufacturers. Maharashtra's Mumbai-Pune corridor concentrates private-label formulation capacity for regional brands.
Cosmetic Serum Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with clinical-grade innovators commanding margin premiums while scale manufacturers capture volume through private-label relationships. The market structure fragments across three tiers: multinational dermatology-aligned brands, integrated contract manufacturers with captive ingredient sourcing, and specialized small-batch formulators serving niche positioning. Strategic archetypes include backward-integrated ingredient suppliers, encapsulation technology licensors, and subscription-platform-native brands. Dominant competitive moves center on M&A for biotechnology capabilities and capacity expansion in airless packaging componentry.
Among North American manufacturers, New Look Cosmetics exemplifies scale-driven private-label service across mass and prestige tiers. Trilogy Laboratories occupies a position within the small-batch custom formulation segment serving dermatology-aligned brands. BO International represents the backward-integrated archetype through captive control over active ingredient supply chains.
| Leading Market Players |
|---|
| New Look Cosmetics |
| Trilogy Laboratories |
| Global Cosmetics |
| Biocrown |
| BO International |
| Xiran Skincare |
| RainShadow Labs |
| Arielcosmetic |
| Evora Worldwide |
| Others |
Supply Flow & Price Mechanics
Encapsulated retinol using porous silica microspheres displacing conventional ester-based delivery simultaneously concentrates manufacturing expertise in German and Swiss specialty chemical hubs while compressing margin premiums previously captured by legacy formulation houses. This substitution dynamic redistributes pricing power toward patent-holding encapsulation technology licensors and away from commodity retinol suppliers.
Pricing Analysis
Subscription-based replenishment revenue drives lifetime value for direct-to-consumer serum brands. Three-tier pricing structure across premium, standard, and economy levels separates dermatology-endorsed clinical formulations from mass retail and private-label tiers. Price differentiation rests on MFDS functional cosmetic certification and molecular weight fractionation claims. Pricing pressure stems from Shandong biotech clusters expanding fermentation capacity for sodium hyaluronate. Tier-2 urban consumers in India exhibit highest price sensitivity; German salon-channel buyers show lowest elasticity.
Supply Chain Analysis
Strait of Malacca transit exposure concentrates risk for vitamin C raw material flows from Chinese ascorbic acid manufacturers to Southeast Asian formulators. Active ingredient production clusters in Shandong and Zhejiang provinces for hyaluronic acid, Basel region for peptide synthesis, and Busan for encapsulation componentry. Raw material dependencies include fermentation-derived sodium hyaluronate, L-ascorbic acid precursors, and porous silica microspheres. Single-source vulnerability characterizes patented ethyl ascorbic acid stabilization technologies held by Japanese and Swiss suppliers. Distribution runs through professional salon protocols in Germany, direct-to-consumer platforms in the United States, and specialty retail in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cosmetic serum market functions as a defensive-moat arena where regulatory entrenchment through REACH compliance and NMPA registration creates sustainable barriers against fast-follower competition.
For Market Incumbents: Shield market position by deepening backward integration into active ingredient sourcing, particularly fermentation-derived sodium hyaluronate production in Shandong-adjacent facilities. Acquire encapsulation technology patents to neutralize porous silica microsphere displacement threats from Swiss and Japanese licensors. Prioritize CDSCO registration investment to preempt domestic Indian manufacturers in tier-2 urban expansion zones.
For New Entrants and Emerging Players: Lead with vitamin C stabilization innovation targeting oxidation-sensitive brightening formulations where patent cliffs open white space. Brazil and Indonesia present the most penetrable geographies given lower per-capita serum saturation and social media-driven discovery patterns. Deploy medical aesthetic clinic partnerships as the primary go-to-market angle to bypass crowded retail shelf competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract manufacturers possessing captive airless packaging componentry and established NMPA registration dossiers. Long-term viability favors platforms with dual US-EU regulatory clearance and subscription-native customer data infrastructure. Watch ECHA preservative restriction announcements as the critical inflection signal for reformulation-driven M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Porous silica microsphere patents from Swiss suppliers command premium positioning in dermatology channels. |
| Backward Integration into Fermentation | Shandong biotech cluster proximity secures sodium hyaluronate supply against input volatility. |
| Professional Channel Integration | Medical aesthetic clinic protocols in Germany lock recurring replenishment through post-treatment mandates. |
| Airless Packaging Scale-Up | Korean and Chinese domestic component supply reduces import dependency for oxidation-sensitive actives. |
| Regulatory Registration Acceleration | CDSCO and NMPA dossier completion preempts competitor access in India and China expansion corridors. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with formulation chemists, dermatology brand product development heads, specialty retail category buyers, and contract manufacturing procurement directors; and secondary validation against REACH substance restriction databases, NMPA registration filings, MFDS functional cosmetic notifications, and customs-derived trade flow records. Bottom-up SKU-level modeling triangulated against top-down category spend estimates.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, active ingredient concentration tier, packaging format, distribution channel, and regional regulatory cluster. CAGRs derived from segment-level growth rate synthesis incorporating professional channel penetration curves and subscription adoption patterns. Forecast inputs included salon protocol expansion rates in Germany and tier-2 urban disposable income trajectories in India.
Forecasts assume regulatory continuity in EU REACH, China NMPA, and South Korea MFDS regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as ECHA preservative restriction timelines and NMPA registration backlog conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Cosmetic Wax Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Hair Gel Market
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
US Sustainable Personal Care Market
Beauty & Personal Care
Saudi Arabia Eyelash Serum Market
Beauty & Personal Care
Delivery Systems in Personal Care Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market
Beauty & Personal Care
Cosmetic Palettes Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
Deodorant and Antiperspirants Market
Beauty & Personal Care
Cruelty-Free Makeup Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Global Beauty and Personal Care Products Market
Beauty & Personal Care
Beauty Oils Market