
 China Playing Cards & Board Games Market | 2026-2036
China Playing Cards & Board Games Market Size, Share, and Industry Trends Forecast 2026-2036
China Playing Cards & Board Games Market Insights
Aftermarket service revenue from game café equipment leasing and tournament organization is narrowing as direct-to-consumer online channels capture margin pools previously held by rental operators. ShangHai YaoJi Playing Card Co.,Ltd. leverages its historic brand recognition in premium card decks to sustain domestic shelf presence against newer entrants. Shenzhen Swarm Playing Cards Co., Ltd. specializes in custom-printed collectible card runs for esports tie-ins, positioning it at the intersection of gaming and merchandising growth.
Playing cards and board games comprise paper-based or polymer-coated game systems with standardized dimensions, surface finishes, and rule structures designed for recreational or competitive tabletop engagement. Manufacturing employs offset lithography on 300-350 gsm card stock with aqueous or UV coating for durability and shuffle performance, serving entertainment, education, and social interaction purposes. Strategy games and collectible cards attract disproportionate margin pools as hobbyist communities drive repeat purchases and expansion pack cycles, while traditional cards occupy stable volume positions through mass merchant channels. The online retail distribution channel is reshaping access patterns, with livestream commerce on domestic platforms enabling direct manufacturer-to-player sales that bypass traditional wholesale tiers.
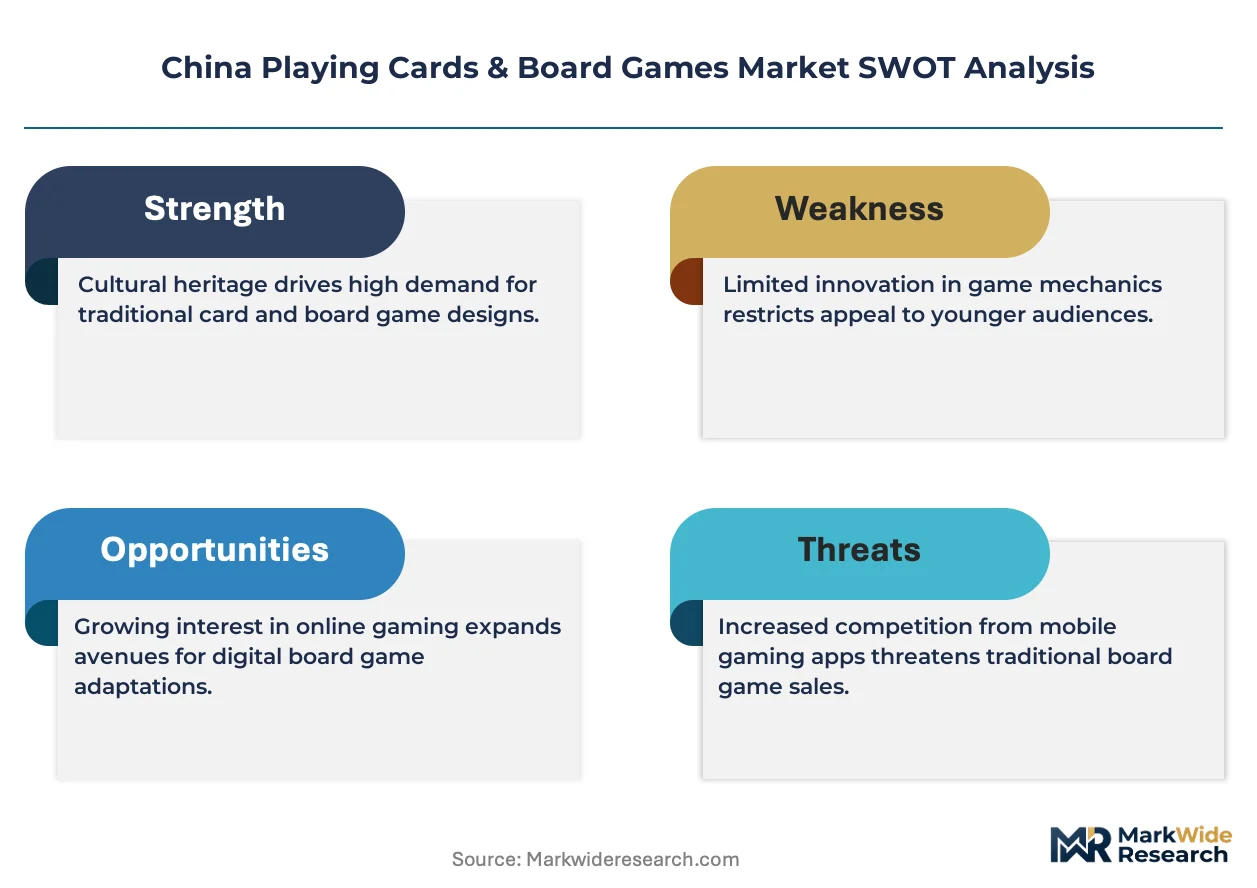
SAMR enforces GB standards for product safety in toys and games, including chemical migration limits and labeling requirements that manufacturers must satisfy for domestic market access. The Ministry of Industry and Information Technology oversees printing industry environmental compliance, pushing solvent reduction and waste recovery obligations onto card and board game producers. Stakeholders must monitor how evolving national packaging waste regulations and provincial green manufacturing mandates will alter material sourcing economics and compliance cost structures across the production base.
Market Dynamics
Livestream commerce on domestic platforms is compressing wholesale tier margins while redirecting manufacturer-player relationships toward direct fulfillment models. This channel shift is forcing incumbents to rebuild distribution economics around content-driven conversion rather than shelf-space negotiation.
Growth Catalysts
- Strategy game cafés:Young adult social gaming venues in Chengdu and Shanghai are expanding orders for premium strategy game sets, creating concentrated demand nodes that validate higher-margin product development.
- GB standards compliance:SAMR's updated national safety standards for toy and game materials are filtering out subscale competitors, consolidating shelf access for certified domestic manufacturers.
- Yangtze River Delta supplier networks:Dense printing and packaging infrastructure across Zhejiang and Jiangsu provinces is shortening production lead times and reducing logistics overhead for card and board game producers.
Market Restraints
- Coated paper stock volatility:300-350 gsm card stock with aqueous or UV coating faces input cost pressure from pulp markets and petrochemical feedstocks, squeezing margin on mass-market card decks.
- Single-region supplier concentration:Printing and laminating capacity clusters heavily in eastern coastal provinces, exposing producers to localized environmental compliance shutdowns under MIIT oversight.
- Digital entertainment substitution:Mobile gaming and short-video platforms capture leisure hours from casual tabletop players, constraining volume growth in traditional playing card segments.
Strategic Opportunities
- Esports merchandising convergence:Custom-printed collectible card runs tied to competitive gaming tournaments open premium pricing tiers beyond standard hobbyist markets.
- Livestream commerce infrastructure:Platform-native fulfillment and influencer seeding enable direct-to-player sales that capture wholesale margin pools previously distributed through regional distributors.
- Dual carbon manufacturing incentives:MIIT's green manufacturing mandates create preferential access to state-backed financing for producers investing in solvent reduction and waste recovery systems.
Industry Challenges
- Offset lithography technician scarcity:Skilled press operators capable of maintaining color consistency across 300-350 gsm card stock are aging out of the workforce faster than vocational pipelines replenish them.
- Packaging waste compliance timelines:Evolving national packaging regulations under MEE oversight require rapid reformulation of blister packs and display boxes, compressing product redesign cycles.
- Cross-border IP licensing complexity:Collectible card tie-ins with international entertainment properties face protracted rights negotiations that delay market windows and inflate upfront guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Playing Cards & Board Games Market |
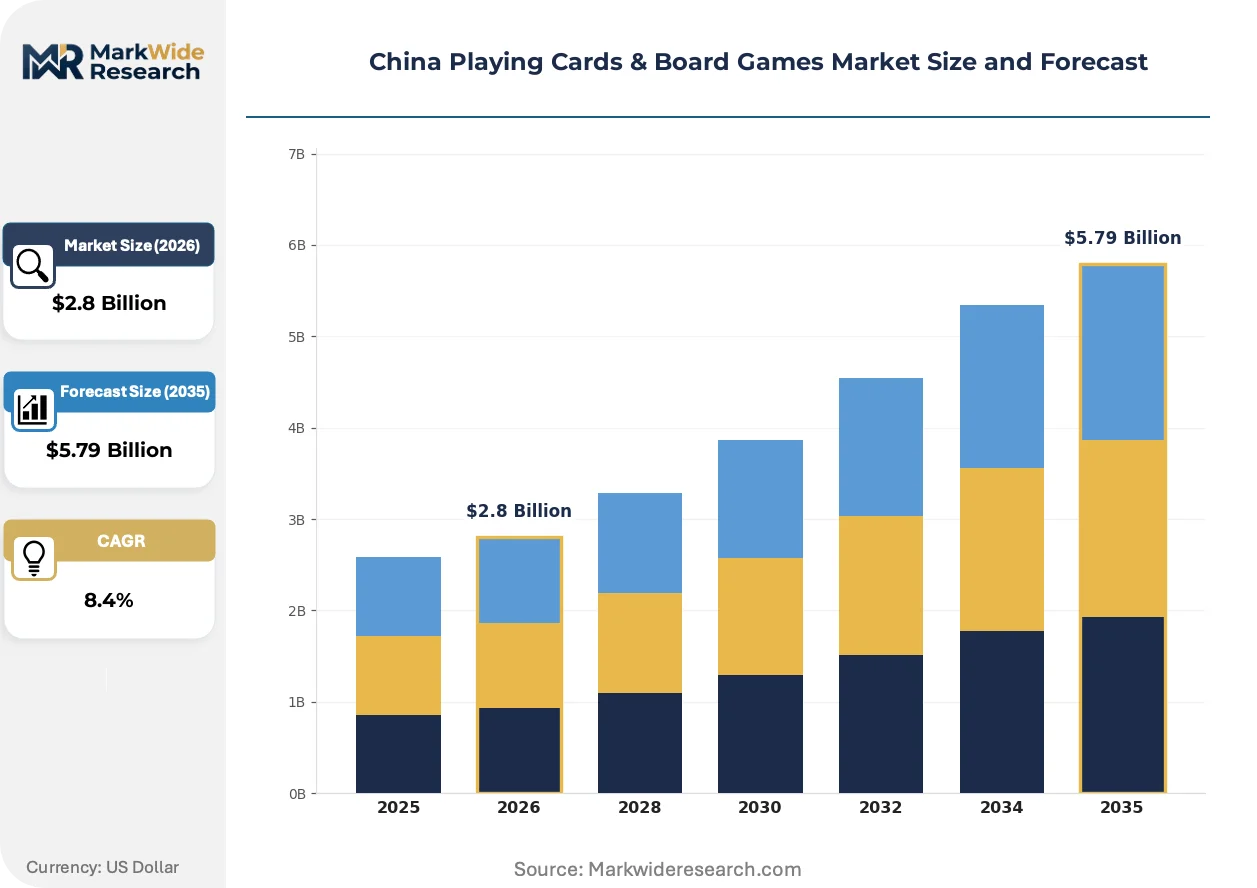
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Cards, Board Games, Collectible Cards, Strategy Games Target Audience: Children, Teenagers, Adults, Families Distribution Channel: Online Retail, Specialty Stores, Mass Merchants, Supermarkets Game Mechanics: Cooperative, Competitive, Deck-building, Role-playing |
| Companies Covered | ShangHai YaoJi Playing Card Co.,Ltd., Shenzhen YHD Packaging Products Co., Ltd., Shenzhen ITIS Packaging Products Co., Ltd., Shenzhen Yahong Color Printing Co., Ltd., Zhejiang Chinu Packing & Printing Co., Ltd., Ningbo Charron Industry Co., Ltd., Shenzhen Swarm Playing Cards Co., Ltd., Yangzhou Jinyi Stationery Co., Ltd., Yangzhou Jumbay International Trading Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Playing Cards & Board Games Market Trends and Innovations
Surface finishing technologies and fulfillment models are converging to reshape how card and board games reach players. Manufacturers are racing to match premium tactile expectations with production economics that survive direct-channel price transparency.
Polymer-coated card stock with specialized texture layers is migrating from luxury collectible segments toward mid-tier strategy game releases. Boutique publishers in the Yangtze River Delta cluster are adopting these finishes at compressed volume minimums. The technology is migrating from premium proof-of-concept runs to standard production configurations, eroding the historical price gap between mass-market and enthusiast card quality.
SAMR's GB standards for chemical migration limits are tightening material certification requirements for all domestic market entry. Manufacturers must now document compliance across aqueous coatings, adhesives, and printed substrates prior to distribution authorization. Strategy game producers with complex multi-component packaging face the steepest compliance cost escalation as testing protocols expand.
Social gaming cafés are consolidating purchasing authority through centralized procurement consortia that bypass traditional distributor relationships. These venue networks negotiate directly with manufacturers for tournament-grade equipment and exclusive card deck runs, displacing the fragmented wholesale tier that historically served fragmented retail accounts. This concentration is most visible in Shanghai and Chengdu, where café density supports dedicated account management structures.
China Playing Cards & Board Games Market Segmentation
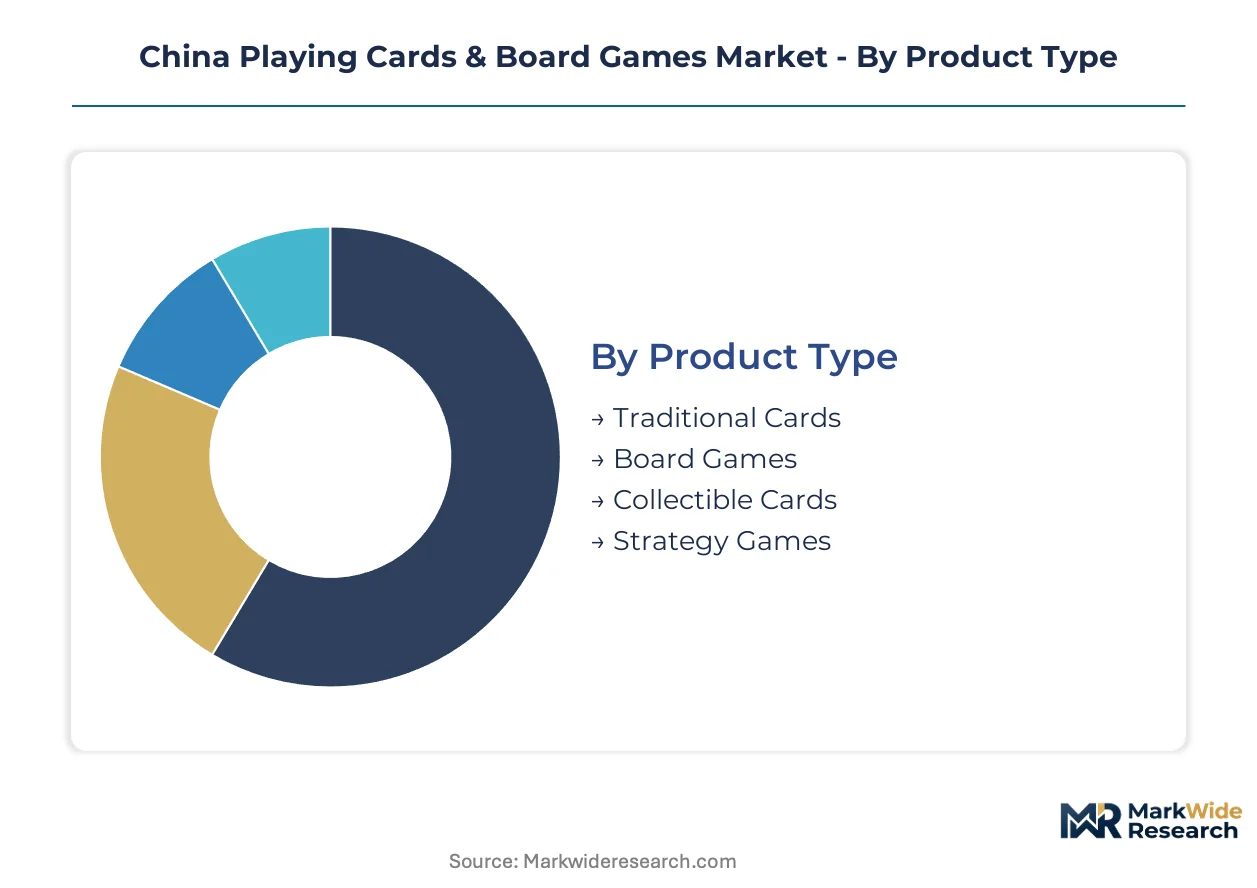
Segmentation in China's playing cards and board games market reveals how product positioning, audience targeting, and channel economics diverge across distinct consumption contexts. Manufacturers calibrate material specifications, pricing tiers, and marketing investments differently for each slice, with SAMR compliance costs and Yangtze River Delta supplier access acting as cross-cutting filters.
Product Type:
Mature formats anchor volume throughput while emerging categories capture margin expansion and community-driven repeat purchase cycles.
- Traditional Cards:Standard 52-card decks and regional variants utilize 300-350 gsm card stock with aqueous coating for shuffle durability. Demand concentrates in mass merchant channels across lower-tier cities where price sensitivity limits premium positioning. SAMR's GB chemical migration standards have raised entry barriers for uncertified producers, consolidating supply among established Zhejiang and Jiangsu manufacturers.
- Strategy Games:Complex rule systems with modular boards and multi-component packaging target hobbyist communities in Chengdu and Shanghai gaming cafés. These venues negotiate direct procurement agreements, bypassing traditional wholesale tiers and enabling exclusive tournament-grade product runs. Expansion pack cycles and community-organized events sustain recurring revenue streams beyond initial box sales.
- Board Games:Family-oriented titles with simplified mechanics and shorter play durations dominate supermarket and online retail placement. Packaging waste regulations under MEE oversight are compressing redesign timelines for blister packs and display boxes.
- Collectible Cards:Polymer-coated stock with specialized texture layers supports esports merchandising tie-ins and limited-edition runs. Rights negotiations for international entertainment properties delay market windows.
Traditional Cards retains volume leadership; Strategy Games holds the steepest expansion curve.
Target Audience:
Audience segmentation maps directly to occasion-based purchasing patterns and channel access economics across China's urban hierarchy.
- Adults:Hobbyist collectors and competitive players drive premium strategy game and collectible card demand through specialized online communities and café networks. Livestream commerce platforms enable direct manufacturer relationships that capture margin pools previously distributed through regional distributors.
- Families:Multi-generational play occasions prioritize accessibility and replay value, concentrating purchases in mass merchant and supermarket channels during seasonal gifting periods. Price transparency across e-commerce platforms constrains premium positioning for mass-market titles.
- Teenagers:Esports-adjacent consumption and social signaling motivations favor collectible cards with tournament legitimacy and influencer endorsement. Short-video platform engagement competes directly for leisure hours.
- Children:Educational positioning and parental safety certification priorities dominate purchase decisions, with SAMR's updated toy and game standards filtering subscale competitors from shelf access.
Families command the broadest channel footprint; Adults generate the highest per-capita expenditure rates.
Distribution Channel:
Channel structure is bifurcating between content-driven direct conversion and legacy wholesale relationships under margin compression.
- Online Retail:Domestic platform livestream commerce enables manufacturer-to-player fulfillment with real-time inventory visibility and influencer-seeded conversion. This model redirects margin pools from fragmented regional distributors toward content production and logistics infrastructure investments.
- Specialty Stores:Hobbyist-focused retailers in Shanghai and Chengdu curate tournament-grade equipment and exclusive releases for gaming café procurement consortia. Centralized purchasing authority is displacing the fragmented account structures that historically served dispersed venues.
- Mass Merchants:Volume placement for traditional cards and family board games depends on shelf-space negotiation and promotional calendar alignment. Pulp and petrochemical feedstock volatility squeezes margin on standardized card deck offerings.
- Supermarkets:Impulse and seasonal gifting purchases concentrate in urban retail formats with limited SKU depth and rapid inventory turnover requirements.
Mass Merchants maintain the widest SKU distribution; Online Retail is climbing the fastest in transaction volume share.
Game Mechanics:
Mechanical complexity correlates with production cost structure, community organizing intensity, and expansion content monetization potential.
- Competitive:Head-to-head victory conditions dominate esports-adjacent collectible cards and tournament-organized strategy titles, with ranking systems and prize structures sustaining player investment. MIIT green manufacturing mandates create preferential financing access for producers investing in solvent reduction for complex multi-component packaging.
- Cooperative:Team-based victory against game systems appeals to family and casual adult segments, with lower replay value compression risk through modular difficulty scaling and narrative campaign extensions.
- Deck-building:Card acquisition and engine construction mechanics generate recurring expansion pack revenue through curated card pool releases, requiring precise print run calibration to balance scarcity and accessibility.
- Role-playing:Narrative immersion and character progression systems demand substantial rulebook and component investments, with skilled offset lithography technician scarcity constraining color consistency across premium production runs.
Competitive mechanics anchor the highest-margin product development; Deck-building is gaining share fastest through expansion cycle monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's playing cards and board games consumption concentrates in coastal urban clusters where gaming café culture and livestream commerce reshape purchase patterns, while interior provinces maintain traditional mass-market channels. This geographic split creates divergent margin structures and compliance exposure across the production base.
Yangtze River Delta
Zhejiang and Jiangsu provinces host dense printing and packaging supplier networks that shorten production lead times for card and board game manufacturers. MIIT's green manufacturing mandates push solvent reduction obligations onto producers in this cluster. Hangzhou and Suzhou anchor the region's offset lithography capacity, with environmental compliance shutdowns periodically disrupting output schedules.
Pearl River Delta
Guangdong's manufacturing ecosystem supports custom-printed collectible card runs and esports merchandising tie-ins targeting young adult consumers. SAMR's GB chemical migration standards filter subscale competitors from domestic market access. Shenzhen's packaging specialists occupy the intersection of gaming and merchandising growth, serving cross-border e-commerce fulfillment channels.
Sichuan-Chongqing
Chengdu's young adult social gaming cafés generate concentrated demand nodes for premium strategy game sets that validate higher-margin product development. Provincial environmental regulations under MEE oversight compress packaging waste compliance timelines. The municipality's procurement consortia negotiate directly with manufacturers, displacing fragmented wholesale relationships.
Beijing-Tianjin-Hebei
Regulatory oversight from SAMR and MIIT concentrates in this administrative corridor, shaping national standards that cascade to production bases elsewhere. Family-oriented board game purchases concentrate in mass merchant channels during seasonal gifting periods. Tianjin's port infrastructure supports import-export flows for international entertainment property licensing.
Shandong Peninsula
Pulp and paper feedstock markets in this region influence input cost pressure on 300-350 gsm card stock production. Traditional playing card demand concentrates in lower-tier city retail formats where price sensitivity limits premium positioning. Qingdao's logistics networks connect interior production to coastal export channels.
China Playing Cards & Board Games Market Competitive Landscape
Capability concentration sits with heritage-brand specialists; scale advantage sits with integrated packaging conglomerates. The market structures around three tiers: historic card manufacturers with domestic shelf access, custom-printing specialists serving esports merchandising, and diversified packaging houses with offset lithography capacity. Competitive moves center on direct-to-player channel buildout and SAMR certification investment that filters uncertified rivals.
Within the heritage-brand tier, ShangHai YaoJi Playing Card Co.,Ltd. occupies a position sustained by historic recognition in premium card decks. Shenzhen-based fabricators exemplify the custom-printing specialization vector: Shenzhen Swarm Playing Cards Co., Ltd. represents the esports merchandising convergence archetype, while Shenzhen YHD Packaging Products Co., Ltd. and Shenzhen ITIS Packaging Products Co., Ltd. sit within integrated packaging houses leveraging Pearl River Delta supplier density.
| Leading Market Players |
|---|
| ShangHai YaoJi Playing Card Co.,Ltd. |
| Shenzhen YHD Packaging Products Co., Ltd. |
| Shenzhen ITIS Packaging Products Co., Ltd. |
| Shenzhen Yahong Color Printing Co., Ltd. |
| Zhejiang Chinu Packing & Printing Co., Ltd. |
| Ningbo Charron Industry Co., Ltd. |
| Shenzhen Swarm Playing Cards Co., Ltd. |
| Yangzhou Jinyi Stationery Co., Ltd. |
| Yangzhou Jumbay International Trading Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
MIIT environmental compliance shutdowns in the Yangtze River Delta determine both pricing tier spreads and supply chain shape for China's playing cards and board games market. Producers face compressed margins when Hangzhou and Suzhou offset lithography capacity idles under green manufacturing mandates, forcing rapid cost reallocation across premium and mass-market tiers.
Pricing Analysis
Long-term offtake agreements between gaming café procurement consortia and Zhejiang manufacturers anchor volume pricing for tournament-grade strategy game sets, while spot purchasing dominates mass-market traditional card replenishment. Three-tier pricing structure across premium, standard, and economy levels separates polymer-coated collectible cards with esports tie-ins from aqueous-coated family board games and uncoated promotional decks. Pricing pressure stems from pulp and petrochemical feedstock volatility squeezing 300-350 gsm card stock economics. Mass merchant buyers in lower-tier cities exhibit the highest price sensitivity, constraining premium positioning for standardized offerings.
Supply Chain Analysis
Extended payment terms from Shanghai and Chengdu gaming café networks strain working capital for Yangtze River Delta suppliers, accelerating supply-chain finance facility adoption among Zhejiang and Jiangsu printing houses. Raw material dependencies center on coated paper stock, UV and aqueous coating chemicals, and specialized polymer substrates for premium finishes. Single-region supplier concentration in eastern coastal provinces exposes producers to localized environmental compliance shutdowns under MIIT oversight. Distribution runs through direct-to-player livestream commerce platforms and fragmented wholesale tiers serving mass merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Livestream commerce fragmentation creates white-space opportunities across China's playing cards and board games market, as content-driven conversion displaces legacy shelf-space negotiation and opens niches for specialized producers.
For Market Incumbents: Insulate core revenue streams by deepening direct relationships with gaming café procurement consortia in Shanghai and Chengdu, while accelerating SAMR GB standards certification to filter subscale competitors from domestic shelf access. Vertical integration into solvent-reduction coating systems captures MIIT green manufacturing incentives and defends margin position against pulp feedstock volatility. For New Entrants and Emerging Players: Establish a beachhead in esports merchandising tie-ins for collectible card runs, where rights negotiation complexity delays incumbent responses and opens premium pricing tiers. Target Sichuan-Chongqing gaming café networks with tournament-grade equipment leasing bundled with exclusive card deck production, bypassing fragmented wholesale relationships entirely. For Investors and Strategic Acquirers: SAMR's evolving chemical migration standards reshape the acquisition landscape by consolidating shelf access among certified domestic manufacturers and eliminating subscale competitors. Viable targets include Yangtze River Delta offset lithography specialists with documented GB compliance and established gaming café account management. Watch for MIIT environmental shutdown frequency as an inflection indicator for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Player Livestream Commerce Buildout | Captures wholesale margin pools previously distributed through regional distributors on domestic platforms. |
| SAMR GB Standards Certification Investment | Filters uncertified rivals from domestic market access and consolidates shelf presence for compliant producers. |
| Gaming Café Procurement Consortium Partnership | Secures concentrated demand nodes in Chengdu and Shanghai that validate higher-margin product development. |
| Solvent Reduction and Waste Recovery Systems | Unlocks preferential state-backed financing under MIIT green manufacturing mandates for Yangtze River Delta producers. |
| Esports Merchandising Rights Acquisition | Positions custom-printed collectible card runs at the intersection of gaming and premium merchandising growth. |
Research Methodology
Initial hypotheses were tested against primary input from offset lithography plant managers, gaming café procurement leads, packaging R&D directors, and MIIT compliance officers and refined through secondary validation. Primary fieldwork drew from Zhejiang and Jiangsu manufacturing clusters and Shanghai distribution networks. Secondary sources included SAMR regulatory filings, MIIT environmental compliance disclosures, customs trade data for coated paper stock imports, and domestic platform livestream commerce transaction records. Bottom-up production capacity estimates and top-down consumption pattern analysis were triangulated to cross-validate volume and value outputs.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, target audience, distribution channel, and game mechanics dimensions. CAGRs were derived from annualized growth rate calculations applied to base-year market sizing. Industry-specific forecast inputs incorporated gaming café expansion rates in Chengdu and Shanghai, SAMR certification timeline assumptions, and MIIT environmental compliance shutdown probability.
Sensitivities concentrate around pulp and petrochemical feedstock volatility, SAMR standards implementation pacing, and MIIT enforcement intensity for green manufacturing mandates. Forecasts reflect documented assumptions about gaming café network consolidation and livestream commerce penetration trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Microwaveable Stuffed Animal Toys Market
Toys and Games
Animation Toys Market
Toys and Games
Baby Toys Market
Toys and Games
Action Figures Market
Toys and Games
Ride-Ons Market
Toys and Games
Eco-Friendly Toys Market
Toys and Games
Blind Box Toys Market
Toys and Games
Global Toys Market
Toys and Games
Autonomous Robot Toys Market
Toys and Games
Dildo Sex Toy Market
Toys and Games
Toy Kitchens and Play Food Market
Toys and Games
Plastic Toy Storage Market
Toys and Games
Games and Puzzles Market
Toys and Games
Kids Toys Market
Toys and Games
US BDSM Sex Toys Market
Toys and Games
Kids Recreational Services Market