
 Toilet Paper Market | 2026-2036
Toilet Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Toilet Paper Market Analysis
E-commerce subscription channels is rewriting how consumers replenish household essentials, bypassing traditional retail shelf competition. Kimberly-Clark leverages its direct-to-consumer infrastructure to sustain recurring revenue streams. Procter & Gamble anchors brand loyalty through bundled delivery programs. Georgia-Pacific competes on bulk logistics efficiency for commercial accounts.
Toilet paper consists of layered cellulose sheets, typically two-ply or three-ply, engineered for absorbency, tensile strength, and disintegration compliance with plumbing and wastewater systems. Virgin pulp variants deliver softness benchmarks for premium household buyers, while recycled grades serve cost-sensitive commercial contracts and sustainability procurement policies. Two-ply products occupy the largest volume share across mass retail, yet bamboo-based material variants represent the fastest-growing fiber input as institutional buyers rewrite supplier qualification criteria. Jumbo roll formats dominate away-from-home installations in hotels and healthcare facilities, where dispenser compatibility and reduced restocking labor define procurement decisions.
The EPA's Comprehensive Procurement Guidelines steer U.S. federal purchasers toward post-consumer recycled content thresholds, while the EU Green Deal's packaging waste framework pressures exporters to certify fiber sourcing and plastic reduction in multi-roll wraps. FDA sanitation standards for healthcare facility supplies add compliance layers for manufacturers targeting hospital procurement networks. Stakeholders must monitor how divergent transatlantic sustainability timelines reshape raw material sourcing strategies and capital allocation for recycled pulp capacity.
Market Dynamics
EU Green Deal packaging waste directives are forcing fiber-light redesigns and recycled content mandates across manufacturing footprints, while e-commerce subscription channels simultaneously disintermediate traditional retail shelf competition for household replenishment.
Growth Catalysts
- Healthcare facility expansion:North American and European hospitals are increasing procurement volumes for hygienic tissue products as patient capacity grows and infection control protocols tighten.
- EU Green Deal packaging mandates:The framework's waste reduction targets create regulatory pull for fiber-light designs and certified recycled content in multi-roll packaging.
- Bamboo fiber substitution:Institutional buyers are rewriting supplier qualification criteria to favor rapidly renewable fiber inputs that reduce virgin pulp dependence.
Market Restraints
- Softwood pulp cost volatility:Northern European and Canadian conifer supply fluctuations transmit directly to virgin pulp pricing benchmarks, compressing margin predictability for premium household grades.
- Recycled fiber contamination thresholds:Post-consumer waste streams carry plastic and adhesive residues that degrade tissue softness, limiting recycled content ceilings in premium positioning.
- Dispenser hardware lock-in:Jumbo roll formats for away-from-home installations create path dependency, slowing format transitions even when superior products emerge.
Strategic Opportunities
- Direct-to-consumer infrastructure:Subscription replenishment platforms bypass retail slotting fees and build recurring revenue streams through bundled delivery programs.
- EPA Comprehensive Procurement Guidelines:Federal purchasing thresholds for post-consumer recycled content create qualified demand pools for compliant manufacturers.
- Smart dispenser integration:IoT-enabled restocking sensors in healthcare and hospitality reduce labor costs while locking in supply relationships through data-driven replenishment.
Industry Challenges
- Recycled pulp capacity scaling:De-inking and fiber recovery infrastructure requires substantial capital deployment with multi-year payback horizons.
- FDA sanitation certification timelines:Healthcare facility supply approvals involve extended validation protocols that delay market entry for new manufacturing lines.
- Divergent transatlantic sustainability timelines:EU fiber sourcing certifications and US recycled content thresholds create compliance fragmentation for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toilet Paper Market |
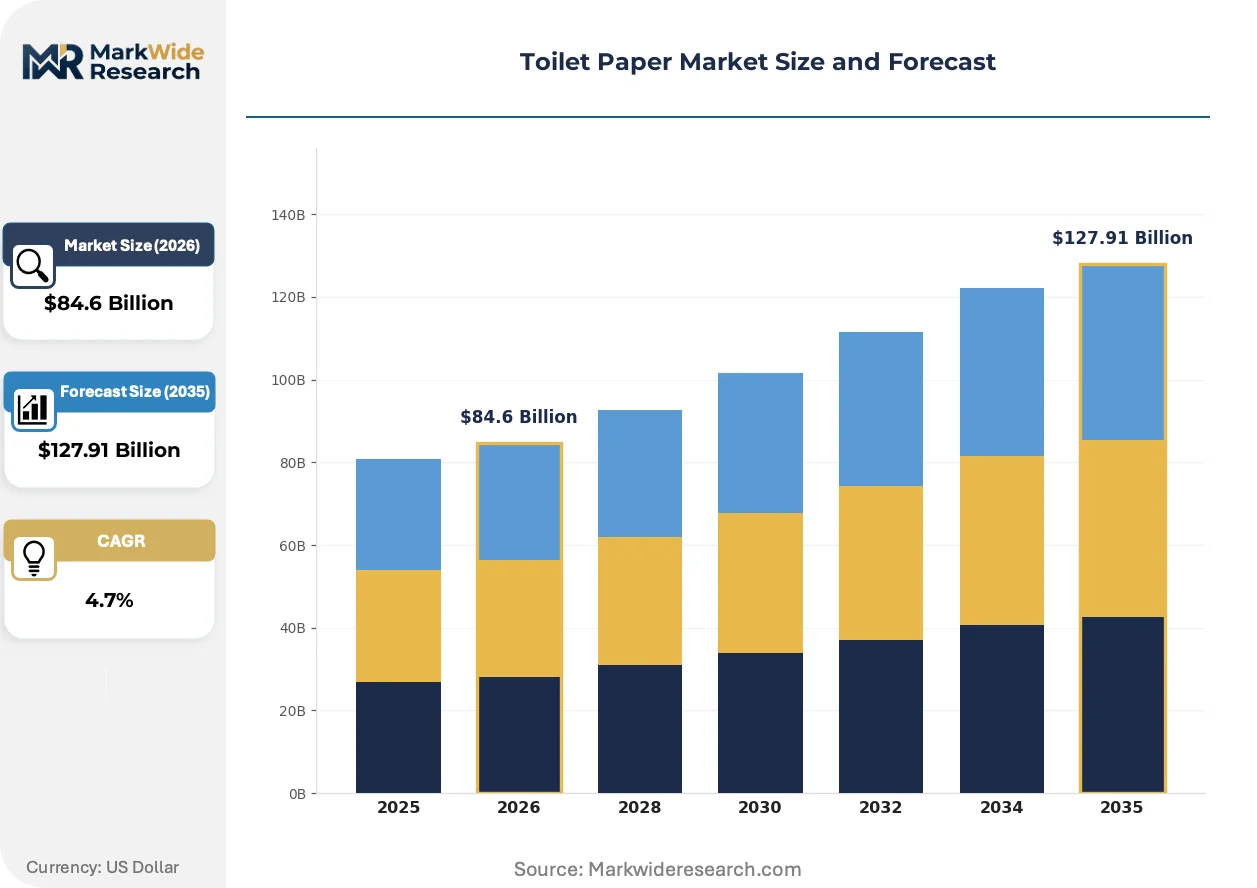
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $127.91 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Ply, Three-Ply, Recycled, Jumbo Roll Material: Virgin Pulp, Bamboo, Recycled Paper, Dinxin Packaging Type: Pack of 4, Pack of 8, Single Roll, Bulk Pack End User: Households, Commercial Establishments, Hotels, Healthcare Facilities |
| Companies Covered | Essity AB, Who Gives a Crap, Kimberly-Clark, Scott, Charmin, Procter & Gamble, Seventh Generation, Cottonelle, Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toilet Paper Market Emerging Trajectories
Active innovation fronts span fiber substitution chemistry, regulatory compliance automation, and channel architecture restructuring that together compress traditional competitive moats.
Dry-formed tissue manufacturing is rendering obsolete conventional wet-press energy intensity. Hotel and healthcare facility buyers are piloting these lower-basis-weight structures at accelerated procurement cycles. The technology is rendering obsolete historical trade-offs between roll density and dispenser compatibility.
EU Green Deal packaging waste directives are mandating plastic reduction in multi-roll wraps and fiber sourcing traceability. Exporters to European markets must certify chain-of-custody documentation and eliminate petroleum-based overwrap materials. Premium household segments face the steepest reformulation costs as visual packaging differentiation loses regulatory permission.
Bulk logistics efficiency now determines commercial account retention as institutional buyers consolidate supplier panels. Food service and facility management intermediaries are displacing fragmented local distributors with national contract frameworks. Germany and France exhibit the most advanced procurement centralization, compressing vendor counts by half across hospital networks.
Toilet Paper Market Segmentation
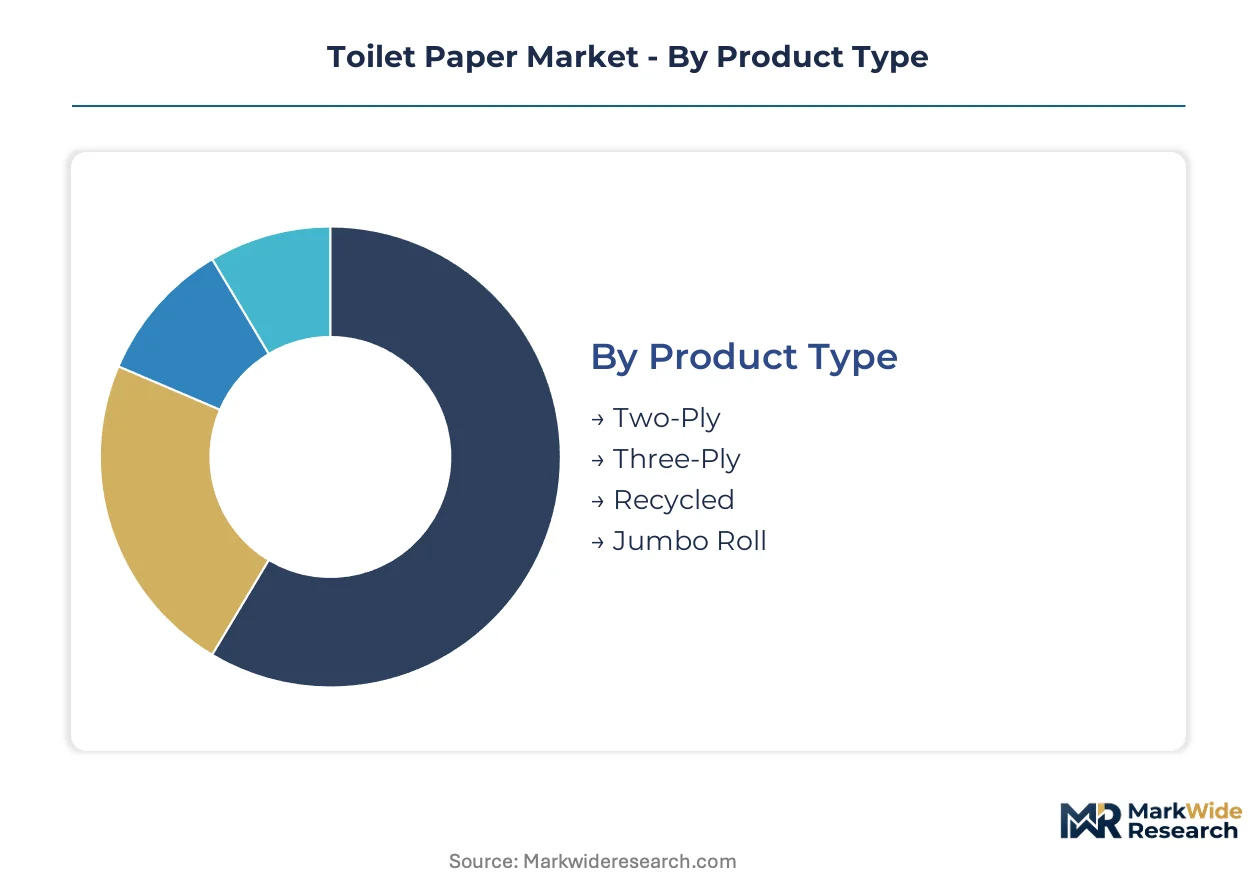
Toilet paper segmentation reveals divergent technical specifications across use environments, from residential plumbing compatibility to institutional dispenser standards. Manufacturers configure fiber blends, sheet counts, and roll dimensions to match distinct procurement criteria and consumption patterns.
Product Type:
Use-case spectrum spans residential comfort preferences to high-traffic facility maintenance economics.
- Two-Ply:Dual-layer cellulose construction balances absorbency with septic system disintegration standards. Mass retail channels in the United States concentrate volume here, with household buyers prioritizing unit cost over plushness.
- Three-Ply:Triple-layered sheets deliver elevated softness benchmarks through denser fiber matrices. Premium household segments in Germany and France absorb disproportionate volume as private-label quality tiers rise.
- Recycled:Post-consumer fiber content meets EPA procurement thresholds for federal supply contracts. Softness limitations restrict penetration in premium residential positioning.
- Jumbo Roll:Expanded diameter formats reduce restocking frequency in away-from-home installations. Healthcare facilities specify these for dispenser compatibility and labor cost containment.
The dominant share belongs to Two-Ply, while Jumbo Roll is closing the gap fastest as institutional procurement centralizes.
Material:
Cost tier stratification separates commodity virgin pulp from certified sustainable alternatives commanding procurement premiums.
- Virgin Pulp:Northern softwood fibers deliver tensile strength and surface smoothness benchmarks. Canadian and Scandinavian conifer supply chains serve premium household specifications.
- Bamboo:Rapidly renewable grass fibers reduce virgin pulp dependence with comparable softness profiles. EU Green Deal sourcing mandates accelerate qualification across hospital networks.
- Recycled Paper:De-inked post-consumer waste streams carry contamination thresholds limiting premium applications. EPA guidelines steer U.S. federal purchasing toward specified content minimums.
- Dinxin:Hybrid fiber blends optimize cost-performance ratios for private-label mass retail positioning. Asian manufacturing clusters specialize in these formulations.
Virgin Pulp retains volume leadership, though Bamboo is expanding most quickly as sustainability criteria harden in procurement specifications.
Packaging Type:
Volume economics and retail channel mechanics dictate format selection from convenience stores to warehouse clubs.
- Pack of 4:Standard household replenishment unit balancing shelf space efficiency with purchase frequency. Supermarket and hypermarket planograms allocate prime positioning here.
- Pack of 8:Mid-tier bundling reduces per-roll cost for budget-conscious household segments. Club store penetration remains limited by storage space constraints.
- Single Roll:Emergency purchase and travel-size convenience formats. Urban convenience stores and hospitality amenity programs drive residual demand.
- Bulk Pack:Commercial-grade palletized shipments optimize logistics for facility management intermediaries. Healthcare procurement consolidation favors these formats for contract efficiency.
Pack of 4 configurations dominate retail velocity, while Bulk Pack formats gain share fastest through institutional panel consolidation.
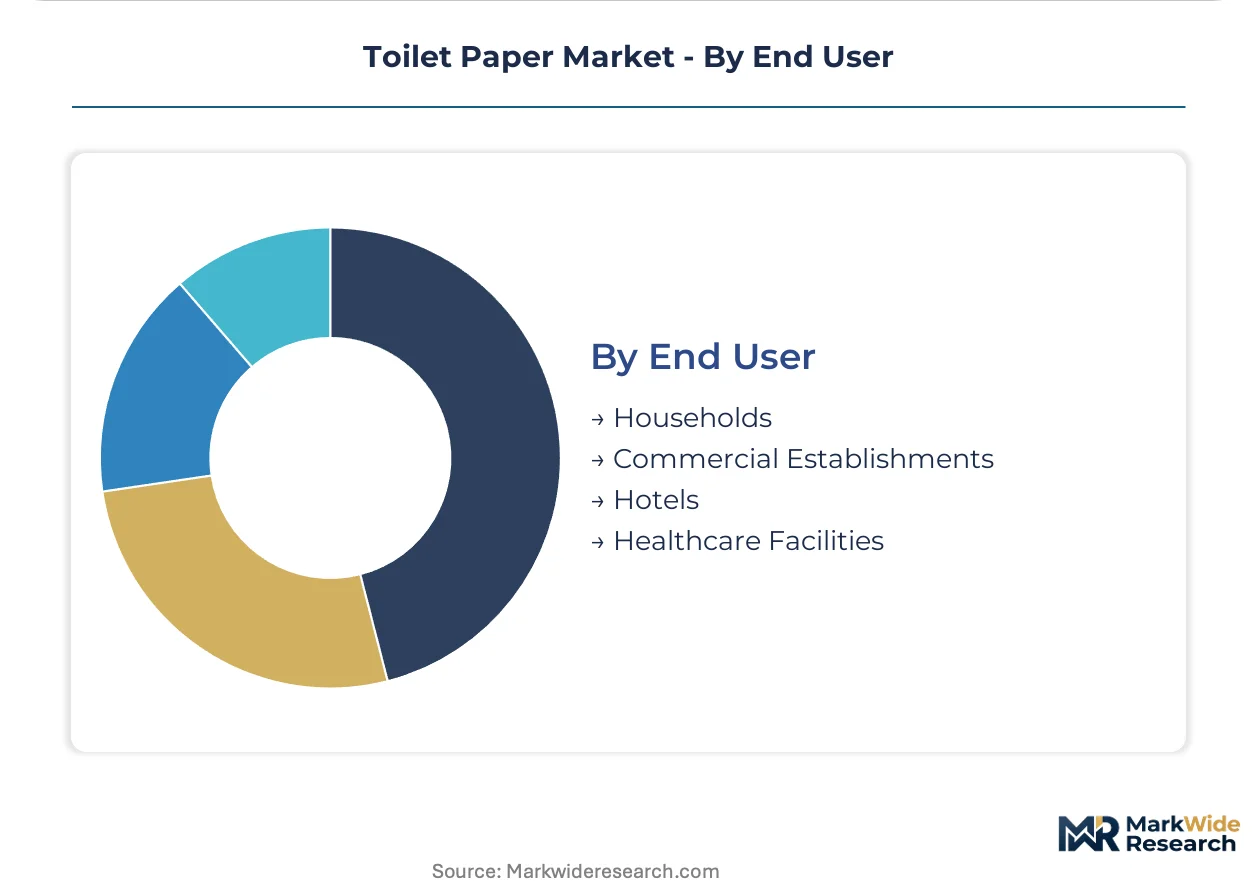
End User:
Customer type segmentation exposes divergent performance requirements across private consumption and professional facility management.
- Households:Individual consumers select on softness, brand recognition, and shelf price with low switching costs. E-commerce subscription channels now capture replenishment frequency.
- Commercial Establishments:Office buildings and food service operations prioritize dispenser compatibility and cost-per-use metrics. National contract frameworks displace fragmented local purchasing.
- Hotels:Guest experience standards mandate premium feel despite high consumption volumes. Boutique properties differentiate through sustainable fiber messaging.
- Healthcare Facilities:Infection control protocols and FDA sanitation certifications create entry barriers. Hospital networks in France and Germany centralize procurement around qualified supplier panels.
Households absorb the largest volume, yet Healthcare Facilities are climbing the fastest as patient capacity expansion and hygiene protocol intensification compound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European distribution networks for hygienic tissue products, while the Mississippi River barge system anchors North American pulp logistics. These infrastructure assets shape where manufacturing capacity clusters and how finished goods reach institutional buyers.
United States
Federal procurement through the EPA's Comprehensive Procurement Guidelines drives post-consumer recycled content demand across hospital networks and government facilities. The Southeast pulp corridor spanning Georgia and Alabama concentrates virgin fiber production for premium household grades. E-commerce subscription channels capture replenishment frequency in metropolitan markets.
Germany
Hospital procurement centralization in Bavaria and North Rhine-Westphalia consolidates supplier panels around EU Green Deal compliance. The country's national packaging regulator enforces plastic reduction mandates in multi-roll overwraps. Frankfurt's logistics hub serves as the distribution anchor for Central European institutional contracts.
China
Bamboo fiber processing clusters in Sichuan-Chongqing supply rapidly renewable inputs for export qualification. The Ministry of Ecology and Environment enforces dual carbon goals that pressure mills toward energy efficiency retrofits. Yangtze River Delta manufacturers specialize in hybrid fiber blends for private-label mass retail.
France
Île-de-France healthcare networks rewrite supplier qualification criteria to favor certified sustainable fiber sourcing. The national pharmaceutical regulator enforces sanitation standards for hospital tissue supplies. Lyon-based procurement intermediaries consolidate food service and facility management contracts nationally.
Canada
Boreal forest conifer supply chains in British Columbia and Quebec serve premium softness benchmarks for North American export. Federal sustainable procurement policies steer institutional purchasing toward certified fiber content. Vancouver's port infrastructure handles Pacific Rim containerized shipments.
Toilet Paper Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational consumer goods conglomerates with captive pulp supplies, regional specialists in sustainable fiber formats, and private-label manufacturers serving retail channel intermediaries. Competitive dynamics center on backward integration into pulp assets and direct-to-consumer channel architecture. M&A activity targets recycled fiber capacity, while strategic partnerships lock in healthcare procurement networks.
Among North American-based operators, Procter & Gamble and Kimberly-Clark exemplify the scale-driven conglomerate archetype with integrated supply chains. Georgia-Pacific represents the industrial pulp-to-tissue vertical. Who Gives a Crap occupies a position within the sustainability-native tier, anchoring the direct-to-consumer subscription model that bypasses traditional retail slotting economics.
| Leading Market Players |
|---|
| Essity AB |
| Who Gives a Crap |
| Kimberly-Clark |
| Scott |
| Charmin |
| Procter & Gamble |
| Seventh Generation |
| Cottonelle |
| Georgia-Pacific |
| Others |
Supply Flow & Price Mechanics
The Sichuan-Chongqing bamboo processing corridor anchors rapidly renewable fiber supply, translating upstream capacity expansion into downstream pricing leverage for sustainable-grade manufacturers competing against virgin pulp incumbents.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transaction architecture. Price differentiation hinges on softness certification grade and volume scale, with healthcare procurement contracts commanding premiums for FDA-compliant sanitation tiers. Cost compression in recycled fiber grades is intensifying because contamination thresholds limit premium positioning. Household segments exhibit highest price sensitivity, while hospital networks prioritize compliance over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for bamboo fiber exporters seeking EU Green Deal qualification. Pulp production concentrates in Canada, Sweden, and Brazil, drawing from boreal conifer and eucalyptus plantations. Raw material dependencies rest on softwood chips, de-inked post-consumer waste, and grass fiber inputs. Distribution runs through Port of Rotterdam container terminals for European institutional buyers and Mississippi River barge networks for North American mass retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment platforms have restructured this market toward platform-economics dynamics, where dispenser hardware interoperability and data-driven restocking algorithms now determine supplier lock-in more than brand equity alone.
For Market Incumbents: Build captive pulp supply moats through backward integration into recycled fiber capacity in the Southeast United States. Secure FDA sanitation certifications ahead of healthcare procurement centralization. Anchor brand loyalty through bundled delivery programs that raise switching costs for household subscribers. For New Entrants and Emerging Players: Mid-market commercial buildings in France and Germany represent the most penetrable entry point, as facility management intermediaries displace fragmented local distributors. Target smart dispenser retrofit installations with IoT-enabled restocking sensors. Pursue EU Green Deal certification as the primary qualification wedge for hospital network panels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dry-formed tissue manufacturing specialists with energy-efficient production footprints. Long-term viability rests on fiber substitution chemistry and regulatory compliance automation capabilities. Watch for EPA procurement guideline threshold revisions as the signal indicating federal demand inflection toward post-consumer recycled content minimums.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Kimberly-Clark's subscription infrastructure builds recurring revenue streams bypassing retail slotting fees. |
| Bamboo Fiber Capacity Expansion | Sichuan-Chongqing processing clusters qualify rapidly renewable inputs for EU Green Deal compliance mandates. |
| Smart Dispenser Integration | IoT-enabled restocking sensors in healthcare facilities reduce labor costs while locking in supply relationships. |
| Recycled Pulp Infrastructure Investment | De-inking and fiber recovery capacity addresses EPA Comprehensive Procurement Guidelines threshold requirements. |
| Healthcare Procurement Panel Consolidation | National contract frameworks in Germany and France compress vendor counts by half across hospital networks. |
Methodological Framework
Desk research of trade association publications, customs records, and regulatory filings preceded structured interviews with tissue manufacturing executives, hospital procurement managers, facility management intermediaries, and retail category buyers. Primary fieldwork captured operating data on fiber substitution economics and dispenser hardware deployment cycles. Secondary validation drew from EPA procurement databases, EU Green Deal implementation trackers, and pulp futures pricing benchmarks. Bottom-up volume modeling triangulated against top-down market sizing across product type, material, and end-user dimensions.
Forecast assumptions held fixed regulatory timelines and pulp cost trajectories while varying healthcare capacity expansion rates and e-commerce penetration curves across the projection horizon. Segmentation modeling spanned product type, material composition, packaging format, and end-user environment. CAGRs derived from regression analysis against macroeconomic indicators and historical demand elasticities. Industry-specific inputs included pulp futures volatility indices and hospital bed capacity forecasts.
Macroeconomic conditions sit as an overlay; deviation in softwood pulp pricing benchmarks or EU packaging waste enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation schedules and fiber substitution adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Shower Market
Household Items
Infuser Water Bottles Market
Household Items
Indoor Humidifier Market
Household Items
Manual Bottle Opener Market
Household Items
Window Rain Guards Market
Household Items
Latex Mattress Market
Household Items
Integrated Smart Toilet Market
Household Items
Dishwasher Detergent Market
Household Items
India POU Water Purifiers Market
Household Items
Electric Air Freshener Market
Household Items
Bristle Brush Market
Household Items
France Digital Showers Market
Household Items
Robot Vacuum Cleaners Market
Household Items
Replacement Sheets Market
Household Items
Toilet Care Wipes Market
Household Items
Hydralight Lanterns Market