
 India Musical Instruments Market | 2026-2036
India Musical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
India Musical Instruments Market Foresight
Skilled luthier and craftsman availability is bifurcating the India musical instruments landscape into heritage handcraft clusters and mechanized production corridors. Yamaha Corporation anchors its position through dedicated R&D facilities targeting Indian tonal preferences, while Casio competes via aggressive channel control across tier-two and tier-three cities. Haribhau Vishwanath Musical Industries sustains dominance in traditional string instruments through captive supply of seasoned tonewood from domestic forests.
India musical instruments comprise acoustically or electronically generated sound-producing devices crafted from wood, metal, synthetic composites, or semiconductor arrays, with functional parameters spanning frequency range, resonance sustain, and signal-to-noise ratios in electronic variants; these tools serve commercial performance, pedagogical instruction, and cultural ceremony applications. String instruments occupy the largest margin pool due to sustained replacement cycles among professional performing artists, while electronic instruments represent the fastest-growing category as hobbyists migrate toward digital workstations and MIDI controllers. The distribution channel dimension reveals online retailers capturing share from legacy music shops through augmented reality-based instrument preview tools.
BIS certification requirements for electronic instruments, CDSCO oversight on materials contacting human skin, and CEA electrical safety standards collectively elevate compliance costs for importers while creating protected terrain for certified domestic manufacturers. The PLI scheme for electronic manufacturing offers partial offset for firms establishing local assembly of digital keyboards and synthesizers. Stakeholders must monitor how India's forthcoming e-commerce inventory labeling rules reshape fulfillment economics for cross-border instrument sellers.
Market Dynamics
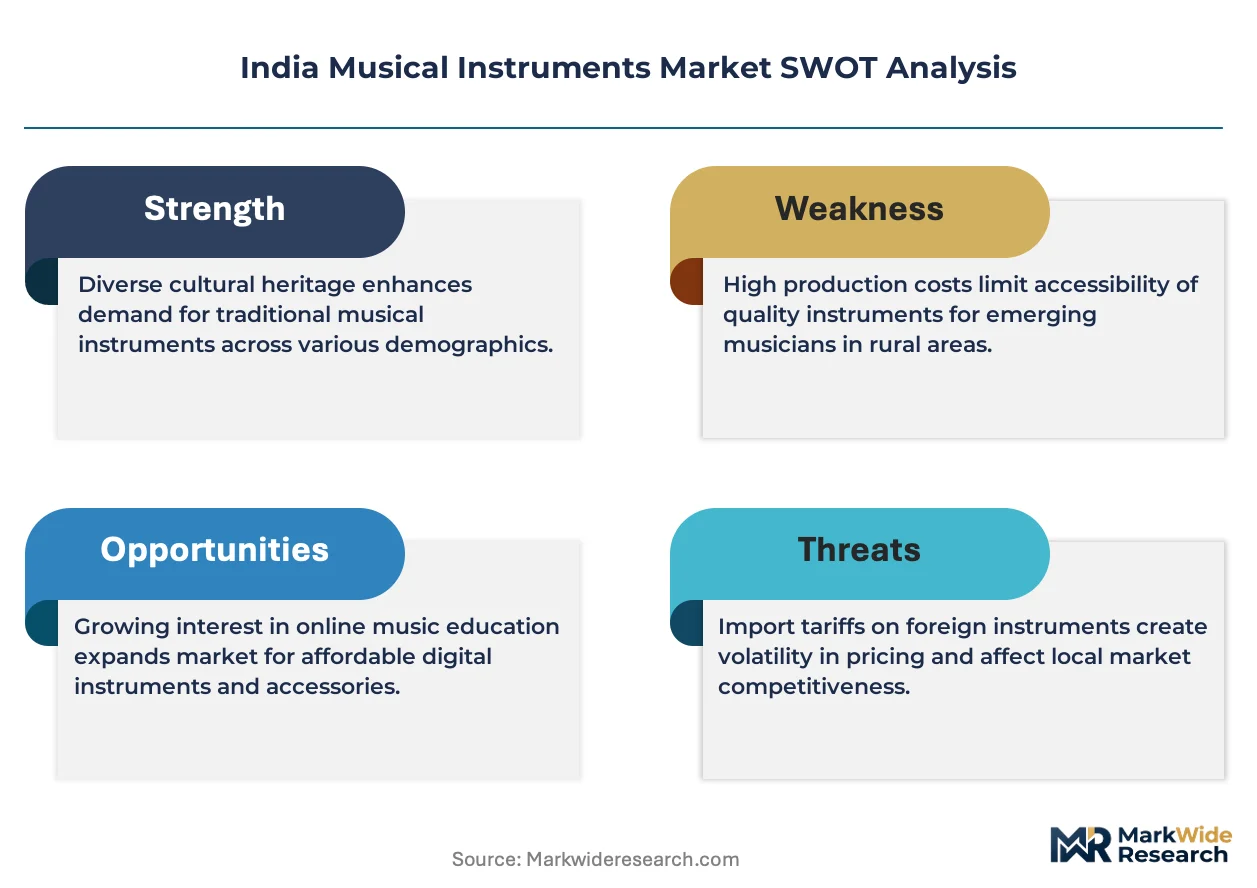
Skilled luthier scarcity is bifurcating India musical instruments into heritage handcraft clusters and mechanized production corridors, with BIS certification mandates for electronic instruments simultaneously elevating quality thresholds and compliance burdens for domestic manufacturers.
Growth Catalysts
- PLI Scheme for Electronics:The Production Linked Incentive scheme offers partial cost offset for firms establishing local assembly of digital keyboards and synthesizers, accelerating domestic manufacturing capacity.
- Carnatic Music Ecosystem Expansion:Chennai's institutional training infrastructure sustains premium instrument procurement from professional performing artists and expanding student cohorts.
- Film Studio Infrastructure:Mumbai's recording ecosystem drives sustained replacement cycles for professional-grade string and percussion instruments among session musicians.
Market Restraints
- Tonewood Supply Concentration:Heritage handcraft clusters depend on captive supply of seasoned tonewood from specific domestic forest zones, creating geographic vulnerability to harvest restrictions.
- BIS Certification Friction:Bureau of Indian Standards requirements for electronic instruments impose testing timelines and documentation burdens that delay import clearance and market entry.
- Digital Workstation Substitution:MIDI controllers and software-based production tools compress demand for traditional acoustic instruments among hobbyist segments.
Strategic Opportunities
- Tier-Two City Channel Penetration:Aggressive distributor control across tier-two and tier-three cities opens white space for electronic instrument brands beyond Mumbai and Chennai concentration zones.
- Augmented Reality Preview Tools:Online retailers deploying AR-based instrument visualization are capturing share from legacy music shops, enabling geographic expansion without physical showroom investment.
- E-Commerce Inventory Labeling Tailwind:Forthcoming domestic inventory disclosure rules for cross-border sellers create protected terrain for certified domestic manufacturers with established local fulfillment.
Industry Challenges
- CDSCO Materials Compliance:Oversight on materials contacting human skin requires reformulation of finishes and hardware for string instruments, extending product development cycles.
- CEA Electrical Safety Integration:Central Electricity Authority standards for electronic instruments demand design modifications that complicate platform sharing with international product lines.
- Master Craftsman Succession:Heritage handcraft clusters face generational transfer gaps as traditional luthier training periods exceed younger worker retention thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Musical Instruments Market |
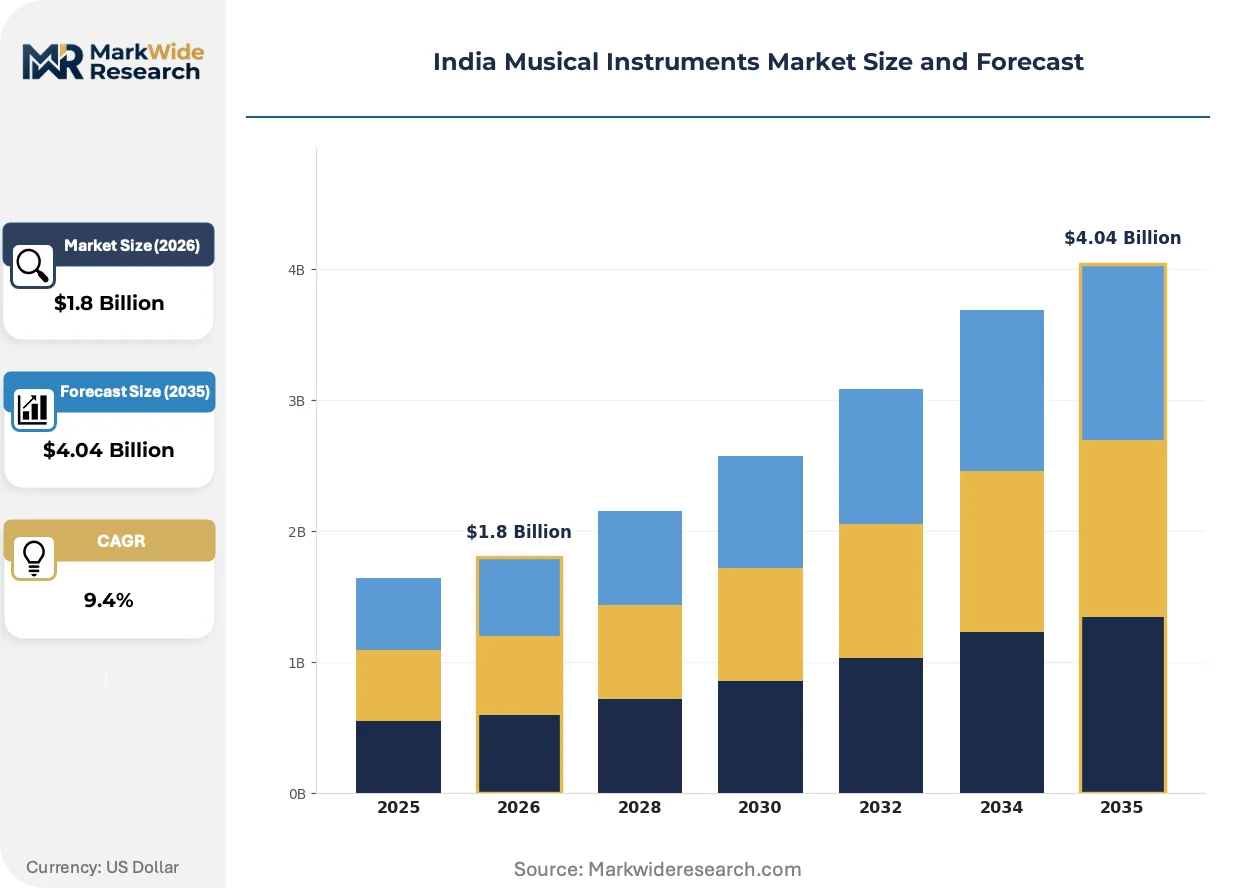
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Instruments, Percussion Instruments, Wind Instruments, Electronic Instruments End User: Schools, Professionals, Hobbyists, Performing Artists Distribution Channel: Online Retailers, Music Shops, Department Stores, Direct Sales Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Kawai Musical Instruments Mfg Co. Ltd, Casio, Yamaha Corporation, Haribhau Vishwanath Musical Industries, Bina Musical Stores, Roland Corporation, Cor-Tek Corporation, Radel Electronics, Fender Musical Instruments Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Musical Instruments Market Shifts & Advancements
Digital signal processing architectures are actively compressing the boundary between acoustic resonance and electronic synthesis, reshaping instrument design priorities across professional and consumer segments.
Silicon-based modeling engines is supplanting analog oscillator circuits in mid-tier digital keyboards. Music education institutes in Maharashtra are adopting these platforms at accelerated replacement cycles. The technology is supplanting traditional tone-generation methods while reducing per-unit component costs and enabling firmware-upgradeable feature expansion.
BIS certification mandates for electronic instruments are elevating electromagnetic compatibility testing requirements. Domestic manufacturers must redesign power supply architectures and shielding protocols to achieve compliance. Electronic keyboard and synthesizer categories face the steepest adaptation curves, with firms establishing captive testing laboratories to compress certification timelines.
Student cohorts at classical music training institutes are fragmenting instrument procurement across acoustic heritage models and hybrid electronic-acoustic platforms. Augmented reality preview tools at online retailers are displacing physical trial visits to legacy music shops. Tamil Nadu's Carnatic ecosystem exhibits the most pronounced bifurcation, with institutional buyers maintaining acoustic traditions while individual learners gravitate toward portable electronic alternatives.
India Musical Instruments Market Segmentation
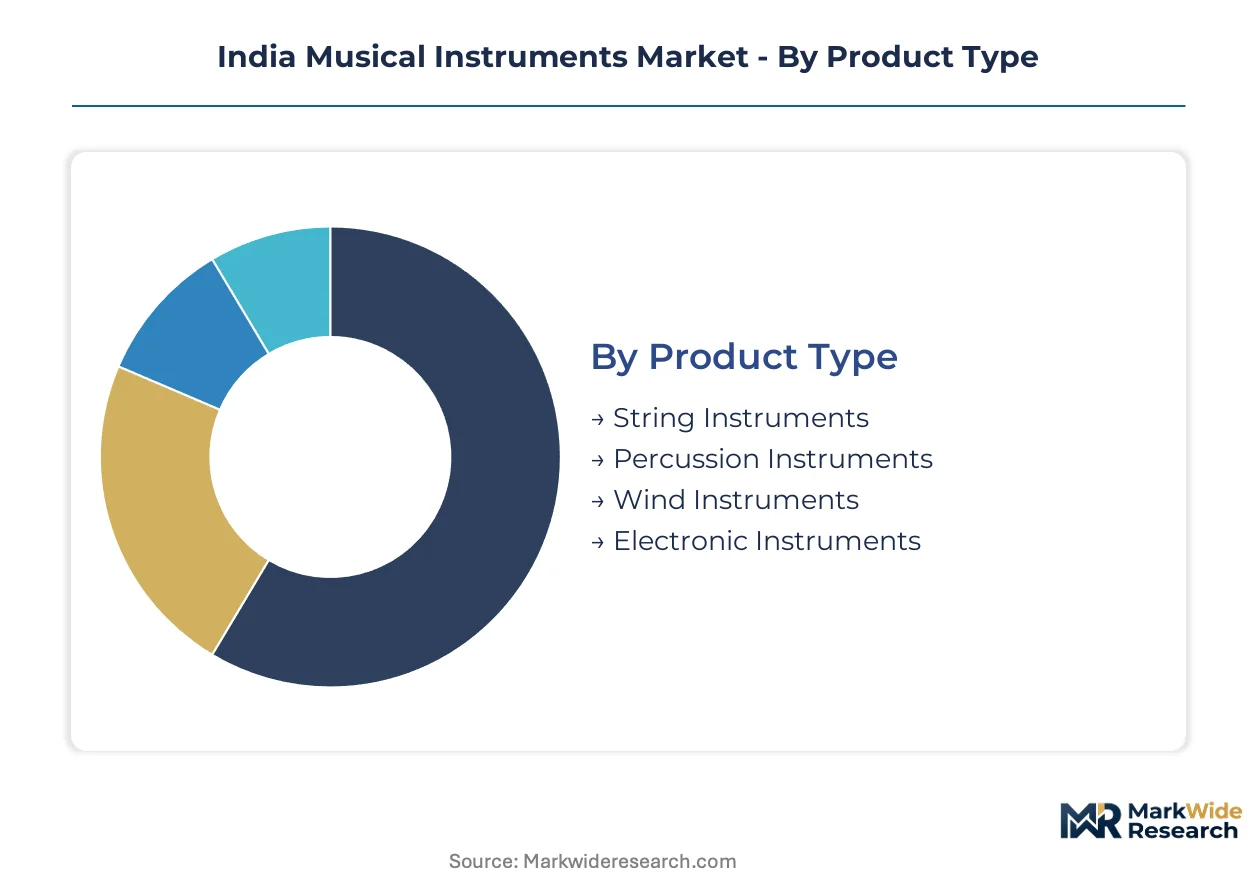
Segmentation in the India musical instruments market reveals how substitution pressures fragment procurement patterns across acoustic heritage categories and electronic alternatives. Understanding these divides exposes where BIS certification burdens and skilled luthier scarcity reshape competitive terrain most acutely.
Product Type:
Electronic instruments face the most intense substitution pressure as MIDI controllers and software-based production tools compress demand for traditional acoustic platforms across hobbyist segments.
- String Instruments:Crafted from seasoned tonewood with functional parameters spanning resonance sustain and frequency range. Demand concentrates among professional performing artists in Chennai's Carnatic ecosystem and Mumbai's film studio infrastructure, where replacement cycles remain sustained despite digital encroachment.
- Electronic Instruments:Generated through semiconductor arrays with signal-to-noise ratios as core functional metrics. Demand is accelerating fastest among hobbyists migrating toward digital workstations and MIDI controllers, though BIS certification mandates impose testing timelines that delay import clearance.
- Percussion Instruments:Acoustic variants crafted from wood and metal serving commercial performance and cultural ceremony applications.
- Wind Instruments:Brass and woodwind categories serving pedagogical instruction and institutional procurement.
String instruments anchor the volume base while electronic instruments gain share at the steepest rate.
End User:
Cost tier stratification separates institutional buyers with captive procurement budgets from individual purchasers facing acute price sensitivity.
- Performing Artists:Professional-grade instrument procurement with replacement cycles tied to performance revenue stability. Demand concentrates in Maharashtra and Tamil Nadu where film studio infrastructure and Carnatic training institutes sustain premium purchases.
- Schools:Institutional procurement driven by expanding classical music training cohorts with bulk acquisition protocols. Procurement is fragmenting across acoustic heritage models and hybrid electronic-acoustic platforms as student preferences diverge.
- Professionals:Session musicians and studio players requiring sustained replacement cycles for professional-grade equipment.
- Hobbyists:Price-sensitive segment gravitating toward portable electronic alternatives and augmented reality preview tools at online retailers.
Schools anchor the volume base while hobbyists expand most quickly as digital platforms lower entry barriers.
Distribution Channel:
Geography determines channel viability as tier-two and tier-three cities lack legacy music shop density to support physical trial infrastructure.
- Online Retailers:Deploying augmented reality-based instrument visualization to capture share from legacy music shops. Channel enables geographic expansion without physical showroom investment, particularly effective among hobbyist segments in tier-two cities.
- Music Shops:Traditional channel sustaining dominance in Chennai and Mumbai where physical trial remains essential for professional performing artists. Heritage handcraft clusters depend on these outlets for seasoned tonewood instrument distribution.
- Department Stores:Mass-market channel serving budget-tier electronic instruments and entry-level acoustic categories.
- Direct Sales:Manufacturer-controlled channel for premium and luxury tier instruments with custom specification requirements.
Music shops anchor the volume base while online retailers climb the fastest as AR tools displace physical trial visits.
Price Tier:
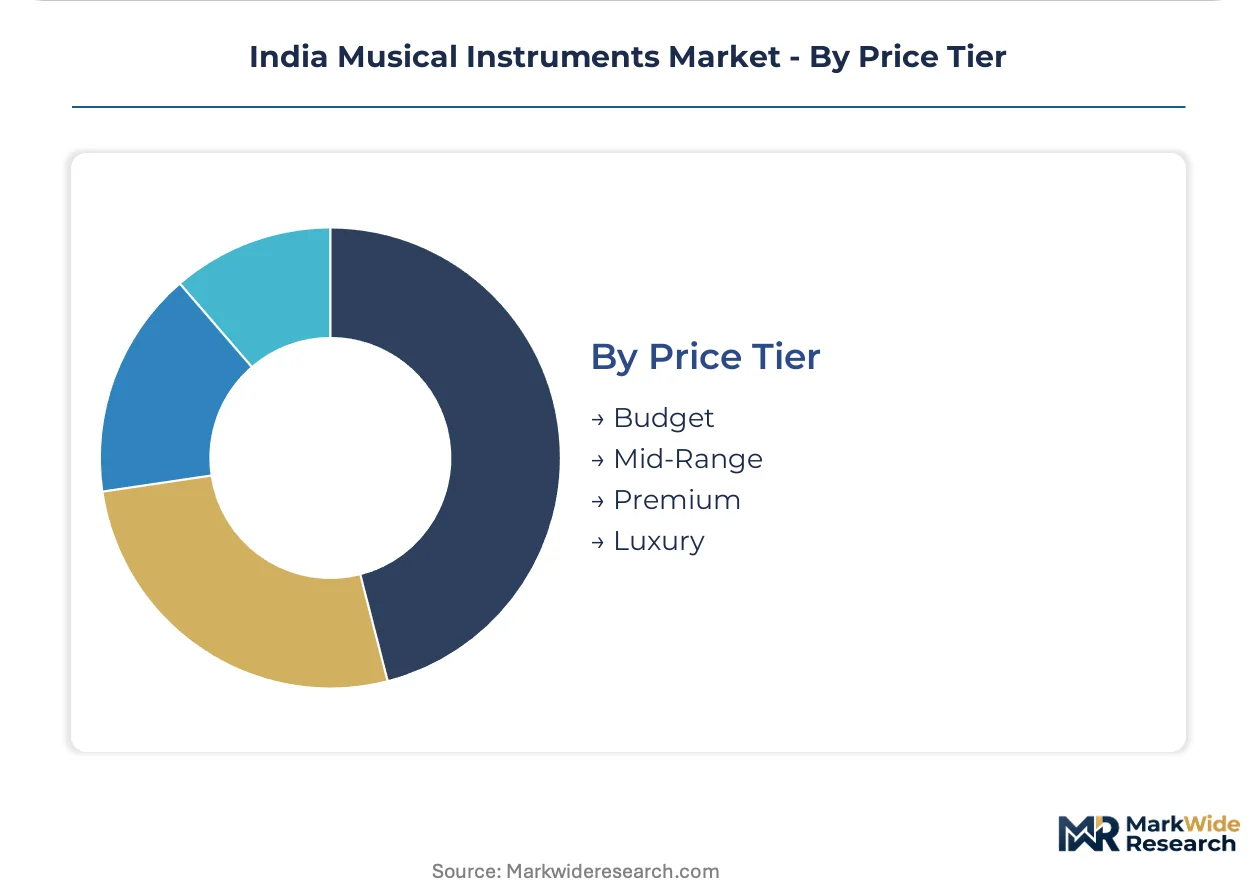
Margin concentration separates heritage handcraft clusters serving luxury segments from mechanized production corridors capturing volume at budget and mid-range levels.
- Premium:Professional-grade instruments with specifications meeting institutional procurement standards. Demand concentrates among performing artists and schools in Tamil Nadu's Carnatic ecosystem where acoustic traditions persist.
- Luxury:Heritage handcraft instruments from captive tonewood supply with extended production timelines. Haribhau Vishwanath Musical Industries sustains dominance through domestic forest-sourced materials.
- Budget:Entry-level electronic and acoustic instruments serving price-sensitive hobbyist segments.
- Mid-Range:Intermediate specifications targeting advancing students and semi-professional players.
Premium tier anchors the volume base while luxury tier gains share fastest as professional artists prioritize heritage craftsmanship.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification requirements and the PLI scheme for electronics anchor Maharashtra's regulatory environment, concentrating instrument manufacturing capacity and film studio procurement in India's western economic corridor.
Maharashtra
Mumbai's film studio infrastructure sustains replacement cycles for professional-grade string and percussion instruments among session musicians. CEA electrical safety standards for electronic instruments demand design modifications that complicate platform sharing with international product lines. Pune's mechanized production corridors host assembly operations for digital keyboards targeting tier-two city distribution.
Tamil Nadu
Chennai's Carnatic music ecosystem drives premium instrument procurement from institutional training programs and professional performing artists. CDSCO oversight on materials contacting human skin requires reformulation of finishes and hardware for string instruments. Thanjavur's heritage handcraft clusters face generational transfer gaps as traditional luthier training periods exceed younger worker retention thresholds.
Karnataka
Bengaluru's technology workforce generates hobbyist demand for MIDI controllers and digital workstations. BIS electromagnetic compatibility testing requirements are elevating compliance costs for electronic instrument importers. The city's online retailer concentration deploys augmented reality preview tools to capture share from legacy music shops across southern India.
Gujarat
Surat's synthetic materials processing base supplies component inputs for budget-tier electronic instruments. DGFT import documentation protocols intersect with BIS certification timelines to delay market entry for cross-border sellers. Ahmedabad's distribution networks penetrate tier-three cities where physical music shop density remains insufficient.
Delhi-NCR
Institutional procurement from national music academies concentrates in the capital region's training infrastructure. PLI scheme incentives for electronic manufacturing attract firms establishing local assembly of synthesizers. Noida's logistics corridors enable fulfillment economics for domestic manufacturers competing against cross-border e-commerce inventory.
India Musical Instruments Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with heritage handcraft specialists commanding premium positioning while mechanized assemblers capture volume at mid-range tiers. The vendor base separates into three strategic groupings: Japanese multinationals with dedicated R&D facilities, domestic heritage craftsmen with captive tonewood supply, and electronics specialists leveraging PLI scheme incentives. Competitive moves concentrate on channel control expansion across tier-two cities and backward integration into component manufacturing.
Among Japanese multinationals, Yamaha Corporation and Casio occupy positions representing technology-forward archetypes with India-specific tonal adaptation capabilities. Haribhau Vishwanath Musical Industries exemplifies the heritage handcraft tier through its dominance in traditional string instruments. Roland Corporation and Kawai Musical Instruments Mfg Co. Ltd sit within the premium electronic segment where BIS certification requirements reshape competitive positioning.
| Leading Market Players |
|---|
| Kawai Musical Instruments Mfg Co. Ltd |
| Casio |
| Yamaha Corporation |
| Haribhau Vishwanath Musical Industries |
| Bina Musical Stores |
| Roland Corporation |
| Cor-Tek Corporation |
| Radel Electronics |
| Fender Musical Instruments Corp |
| Others |
Supply & Pricing Matrix
Mechanized production corridors in Maharashtra and Gujarat achieve scale efficiencies that compress per-unit costs for electronic instruments while heritage handcraft clusters in Tamil Nadu maintain price floors through captive tonewood scarcity. This bifurcation concentrates pricing power with domestic manufacturers holding BIS certification and seasoned wood reserves, forcing import-dependent brands into margin compression.
Pricing Analysis
Maharashtra commands premium pricing for professional-grade string instruments used in Mumbai's film studios, while Gujarat's synthetic materials base enables aggressive budget-tier positioning for electronic keyboards. Three-tier pricing structure across premium, standard, and economy levels separates heritage craftsmanship from mechanized assembly and mass-market imports. Cost compression in the hobbyist electronic segment is intensifying because MIDI controller substitution erodes acoustic instrument demand. Schools exhibit highest price sensitivity due to bulk procurement protocols, while performing artists in Chennai's Carnatic ecosystem demonstrate lowest sensitivity as acoustic traditions override cost considerations.
Supply Chain Analysis
Strategic stockpiling of seasoned tonewood dominates heritage handcraft procurement, while electronic instrument assemblers favor just-in-time component flows from China, Taiwan, and South Korea. Semiconductor arrays, synthetic keybed materials, and electromagnetic shielding components draw from East Asian manufacturing hubs. Single-source vulnerability concentrates in specialized DSP chip supply for digital keyboards. Distribution runs through tier-two city distributor networks for electronic brands, while heritage instruments depend on Chennai and Mumbai music shop density for professional artist access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional training programs consolidating procurement volumes, fragmenting individual artist purchasing into smaller discretionary decisions. This consolidation elevates schools and music academies as price-setters while compressing margins for brands dependent on hobbyist fragmentation.
For Market Incumbents: Fortify BIS certification moats by establishing captive testing laboratories to compress electromagnetic compliance timelines for electronic keyboards. Deepen backward integration into domestic tonewood reserves to secure supply against harvest restrictions threatening Thanjavur's heritage clusters. Channel control expansion across tier-three cities remains essential as online retailers with augmented reality tools erode legacy music shop dominance. For New Entrants and Emerging Players: Anchor in Bengaluru's technology workforce hobbyist segment where MIDI controller demand outpaces acoustic instrument replacement cycles. The most penetrable white space sits in mid-range electronic-acoustic hybrid platforms for advancing students seeking portable practice solutions. A direct-to-consumer go-to-market angle leveraging augmented reality preview tools bypasses legacy channel infrastructure concentrated in Maharashtra and Tamil Nadu. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electronic instrument manufacturers with firmware-upgradeable feature architectures and subscription-based learning platform integrations. Long-term viability favors firms combining PLI scheme incentives with India-specific R&D capabilities rather than pure import-reliant distribution plays. Acquisition targets should demonstrate established BIS certification pathways and captive component sourcing from Surat's synthetic materials base. The signal to watch is e-commerce inventory labeling rule implementation timing, which will reshape fulfillment economics for cross-border sellers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tonewood Reserves | Secures captive supply for heritage handcraft clusters against CDSCO materials compliance extending development cycles. |
| BIS Certification Laboratory Investment | Compresses electromagnetic testing timelines for electronic keyboards facing DGFT import documentation friction. |
| Tier-Two City Distributor Control | Captures hobbyist demand in geographies where legacy music shop density cannot support physical trial infrastructure. |
| Augmented Reality Preview Deployment | Enables online retailers to displace Chennai and Mumbai music shop dominance without showroom capital expenditure. |
| PLI Scheme Manufacturing Localization | Offsets assembly costs for digital keyboards while creating protected terrain against forthcoming e-commerce labeling rules. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with instrument manufacturers, music school procurement directors, distributor channel heads, and professional performing artists across Maharashtra and Tamil Nadu. Secondary validation drew from BIS certification registries, CDSCO materials safety filings, PLI scheme beneficiary disclosures, and customs import documentation patterns. Bottom-up triangulation across product category shipment data and top-down reconciliation against institutional procurement budgets anchored volume estimates.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, end-user archetype, distribution channel, and price tier, with regional regulatory cluster effects layered for BIS and CEA compliance zones. CAGRs were derived from replacement cycle analysis for professional artists, student cohort expansion rates at classical training institutes, and substitution elasticity estimates for electronic platforms. Industry-specific inputs included Carnatic music ecosystem institutional procurement patterns and Mumbai film studio infrastructure utilization rates.
Underlying assumptions cover sustained PLI scheme incentive continuity and stable tonewood harvest permissions, with deviation risk concentrated in BIS certification timeline extensions and generational luthier training gaps. Forecasts reflect these conditions without explicit probability weighting. Revision becomes warranted when e-commerce inventory labeling rule enforcement crosses thresholds that fundamentally alter cross-border seller fulfillment economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
North America Fashion Accessories Market
Consumer Goods
Hair Mask Market
Consumer Goods
Fine Mist Sprayer Market
Consumer Goods
France Cookware Market
Consumer Goods
Europe Gaming Headset Market
Consumer Goods
Global Baseball Gloves Market
Consumer Goods
Earplugs Market
Consumer Goods
Europe Beauty and Personal Care Products Market
Consumer Goods
Automated Blinds and Shades Market
Consumer Goods
Refurbished Running Shoes Market
Consumer Goods
Apparel and Leather Products Market
Consumer Goods
Cannabidiol CBD Pet Market
Consumer Goods
Global Personal Care Electrical Appliances Market
Consumer Goods
Kids Musical Instrument Market
Consumer Goods
Slovakia Home Appliances Market
Consumer Goods
Matte Lipstick Market