
 Smart Musical Instrument Market | 2026-2036
Smart Musical Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Musical Instrument Market Analytics
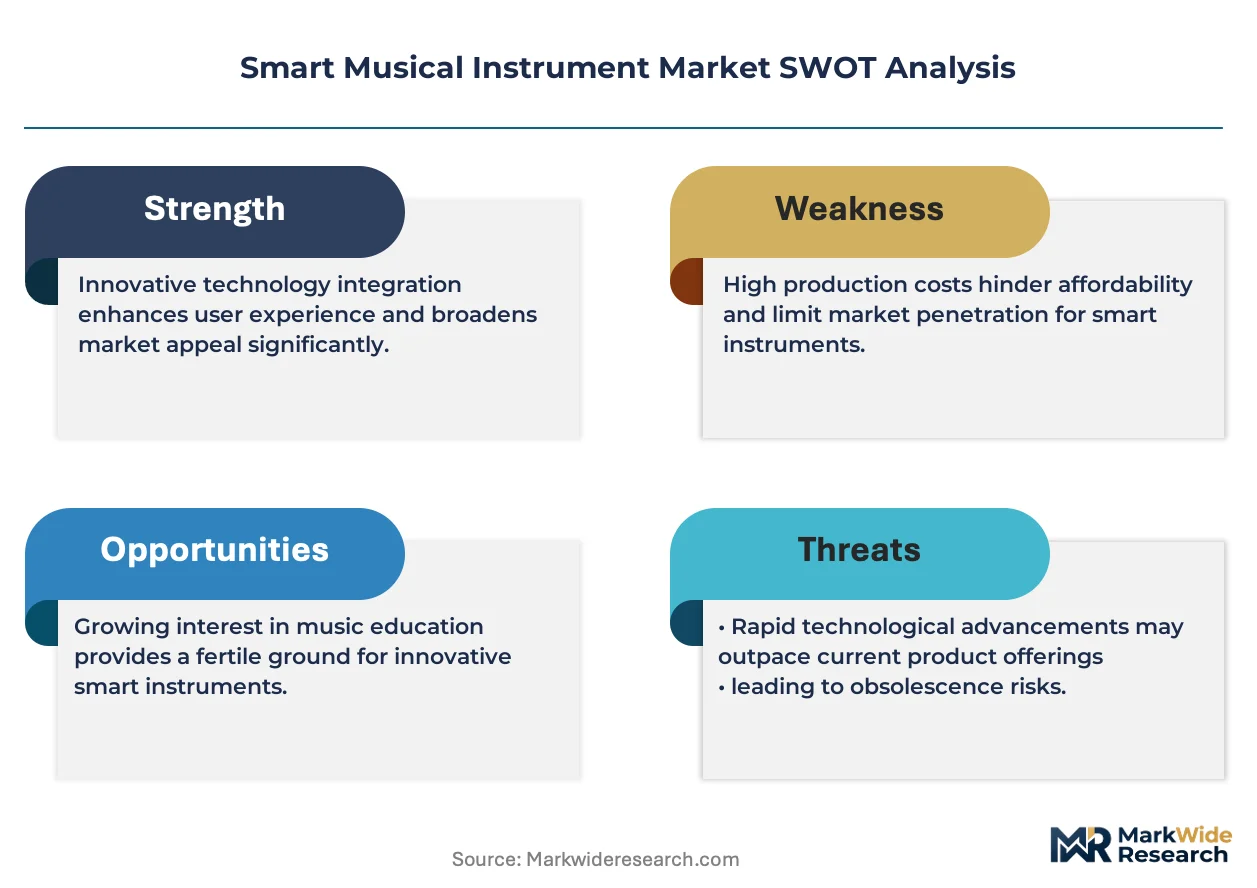
Advanced polymer composites are replacing traditional wood bodies in electronic guitars, which is restructuring bill-of-materials economics across the Smart Musical Instrument landscape. Yamaha leverages its captive semiconductor sourcing to sustain margin control on touch-sensor arrays. Roland anchors its position through specialized R&D on haptic feedback engines for digital pianos. Korg competes by dominating compact MIDI controller segments in Asia-Pacific retail channels.
Smart musical instruments integrate embedded sensors, wireless connectivity modules, and software platforms to capture player biometric data, transmit performance metrics, and enable real-time digital audio workstation synchronization. Digital pianos command the largest installed base, though augmented reality-enabled instruments represent the fastest-expanding margin pool as schools adopt immersive music education curricula. Bluetooth connectivity has matured into a baseline specification, while Wi-Fi streaming capabilities differentiate premium tiers for professional recording applications.
The Federal Communications Commission governs wireless transmission standards for Bluetooth and Wi-Fi modules in US-distributed instruments, while the EU Radio Equipment Directive mandates CE marking for all connected devices entering European markets. China's Ministry of Industry and Information Technology enforces GB standards for electromagnetic compatibility in consumer electronics with embedded radios. Stakeholders must monitor evolving spectrum allocation rulings and interoperability certification requirements as regulatory fragmentation across major economies intensifies compliance complexity.
Market Dynamics
Bluetooth Low Energy and haptic feedback integration are compressing product development cycles while forcing legacy manufacturers to restructure R&D staffing models around embedded systems engineering.
Growth Catalysts
- K-12 Music Education Mandates:School districts in the United States are expanding digital instrument procurement for STEM-integrated curricula. Federal ESSA funding flexibility allows music technology to qualify for Title I allocations.
- REACH Compliance Migration:European manufacturers are accelerating replacement of restricted substances in polymer composite bodies. This is opening specification windows for advanced material suppliers.
- Haptic Engine Miniaturization:Precision actuator costs are declining through smartphone supply chain spillover. Digital piano manufacturers are integrating force-feedback keybeds at mid-tier price points.
Market Restraints
- Semiconductor Input Volatility:Touch-sensor array controllers face allocation pressure from automotive and medical device demand. Captive foundry relationships remain concentrated among Japanese and Taiwanese suppliers.
- GB Standards Certification Burden:China's MIIT electromagnetic compatibility testing adds six-to-nine month pre-market timelines. Smaller developers lack in-country testing facility relationships.
- Acoustic Instrument Persistence:Traditional wood-body guitars retain preference among professional recording engineers. Studio procurement committees specify analog signal chains for vintage tone requirements.
Strategic Opportunities
- Immersive Education Software Bundling:Augmented reality lesson platforms represent whitespace for hardware-software integration. German conservatory networks are piloting mixed-reality ensemble training.
- India PLI Scheme Alignment:Electronics manufacturing incentive thresholds now include connected consumer devices. Contract assemblers are qualifying Bluetooth module surface-mount lines for instrument OEMs.
- Subscription Firmware Monetization:Continuous feature delivery models are displacing one-time software licensing. Student users in China demonstrate higher lifetime value under recurring payment structures.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for real-time audio latency requires specialized DSP optimization skills. Music technology employers compete with gaming and automotive sectors for qualified candidates.
- Cross-Platform Synchronization Complexity:Proprietary digital audio workstation protocols fragment connectivity standards. Manufacturers must maintain multiple certification streams for Ableton, Logic, and FL Studio compatibility.
- RoHS Substance Tracking:Supply chain documentation for solder and finish materials demands dedicated compliance personnel. Mid-size brands lack ERP systems with automated supplier attestation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Musical Instrument Market |
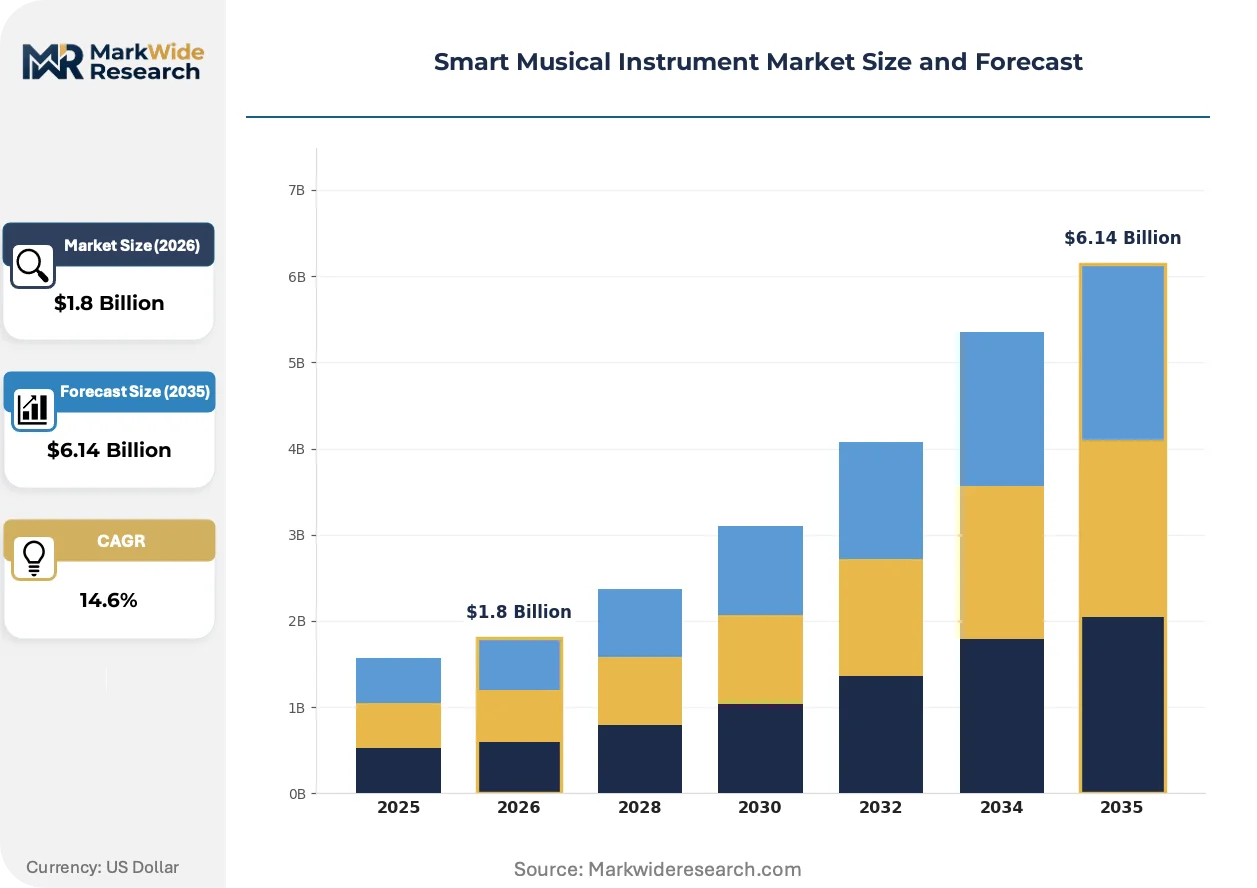
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Pianos, Electronic Guitars, Smart Drums, MIDI Controllers Technology: Bluetooth, Wi-Fi, Touch Sensors, Augmented Reality End User: Students, Professionals, Hobbyists, Schools Application: Music Education, Performance, Composing, Recording |
| Companies Covered | LiteJam, Kawai, Roland, Pearl River Piano Group, Casio, Yamaha, Jamstik, Behringer, Korg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Musical Instrument Market Evolving Landscape
Real-time biometric capture and wireless protocol convergence are restructuring how instruments interface with learning platforms and recording environments.
Advanced polymer composites are absorbing traditional wood-body functions in electronic guitar manufacturing. K-12 procurement departments are specifying these instruments for durability in classroom settings. The shift is compressing material cost curves while enabling consistent acoustic properties across production batches.
The EU Radio Equipment Directive is tightening CE marking documentation requirements for wireless-enabled devices. Manufacturers must now submit detailed radio spectrum usage declarations for Bluetooth and Wi-Fi modules. German distributors are demanding pre-certified module integration to avoid customs detention at Rotterdam and Hamburg ports.
Institutional purchasing committees are unbundling after-sales service from hardware procurement. United States school districts now negotiate separate maintenance contracts with regional AV integrators. This fragmentation is compressing OEM service margins while elevating third-party technical certification requirements.
Smart Musical Instrument Market Segmentation
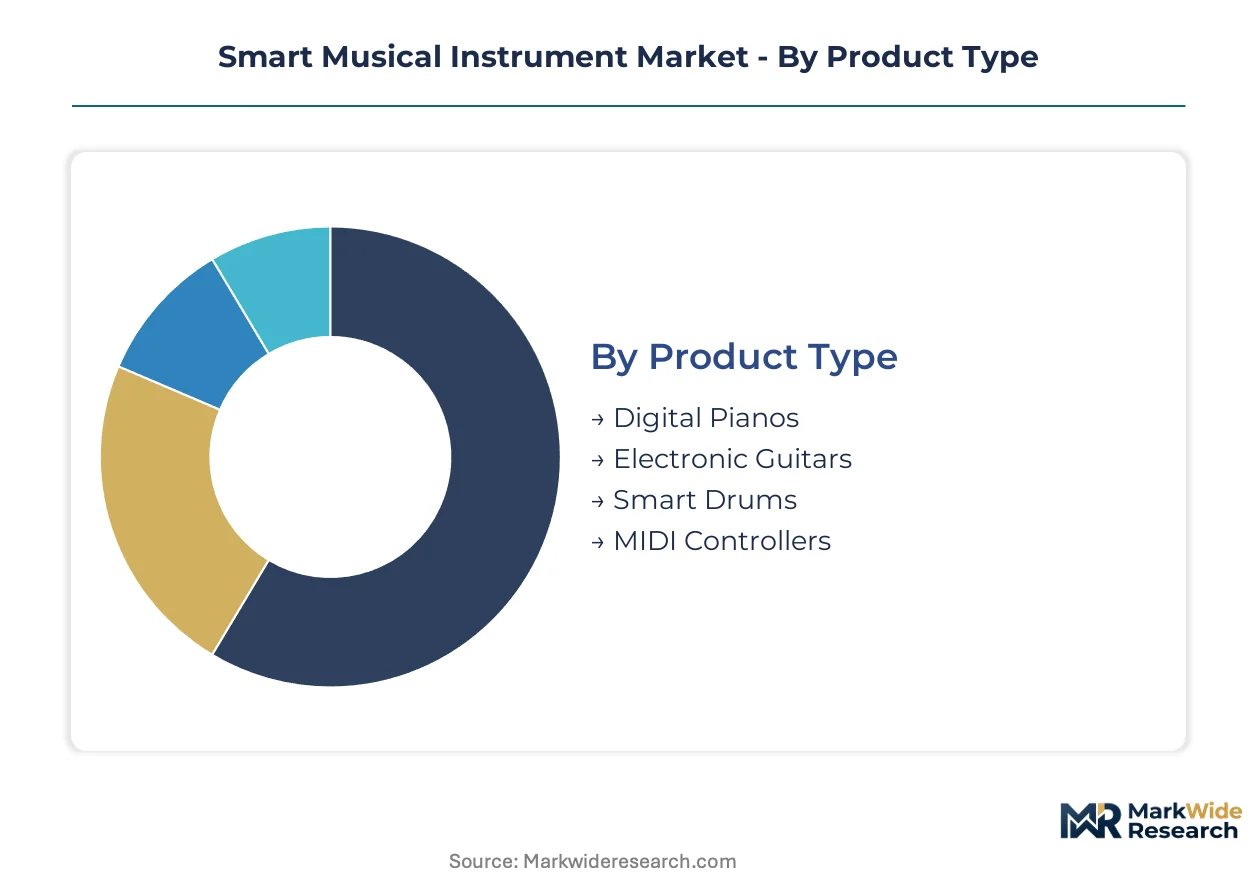
Product architecture in smart musical instruments fragments across connectivity protocols, player skill levels, and use-case intensity. Manufacturers configure hardware specifications and software bundles differently for institutional procurement versus individual consumers. Understanding these segment boundaries clarifies where margin pools concentrate and which technical features command pricing premiums.
Product Type:
Standardization dominates entry-level SKUs while professional tiers demand extensive customization in keybed action, sensor density, and output configurations.
- Digital Pianos:Hammer-action keybeds with graded weighting replicate acoustic piano response. Demand concentrates in United States school districts purchasing ESSA-funded STEM-music integration labs, constrained by maintenance contract fragmentation that compresses OEM service margins.
- Electronic Guitars:Advanced polymer composite bodies replace traditional wood for durability in K-12 classroom environments. German conservatory networks specify these for mixed-reality ensemble training pilots, though acoustic purists in professional recording studios resist adoption.
- Smart Drums:Mesh heads with piezoelectric triggering enable volume-controlled practice. Mid-tier pricing benefits from smartphone haptic engine supply chain spillover.
- MIDI Controllers:Compact form factors dominate Asia-Pacific retail channels. Korg's channel control in Japan and Taiwan shapes regional specification standards.
Leading the category by volume: Digital Pianos. Expanding most quickly: Electronic Guitars.
Technology:
Cost tier stratification separates baseline connectivity from premium streaming capabilities that differentiate professional recording tiers.
- Bluetooth:Low Energy protocols have matured into baseline specifications across all price tiers. United States FCC Part 15 compliance governs transmission power limits, while EU Radio Equipment Directive CE marking requirements intensify documentation burdens for Rotterdam and Hamburg port entry.
- Wi-Fi:Streaming capabilities enable real-time digital audio workstation synchronization with sub-10ms latency. Professional recording applications in Germany and China drive specification premiums, though spectrum allocation rulings across major economies fragment certification complexity.
- Touch Sensors:Capacitive arrays capture biometric player data for learning platform integration. Automotive and medical device demand creates allocation pressure on controller chips.
- Augmented Reality:Immersive lesson platforms represent the steepest expansion trajectory as schools adopt STEM-integrated curricula. Hardware-software bundling whitespace attracts firmware monetization strategies.
Bluetooth dominates unit shipments. Augmented Reality climbs fastest in education verticals.
End User:
Application intensity varies dramatically between institutional procurement with formal RFP processes and individual purchase decisions driven by feature accessibility.
- Students:Subscription firmware models demonstrate higher lifetime value under recurring payment structures in China. ESSA funding flexibility allows music technology to qualify for Title I allocations in United States districts.
- Professionals:Analog signal chain requirements persist in studio environments. Vintage tone specifications from recording engineers constrain smart instrument penetration.
- Hobbyists:Price-sensitive segment with preference for compact MIDI controllers. Asia-Pacific retail channels optimize for this demographic.
- Schools:K-12 procurement committees unbundle after-sales service from hardware, elevating third-party AV integrator certification requirements.
Schools drive institutional volume. Students represent the fastest-growing recurring revenue base.
Application:
Customer type alignment shapes whether instruments emphasize pedagogical feedback loops or low-latency performance specifications.
- Music Education:Biometric capture and real-time lesson synchronization dominate product requirements. German pilot programs for mixed-reality ensemble training establish reference architectures.
- Performance:Wireless protocol reliability under stage conditions mandates redundant connectivity. FCC and EU Radio Equipment Directive compliance ensures cross-border touring compatibility.
- Composing:Digital audio workstation synchronization demands multi-protocol certification streams. Ableton, Logic, and FL Studio compatibility maintenance fragments engineering resources.
- Recording:Analog signal chain persistence among professional engineers limits smart instrument specification. Studio procurement committees specify vintage tone requirements.
Music Education leads application volume. Composing gains share fastest through software bundling strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for electronics manufacturing is attracting contract assemblers to set up Bluetooth module surface-mount lines for instrument OEMs. This tax-incentive zone is accelerating regional supply chain reconfiguration across Asia-Pacific.
United States
K-12 school districts in Texas and California are expanding ESSA-funded STEM-music integration labs with digital piano procurement. The FCC governs Bluetooth and Wi-Fi transmission standards under Part 15 rules. Nashville's music technology cluster anchors professional recording equipment distribution.
Germany
Conservatory networks in Berlin and Leipzig are piloting mixed-reality ensemble training with augmented reality-enabled instruments. The EU Radio Equipment Directive mandates CE marking with detailed radio spectrum declarations. Hamburg's port logistics handle pre-certified module imports to avoid customs detention.
China
Student users in Shanghai and Beijing demonstrate higher lifetime value under subscription firmware models. MIIT enforces GB standards for electromagnetic compatibility with six-to-nine month pre-market timelines. Shenzhen's electronics manufacturing base concentrates haptic engine component sourcing.
Japan
Digital-native student populations in Tokyo and Osaka drive compact MIDI controller demand through retail channels. METI oversees industrial standards coordination for consumer electronics with embedded radios. Hamamatsu's musical instrument manufacturing heritage sustains specialized R&D on sensor arrays.
South Korea
Hobbyist segments in Seoul favor price-sensitive wireless-enabled practice instruments. The country's national telecommunications regulator manages spectrum allocation for Bluetooth Low Energy devices. Busan's port infrastructure supports component import for domestic assembly operations.
Smart Musical Instrument Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with established instrument makers defending position through captive semiconductor relationships and embedded systems capabilities. The vendor base concentrates among Japanese and Taiwanese suppliers with foundry access. Three archetypes dominate: heritage acoustic brands pivoting to sensor integration, pure-play digital natives, and electronics contract manufacturers. Competitive moves center on haptic feedback engine miniaturization and firmware monetization through subscription models.
Within the heritage instrument tier, Yamaha and Roland exemplify archetypes of vertical integration into semiconductor sourcing and specialized haptic R&D respectively. Korg occupies a position among compact controller specialists with channel control in Asia-Pacific retail. These three Japanese manufacturers represent the competitive core around which mid-tier and contract assembly players organize positioning.
| Leading Market Players |
|---|
| LiteJam |
| Kawai |
| Roland |
| Pearl River Piano Group |
| Casio |
| Yamaha |
| Jamstik |
| Behringer |
| Korg |
| Others |
Value Network & Pricing Analysis
K-12 procurement committees in United States school districts concentrate buying power through consolidated ESSA-funded tenders, anchoring contract-based pricing with multi-year maintenance bundles that compress spot-market flexibility for smaller OEMs.
Pricing Analysis
Short lead-time premiums attach to haptic engine components sourced from smartphone supply chain spillover, while spot inventory discounts emerge for Bluetooth modules facing allocation pressure. Three-tier pricing structure across premium, standard, and economy levels separates Wi-Fi-enabled professional recording tiers from BLE-baseline education SKUs. Cost compression in mid-tier digital pianos intensifies because semiconductor input volatility from automotive demand crowds out controller chip availability. Hobbyists in Asia-Pacific retail channels exhibit highest price sensitivity, while German conservatory networks show lowest sensitivity due to specification-driven procurement.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States school district consortia, while Asia-Pacific retail distribution feeds compact MIDI controller volume through Korg's channel control. Component sourcing concentrates in Japan for Yamaha's captive semiconductor relationships, Taiwan for touch-sensor array foundries, and China for haptic engine miniaturization. Raw material dependencies include advanced polymer composites replacing wood bodies, precision actuators from smartphone supply chains, and BLE/Wi-Fi radio modules. Single-source vulnerability in Japanese and Taiwanese foundry relationships elevates allocation risk. Distribution runs through Hamburg and Rotterdam ports for EU Radio Equipment Directive pre-certified modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints prop pricing power for manufacturers with captive sourcing relationships, creating a supply-constrained market structure favoring incumbents with backward integration.
For Market Incumbents: Deploy firmware monetization through subscription models to lock in student lifetime value in China. Deepen backward integration into haptic engine component sourcing to offset smartphone sector competition for precision actuators. Consolidate channel control in Asia-Pacific retail to defend against emerging compact controller specialists. For New Entrants and Emerging Players: Augmented reality lesson platform integration offers a technology-first wedge into German conservatory pilot programs. White-space concentrates in immersive education software bundling for K-12 STEM-music integration. Target India PLI scheme-aligned contract assembly partnerships to bypass China's six-to-nine month MIIT certification timelines. For Investors and Strategic Acquirers: The window for entry favors mid-tier brands with embedded systems engineering capabilities and ERP systems capable of automated RoHS substance tracking. Long-term viability hinges on firmware monetization infrastructure and cross-platform DAW synchronization competence. Watch for inflection in spectrum allocation rulings across major economies fragmenting certification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Haptic Engine Miniaturization Investment | Captures smartphone supply chain spillover cost declines for mid-tier digital piano integration. |
| Subscription Firmware Monetization | Locks in higher lifetime value from Chinese student users under recurring payment structures. |
| India PLI Scheme Alignment | Qualifies contract assemblers for tax incentives on Bluetooth module surface-mount lines. |
| Augmented Reality Platform Integration | Enables hardware-software bundling whitespace in German mixed-reality ensemble training pilots. |
| Pre-Certified Module Integration | Avoids EU Radio Equipment Directive customs detention at Rotterdam and Hamburg ports. |
Research Methodology
SEC filings from instrument OEMs, customs trade data on polymer composite imports, and FCC equipment authorization databases formed the secondary backbone. Primary interviews with digital piano product managers, BLE module procurement leads at contract manufacturers, K-12 music technology coordinators, and haptic engine component suppliers validated demand assumptions. Bottom-up unit shipment estimates triangulated against top-down education technology spending allocations.
Historical trendline analysis of digital instrument procurement cycles established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, connectivity protocol tier, end-user archetype, and application intensity dimensions. CAGRs derived from curve-fitting against ESSA funding trajectories and haptic engine cost decline curves. Industry-specific inputs included semiconductor allocation lead times and MIIT certification timeline distributions.
Several conditions sit outside the modeled scope, including sudden spectrum reallocation rulings, raw material substitution breakthroughs in bio-composites, and trade policy shifts affecting Taiwan-Japan component flows. Forecasts reflect documented assumptions on education funding continuity and wireless protocol standardization. Periodic stress-testing of base assumptions is recommended against semiconductor supply shocks and regulatory fragmentation intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Electric Guitar Market
Musical Instruments
Woodwind Instruments Market
Musical Instruments
Drum Sets Market
Musical Instruments
Kids Musical Instrument Market
Musical Instruments
Bass Guitar Market
Musical Instruments
Digital Ensemble Pianos Market
Musical Instruments
Global Piano Market
Musical Instruments
Electronic Musical Instruments Market
Musical Instruments
Electric Violin Market
Musical Instruments
Digital Piano Market
Musical Instruments
Classical Guitar Market
Musical Instruments
Guitar Market
Musical Instruments
Violin Market