
 Electric Pocket Lighter Market | 2026-2036
Electric Pocket Lighter Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Pocket Lighter Market Analysis
Outdoor enthusiast retail is recalibrating the Electric Pocket Lighter demand profile as camping and adventure sports channels expand shelf space for windproof, rechargeable units. Zippo Manufacturing Company leverages its heritage metalworking expertise to sustain premium positioning in collectible and gift segments. BIC USA Inc. competes on mass-market scale and convenience-store distribution density. Tokai Corporation anchors Asian supply relationships through precision ignition component manufacturing.
An electric pocket lighter is a handheld ignition device powered by rechargeable lithium-ion cells or disposable batteries, generating heat through resistive coil or plasma arc mechanisms to ignite combustible materials without open flame. Plasma variants employ high-voltage electrode discharge between ceramic nodes, achieving ignition temperatures exceeding 1,100 degrees Celsius in wind-resistant configurations. USB rechargeable models now lead product type growth as consumers reject recurring butane purchases, while household end users represent the mature volume base with thinner margins. Barbecue usage applications command premium pricing due to durability requirements and extended runtime specifications.
The US Consumer Product Safety Commission enforces child-resistance standards and battery safety protocols that shape product design thresholds for domestic market entry. China's SAMR oversees lithium-cell transportation and recycling mandates affecting export manufacturing compliance. The EU Battery Directive and REACH chemical frameworks restrict heavy metal content and establish end-of-life collection obligations for rechargeable units sold in member states. Stakeholders must monitor evolving carbon border adjustments and raw material sourcing certification requirements that will determine competitive access across major demand zones.
Market Dynamics
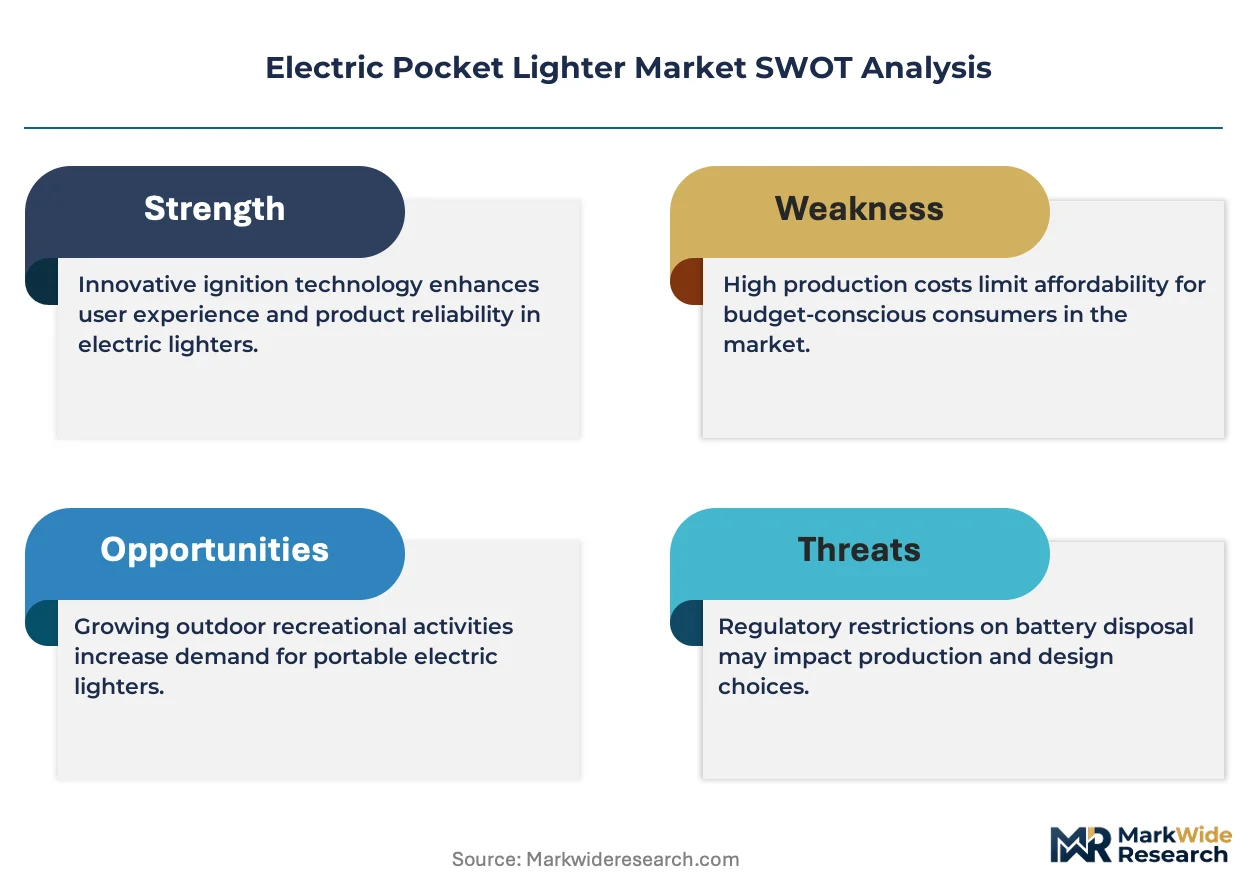
USB rechargeable lithium-ion technology is compressing the traditional butane lighter replacement cycle while indoor air quality mandates in food service and hospitality sectors accelerate flameless adoption curves.
Growth Catalysts
- Indoor air quality mandates:Municipal fire codes and ventilation standards in US and German food service sectors are mandating flameless ignition devices for enclosed dining environments.
- Camping retail channel expansion:Outdoor recreation retailers are allocating expanded shelf space to windproof plasma arc units targeting adventure sports participants.
- REACH chemical frameworks:EU restrictions on disposable butane canister waste streams are steering consumer preference toward rechargeable alternatives with established collection obligations.
Market Restraints
- Lithium-cell input volatility:Cobalt and nickel price fluctuations from Democratic Republic of Congo and Indonesian mining concentration create margin pressure for rechargeable unit assemblers.
- Plasma electrode technical limitation:Ceramic node degradation after 200-300 ignition cycles limits product lifespan in high-frequency commercial barbecue applications.
- SAMR transportation compliance:China's lithium-cell export certification requirements add 6-8 week lead times for manufacturing clusters in Guangdong and Zhejiang provinces.
Strategic Opportunities
- India outdoor recreation penetration:Underdeveloped camping equipment retail infrastructure in Maharashtra and Karnataka states offers first-mover positioning for rechargeable lighter distributors.
- Gift and collectible convergence:Premium metalworking heritage from Zippo Manufacturing's collectible segment can extend into limited-edition plasma arc releases.
- EU Battery Directive tailwind:End-of-life collection infrastructure subsidies in Germany and France reduce reverse logistics costs for rechargeable unit manufacturers.
Industry Challenges
- IP licensing complexity:Plasma arc electrode geometry patents held by Tokai Corporation and Chinese component suppliers create royalty stacking for new market entrants.
- Certification timeline compression:US Consumer Product Safety Commission child-resistance testing protocols require 14-18 month validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Pocket Lighter Market |
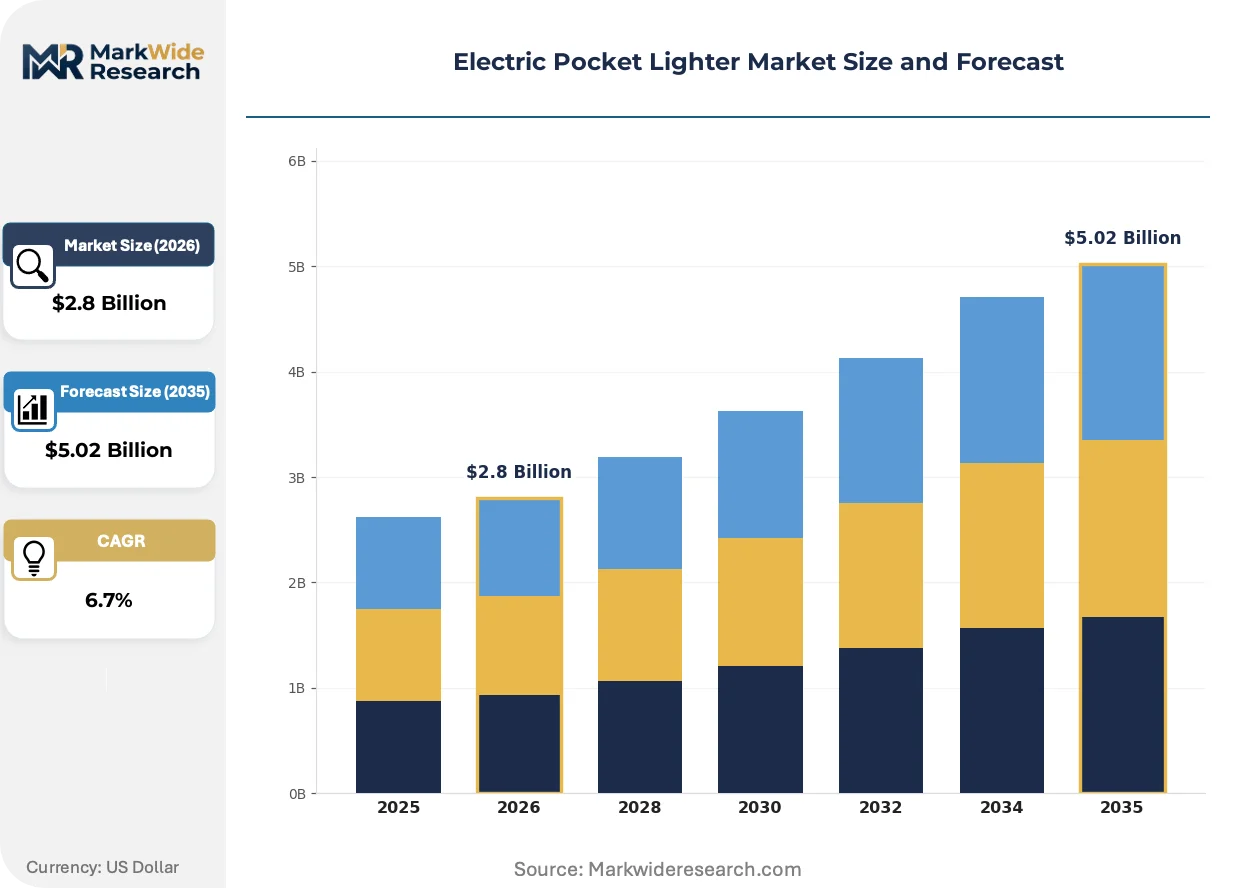
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzene lighters, Butane lighters, Electric lighters, Plasma lighters End User: Households, Restaurants, Bars, Outdoor enthusiasts Fuel Source: Butane, Electric, USB rechargeable, Solar Usage: Cigarettes, Candles, Barbecues, Campfires |
| Companies Covered | Zippo Manufacturing Company, BIC USA Inc., S.T. Dupont, Tokai Corporation, Colibri, Ningbo Xinhai Electric Co., BAIDE International Enterprise, Swedish Match, Flamagas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Pocket Lighter Market Emerging Trajectories
Product architecture is pivoting from fuel-based systems toward solid-state electronic ignition, with supply chains reorganizing around battery cell procurement and high-voltage component sourcing rather than pressurized hydrocarbon logistics.
Plasma arc ignition is rewriting competitive requirements for outdoor applications. The technology generates temperatures exceeding 1,100 degrees Celsius through high-voltage electrode discharge between ceramic nodes. Camping and adventure sports retailers are accelerating shelf resets to prioritize windproof configurations. This electronic foundation is compressing the addressable market for traditional butane windproof designs in exposed environments.
EU Battery Directive end-of-life collection obligations are restructuring manufacturer responsibility frameworks. The regulation mandates producer financing of rechargeable unit recycling infrastructure across member states. Premium-positioned brands with established European distribution networks are capturing compliance cost advantages over import-dependent competitors. Germany and France have operationalized the directive through national collection scheme participation requirements.
Convenience store channel consolidation is altering mass-market access patterns. Dollar store and pharmacy chain buyers are reducing SKU counts in disposable lighter categories while expanding rechargeable facings. This assortment shift favors suppliers with direct retail data integration capabilities. The restructuring is most visible in US suburban markets where tobacco accessory purchasing has migrated from independent retailers to national chains.
Electric Pocket Lighter Market Segmentation
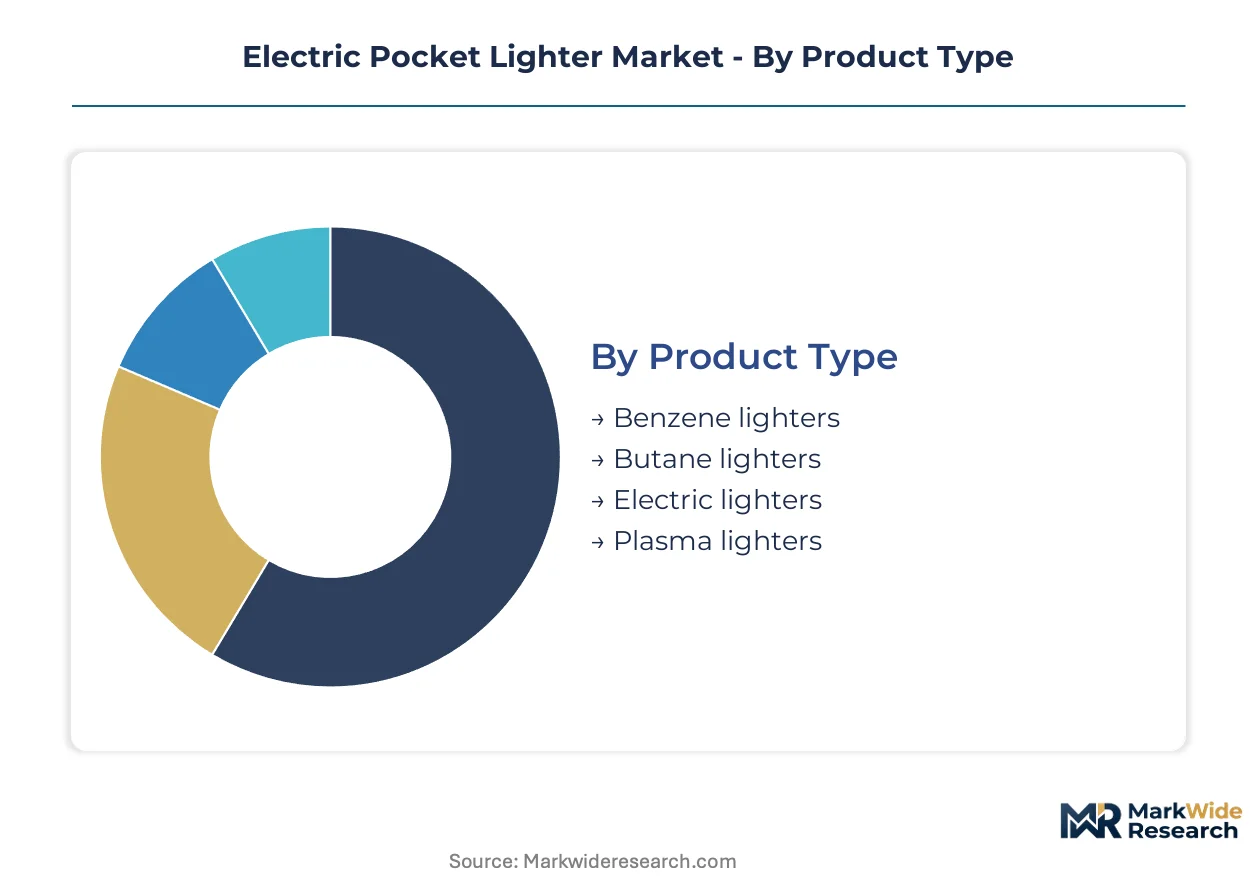
Electric pocket lighter segmentation reveals how technology substitution and use-case specificity are fragmenting demand across fuel types, power sources, and ignition applications. Manufacturers must align product specifications with end-user durability expectations and regulatory constraints governing indoor versus outdoor deployment.
Product Type:
Technical architecture distinguishes competitive positioning across ignition mechanisms and fuel delivery systems.
- Electric lighters:Resistive coil systems powered by lithium-ion cells generate heat through metal filament oxidation, achieving ignition temperatures suitable for standard combustibles. USB rechargeable configurations are displacing disposable fuel models in North American food service settings amid indoor air quality mandates.
- Plasma lighters:High-voltage electrode discharge between ceramic nodes produces arc temperatures exceeding 1,100 degrees Celsius in wind-resistant configurations. Camping and adventure sports retailers are accelerating shelf resets to prioritize these units for exposed outdoor environments.
- Benzene lighters:Traditional wick-based liquid fuel systems retain niche collectible and emergency backup demand.
- Butane lighters:Pressurized hydrocarbon ignition faces regulatory pressure from EU waste stream restrictions and municipal fire code limitations.
Electric lighters lead on scale; plasma lighters lead on momentum.
End User:
Procurement patterns diverge sharply between regulated commercial environments and discretionary consumer segments.
- Restaurants:Enclosed dining venues in US and German municipalities face mandatory flameless ignition requirements under ventilation and fire safety codes. Procurement concentrates on rechargeable units with extended runtime specifications for kitchen and service floor deployment.
- Households:Mature volume base with thinner margins, dominated by convenience-store purchasing patterns and price-sensitive replacement cycles. Dollar store and pharmacy chain consolidation is reducing SKU counts while expanding rechargeable facings.
- Bars:Nightlife venues adopt flameless units for patron safety and insurance compliance, though volume trails restaurant procurement.
- Outdoor enthusiasts:Underdeveloped retail infrastructure in Maharashtra and Karnataka states offers first-mover positioning for windproof plasma distributors.
Households anchor volume throughput; restaurants command premium pricing tiers.
Fuel Source:
Power architecture determines supply chain reorganization around battery procurement versus hydrocarbon logistics.
- USB rechargeable:Lithium-ion cell integration enables solid-state electronic ignition without recurring fuel purchases. China's SAMR oversees export certification requirements adding lead times for Guangdong and Zhejiang manufacturing clusters.
- Electric:Disposable battery configurations serve price-sensitive segments and emergency backup applications with lower upfront cost.
- Butane:Pressurized canister systems face EU Battery Directive tailwinds steering preference toward alternatives with established collection obligations.
- Solar:Photovoltaic cell integration targets extreme remote applications with extended off-grid deployment requirements.
USB rechargeable captures the steepest expansion trajectory; butane retains residual mass-market presence.
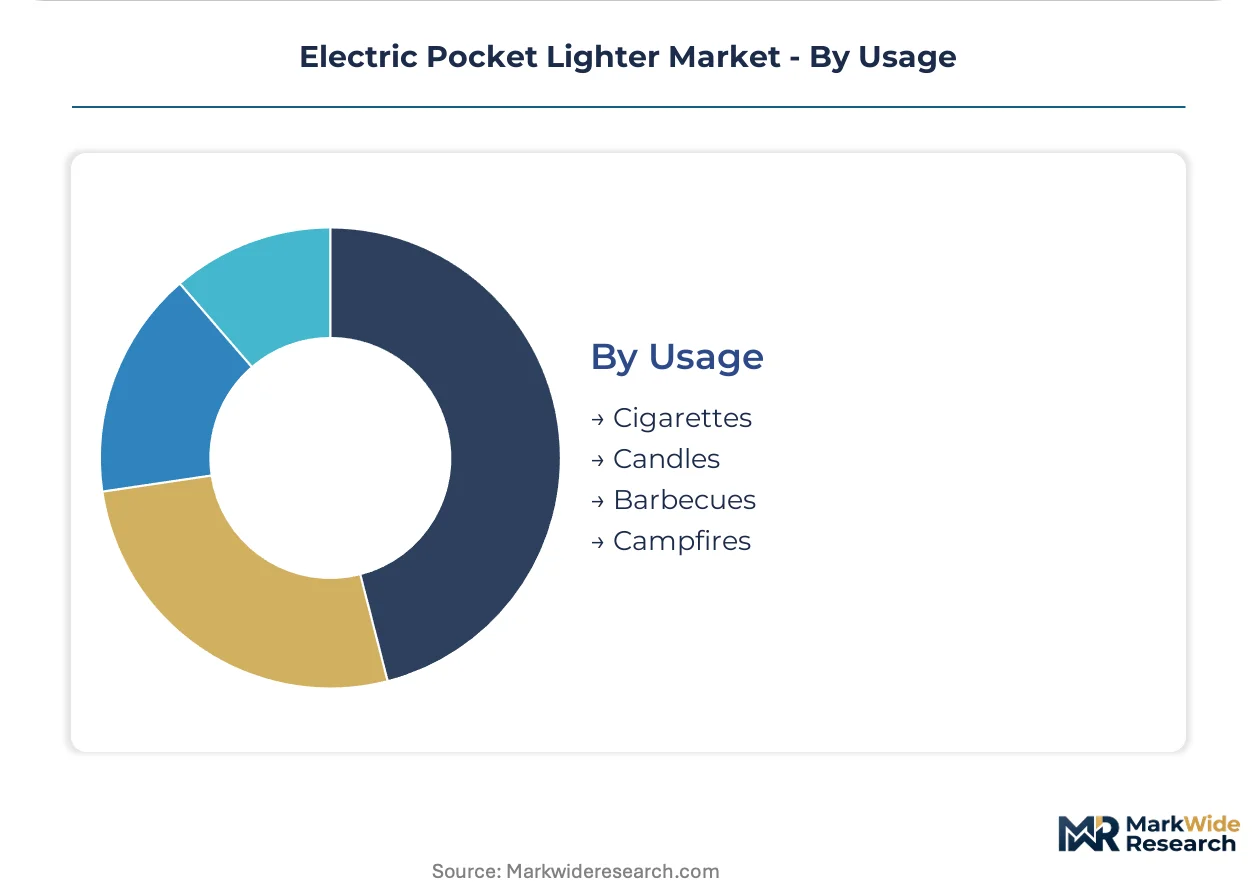
Usage:
Application-specific durability and runtime requirements stratify pricing and component specifications.
- Barbecues:Extended runtime and thermal durability specifications command premium positioning. Ceramic node degradation after 200-300 ignition cycles limits plasma product lifespan in high-frequency commercial applications.
- Cigarettes:High-frequency personal use drives volume concentration in convenience retail channels with emphasis on portability and rapid recharge cycles.
- Candles:Household decorative use favors aesthetic design integration and moderate duty cycles.
- Campfires:Outdoor ignition demands windproof performance and ruggedized housing specifications.
Cigarette usage dominates unit volume; barbecue usage secures margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing manufacturing footprints as producers migrate toward jurisdictions with streamlined battery safety certification pathways and lower compliance overhead for lithium-cell assembly operations.
United States
Restaurants and bars in Chicago and New York City face mandatory flameless ignition requirements under municipal fire codes and indoor air quality ordinances. The US Consumer Product Safety Commission enforces 14-18 month child-resistance validation cycles that compress product launch timelines. Manufacturing procurement concentrates in Dallas-Fort Worth logistics corridors serving convenience store and outdoor retail channels.
Germany
EU Battery Directive end-of-life collection obligations are steering food service procurement toward rechargeable alternatives with established producer-financed recycling infrastructure. ECHA REACH frameworks restrict heavy metal content in ignition components sold across member states. Retail distribution networks in Hamburg and Frankfurt are capturing compliance cost advantages through integrated reverse logistics systems.
China
SAMR lithium-cell transportation mandates add 6-8 week certification lead times for export manufacturing clusters seeking North American and European market access. Guangdong and Zhejiang provinces anchor precision ignition component assembly for plasma electrode and resistive coil systems. Shenzhen-based fabricators are reorganizing supply chains around battery cell procurement rather than pressurized hydrocarbon logistics.
India
Underdeveloped camping equipment retail infrastructure in Maharashtra and Karnataka states offers positioning opportunities for windproof plasma distributors targeting adventure sports channels. BIS standards for electronic ignition devices are evolving alongside import tariff structures affecting lithium-cell sourcing. Mumbai-Pune industrial corridors are emerging as assembly locations for USB rechargeable units serving domestic household demand.
Japan
METI energy efficiency guidelines are shaping consumer preference toward solid-state electronic ignition with rapid recharge specifications. Precision manufacturing heritage in Osaka-Nagoya industrial zones supports high-voltage component sourcing for plasma arc electrode systems. Tokyo-based retailers are compressing shelf space for disposable fuel models amid municipal waste reduction targets.
Electric Pocket Lighter Market Vendor Landscape
Technology licensing dominates the current landscape as plasma arc electrode geometry patents create royalty stacking barriers for new entrants. The vendor base organizes around three strategic archetypes: heritage metalworking specialists with collectible positioning, mass-market scale operators with convenience-store density, and precision component manufacturers anchoring Asian supply relationships. Competitive moves concentrate on portfolio diversification into rechargeable formats and geographic expansion into underpenetrated outdoor retail channels.
Within the heritage metalworking tier, Zippo Manufacturing Company exemplifies premium positioning through collectible and gift segment anchoring. Among mass-market scale operators, BIC USA Inc. occupies a position defined by convenience-store distribution density and household volume throughput. At the precision component end, Tokai Corporation represents Asian supply relationship anchoring through ignition component manufacturing specialization.
| Leading Market Players |
|---|
| Zippo Manufacturing Company |
| BIC USA Inc. |
| S.T. Dupont |
| Tokai Corporation |
| Colibri |
| Ningbo Xinhai Electric Co. |
| BAIDE International Enterprise |
| Swedish Match |
| Flamagas |
| Others |
Supply Flow & Price Mechanics
USB rechargeable lithium-ion technology migration is simultaneously compressing unit economics and redistributing manufacturing concentration away from pressurized hydrocarbon logistics hubs toward battery cell procurement corridors. Guangdong and Zhejiang assembly clusters now capture value through vertical integration into lithium-cell sourcing rather than butane canister distribution networks.
Pricing Analysis
Distributor margins in convenience store channels absorb the steepest compression as national pharmacy and dollar store chains consolidate SKU counts and demand direct data integration. Three-tier pricing structure across premium plasma arc, standard resistive coil, and economy disposable battery configurations stratifies around certification grade and runtime specifications. Pricing pressure stems from cobalt and nickel input volatility originating in Democratic Republic of Congo and Indonesian mining concentration. Household end users exhibit highest price sensitivity; barbecue application buyers accept premium positioning for extended durability specifications.
Supply Chain Analysis
Reverse logistics flows for EU Battery Directive compliance are operationalizing collection infrastructure subsidies in Germany and France, reducing producer-financed recycling cost burdens for established distributors. Component sourcing concentrates in China, South Korea, and Japan, with precision electrode manufacturing anchored in Osaka-Nagoya industrial zones and final assembly clustering in Guangdong province. Raw material dependencies center on lithium carbonate, cobalt sulfate, and ceramic substrate feedstocks. Single-source vulnerability in plasma arc electrode geometry patents held by Tokai Corporation and Chinese suppliers creates royalty stacking exposure. Distribution runs through Dallas-Fort Worth logistics corridors serving North American retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on USB rechargeable format penetration displacing recurring butane purchase cycles, while premium-tier plasma arc positioning captures outdoor enthusiast willingness to pay for windproof performance.
For Market Incumbents: Lock in channel control through exclusive data integration partnerships with consolidating pharmacy and dollar store chains. Secure backward integration into lithium-cell sourcing through captive supply arrangements with Guangdong fabricators. Defend against patent-royalty stacking by investing in alternative electrode geometry R&D outside Tokai Corporation licensing scope.
For New Entrants and Emerging Players: Direct-to-consumer subscription models for USB rechargeable units bypass incumbent convenience store density advantages. Target underdeveloped camping equipment retail infrastructure in Maharashtra and Karnataka states for first-mover positioning. Leverage crowdfunding platforms to validate plasma arc designs before committing to SAMR certification timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision component manufacturers with established Asian supply relationships and transferable ignition technology IP. Long-term viability favors suppliers with demonstrated EU Battery Directive compliance infrastructure and operational reverse logistics systems. Monitor municipal flameless ignition mandate expansion in US and German food service sectors as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Arc R&D Investment | Windproof performance differentiation captures outdoor retailer shelf resets from butane competitors. |
| EU Collection Infrastructure Buildout | Producer-financed recycling compliance in Germany reduces reverse logistics cost disadvantage versus import competitors. |
| Lithium-Cell Backward Integration | Captive supply from Guangdong fabricators insulates margin from cobalt and nickel price volatility. |
| Digital Channel Direct Launch | Subscription models bypass incumbent convenience store distribution density moats. |
| India Outdoor Retail Expansion | First-mover positioning in Maharashtra and Karnataka camping channels establishes brand recognition before infrastructure matures. |
Methodological Framework
Multiple input streams — regulatory filings from SAMR and the US Consumer Product Safety Commission, customs trade data for lithium-cell movements, and Nielsen retail audit figures for convenience store channel SKU resets — were reconciled through bottom-up and top-down triangulation. Primary interviews with procurement managers at US restaurant chains, category buyers at German retail distributors, and plant managers at Guangdong assembly facilities were validated against secondary sources including EU Battery Directive implementation reports, ECHA REACH chemical framework updates, and METI energy efficiency guideline releases.
Cross-referencing historical adoption curves for electronic ignition against panel input from outdoor equipment retailers and food service operators shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include ignition mechanism, power architecture, end-use application, and regional regulatory cluster. CAGRs were derived through trend extrapolation moderated by technology substitution elasticity estimates and channel consolidation velocity indicators specific to convenience store and camping retail formats.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery integration or hydrogen fuel cell miniaturization would alter the outlook for lithium-ion rechargeable dominance. Forecasts reflect assumptions about SAMR certification timeline stability and EU collection infrastructure subsidy continuity. Practitioners should monitor municipal flameless mandate expansion velocity and plasma electrode patent litigation developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
Cigarette Lighter Market
Smoking Accessories
North America Smoking Pipe Market
Smoking Accessories
Pocket Flask Market
Smoking Accessories
Smart Ashtray Market
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
Wearable Tailgating Keg Market
Smoking Accessories
China Smoking Accessories Market
Smoking Accessories
China Smoking Pipe Market
Smoking Accessories
North America Cigarette Lighter Market
Smoking Accessories
Smoking Pipe Market
Smoking Accessories
Herb Grinder Market
Smoking Accessories
Rolling Papers Market
Smoking Accessories
Latin America Cigarette Lighter Market
Smoking Accessories
Ashtray Market
Smoking Accessories
Lighter Market
Smoking Accessories
Japan Smoking Accessories Market