
 Handyman Service Market | 2026-2036
Handyman Service Market Size, Share, and Industry Trends Forecast 2026-2036
Handyman Service Market Foresight
North American residential construction corridors are fragmenting into specialized micro-regions for handyman labor deployment. Mr. Handyman leverages its franchise network to sustain standardized service protocols across dispersed markets. TaskRabbit competes through on-demand platform economics that anchor gig-worker flexibility against traditional contractor models.
A handyman service constitutes a skilled labor provision encompassing repair, maintenance, installation, and renovation tasks performed at residential or commercial premises, typically requiring tool-based execution without full trade licensure for minor electrical, plumbing, carpentry, or painting work. The service functions as a cost-efficient alternative to licensed specialty contractors for non-structural jobs below jurisdictional permit thresholds. Home Repair and Maintenance categories within Service Type dominate transaction volume due to recurring property upkeep needs, while Installation and Renovation command premium pricing per job. Residential end users anchor baseline demand cyclicality, whereas Property Management segments generate contracted recurring revenue streams with superior lifetime value profiles.
OSHA workplace safety standards, EPA lead-safe renovation rules, and state-level contractor licensing boards collectively shape operational compliance costs and workforce eligibility across the United States. Local permitting thresholds and insurance mandate variations create fragmented market access conditions that favor scaled operators with dedicated compliance infrastructure. Stakeholders must monitor evolving platform-labor classification litigation and municipal gig-economy ordinances that threaten on-demand business model viability.
Market Dynamics
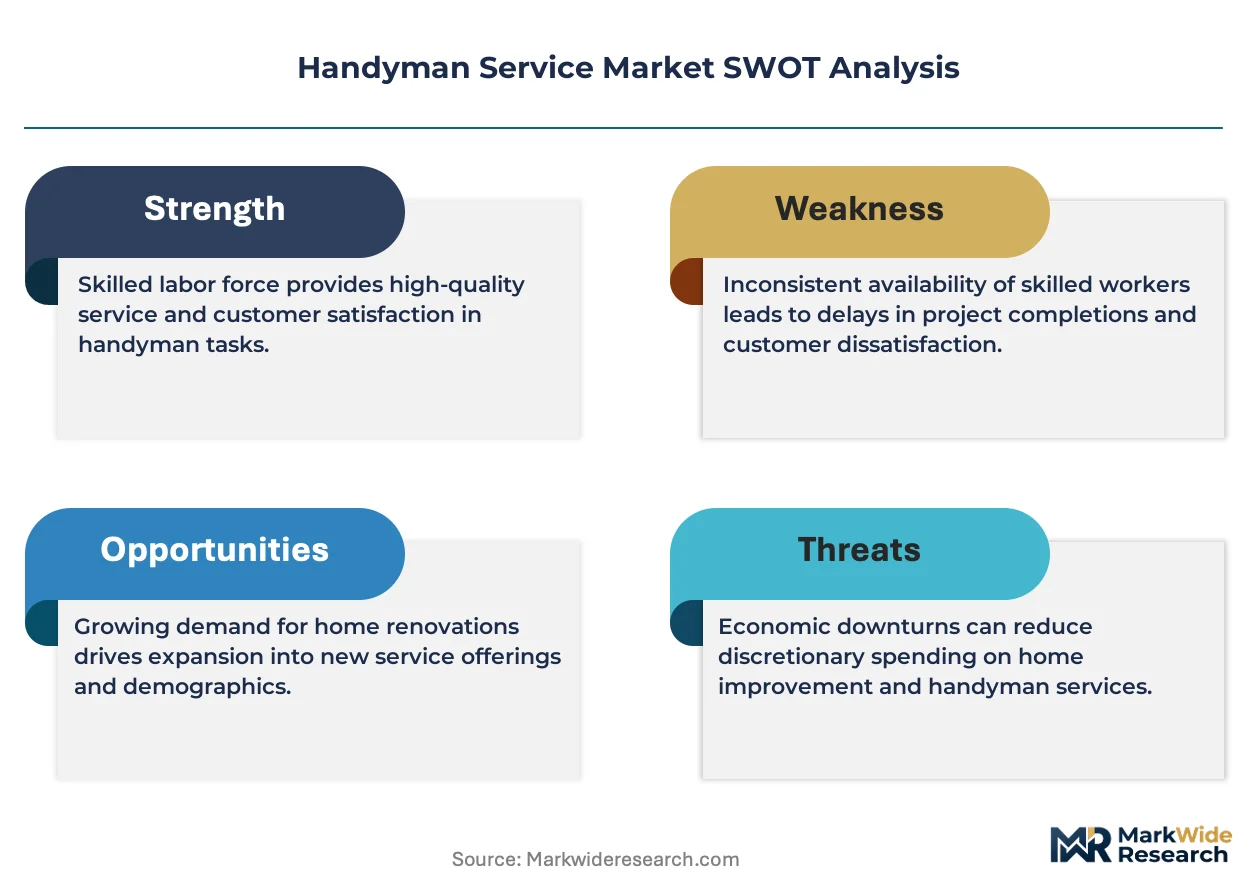
The handyman service market is experiencing structural compression as EPA lead-safe certification requirements and municipal contractor licensing boards tighten workforce eligibility, forcing operators to absorb compliance infrastructure costs or exit fragmented local markets.
Growth Catalysts
- Sun Belt Housing Expansion:Rapid inventory growth across Phoenix, Austin, and Tampa metropolitan corridors generates sustained maintenance demand from aging housing stock and new construction warranty periods.
- Property Management Outsourcing:Institutional landlords and real estate investment trusts consolidate vendor relationships into recurring maintenance contracts, reducing procurement overhead through single-source handyman agreements.
- OSHA Workplace Safety Standards:Federally mandated safety protocols elevate barrier to entry for informal operators, channeling demand toward insured, certified service providers with documented training programs.
Market Restraints
- Skilled Labor Scarcity:Journeyman carpenters and experienced maintenance technicians command wage premiums that compress gross margins for flat-rate service pricing models.
- Insurance Cost Escalation:General liability and workers compensation premiums for tool-equipped field technicians rise faster than service rate inflation in high-litigation jurisdictions.
- Permit Threshold Variability:Municipal definitions of handyman-exempt work differ block-by-block, creating compliance complexity that discourages cross-jurisdictional expansion.
Strategic Opportunities
- Aging-in-Place Modifications:Medicare Advantage supplemental benefits increasingly cover bathroom grab bar installation and doorway widening, opening reimbursement-funded revenue streams.
- Smart Home Integration:Convergence of WiFi-enabled thermostats, leak detection sensors, and video doorbells creates installation demand beyond traditional electrical licensure thresholds.
- Short-Term Rental Maintenance:Airbnb and Vrbo hosts require rapid-response turnover services, preferring platform-booked handyman availability over conventional contractor scheduling.
Industry Challenges
- EPA RRP Certification Backlogs:Lead-safe renovator training course availability lags demand in high-growth markets, delaying workforce deployment for pre-1978 housing work.
- Platform Labor Classification:Municipal gig-economy ordinances and state-level ABC test litigation threaten on-demand handyman model viability by reclassifying independent contractors as employees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handyman Service Market |
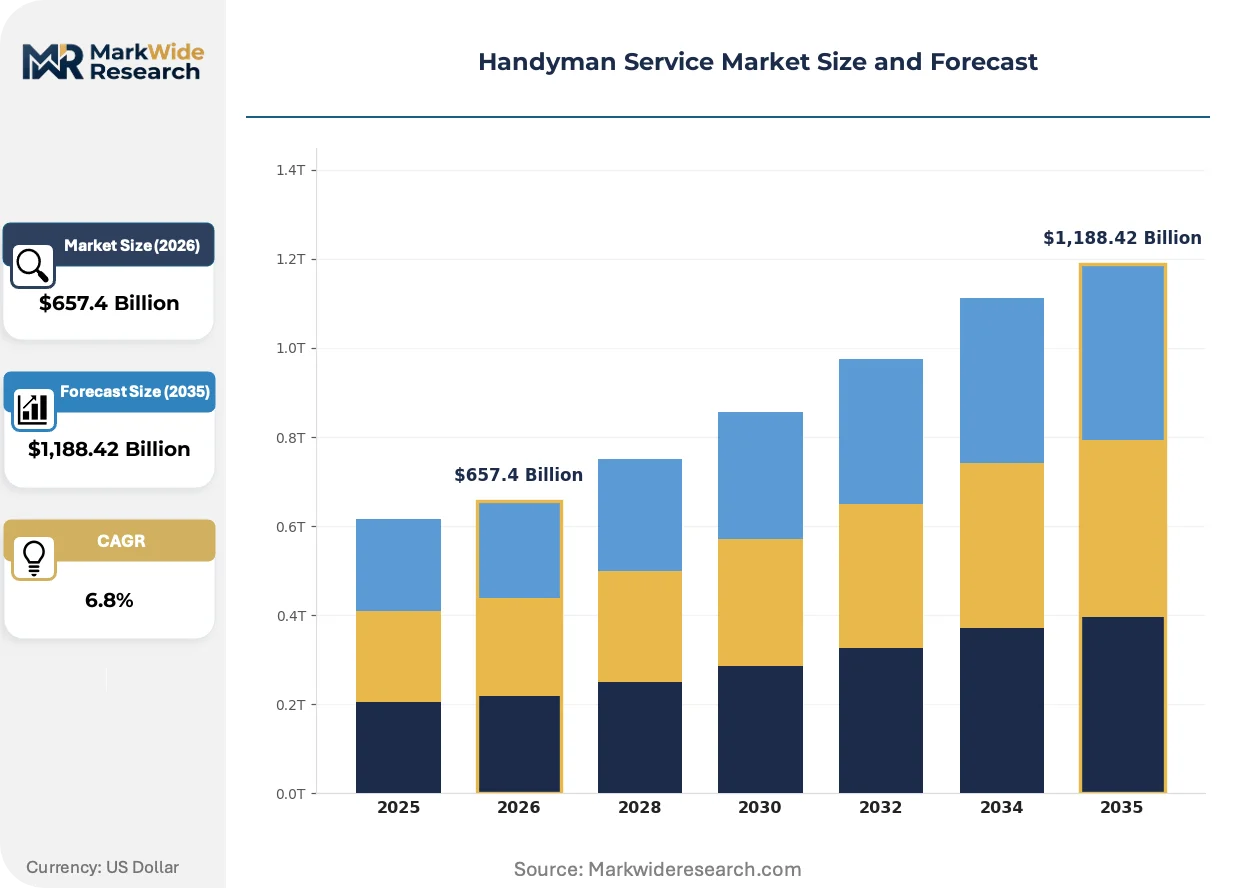
| Market Size in 2026 | $657.4 Billion |
| Market Size in 2035 | $1,188.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Home Repair, Maintenance, Installation, Renovation End User: Residential, Commercial, Industrial, Property Management Pricing Model: Hourly Rate, Fixed Price, Subscription, Package Deals Service Offering: Electrical, Plumbing, Carpentry, Painting |
| Companies Covered | Mr. Handyman, Ace Handyman Services, Angi, Thumbtack, TaskRabbit, HomeAdvisor, Handyman Connection, Handy, Porch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handyman Service Market Shifts & Advancements
Digital dispatch platforms and mobile payment systems are compressing the traditional contractor-homeowner matching process, while specialized tool ecosystems and modular repair components reshape service delivery economics.
Diagnostic sensor technology is hybridizing with conventional handyman workflows. Bluetooth-enabled moisture meters and thermal imaging attachments now accompany standard toolkits. Property management firms deploy these connected devices to prioritize work orders based on objective damage severity rather than tenant complaint volume. The technology is hybridizing preventive maintenance schedules with reactive repair dispatch, compressing average response times while extending asset lifecycles.
EPA lead-safe renovation rules now mandate dust containment and clearance testing for disturbance of painted surfaces in pre-1978 housing. Compliance documentation requirements add administrative overhead to previously informal jobs. Residential rental property owners in Massachusetts and Rhode Island face the strictest enforcement, with state environmental agencies conducting unannounced job site inspections and issuing stop-work orders for uncertified firms.
Subscription maintenance plans are displacing per-incident service calls among high-net-worth homeowners and institutional property holders. Annual contracts covering seasonal gutter cleaning, HVAC filter replacement, and safety device testing generate predictable technician utilization. This model concentrates most rapidly in California coastal markets where labor scarcity and scheduling friction already inflate single-visit pricing.
Handyman Service Market Segmentation
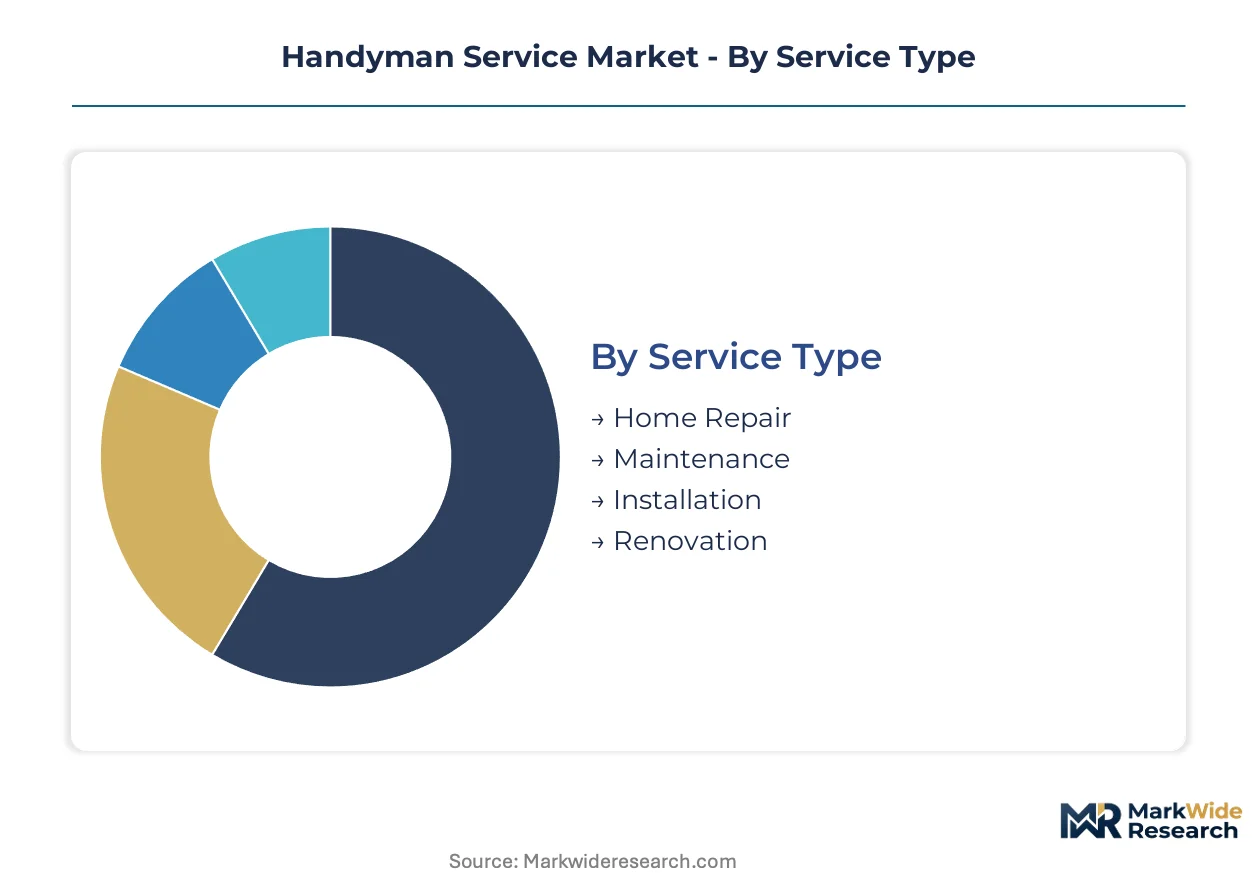
Segmentation in the handyman service market reveals distinct operational rhythms and margin profiles. Service type and end-user composition determine technician deployment patterns, while pricing model selection shapes customer lifetime value and cash flow predictability.
Service Type:
Cycle times vary dramatically across service categories, with reactive repairs turning over in hours while renovation projects stretch across weeks.
- Home Repair:Urgent fixes addressing plumbing leaks, drywall damage, or malfunctioning fixtures command immediate dispatch. Demand concentrates in Sun Belt metropolitan areas where rapid housing inventory expansion strains maintenance capacity. Property management firms prioritize these tickets to minimize tenant turnover costs.
- Maintenance:Scheduled seasonal work including gutter cleaning, HVAC filter replacement, and caulking renewal generates recurring revenue streams. Subscription bundling in California coastal markets compresses per-visit pricing while locking in annual technician utilization.
- Installation:Fixture mounting and appliance connection require precise scheduling coordination. Smart home device deployment in Austin and Phoenix corridors drives specialized electrical-adjacent demand beyond traditional handyman scopes.
- Renovation:Kitchen refresh and bathroom update projects absorb multiple technician days. EPA lead-safe certification requirements for pre-1978 housing in Massachusetts and Rhode Island add compliance overhead to previously informal jobs.
Home Repair anchors the volume base while Installation gains share at the steepest rate.
End User:
Customer type dictates procurement complexity, with institutional buyers consolidating vendor relationships while residential clients prioritize scheduling flexibility.
- Residential:Individual homeowners initiate discrete, emotionally driven purchases following property damage or aesthetic fatigue. Aging-in-place modifications for Medicare Advantage beneficiaries in Florida and Arizona open reimbursement-funded revenue channels.
- Commercial:Retail and office facilities demand after-hours service windows to minimize operational disruption. Multi-location chains in Texas and Georgia favor master service agreements with standardized pricing across properties.
- Industrial:Warehouse and light manufacturing maintenance requires heavier tool inventories and specialized safety training. OSHA workplace standards elevate insurance and documentation burdens beyond typical residential deployments.
- Property Management:Institutional landlords and real estate investment trusts generate contracted recurring revenue with superior lifetime value profiles. Vendor consolidation in Tampa and Charlotte markets reduces procurement overhead through single-source agreements.
Property Management delivers the most predictable revenue streams while Residential commands the largest absolute transaction count.
Pricing Model:
Margin exposure shifts across pricing structures, with fixed-rate models absorbing scope uncertainty while subscription plans trade upfront discounting for utilization certainty.
- Hourly Rate:Time-and-materials billing dominates emergency repair scenarios where scope remains undefined until technician arrival. Customer price sensitivity in competitive urban markets pressures rate transparency.
- Fixed Price:Flat-rate quoting for defined scopes transfers risk to operators while enabling customer budget certainty. Scope creep management becomes critical for margin protection.
- Subscription:Annual maintenance contracts covering seasonal inspections and preventive tasks generate predictable technician deployment. California markets show fastest adoption among high-net-worth homeowners facing labor scarcity friction.
- Package Deals:Bundled service offerings combining multiple trade disciplines improve per-visit economics. Move-in/move-out packages for short-term rental hosts in Austin and Nashville address rapid-turnover maintenance needs.
Hourly Rate remains the default transaction structure while Subscription expands most quickly in supply-constrained coastal markets.
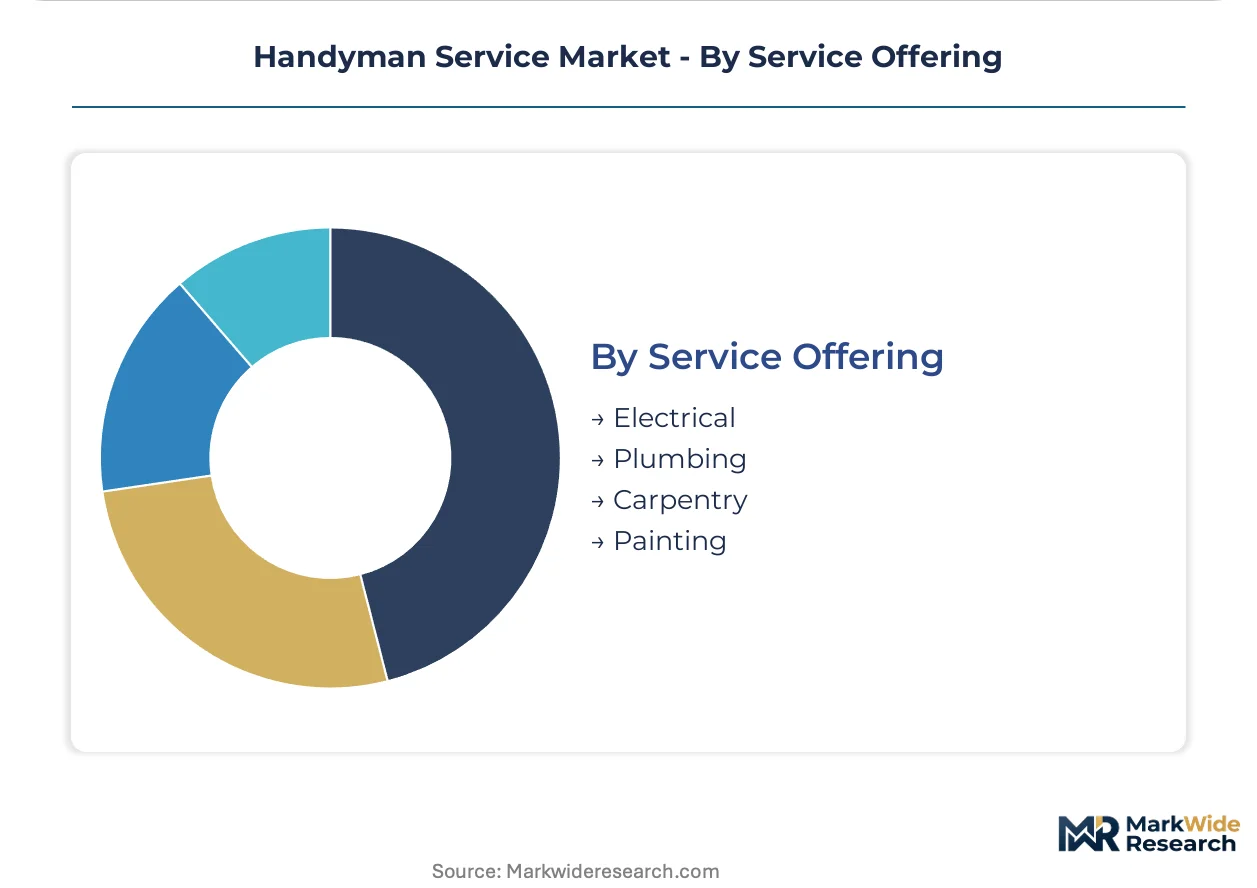
Service Offering:
Technical specialization requirements determine workforce training investments and jurisdictional licensing exposure across trade disciplines.
- Electrical:Outlet replacement, fixture installation, and smart device integration sit below licensed electrician thresholds in most jurisdictions. WiFi-enabled thermostat deployment creates demand beyond traditional handyman scopes.
- Plumbing:Leak repair, fixture replacement, and drain clearing constitute high-frequency reactive demand. Municipal licensing variations create compliance complexity for cross-jurisdictional operators.
- Carpentry:Door hanging, trim repair, and shelving installation require precise measurement and finish quality. Experienced journeyman carpenters command wage premiums that compress flat-rate model margins.
- Painting:Interior and exterior surface finishing generates substantial project volume with lower technical barriers to entry. EPA lead-safe renovation rules mandate dust containment and clearance testing for pre-1978 housing disturbance.
Electrical and Plumbing together drive the majority of emergency dispatch volume while Carpentry captures premium pricing for finish-quality work.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety standards and EPA lead-safe certification requirements anchor operational compliance across the United States, the dominant geography for handyman service demand. Municipal contractor licensing boards create fragmented access conditions that favor scaled operators with dedicated compliance infrastructure.
United States
Sun Belt metropolitan corridors including Phoenix, Austin, and Tampa generate sustained maintenance demand from rapid housing inventory expansion. EPA Renovation, Repair and Painting rules mandate dust containment and clearance testing for pre-1978 housing disturbance. Massachusetts and Rhode Island state environmental agencies conduct unannounced job site inspections with stop-work authority for uncertified firms.
Canada
Provincial contractor licensing variations and building code differences create compliance complexity for cross-jurisdictional operators. Health Canada and the Canada Revenue Agency shape workplace safety and employment classification standards. Ontario and British Columbia concentrate demand from aging housing stock in Toronto and Vancouver metropolitan areas.
Germany
Chamber of Crafts membership requirements and trade guild certifications elevate workforce entry barriers beyond North American thresholds. The Federal Ministry of Labour and Social Affairs enforces workplace safety through the Occupational Safety and Health Act. Bavaria and North Rhine-Westphalia industrial clusters sustain commercial facility maintenance demand from manufacturing and logistics assets.
United Kingdom
Gas Safe Register certification and Part P electrical competency rules restrict scope for unlicensed operators in residential work. The Health and Safety Executive prosecutes workplace safety violations with criminal penalties. London and Southeast England concentrate property management outsourcing demand from institutional landlords and Build-to-Rent operators.
Australia
State-level builder licensing and home warranty insurance mandates create fragmented operational requirements across New South Wales, Victoria, and Queensland. Safe Work Australia harmonizes workplace safety standards while state regulators enforce trade-specific competencies. Sydney and Melbourne metropolitan areas concentrate demand from strata-titled apartment maintenance obligations.
Handyman Service Market Competitive Landscape
Capability concentration sits with specialized trade contractors; scale advantage sits with platform-mediated networks and franchise systems. The market structure fragments across informal sole proprietors, regional multi-trade operators, and national platform brands. Three archetypes dominate: insurance-backed franchise networks, on-demand labor platforms, and vertically integrated property management vendors. Competitive moves center on compliance infrastructure investment and subscription pricing model adoption.
Within the franchise network tier, Mr. Handyman and Ace Handyman Services occupy positions anchored by standardized service protocols and brand-mediated customer trust. TaskRabbit exemplifies the platform archetype, competing through gig-worker flexibility against traditional contractor scheduling constraints. These three companies represent the structural tension between centralized quality assurance and distributed labor market access.
| Leading Market Players |
|---|
| Mr. Handyman |
| Ace Handyman Services |
| Angi |
| Thumbtack |
| TaskRabbit |
| HomeAdvisor |
| Handyman Connection |
| Handy |
| Porch |
| Others |
Supply & Pricing Matrix
Technician undercapacity across Sun Belt metropolitan corridors compresses dispatch availability while inflating flat-rate service premiums, forcing operators to balance wage absorption against customer price sensitivity in supply-constrained markets.
Pricing Analysis
Coastal California markets command subscription premiums nearly double Phoenix flat-rate equivalents, reflecting labor scarcity and scheduling friction differentials. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and response urgency, with EPA lead-safe certified technicians capturing tier-one positioning. Pricing pressure stems from insurance cost escalation outpacing service rate inflation in high-litigation jurisdictions. Residential homeowners exhibit highest price sensitivity per incident, while property management firms prioritize lifetime value over per-job economics.
Supply Chain Analysis
Export-control regimes on lithium-ion power tools and Bluetooth-enabled diagnostic equipment from China create procurement friction for US-based service fleets. Tool and equipment manufacturing concentrates in China, Taiwan, and Germany, with cordless platform ecosystems tethered to proprietary battery architectures. Raw material dependencies span lithium battery cells, carbon steel fasteners, and EPA-compliant lead-test kits. Single-source vulnerability runs through dominant power tool OEM platform lock-in. Distribution runs through wholesale contractor supply houses and direct-to-fleet e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with EPA certification backlogs and municipal licensing complexity creating structural switching costs that protect incumbent positions.
For Market Incumbents: Insulate market position by deepening compliance infrastructure investments in EPA lead-safe training capacity and multi-jurisdictional licensing databases. Acquire regional operators in Tampa and Charlotte corridors to consolidate vendor relationships with institutional property managers. Platform labor classification litigation threatens on-demand model viability; anchor defensive posture in employee-classification workforce structures.
For New Entrants and Emerging Players: Establish a beachhead in short-term rental maintenance segments, where rapid-response turnover demand outstrips conventional contractor scheduling capacity. Target Austin and Nashville metropolitan clusters with package-deal offerings for Airbnb and Vrbo hosts. Deploy platform-booked availability as go-to-market wedge against legacy scheduling friction.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across subscription maintenance plan operators, as annual contract bundling demands working capital for technician utilization smoothing. Five-to-ten year viability favors scaled franchises with dedicated compliance infrastructure over sole proprietors. Target acquisition archetype: regional multi-trade operators with existing property management contracts. Watch EPA RRP certification course availability as inflection signal for workforce deployment constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| EPA Certification Infrastructure Buildout | Lead-safe renovator training capacity removes workforce deployment bottleneck for pre-1978 housing work. |
| Property Management Contract Consolidation | Single-source agreements with REITs in Tampa and Charlotte reduce customer acquisition cost. |
| Smart Home Integration Capability | WiFi-enabled thermostat deployment captures electrical-adjacent demand beyond traditional scopes. |
| Subscription Maintenance Plan Rollout | Annual contracts in California coastal markets lock in technician utilization against labor scarcity. |
| Diagnostic Sensor Technology Deployment | Bluetooth moisture meters and thermal imaging prioritize work orders by objective damage severity. |
Research Methodology
The analysis maps home repair, maintenance, installation, and renovation service lines, each validated through franchise operations directors, property management procurement leads, municipal licensing administrators, and EPA training providers. Primary interview findings triangulate against secondary sources including OSHA enforcement databases, state contractor board filings, and property management industry association surveys. Bottom-up technician deployment modeling and top-down housing stock maintenance spend estimates reconcile through iterative validation.
Assumptions held fixed include prevailing EPA RRP certification requirements and municipal permitting thresholds, while variables included Sun Belt housing inventory growth rates and platform labor classification litigation outcomes. The projection horizon spans service type, end-user segment, pricing model, and regional regulatory cluster dimensions. CAGRs derive from housing stock aging curves and outsourced maintenance contract penetration trends, with smart home device installation intensity and Medicare Advantage supplemental benefit coverage as key forecast inputs.
Stress conditions across EPA training course availability, insurance premium inflation, and gig-economy ordinance adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented in segmentation and regional frameworks. Material shifts in federal contractor classification standards or state-level environmental enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Global Used Smartphones Market
Consumer Goods
Europe Watch Market
Consumer Goods
Kindle E-Reader Accessories Market
Consumer Goods
Claw Machine Market
Consumer Goods
Liquid Makeup Market
Consumer Goods
Deodorant Wipes Market
Consumer Goods
Digital BBQ Tongs and Thermometer Market
Consumer Goods
Refrigerator Market
Consumer Goods
Hand Gloves Market
Consumer Goods
Baby Bottle Warmers Market
Consumer Goods
Europe Digital Showers Market
Consumer Goods
Global Smartwatch Battery Market
Consumer Goods
Animation Toys Market
Consumer Goods
Spain Luxury Goods Market
Consumer Goods
Insulated Dog House Market
Consumer Goods
Lipstick Market