
 US Mobile Phone Accessories Market | 2026-2036
US Mobile Phone Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
US Mobile Phone Accessories Market Insights
Subscription-based warranty and replacement services is shifting how US consumers evaluate accessory purchases over product lifecycles. Apple Inc. leverages its integrated ecosystem to lock in recurring accessory revenue through branded charging and audio peripherals. Anker Innovations competes on charging technology specialization, sustaining rapid SKU turnover in power delivery standards. Otter Products, LLC anchors its position in protective case durability, dominating retail shelf space through carrier partnerships.
US mobile phone accessories comprise physical add-on products—cases molded from polycarbonate or thermoplastic polyurethane, tempered glass screen laminates, gallium nitride charging circuits, and Bluetooth audio transducers—designed to extend device protection, power availability, and media functionality. Cases and screen protectors command mature, high-volume positions with compressed margins, while gallium nitride chargers and wireless audio accessories capture expanding margin pools through semiconductor content and protocol complexity. Silicone and glass materials face substitution pressure as recycled ocean plastics and sapphire laminates enter premium positioning.
FCC equipment authorization requirements govern radio-frequency accessories including Bluetooth earbuds and wireless chargers, while California's SB 244 right-to-repair law mandates parts availability and repair documentation that reshapes case and battery design standards. NHTSA scrutiny of in-vehicle phone mounting and charging safety influences automotive accessory specifications. Stakeholders must monitor state-level repair legislation divergence and USB-C standardization mandates from the EU that ripple through US importer design decisions.
Market Dynamics
California's SB 244 right-to-repair law is forcing accessory manufacturers to redesign product architectures for disassembly and component replacement, compressing development cycles while expanding parts documentation obligations.
Growth Catalysts
- USB-C Standardization Mandates:The EU's universal charging directive is converging with US importer design decisions, collapsing connector fragmentation and enabling scale economies in cable and adapter production.
- Remote Workforce Equipment Refresh:Enterprise procurement of wireless audio peripherals and multi-device charging stations is accelerating as hybrid work policies institutionalize home office infrastructure.
- Gallium Nitride Semiconductor Adoption:GaN power circuits are displacing silicon in compact chargers, unlocking wattage density improvements that support laptop-grade output from pocket-sized form factors.
Market Restraints
- Neodymium Magnet Supply Concentration:Rare earth processing dependency on Chinese refining infrastructure creates input cost volatility for magnetic wireless charging arrays and speaker drivers.
- FCC Equipment Authorization Timelines:Radio-frequency accessory certification delays of 8-14 weeks compress product launch windows and tie up working capital in pre-market inventory.
- Sapphire Laminate Cost Premium:Synthetic sapphire screen protection carries 4-6x material cost multiples against tempered glass, capping addressable market penetration in mid-tier price bands.
Strategic Opportunities
- Texas Tech Corridor Density:Austin's early-adopter population concentration supports premium accessory beta testing and direct-to-consumer channel validation before national rollout.
- Automotive Integration Standards:NHTSA-influenced in-vehicle mounting and Qi2 wireless charging specifications are opening certified accessory placements with domestic automakers.
- Recycled Ocean Plastic Positioning:Post-consumer maritime polymer sourcing is converging with California Extended Producer Responsibility frameworks to differentiate premium case offerings.
Industry Challenges
- RF Engineering Talent Scarcity:Bluetooth protocol optimization and antenna design expertise concentrates in semiconductor firms, forcing accessory makers to outsource core wireless performance engineering.
- Repair Documentation Compliance:SB 244 mandates for disassembly guides and spare parts availability are forcing SKU proliferation and inventory complexity for case and battery suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Mobile Phone Accessories Market |
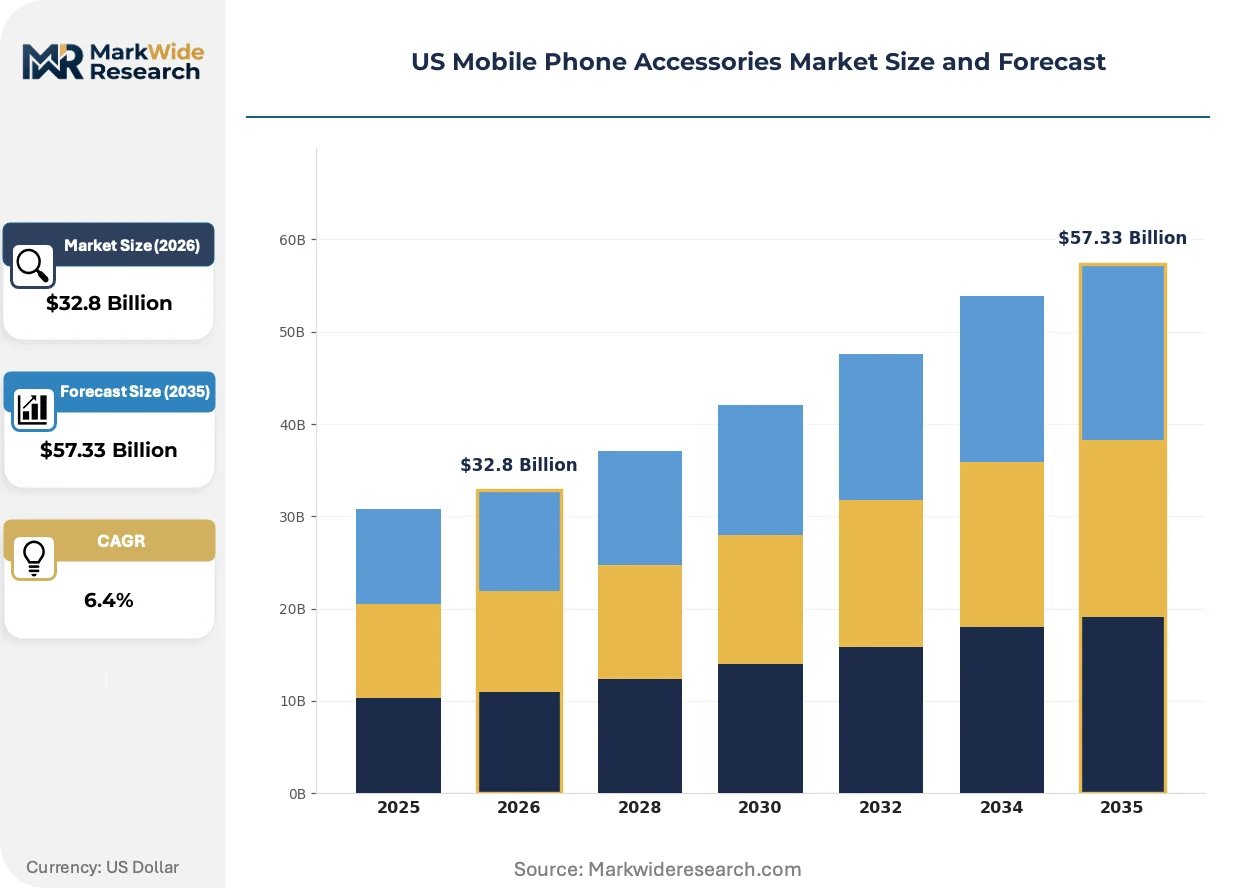
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cases, Screen Protectors, Chargers, Audio Accessories Material: Plastic, Leather, Silicone, Glass End User: Consumers, Businesses, Retailers, Online Shoppers Distribution Channel: Online, Retail Stores, Wholesalers, Third-Party Platforms |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Belkin International, Inc., Otter Products, LLC, Anker Innovations, ZAGG Inc., Spigen Inc., Bose Corporation, Speck Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Mobile Phone Accessories Market Trends and Innovations
Qi2 magnetic alignment protocols and gallium nitride power semiconductors are converging to reshape charging accessory form factors and thermal performance benchmarks across price tiers.
GaN power circuits are converging with USB Power Delivery 3.1 standards to enable 140W output from palm-sized adapters. Enterprise procurement teams are specifying these units for mobile workstation deployments. The technology is converging with traditional laptop power brick margins, compressing ASPs in the 65W-100W segment while expanding total addressable volume.
California's SB 244 right-to-repair legislation mandates parts availability and repair documentation for electronic accessories sold after July 2024. Case manufacturers must redesign snap-fit architectures for non-destructive disassembly. Battery replacement service programs are proliferating in Los Angeles and San Francisco retail footprints as compliance deadlines approach.
Subscription warranty bundling is displacing transactional protection plan attachments at point-of-sale. Carrier retail channels are unbundling device protection from accessory coverage, forcing standalone accessory brands to build direct recurring revenue relationships. Texas and Florida markets show highest attachment velocity for multi-year replacement service contracts.
US Mobile Phone Accessories Market Segmentation
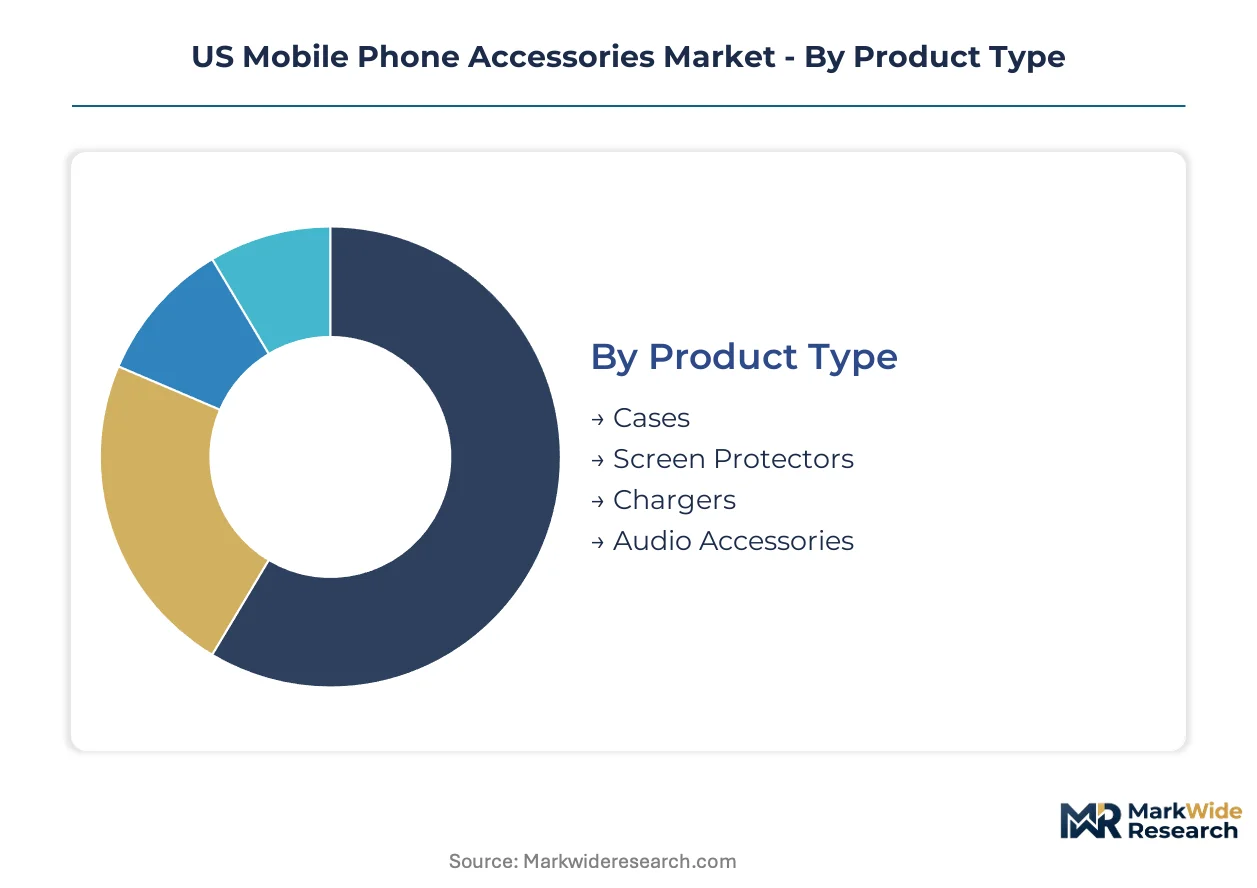
Accessory purchasing patterns diverge sharply across buyer contexts. Enterprise procurement teams prioritize charging infrastructure standardization, while individual consumers respond to material aesthetics and device protection tiers. Understanding these splits enables targeted margin capture across fragmented demand pools.
Product Type:
Purchase frequency and replacement cycles vary dramatically by functional category, reshaping inventory velocity and warranty attachment rates across the supply base.
- Cases:Polycarbonate and thermoplastic polyurethane shells dominate unit economics through carrier retail bundling. Texas and Florida markets show elevated premium case attachment as early-adopter populations refresh devices annually. Volume sits with polycarbonate standard offerings; growth tilts toward recycled ocean plastic premium positioning under California Extended Producer Responsibility frameworks.
- Screen Protectors:Tempered glass laminates command mature, high-volume positions with compressed margins, while synthetic sapphire variants capture 4-6x material cost premiums in luxury retail channels. Austin's tech corridor supports beta testing of diamond-coated alternatives before national carrier rollout.
- Chargers:Gallium nitride circuits displace silicon in compact adapters, unlocking laptop-grade output from pocket-sized form factors under USB Power Delivery 3.1 standards.
- Audio Accessories:Bluetooth earbuds and wireless headphones face FCC equipment authorization timelines of 8-14 weeks, compressing launch windows for seasonal retail cycles.
Margin pools concentrate in charging and audio categories where semiconductor content and protocol complexity create differentiation headroom.
Material:
Raw material selection directly determines price band placement and regulatory compliance burden, particularly under California's SB 244 disassembly mandates and emerging Extended Producer Responsibility frameworks.
- Plastic:Recycled ocean polymers are gaining premium positioning as post-consumer maritime sourcing converges with state-level environmental compliance. Volume concentration remains with virgin polycarbonate in mass-market case production.
- Leather:Genuine and synthetic hides occupy luxury tier pricing, with Italian-sourced full-grain variants commanding placement in flagship carrier stores.
- Silicone:Thermoset rubber compounds face substitution pressure as liquid silicone injection molding enables thinner, more precise fit profiles for device-specific case architectures.
- Glass:Tempered aluminosilicate dominates screen protection volume, though edge-curvature compatibility challenges persist with foldable device form factors.
Plastic retains volume leadership; glass and recycled polymers are climbing fastest on sustainability-driven procurement specifications.
End User:
Procurement authority and volume scale separate organizational buyers from individual purchasers, with distinct channel preferences and service expectations.
- Consumers:Individual purchasers respond to point-of-sale warranty bundling and carrier upgrade cycle synchronization, with highest attachment velocity in Texas and Florida markets for multi-year replacement contracts.
- Businesses:Enterprise procurement teams specify gallium nitride charging stations and wireless audio peripherals for hybrid work infrastructure, institutionalizing refresh cycles independent of consumer holiday patterns.
- Retailers:Carrier and big-box buyers dominate case and screen protector volume through annual SKU rationalization and exclusive colorway arrangements.
- Online Shoppers:Direct-to-consumer channels enable rapid beta testing of Qi2 magnetic alignment accessories before wholesale distribution commitment.
Business procurement is expanding fastest on enterprise hybrid work policies; consumer volume anchors in carrier retail footprints.
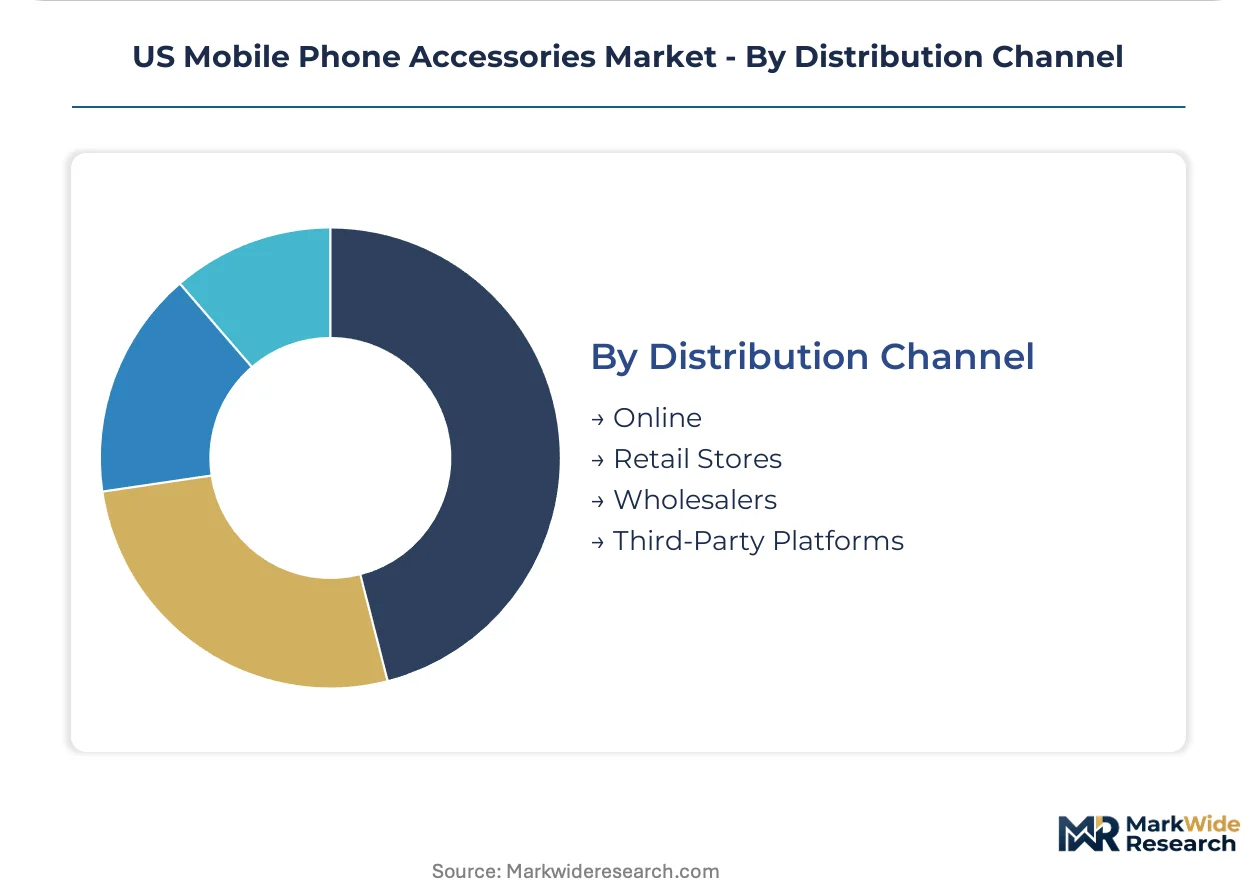
Distribution Channel:
Fulfillment speed and touchpoint density determine competitive access, with divergent working capital requirements and return rate profiles.
- Online:Direct-to-consumer platforms enable subscription warranty bundling and rapid SKU turnover for gallium nitride charging standards evolution.
- Retail Stores:Carrier partnerships dominate case and screen protector placement, with shelf space allocation tied to device launch synchronization and exclusive colorway development.
- Wholesalers:Bulk distribution serves independent repair shops under California SB 244 parts availability mandates, expanding documentation and inventory complexity.
- Third-Party Platforms:Marketplace aggregators concentrate price competition in commoditized cable and adapter categories, compressing ASPs in legacy connector formats.
Online channels are gaining fastest on subscription attachment; retail stores retain volume through carrier exclusivity arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic consumption concentrates on the coasts while manufacturing and distribution infrastructure clusters in the South and Southwest. Texas and California together absorb disproportionate early-adopter demand for premium charging and audio peripherals. State-level regulatory divergence is reshaping where suppliers locate repair documentation and parts fulfillment operations.
California
Silicon Valley and Los Angeles anchor the nation's densest early-adopter populations for gallium nitride charging and Qi2 magnetic accessories. SB 244 right-to-repair mandates are forcing suppliers to maintain Los Angeles and San Francisco retail footprints for battery replacement service programs. San Diego's cross-border logistics infrastructure supports rapid Mexican manufacturing feedback loops for case prototyping.
Texas
Austin's tech corridor generates disproportionate beta testing velocity for wireless audio peripherals before national carrier rollout. Enterprise procurement teams in Dallas-Fort Worth are specifying multi-device charging stations for hybrid work infrastructure at scale. Houston's port complex handles bulk import volumes for third-party cable and adapter distribution throughout the South.
New York Metro
Manhattan carrier flagship stores set national precedent for premium case and screen protector placement through exclusive colorway arrangements. Brooklyn's direct-to-consumer startup ecosystem incubates recycled ocean plastic positioning before wholesale commitment. Newark's air freight corridors accelerate FCC-authorized audio accessory launch windows for seasonal retail cycles.
Florida
Miami's Latin American trade connectivity channels import volumes for leather and synthetic hide luxury case sourcing. Tampa and Orlando retail footprints show highest attachment velocity for multi-year replacement service contracts in consumer segments. Jacksonville distribution centers serve Southeast wholesale demand under compressed margin conditions.
Illinois/Michigan/Ohio
Chicago's enterprise procurement density supports standardized gallium nitride charging infrastructure for Fortune 500 hybrid work policies. Detroit's automotive engineering clusters influence NHTSA-aligned in-vehicle mounting and Qi2 wireless charging specification development. Cleveland's polymer processing legacy feeds recycled plastic compound development for case manufacturers targeting California Extended Producer Responsibility compliance.
US Mobile Phone Accessories Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in charging and protective case categories. The market fragments across three tiers: ecosystem-integrated giants, charging technology specialists, and durability-focused case manufacturers. Strategic moves concentrate on carrier exclusivity arrangements and direct-to-consumer subscription warranty bundling. Portfolio diversification into automotive-certified accessories and enterprise procurement channels is accelerating.
Among ecosystem-integrated giants, Apple Inc. exemplifies vertical control through proprietary charging and audio peripheral architectures. Samsung Electronics Co., Ltd. occupies a parallel position for Android-aligned accessory ecosystems. Anker Innovations sits within the specialist tier, representing rapid SKU turnover around evolving power delivery standards. Otter Products, LLC anchors the durability-focused archetype through retail shelf space concentration in carrier channels.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Belkin International, Inc. |
| Otter Products, LLC |
| Anker Innovations |
| ZAGG Inc. |
| Spigen Inc. |
| Bose Corporation |
| Speck Products |
| Others |
Pricing and Supply Chain Analysis
Neodymium oxide price volatility cascades through magnetic wireless charging arrays and speaker driver assemblies, compressing margins in mid-tier audio accessories while concentrating pricing power with gallium nitride semiconductor suppliers who command premium positioning through wattage density advantages.
Pricing Analysis
Margin tightening in the 65W-100W charger segment reflects gallium nitride circuit commoditization as USB Power Delivery 3.1 standards proliferate. Three-tier pricing structure across premium, standard, and economy levels separates GaN-enabled laptop-grade output from silicon legacy adapters and unbranded cable commodities. Brand premium and FCC certification tier differentiate audio accessories where authorization timelines compress launch windows. Cost-down pressure on polycarbonate cases accelerates because recycled ocean plastic positioning captures California Extended Producer Responsibility compliance value. Enterprise procurement teams show lowest price sensitivity for multi-device charging station standardization, while third-party platform shoppers drive ASP erosion in legacy connector formats.
Supply Chain Analysis
Direct-to-retail carrier partnerships dominate case and screen protector placement through device launch synchronization and exclusive colorway development. Manufacturing concentrates in China for magnetic coil assemblies and injection-molded polymer shells, Vietnam for liquid silicone rubber compounding, and Mexico for rapid case prototyping feedback loops. Rare earth processing draws from Chinese refining infrastructure for neodymium magnet inputs. Semiconductor content rests on Taiwanese foundry capacity for GaN-on-silicon power devices. Single-source vulnerability in rare earth magnet supply creates input cost volatility that propagates through wireless charging array BOMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride foundry capacity constraints prop pricing premiums for high-wattage compact adapters, sustaining margin pools despite silicon legacy displacement.
For Market Incumbents: Anticipate USB-C standardization convergence collapsing connector fragmentation and eroding proprietary cable margins. Defensive consolidation through backward integration into GaN semiconductor sourcing secures wattage density leadership against charging technology specialists. Carrier exclusivity arrangements for Qi2 magnetic alignment accessories lock shelf space against direct-to-consumer entrants. For New Entrants and Emerging Players: Enter via recycled ocean plastic case positioning under California Extended Producer Responsibility frameworks, the most penetrable premium tier for sustainability-differentiated challengers. Target Austin's tech corridor for wireless audio peripheral beta testing before national carrier rollout. Direct-to-consumer subscription warranty bundling builds recurring revenue relationships outside carrier retail channel dependence. For Investors and Strategic Acquirers: Distressed-cycle entries favor charging technology specialists with GaN IP portfolios in Taiwan and China manufacturing corridors. Long-term viability over the next decade hinges on USB Power Delivery standard evolution capture and automotive Qi2 certification placement. Watch NHTSA in-vehicle wireless charging specification finalization as inflection indicator for certified accessory placement value.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Backward Integration | Captive supply of power circuits secures wattage density leadership against Anker Innovations specialization. |
| California SB 244 Repair Documentation Compliance | Parts availability mandates reshape case architecture design and expand Los Angeles retail service footprints. |
| Qi2 Magnetic Alignment Certification | NHTSA-influenced automotive placement opens certified accessory channels with domestic automakers. |
| Recycled Ocean Plastic Premium Positioning | Post-consumer maritime sourcing converges with Extended Producer Responsibility frameworks for differentiation. |
| Enterprise Procurement Channel Development | Hybrid work infrastructure standardization institutionalizes refresh cycles independent of consumer holiday patterns. |
Research Methodology
Independent corroboration across FCC equipment authorization databases, carrier retail SKU rationalization records, and gallium nitride semiconductor foundry utilization reports underwrites the qualitative findings. Primary interviews with accessory category buyers at national carriers, GaN power circuit design engineers, and California repair shop proprietors combined with secondary validation from SEC 10-K filings, customs import manifests, and USB Implementers Forum technical specifications. Bottom-up assembly of charger and audio accessory shipment estimates triangulates against top-down consumer electronics spending allocation models.
Comparable-period anchoring to historical smartphone upgrade cycles and enterprise IT refresh patterns established the forecast window baseline. Segmentation modeling across product type, material composition, end-user procurement authority, and distribution channel fulfillment mode structures volume and value outputs across the projection horizon. CAGRs derive from installed base growth, replacement frequency elasticity, and premium tier mix shift assumptions. GaN semiconductor adoption curves and USB-C standardization penetration rates constitute industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export restriction scenarios or FCC authorization timeline extensions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Portable Speaker Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
Vertical Ergonomic Optical Mouse Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Europe Soundbar Market
Consumer Electronics
TV Mirror Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Dual Screen Laptops Market
Consumer Electronics
Pool Speakers Market