
 Saudi Arabia Gas Hobs Market | 2026-2036
Saudi Arabia Gas Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Gas Hobs Market Analytics
Aftermarket service revenue is tilting toward authorized dealer networks as warranty complexity rises with electronic ignition systems and flame failure devices. Ariston leverages its regional service infrastructure to capture recurring maintenance contracts. Electrolux sustains premium positioning through extended warranty programs that lock in repeat service visits. Beko competes on replacement part availability, shortening lead times for burner assemblies and control valves across Saudi distributor channels.
A gas hob is a cooking appliance comprising one or more gas burners mounted on a metal surface, typically constructed from stainless steel or tempered glass, with thermal outputs ranging from one to five kilowatts per burner depending on configuration. Its primary commercial purpose is to provide controlled, immediate heat for food preparation in residential kitchens, restaurants, and institutional catering facilities. Built-in hobs dominate Saudi residential fit-outs where modular kitchen design prevails, while freestanding units retain share in rental properties and commercial kitchens requiring equipment mobility. Automatic ignition technology leads new installations as consumers reject manual lighting methods, though flame failure devices remain the fastest-growing safety segment due to tightening installation codes.
SFDA enforces appliance safety certification for all gas hobs entering the Kingdom, while SASO mandates energy labeling and efficiency thresholds that filter lower-tier imports from Asian manufacturing bases. These frameworks elevate compliance costs for new entrants but protect established suppliers with in-country testing partnerships. Stakeholders must monitor evolving SFDA gas appliance regulations and SASO efficiency tier revisions to anticipate product line adjustments before enforcement deadlines tighten market access.
Market Dynamics
SFDA safety certification and SASO energy efficiency mandates are compressing import windows for lower-tier Asian manufacturers while elevating compliance costs for all entrants, fundamentally restructuring competitive access to the Saudi gas hobs market.
Growth Catalysts
- Central Region housing stock:New residential developments in Riyadh and surrounding governorates are generating sustained replacement cycles for built-in hobs as modular kitchen adoption accelerates.
- SASO efficiency tier revisions:Upcoming threshold adjustments are filtering substandard imports and creating protected space for compliant suppliers with in-country testing partnerships.
- Automatic ignition technology:Consumer rejection of manual lighting methods is driving specification upgrades across mid-market residential segments.
Market Restraints
- Stainless steel price volatility:Input cost swings for burner housings and surface plates compress margin predictability for finished goods importers.
- Testing infrastructure concentration:Limited SFDA-authorized laboratories in Jeddah and Riyadh create bottlenecks for certification timelines.
- Induction cooking substitution:Electric alternatives are capturing share in new high-end residential towers with integrated smart home specifications.
Strategic Opportunities
- Eastern Province hospitality expansion:Hotel and restaurant construction in Dammam and Al Khobar is creating commercial kitchen equipment demand with shorter replacement cycles than residential.
- Flame failure device mandate trajectory:Anticipated installation code tightening presents first-mover advantage for suppliers pre-certified to advanced safety specifications.
- Authorized service network gaps:Electronic ignition complexity is opening recurring revenue streams for dealers capable of warranty and post-warranty maintenance contracts.
Industry Challenges
- Certification timeline compression:SFDA documentation requirements for gas appliance safety are extending product launch windows by multiple quarters.
- Spare parts inventory coordination:Burner assembly and control valve lead time management across Saudi distributor channels demands working capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Gas Hobs Market |
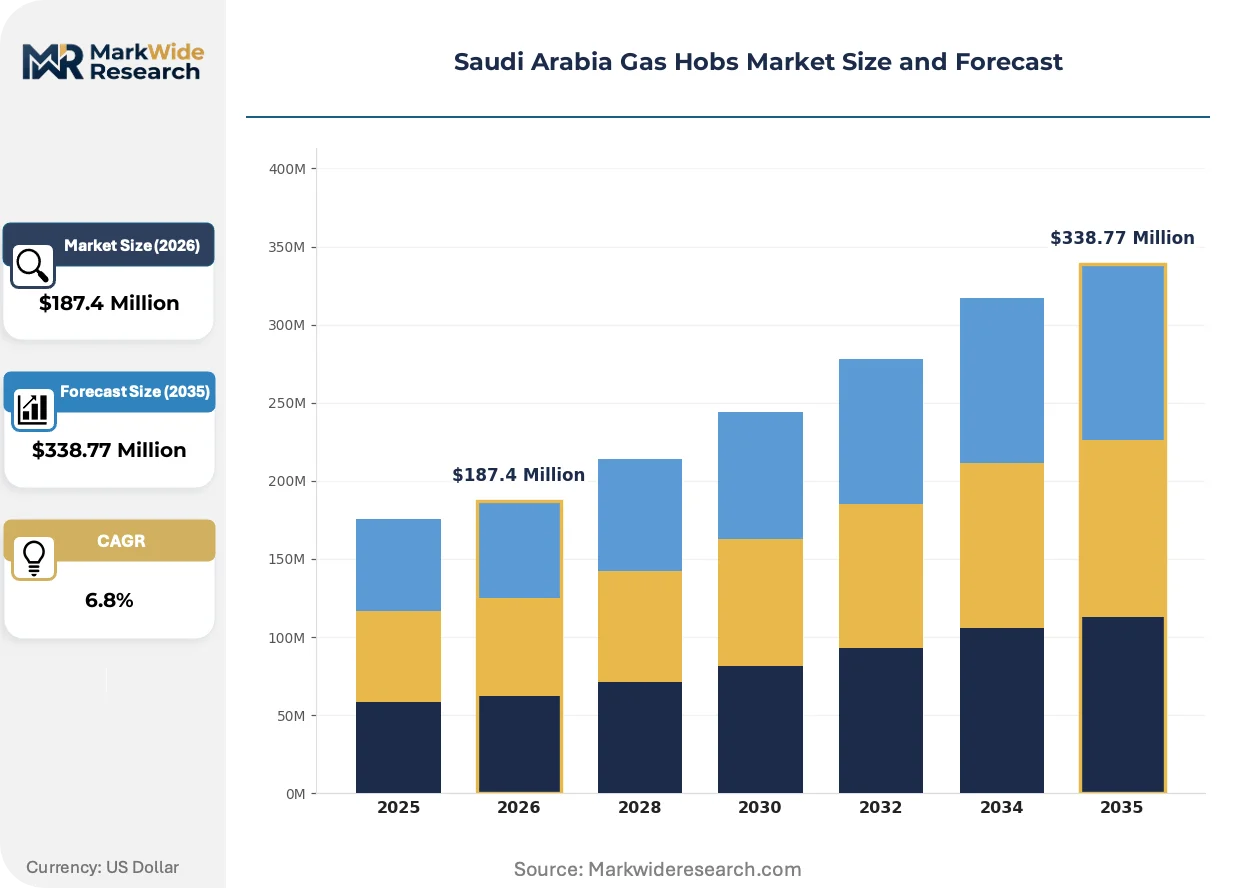
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Hobs, Built-in Hobs, Freestanding Hobs, Modular Hobs Technology: Manual Ignition, Automatic Ignition, Flame Failure Device, Flame Sensor End User: Residential, Commercial, Industrial, Kitchen Showrooms Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Ariston, Simfer, Electrolux, Glem, Candy, Whirlpool, Gorenje, Beko, Elba, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Gas Hobs Market Evolving Landscape
Tempered glass surfaces and electronic control modules are displacing traditional mechanical configurations, while regulatory pressure on safety systems and shifting procurement patterns among hospitality operators are redefining supplier relationships.
Smart connectivity modules with WiFi-enabled temperature monitoring and remote flame adjustment are virtualizing the traditional hob interface. Premium residential developers in Riyadh's northern districts are specifying these systems for luxury villa projects. This technology is virtualizing service relationships by enabling predictive maintenance alerts that bypass traditional dealer dispatch models.
SFDA appliance safety certification requirements are tightening documentation standards for all gas hobs entering Saudi ports. The framework now demands third-party testing from in-country accredited laboratories before customs release. Built-in hob importers with established Riyadh and Jeddah testing partnerships are absorbing compliance costs faster than new entrants reliant on overseas certification.
Large hospitality groups are consolidating procurement through direct manufacturer relationships rather than traditional distributor channels. Hotel operators in Jeddah's Red Sea tourism corridor are negotiating volume frameworks that bundle installation, commissioning, and multi-year service into single contracts. This concentration is most visible in the Western Region where international brand mandates standardize equipment specifications across property portfolios.
Saudi Arabia Gas Hobs Market Segmentation
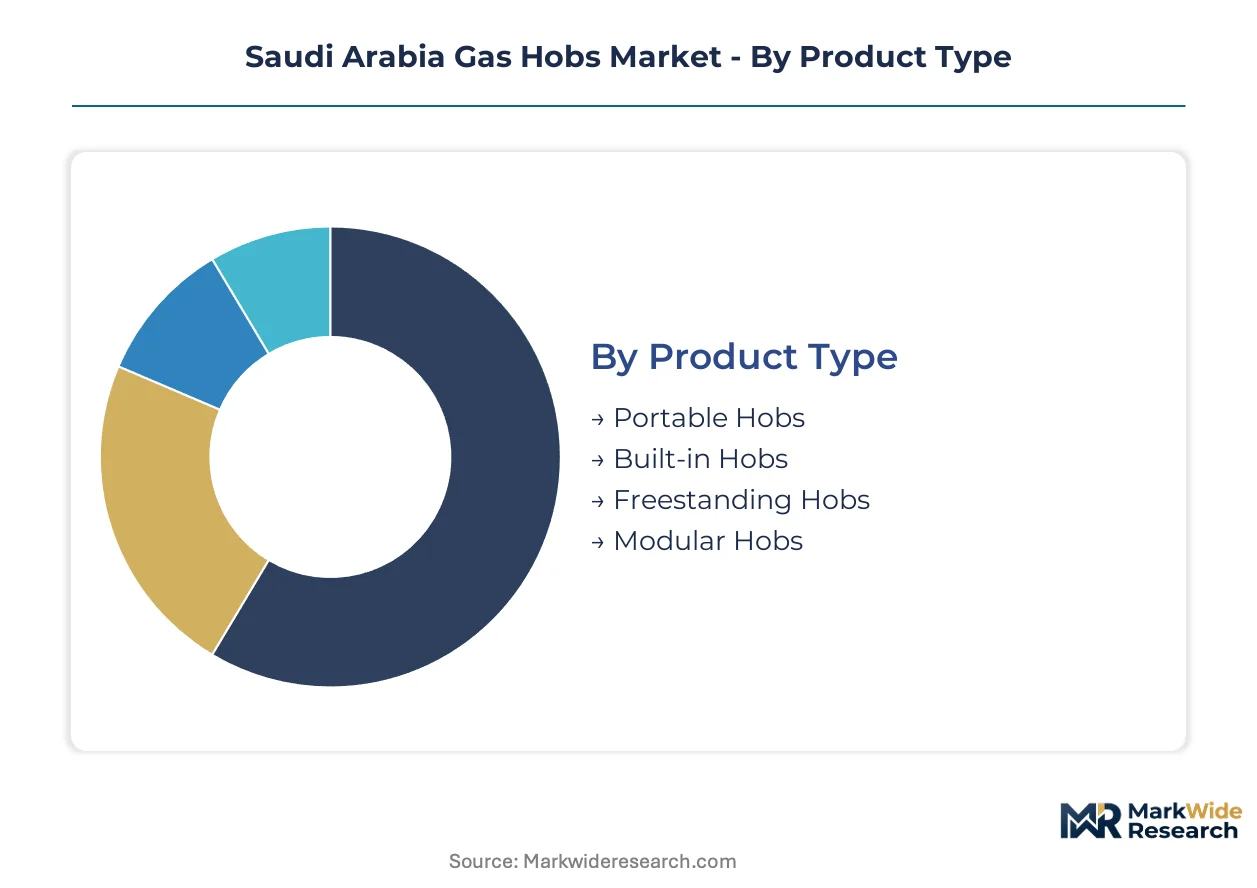
Gas hob segmentation in Saudi Arabia reflects divergent kitchen architectures across residential, hospitality, and industrial environments. Product configuration, ignition technology, and channel access each create distinct competitive battlegrounds shaped by SASO compliance requirements and regional construction patterns.
Product Type:
Mature built-in formats dominate new residential fit-outs, while portable and modular alternatives address emerging flexibility demands in commercial and rental segments.
- Built-in Hobs:These units integrate directly into countertop surfaces with sealed burner assemblies and flush-mounted control panels. Riyadh's northern villa developments and Jeddah's luxury residential towers specify these almost exclusively as modular kitchen adoption accelerates.
- Freestanding Hobs:Self-contained units with integrated bases and side panels allow repositioning without cabinetry modification. Rental properties across Dammam's expatriate housing stock favor these for lease turnover flexibility and reduced installation liability.
- Portable Hobs:Compact single-burner or dual-burner units with countertop placement and LPG cylinder compatibility serve outdoor catering and temporary kitchen setups.
- Modular Hobs:Configurable burner arrangements with interchangeable griddle, wok, and standard burner elements adapt to specialized commercial cooking workflows.
Built-in hobs handle the majority of throughput; modular hobs are gaining share fastest as hospitality operators seek equipment flexibility.
Technology:
Cost tiers separate legacy mechanical ignition from electronic safety systems, with regulatory pressure accelerating the premium tier's expansion.
- Automatic Ignition:Piezoelectric or battery-powered spark generation eliminates manual lighting, with consumer rejection of match-lit operation driving specification upgrades across mid-market Riyadh and Jeddah residential sales.
- Flame Failure Device:Thermocouple or ionization sensors cut gas supply within seconds of flame extinction, with anticipated SFDA installation code tightening positioning pre-certified suppliers for first-mover advantage.
- Manual Ignition:Match or lighter-dependent operation persists in budget-conscious segments and legacy equipment replacement cycles.
- Flame Sensor:Advanced optical or thermal monitoring systems enable smart home integration and predictive maintenance alerts in premium villa specifications.
Automatic ignition commands the largest installed base; flame failure devices are expanding most quickly on regulatory momentum.
End User:
Application diversity spans single-family consumption through institutional procurement, with volume concentration and margin profiles diverging sharply.
- Residential:Single-family and multi-family household installations drive replacement cycles tied to kitchen renovation activity, with Central Region housing stock generating sustained demand for built-in configurations.
- Commercial:Restaurants, hotels, and catering operations demand heavy-duty burner assemblies with shorter replacement cycles than residential, with Eastern Province hospitality expansion creating concentrated procurement opportunities.
- Industrial:Large-scale food production facilities and institutional cafeterias specify high-capacity modular systems with centralized maintenance contracts.
- Kitchen Showrooms:Display and demonstration units for retailer environments require aesthetic finishes and operational reliability for continuous public use.
Residential channels move the highest unit volumes; commercial applications deliver steeper expansion trajectories through hospitality sector growth.
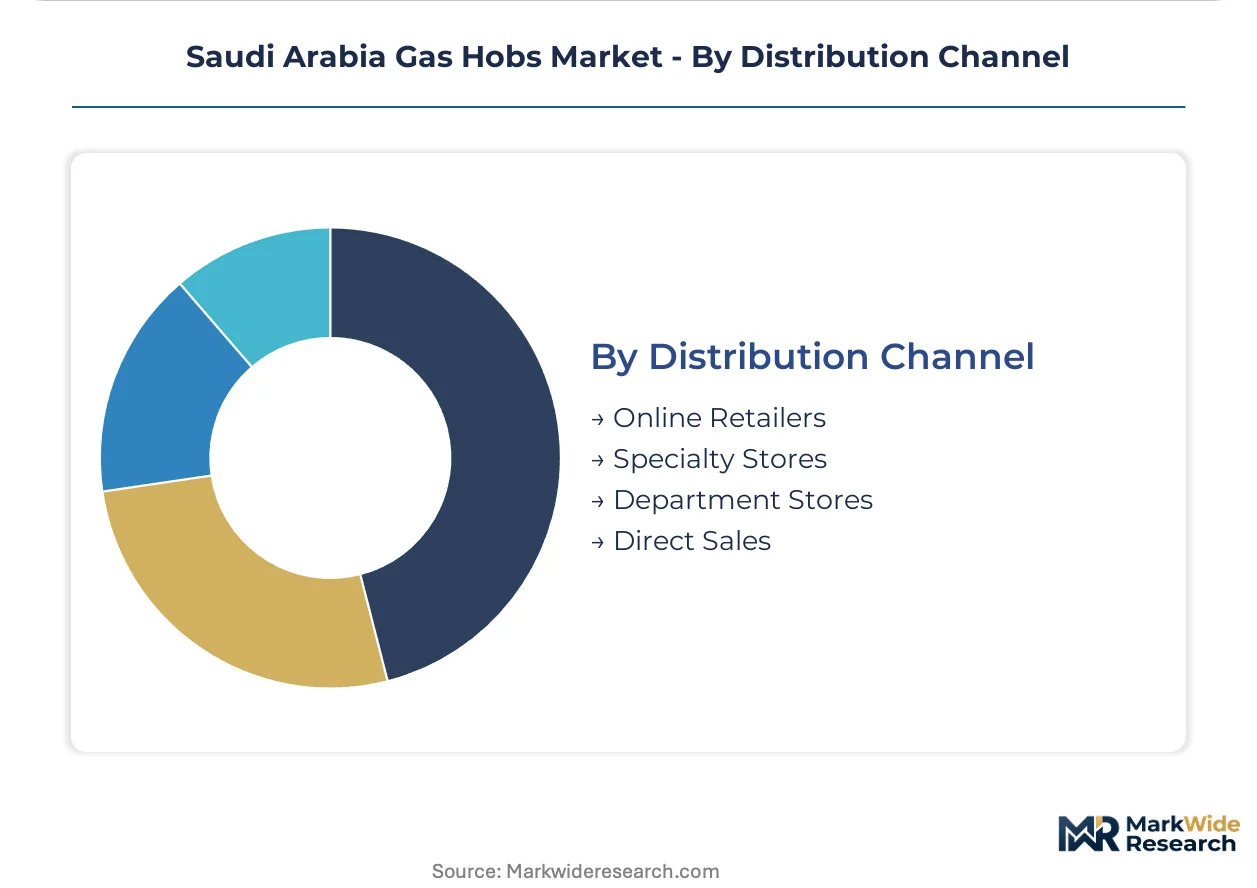
Distribution Channel:
Customer type and purchase urgency shape channel selection, with warranty complexity tilting post-sale service toward authorized networks.
- Specialty Stores:Dedicated appliance retailers with installation and commissioning capabilities capture premium built-in sales, with Riyadh and Jeddah showrooms consolidating around multi-brand portfolios.
- Online Retailers:E-commerce platforms with logistics partnerships address replacement demand and price-sensitive segments, though SASO certification documentation requirements complicate cross-border fulfillment.
- Department Stores:General merchandise retailers with home appliance sections serve impulse and gift purchases, particularly for portable and entry-level freestanding units.
- Direct Sales:Manufacturer-to-operator relationships bypass distributor margins for large hospitality groups, with Jeddah Red Sea tourism corridor hotels negotiating bundled installation and multi-year service frameworks.
Specialty stores retain the dominant transaction share; direct sales channels are climbing fastest as hospitality procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import certification bottlenecks concentrate compliance activity around Riyadh and Jeddah testing partnerships. Regional demand patterns track housing construction cycles and hospitality investment corridors across the Kingdom's four primary economic zones.
Riyadh
Central Region housing stock and modular kitchen adoption drive built-in hob specifications across northern villa developments and luxury residential towers. SFDA safety certification requirements filter substandard imports through mandatory third-party laboratory testing before customs release. Riyadh's distributor networks consolidate around multi-brand specialty retailers with installation capabilities.
Eastern Province
Dammam and Al Khobar hospitality construction generates commercial kitchen equipment demand with compressed replacement cycles compared to residential applications. SASO energy efficiency tier revisions elevate compliance thresholds for imported appliances entering through King Abdulaziz Port. Hotel operators negotiate direct manufacturer relationships bundling installation and multi-year service frameworks.
Western Region
Jeddah's Red Sea tourism corridor concentrates procurement for international hotel brands with standardized equipment specifications across property portfolios. Flame failure device mandates tighten installation codes ahead of anticipated SFDA regulatory adjustments. Western Region distributor channels face margin compression as hospitality groups consolidate procurement through direct sales channels.
NEOM Northwest
Smart city construction specifications integrate WiFi-enabled temperature monitoring and remote flame adjustment systems for premium villa developments. NEOM procurement frameworks prioritize suppliers with established Saudi service infrastructure and localized spare parts inventory. Modular kitchen design standards in the linear city project accelerate specification shifts toward built-in configurations.
Saudi Arabia Gas Hobs Market Competitive Landscape
European appliance conglomerates and Turkish manufacturing specialists split the market between premium-tier positioning and volume-driven replacement part availability. Market access concentrates around distributors with SFDA-authorized testing partnerships and established spare parts logistics. Three archetypes dominate: heritage European brands with regional service infrastructure, Turkish manufacturers competing on replacement part lead times, and diversified home appliance conglomerates leveraging portfolio breadth. Competitive moves center on authorized service network expansion and pre-certification to anticipated flame failure device mandates.
Among European heritage manufacturers, Ariston and Electrolux occupy positions anchored by extended warranty programs and recurring maintenance contract capture. Beko exemplifies the Turkish manufacturing archetype competing on burner assembly and control valve availability across Saudi distributor channels. These three companies represent distinct strategic postures within a market restructuring around compliance capability and service infrastructure depth.
| Leading Market Players |
|---|
| Ariston |
| Simfer |
| Electrolux |
| Glem |
| Candy |
| Whirlpool |
| Gorenje |
| Beko |
| Elba |
| Others |
Value Network & Pricing Analysis
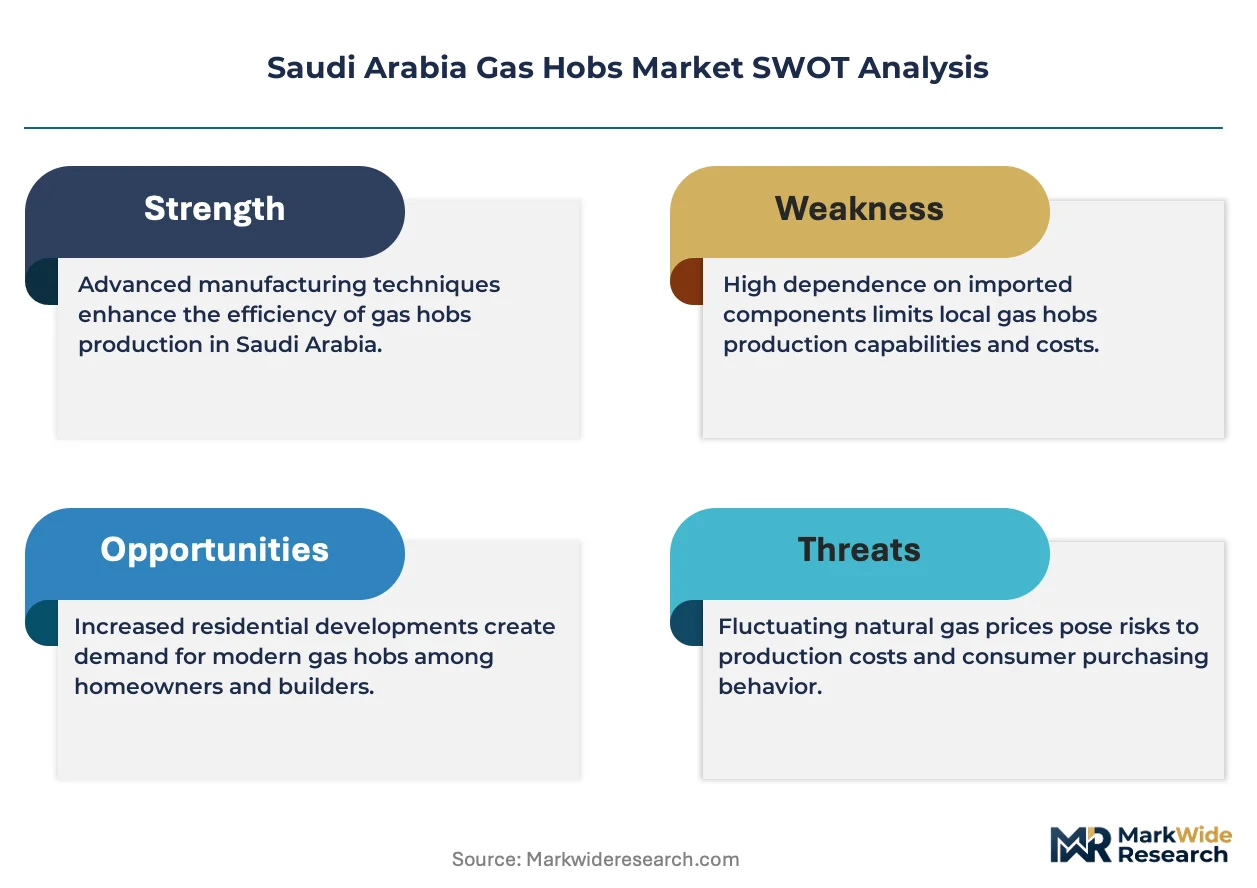
Turkish manufacturing clusters anchor burner assembly and control valve production, concentrating margin capture in aftermarket service tiers where authorized dealer networks extract recurring revenue from electronic ignition complexity. This upstream concentration funnels pricing power toward incumbents with established Saudi spare parts logistics, compressing margin pools for new entrants dependent on overseas sourcing.
Pricing Analysis
Aftermarket service contracts and extended warranty programs drive lifetime value differentiation across the Saudi market. Three-tier pricing structure across premium, standard, and economy levels separates European heritage brands with full-service bundling from Turkish manufacturers competing on replacement part availability and budget imports facing certification cost barriers. Pricing pressure stems from stainless steel input volatility and SFDA compliance cost absorption, with hospitality procurement consolidation amplifying volume discount leverage. Expatriate rental housing segments exhibit highest price sensitivity, while luxury villa developers in Riyadh's northern districts show lowest sensitivity to upfront cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Turkish EMS providers serving European brand OEMs and Chinese foundries producing burner housings for budget-tier imports. Component sourcing draws from Italy for electronic ignition modules, China for tempered glass surfaces, and Turkey for stainless steel burner assemblies. Single-source vulnerability sits with SFDA-authorized testing laboratories concentrated in Riyadh and Jeddah, creating certification bottlenecks. Distribution runs through multi-brand specialty retailers with installation capabilities, though hospitality direct sales channels are bypassing traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospitality procurement consolidation and large developer direct negotiations, fragmenting traditional distributor influence across the Saudi gas hobs market.
For Market Incumbents: Insulate margin pools by deepening backward integration into burner assembly production and securing captive SFDA testing partnerships in Riyadh. Certification timeline compression from documentation requirement extensions threatens product launch windows, demanding pre-emptive regulatory investment. Channel control through authorized service network expansion locks in recurring maintenance revenue as electronic ignition complexity rises. For New Entrants and Emerging Players: Pursue white-space positioning in Eastern Province hospitality construction, where Dammam and Al Khobar hotel development creates commercial kitchen demand with shorter replacement cycles than residential. Modular hob configurations for specialized cooking workflows represent the most penetrable product tier. A go-to-market angle bundling installation, commissioning, and multi-year service contracts mirrors successful Western Region hospitality procurement patterns. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Turkish manufacturing specialists holding established Saudi distributor relationships and replacement part logistics. Long-term viability hinges on regulatory compliance infrastructure depth rather than volume scale alone. The signal to watch is SFDA flame failure device mandate timing, which will force product line adjustments and consolidate competitive access around pre-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Pre-Certification Investment | Early compliance with anticipated flame failure device mandates secures market access ahead of enforcement deadlines. |
| Authorized Service Network Expansion | Electronic ignition complexity creates recurring revenue streams through warranty and post-warranty maintenance contracts. |
| Direct Hospitality Procurement Relationships | Bundled installation and multi-year service frameworks bypass distributor margins in Jeddah's Red Sea tourism corridor. |
| Backward Integration into Burner Assembly Production | In-house production of control valves shortens lead times and insulates margin from stainless steel price volatility. |
| Smart Connectivity Module Development | WiFi-enabled temperature monitoring addresses NEOM premium villa specifications and virtualizes service relationships. |
Research Methodology
Initial hypotheses were tested against primary input from appliance distributor executives, SFDA regulatory affairs specialists, hospitality procurement managers, and aftermarket service technicians, then refined through secondary validation. Bottom-up and top-down triangulation combined customs import records, SASO energy efficiency registry data, and construction permit filings from Riyadh and Jeddah municipal authorities.
Demand-supply balance modeling across the projection horizon incorporated product type, ignition technology, end-user segment, and distribution channel dimensions. CAGRs were derived from replacement cycle analysis tied to housing stock age profiles and hospitality construction pipelines. Forecast inputs included SFDA regulatory trajectory assumptions and stainless steel price correlation models.
Macroeconomic conditions sit as an overlay; deviation in residential construction lending rates or expatriate housing policy would shift the trajectory. Quarterly review of SFDA draft regulation releases and SASO efficiency tier revision announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Colombia Laundry Appliances Market
Appliances
Cooker Hoods Market
Appliances
North America Microwave Oven Market
Appliances
Europe Household Electric Grills Market
Appliances
Global Electric Water Heaters Market
Appliances
UAE Dishwasher Market
Appliances
France Household Electric Grills Market
Appliances
Microwave Oven Market
Appliances
Electric Iron Market
Appliances
Qatar Dishwashers Market
Appliances
Small Appliances Market
Appliances
Israel Laundry Appliances Market
Appliances
Smart Microwave Oven Market
Appliances
Small Electric Kettles Market
Appliances
Mobile Refrigerators Market
Appliances
United States Commercial Laundry Appliances Market