
 Australia Baby Care Products Market | 2026-2036
Australia Baby Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Baby Care Products Market Insights
Subscription-based replenishment financing is tilting competitive dynamics toward brands with direct-to-consumer infrastructure. Procter & Gamble leverages its Gillette Club logistics backbone to lock in recurring diaper revenue. Kimberly-Clark anchors its market position through HUGGIES Australia's pharmacy and supermarket shelf-space dominance. Unilever competes via specialty skincare formulations that command premium pricing in boutique retail channels.
Australia baby care products encompass formulated goods for infant hygiene, skin protection, and comfort maintenance, typically specifying pH-balanced compositions between 4.5 and 5.5 to match neonatal skin chemistry and utilizing non-woven absorbent cores in diaper construction. These products serve parents, caregivers, and pediatric healthcare facilities seeking dermatologically tested solutions for routine infant maintenance. Diapers and wipes occupy the largest volume share due to daily-consumption replenishment cycles, while lotions and creams capture concentrated margin pools through premium positioning in pharmacy and specialty retail. Online retail channels represent the fastest-growing distribution vector as fulfillment networks shorten delivery windows for bulky diaper cartons.
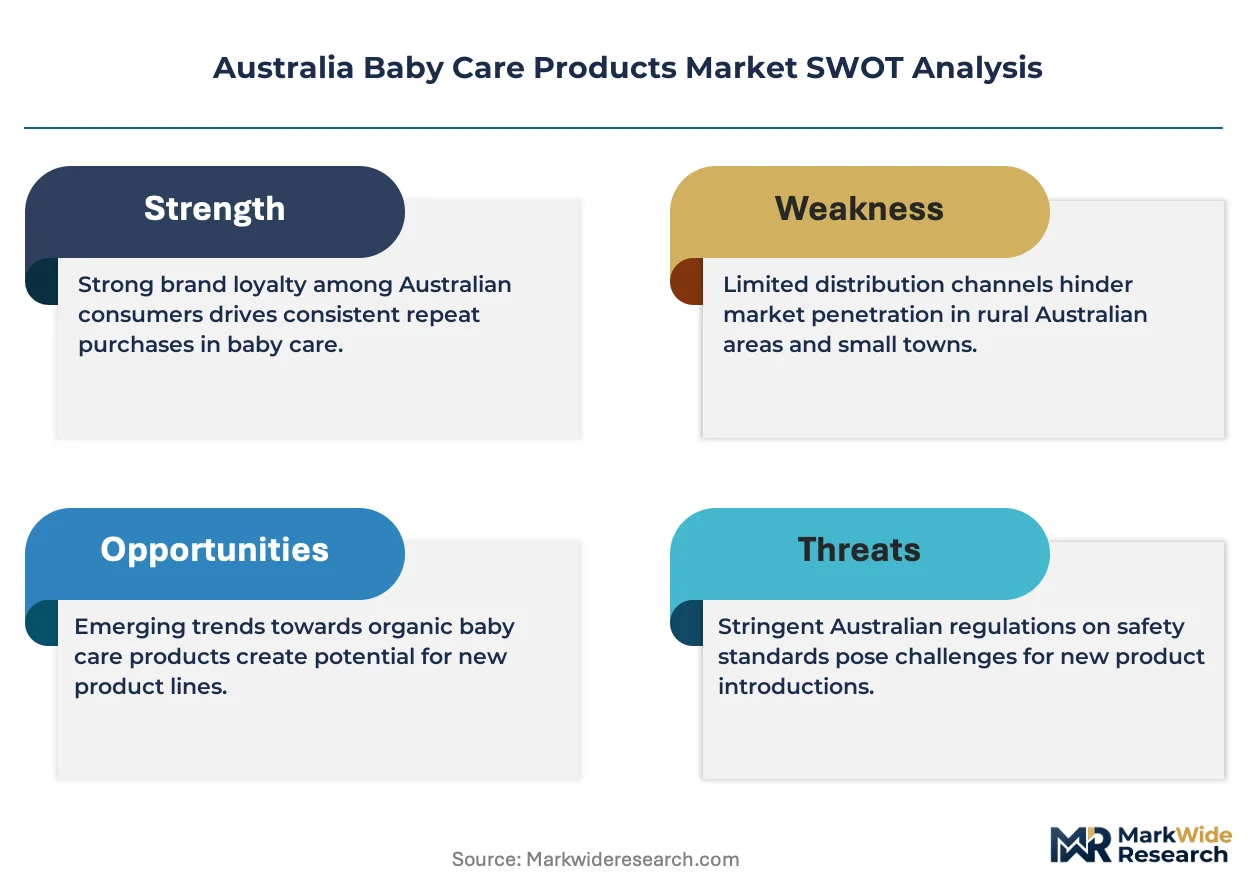
TGA mandates govern cosmetic and therapeutic ingredient disclosures, while ACCC consumer protection frameworks enforce labeling accuracy for products targeting infants. The Therapeutic Goods Administration's evolving sunscreen classification rules extend to baby skincare, compelling reformulation investments from domestic and imported brands. Stakeholders must monitor pending ACCC sustainability claims enforcement and its potential to reshape packaging and ingredient marketing strategies.
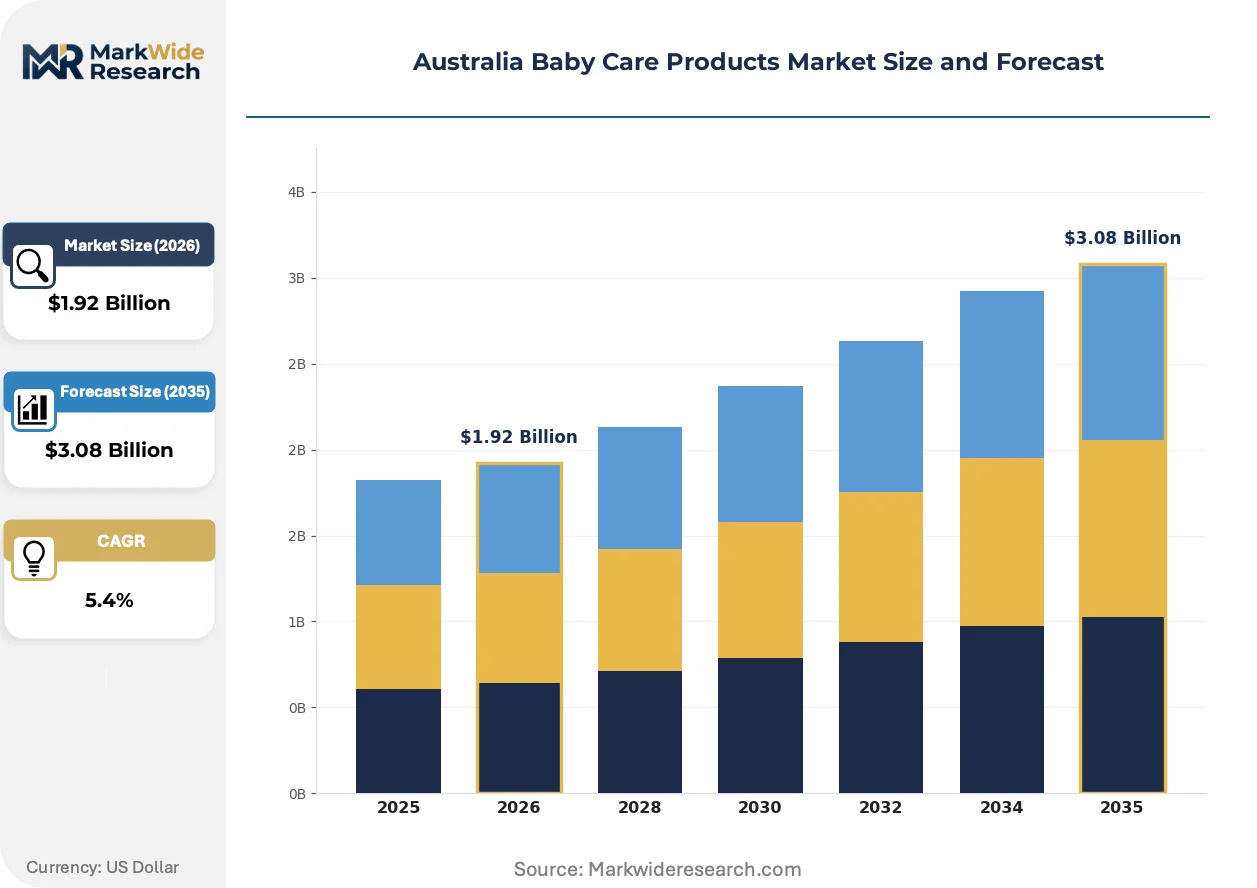
Market Dynamics
Subscription replenishment models are restructuring competitive dynamics in Australian baby care, rewarding brands with direct-to-consumer infrastructure and penalizing those dependent on traditional retail shelf space.
Growth Catalysts
- Millennial urban demand:Parents in Sydney and Melbourne demonstrate elevated willingness to pay for organic formulations, expanding the addressable premium segment.
- TGA ingredient mandates:Disclosure requirements compel manufacturers to reformulate product lines, accelerating category innovation cycles and raising quality baselines.
- Online fulfillment acceleration:Shortened delivery windows for bulky diaper cartons are virtualizing distribution economics and enabling new market entrants.
Market Restraints
- Supermarket shelf-space concentration:Coles and Woolworths control dominant retail real estate, creating barriers for emerging brands without established trade relationships.
- Import dependency for absorbent cores:Non-woven materials rely heavily on Asian supply chains, exposing margins to freight cost volatility and currency fluctuation.
- TGA therapeutic classification friction:Evolving sunscreen rules extend compliance burdens to baby skincare, requiring reformulation investments that strain smaller domestic players.
Strategic Opportunities
- Underpenetrated Queensland and Western Australia:Regional centers outside Sydney-Melbourne corridors show lagging premium product penetration relative to disposable income levels.
- Pharmacy channel specialization:Chemist Warehouse and Priceline Pharmacy networks offer dermatologist-endorsed positioning unavailable in mass retail.
- ACCC sustainability enforcement preparation:Pending packaging and ingredient marketing rules create first-mover advantage for brands with verified environmental credentials.
Industry Challenges
- Pediatric dermatology expertise scarcity:Formulation teams with neonatal skin chemistry specialization command premium compensation, constraining R&D expansion.
- Legacy ERP integration with DTC platforms:Established manufacturers struggle to synchronize inventory systems across wholesale and direct channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Baby Care Products Market |
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.08 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Wipes, Lotions, Creams Distribution Channel: Supermarkets, Online Retail, Pharmacies, Specialty Stores End User: Parents, Caregivers, Hospitals, Pediatric Clinics Packaging Type: Boxes, Pouches, Bottles, Tubs |
| Companies Covered | Unilever plc, Danone S.A., Procter & Gamble Company, HUGGIES Australia, Nestlé S.A., Kimberly-Clark Corporation, Unicharm Corporation, Ontex Australia, Johnson & Johnson Services, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Baby Care Products Market Trends and Innovations
Digital-native replenishment architectures are compressing traditional retail intermediation, while regulatory disclosure mandates and parental information-seeking behaviors reshape product development priorities across the category.
Biodegradable absorbent materials are virtualizing the environmental footprint of diaper manufacturing. Premium brands in Victoria and New South Wales are adopting plant-based core alternatives at accelerated procurement cycles. This substitution is virtualizing competitive differentiation away from absorbency metrics toward sustainability credentials.
TGA's evolving therapeutic goods classification rules now capture baby sunscreen formulations previously regulated as cosmetics. Manufacturers must submit clinical efficacy data and reformulate SPF claims, compressing product development timelines. Domestic brands with established TGA relationships are adapting faster than import-dependent competitors.
Subscription-based auto-replenishment is displacing episodic supermarket purchasing among urban millennial households. Direct-to-consumer platforms capture diaper and wipe volume previously routed through Coles and Woolworths, shortening repurchase cycles and deepening brand loyalty. This behavioral shift concentrates most visibly in Sydney and Melbourne metropolitan statistical areas.
Australia Baby Care Products Market Segmentation
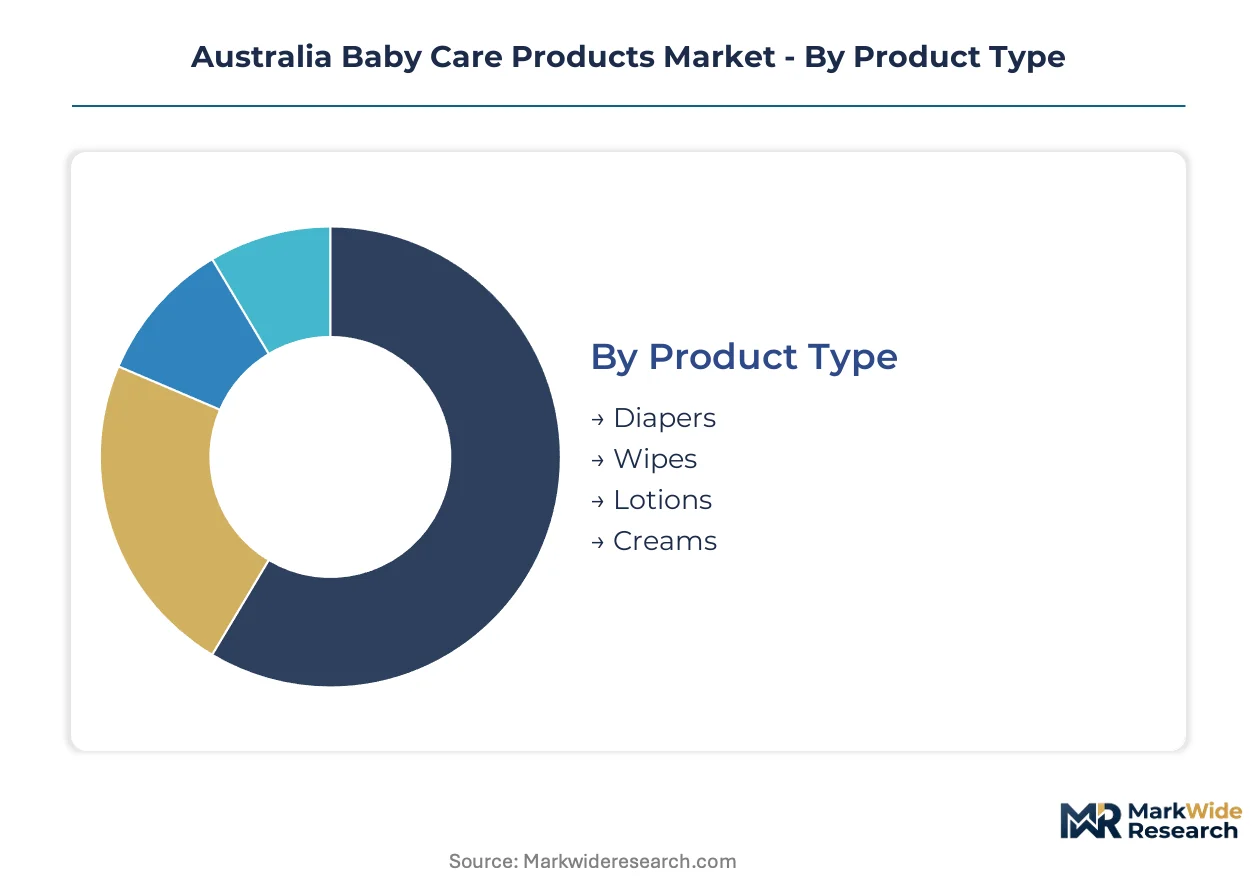
Segmentation in Australian baby care reveals how consumption patterns bifurcate between daily replenishment commodities and premium dermatological solutions. Understanding these divides exposes where margin pools concentrate versus where volume economies dominate procurement strategy.
Product Type:
Cost tier stratification separates high-frequency disposable purchases from episodic premium skincare investments.
- Diapers:Non-woven absorbent cores with pH-balanced surface layers dominate material specifications. Demand concentrates in Sydney and Melbourne metropolitan households where subscription replenishment is displacing supermarket stock-ups.
- Wipes:Biodegradable fiber substrates and preservative-free formulations define the premium tier. Parents in New South Wales and Victoria demonstrate elevated willingness to pay for organic certification marks.
- Lotions:Emulsion-based barrier products targeting neonatal skin chemistry.
- Creams:Zinc oxide and petroleum jelly formulations for diaper rash treatment.
Diapers command the established base. The steepest expansion runs through lotions.
Distribution Channel:
Application context dictates channel selection — emergency replenishment versus planned premium procurement.
- Supermarkets:Coles and Woolworths control shelf-space real estate for diaper and wipe volume. The concentration of weekly grocery trips in suburban corridors locks in high-frequency purchasing patterns.
- Online Retail:Direct-to-consumer platforms capture auto-replenishment subscriptions. Shortened delivery windows in Sydney and Melbourne metropolitan areas enable bulky carton fulfillment without retail intermediation.
- Pharmacies:Chemist Warehouse and Priceline Pharmacy networks offer dermatologist-endorsed positioning for skincare formulations.
- Specialty Stores:Boutique retail channels in affluent Melbourne and Sydney suburbs.
Supermarkets anchor volume throughput. Online retail is climbing the fastest.
End User:
Customer type determines formulation sensitivity and purchasing authority structures.
- Parents:Millennial households in urban centers drive organic formulation premiums and subscription adoption.
- Caregivers:Professional childcare facilities prioritize cost efficiency and bulk procurement.
- Hospitals:Neonatal intensive care units specify medical-grade barrier creams with TGA therapeutic classifications.
- Pediatric Clinics:Dermatology practices recommend prescription-aligned skincare regimens.
Parents command the established base. Pediatric clinics show the steepest expansion trajectory.
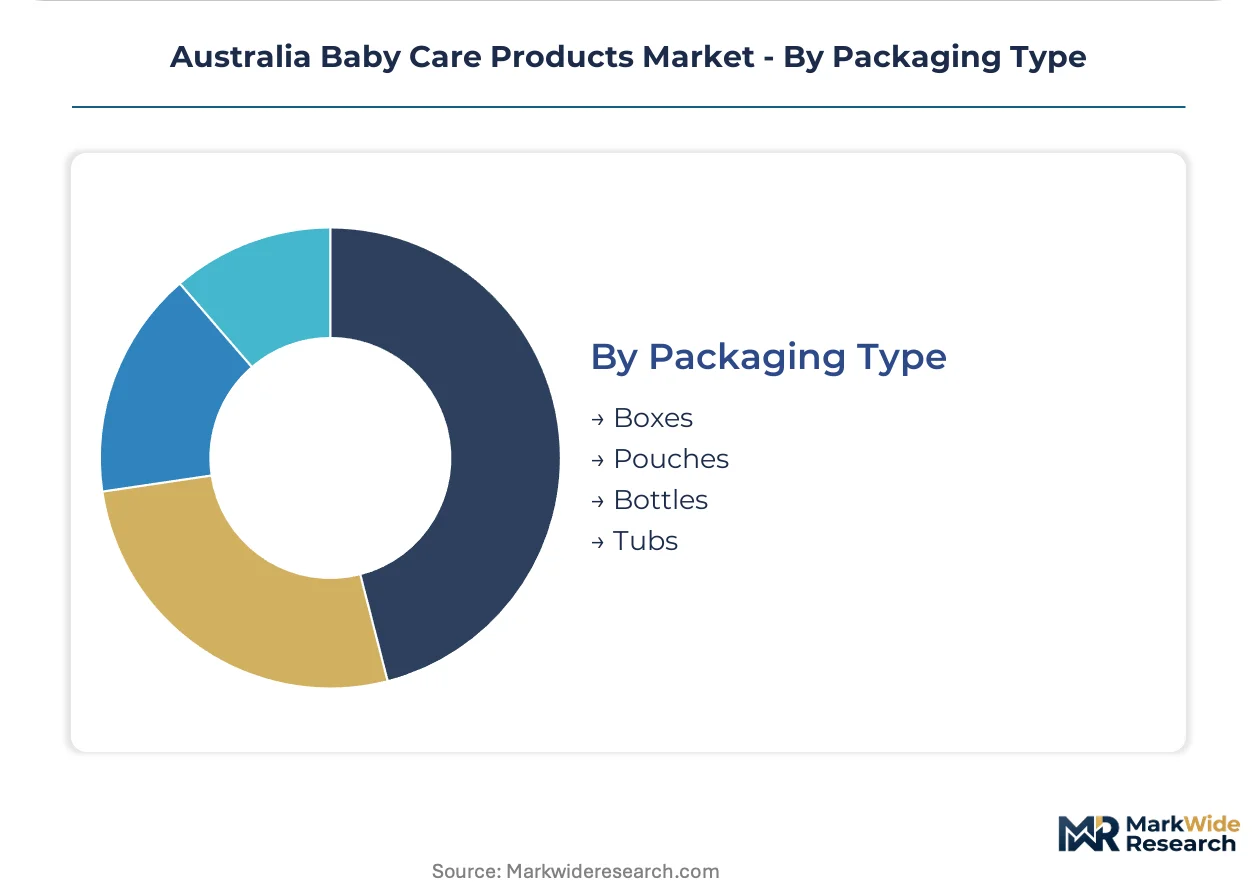
Packaging Type:
Volume and portability requirements shape material selection and sustainability positioning.
- Boxes:Corrugated shipping cartons for diaper bulk packs dominate e-commerce fulfillment.
- Pouches:Flexible film structures for wipe refills enable retail shelf efficiency.
- Bottles:Pump-dispenser formats for lotion and wash products.
- Tubs:Wide-mouth containers for cream and ointment applications.
Boxes anchor the established base. Pouches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial parents in Sydney and Melbourne drive premium category expansion through organic formulation preferences, while regional centers present underpenetrated growth vectors. TGA disclosure mandates and ACCC consumer protection frameworks shape compliance investments across all states.
New South Wales
Sydney metropolitan households anchor subscription replenishment adoption for diapers and wipes. TGA therapeutic goods classification rules compel sunscreen reformulation investments from brands targeting the market. Parramatta and North Shore childcare clusters prioritize bulk procurement contracts with dermatologist-endorsed suppliers.
Victoria
Melbourne's inner suburbs demonstrate elevated willingness to pay for biodegradable fiber substrates in premium wipe tiers. ACCC sustainability claims enforcement pressures packaging redesign investments from domestic manufacturers. The Monash medical research corridor connects pediatric dermatology expertise to local formulation teams.
Queensland
Brisbane-Gold Coast conurbation households show lagging premium product penetration relative to disposable income indicators. TGA ingredient disclosure mandates accelerate quality baseline improvements among import-dependent distributors. Cairns and Townsville regional centers rely on supermarket shelf-space concentration from Coles and Woolworths networks.
Western Australia
Perth metropolitan demand concentrates in standard-tier diaper segments with slower subscription adoption than eastern states. Freight cost volatility from Asian non-woven supply chains compresses margins for distributors serving remote mining communities. The Karratha-Port Hedland corridor presents specialized bulk-procurement opportunities for fly-in-fly-out workforce childcare facilities.
South Australia
Adelaide's pharmacy channel networks offer dermatologist-endorsed positioning for barrier cream formulations targeting neonatal intensive care units. TGA clinical efficacy data requirements for therapeutic classifications favor established brands with regulatory relationships. The Barossa Valley and Fleurieu Peninsula regional markets remain tethered to supermarket replenishment cycles.
Australia Baby Care Products Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Supermarket shelf-space concentration around Coles and Woolworths rewards established trade relationships, while direct-to-consumer infrastructure enables subscription-based revenue capture. Three archetypes dominate: multinational FMCG conglomerates with logistics scale, domestic pharmacy-channel specialists with dermatological credibility, and digital-native entrants with fulfillment agility. Competitive moves center on M&A for DTC platform acquisition and strategic partnerships for biodegradable material sourcing.
Among multinational conglomerates, Unilever plc and Procter & Gamble Company exemplify scale-driven positioning with established TGA compliance histories and wholesale distribution networks. HUGGIES Australia represents the pharmacy and supermarket shelf-space anchor archetype, leveraging trade relationship depth to maintain volume throughput. These three entities occupy positions across the premium-standard-economy pricing spectrum while navigating ACCC sustainability enforcement preparation.
| Leading Market Players |
|---|
| Unilever plc |
| Danone S.A. |
| Procter & Gamble Company |
| HUGGIES Australia |
| Nestlé S.A. |
| Kimberly-Clark Corporation |
| Unicharm Corporation |
| Ontex Australia |
| Johnson & Johnson Services, Inc. |
| Others |
Pricing and Supply Chain Analysis
Asian non-woven manufacturing clusters in Guangdong and Zhejiang provinces anchor global absorbent core capacity, with freight cost volatility transmitting directly into Australian distributor margins and compressing pricing power for standard-tier diaper imports.
Pricing Analysis
Cost-plus contracts with Asian material suppliers index to freight and currency benchmarks, embedding volatility into landed costs. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified formulations from TGA-compliant basics and private-label alternatives. Price differentiation hinges on dermatological endorsement tier and subscription bundling depth. Pricing pressure stems from Coles and Woolworths volume negotiations, which squeeze mid-tier brands between premium positioning and economy alternatives. Childcare facilities exhibit highest price sensitivity, while Sydney millennial households demonstrate lowest sensitivity for certified-organic tiers.
Supply Chain Analysis
Contract manufacturing concentrates with Ontex Group and Unicharm Corporation facilities across Japan, Thailand, and China, which supply finished goods and semi-processed absorbent cores to Australian distributors. Raw material dependencies encompass petroleum-derived superabsorbent polymers, fluff pulp from Scandinavian forestry operations, and elastic non-woven fabrics. Single-source vulnerability runs through the Malacca Strait logistics chokepoint, which channels container traffic from Northeast Asian production hubs. Distribution runs through Coles and Woolworths centralized replenishment centers for mass retail, with direct-to-consumer platforms bypassing wholesale intermediation for subscription volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric dermatology formulation expertise represents the critical capability gap constraining R&D expansion, as qualified chemists command premium compensation and limit domestic brand innovation velocity.
For Market Incumbents: Pre-empt subscription platform consolidation by acquiring direct-to-consumer infrastructure before digital-native entrants capture Sydney and Melbourne household loyalty. Defend pharmacy channel positioning through TGA therapeutic classification investments that emerging brands cannot replicate. Prioritize backward integration into biodegradable fiber sourcing to lock in sustainable material supply ahead of ACCC enforcement deadlines. For New Entrants and Emerging Players: Establish a beachhead in Queensland and Western Australia regional centers where premium penetration lags disposable income indicators. Target pharmacy channel distribution through Chemist Warehouse and Priceline networks, which offer dermatologist-endorsed credibility unavailable in mass retail. Leverage fulfillment partnerships with local logistics providers to overcome supermarket shelf-space barriers. For Investors and Strategic Acquirers: Long-term, this sits as a subscription-infrastructure play because recurring revenue models concentrate customer lifetime value and reduce customer acquisition cost burdens. Target acquisition profiles should emphasize digital-native brands with established auto-replenishment platforms and TGA compliance histories. Watch for inflection in biodegradable material cost parity as the signal for sustainable tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Captures subscription revenue from Coles and Woolworths volume channels in Sydney and Melbourne metropolitan areas. |
| Biodegradable Material Sourcing Partnership | Locks in plant-based fiber supply ahead of ACCC sustainability claims enforcement and premium tier expansion. |
| TGA Therapeutic Classification Investment | Enables sunscreen and barrier cream positioning in Chemist Warehouse networks with prescription-aligned credibility. |
| Pharmacy Channel Expansion | Accesses dermatologist endorsement pathways unavailable through supermarket retail for skincare formulations. |
| Regional Distribution Partnership | Penetrates underdeveloped Queensland and Western Australia markets with localized fulfillment infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with brand managers, category buyers at Coles and Woolworths, pharmacy procurement leads, and pediatric dermatology formulation specialists; and secondary validation through TGA therapeutic goods registers, ACCC consumer protection filings, Nielsen retail audit data, and customs import records for non-woven materials. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs encompassed product type segmentation, distribution channel evolution, and end-user purchasing authority structures, with CAGRs derived from trend extrapolation and elasticity modeling. Modeled variables included millennial household formation rates, TGA regulatory amendment timelines, and e-commerce fulfillment cost trajectories throughout the projection horizon.
Stress conditions across freight rate volatility, currency fluctuation bands, and TGA classification rule acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subscription adoption curves and sustainability premium willingness-to-pay. Quarterly review of biodegradable material cost parity, ACCC enforcement announcements, and pharmacy channel expansion metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Prams and Strollers Market
Baby Products
Infant Care and Baby Care Equipment Market
Baby Products
Children Products Market
Baby Products
Baby Seat Liners Market
Baby Products
Baby Pacifier Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
Baby Powder Market
Baby Products
Tissue and Hygiene Market
Baby Products
Baby Feeding Bottles Market
Baby Products
Baby Digital Monitor Market
Baby Products
Postpartum Products Market
Baby Products
Baby Tableware Market
Baby Products
Baby Playpens Market
Baby Products
Soft Sole Baby Shoes Market
Baby Products
Diaper Pails Market
Baby Products
Luxury Baby Stroller Market