
 Charcoal Bristle Toothbrush Market | 2026-2036
Charcoal Bristle Toothbrush Market Size, Share, and Industry Trends Forecast 2026-2036
Charcoal Bristle Toothbrush Market Outlook
REACH compliance is pivoting the cost-of-entry calculus for European entrants, forcing reformulation of bristle binders and handle coatings. Colgate-Palmolive Company leverages its global regulatory affairs infrastructure to sustain multi-market registrations without SKU fragmentation. Unilever competes through dedicated oral-care R&D hubs in Asia that anchor charcoal-activated product pipelines. Koninklijke Philips N.V. differentiates by embedding charcoal bristle options within its connected electric toothbrush ecosystem.
A charcoal bristle toothbrush incorporates activated carbon—typically derived from coconut shell or bamboo pyrolysis at 600–900°C—infused into nylon-6 or bamboo-fiber bristle matrices to adsorb surface stains and oral malodors. The product serves both cosmetic whitening claims and antimicrobial positioning in consumer oral hygiene regimens. Manual variants dominate unit volume through mass-market accessibility, while electric configurations capture premium margin pools via replacement-head recurring revenue. Bamboo material grades are expanding fastest as retailers enforce plastic-reduction procurement mandates. Online distribution channels concentrate subscription-driven growth, though supermarkets retain impulse-purchase dominance in emerging markets.
FDA oversees bristle safety and cosmetic claim substantiation in the United States, while ECHA enforces REACH chemical restrictions on European imports. ISO 20126 standards for manual toothbrush durability create baseline quality thresholds that filter out low-cost entrants. China's NMPA and GB standards govern antimicrobial additive thresholds for products manufactured domestically. Stakeholders must monitor evolving biodegradability certifications as France's AGEC law and similar extended producer responsibility frameworks proliferate across jurisdictions.
Market Dynamics
EU Green Deal packaging waste directives are forcing wholesale material transitions across the charcoal bristle toothbrush supply chain, compressing development timelines for biodegradable handle alternatives while retailers accelerate plastic-reduction procurement mandates.
Growth Catalysts
- REACH compliance pivot:European chemical restrictions on bristle binders are accelerating reformulation investments by incumbents, raising barriers that protect established suppliers with multi-market registration infrastructure.
- Wellness-focused millennials:This demographic cohort drives SKU expansion at dm-drogerie markt and Rossmann chains, where premium shelf space allocation for charcoal-infused dental products concentrates demand in Germany.
- Bamboo pyrolysis at 600–900°C:Coconut shell and bamboo-derived activated carbon infusion into nylon-6 matrices enables dual cosmetic whitening and antimicrobial positioning that commands price premiums in oral hygiene regimens.
Market Restraints
- Nylon-6 price volatility:Petrochemical feedstock fluctuations compress margins for manufacturers dependent on synthetic bristle matrices, forcing hedging strategies that smaller entrants cannot sustain.
- Antimicrobial additive thresholds:China's NMPA and GB standards impose strict domestic manufacturing limits that fragment production planning for multinational supply chains.
- Manual variant substitution:Low-cost conventional toothbrushes retain impulse-purchase dominance in emerging market supermarkets, constraining premium charcoal SKU penetration.
Strategic Opportunities
- Connected electric ecosystem integration:Replacement-head recurring revenue models within smart toothbrush platforms offer margin pools unavailable to manual-only competitors.
- France's AGEC law proliferation:Extended producer responsibility frameworks across jurisdictions create first-mover advantages for biodegradable certification holders.
- Subscription-driven online channels:Direct-to-consumer models bypass supermarket slotting fees while capturing recurring purchase behavior from urban professional segments.
Industry Challenges
- ISO 20126 durability testing:Manual toothbrush quality thresholds require capital-intensive laboratory validation that filters out low-cost entrants before market access.
- Biodegradability certification timelines:Multi-jurisdictional approval processes for handle materials delay product launches by twelve to eighteen months against fast-fashion competitor cycles.
- Bristle-matrix integration complexity:Activated carbon dispersion uniformity demands specialized extrusion equipment that mid-tier manufacturers must source from limited European machinery suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Charcoal Bristle Toothbrush Market |
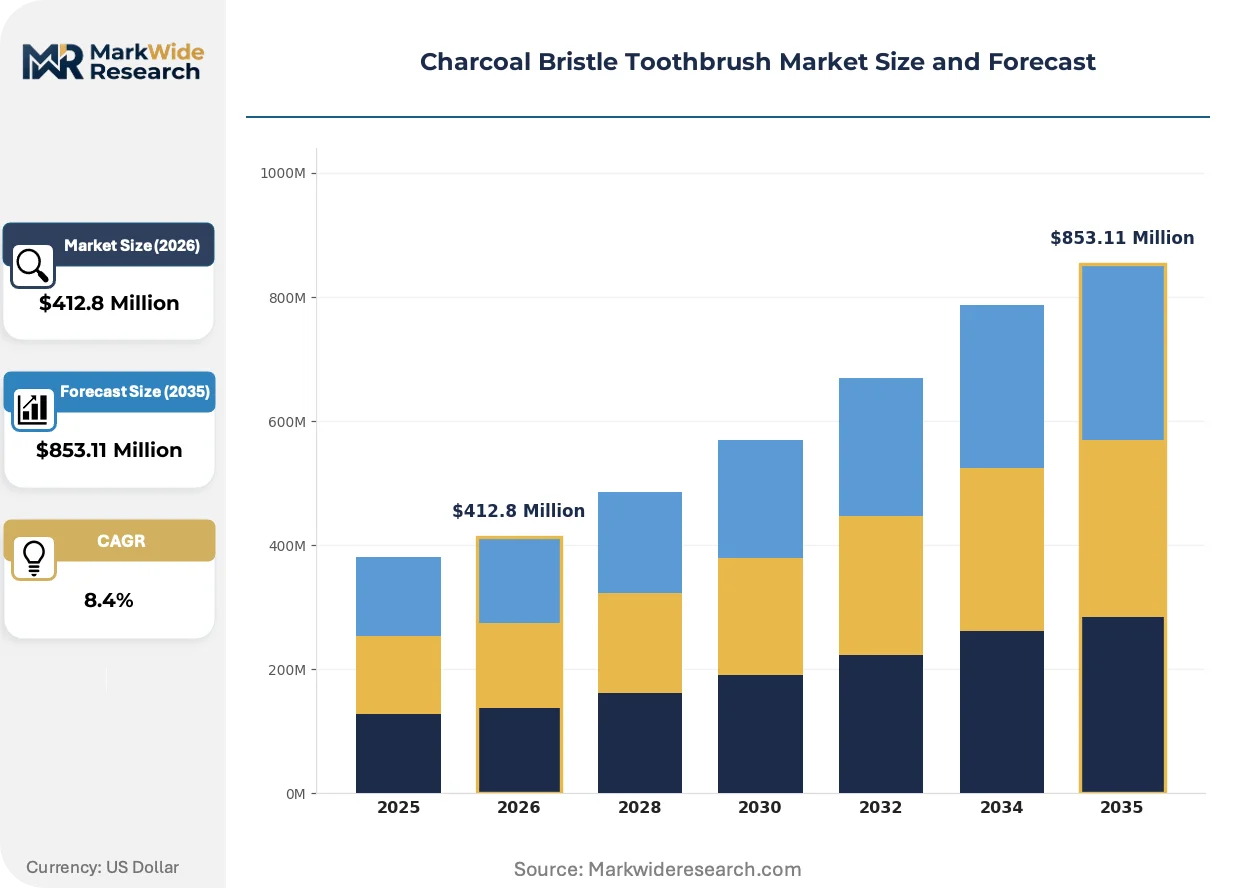
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $853.11 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Eco-friendly, Travel Customer Type: Adults, Children, Seniors, Discount Retail Material: Bamboo, Plastic, Recycled, Biodegradable Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | The Procter & Gamble Company, Colgate-Palmolive Company, Morihata International Ltd, Dental Expert, Wowe Lifestyle, Unilever, Koninklijke Philips N.V., Johnson & Johnson Services Inc., Sunstar Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Charcoal Bristle Toothbrush Market Strategic Shifts
Material science advances and regulatory pressure are converging to reshape competitive positioning in charcoal bristle toothbrush manufacturing, with sustainability credentials becoming the primary axis of product differentiation.
Bamboo fiber bristle matrices are decentralizing production planning away from petrochemical-dependent supply chains. German retailers now mandate plastic-reduction procurement standards that exclude conventional nylon-6 variants from premium shelf allocations. This shift compresses the addressable market for synthetic-only manufacturers while expanding contract manufacturing capacity for pyrolysis-capable suppliers.
ECHA enforcement of REACH chemical restrictions on European imports is fragmenting registration strategies across member states. Manufacturers must maintain separate binder formulations for EU versus non-EU production lines, raising compliance overhead that favors enterprises with dedicated regulatory affairs infrastructure. The electric replacement-head segment faces the steepest adaptation costs due to multi-component material complexity.
Buyer concentration at dm-drogerie markt and Rossmann chains in Germany is compressing negotiation leverage for independent brands. These retailers now demand biodegradable certification as a condition of premium positioning, displacing conventional plastic-handle SKUs from high-visibility displays. Wellness-focused millennials respond to this curation by accepting price premiums that subsidize supply chain reconfiguration investments.
Charcoal Bristle Toothbrush Market Segmentation
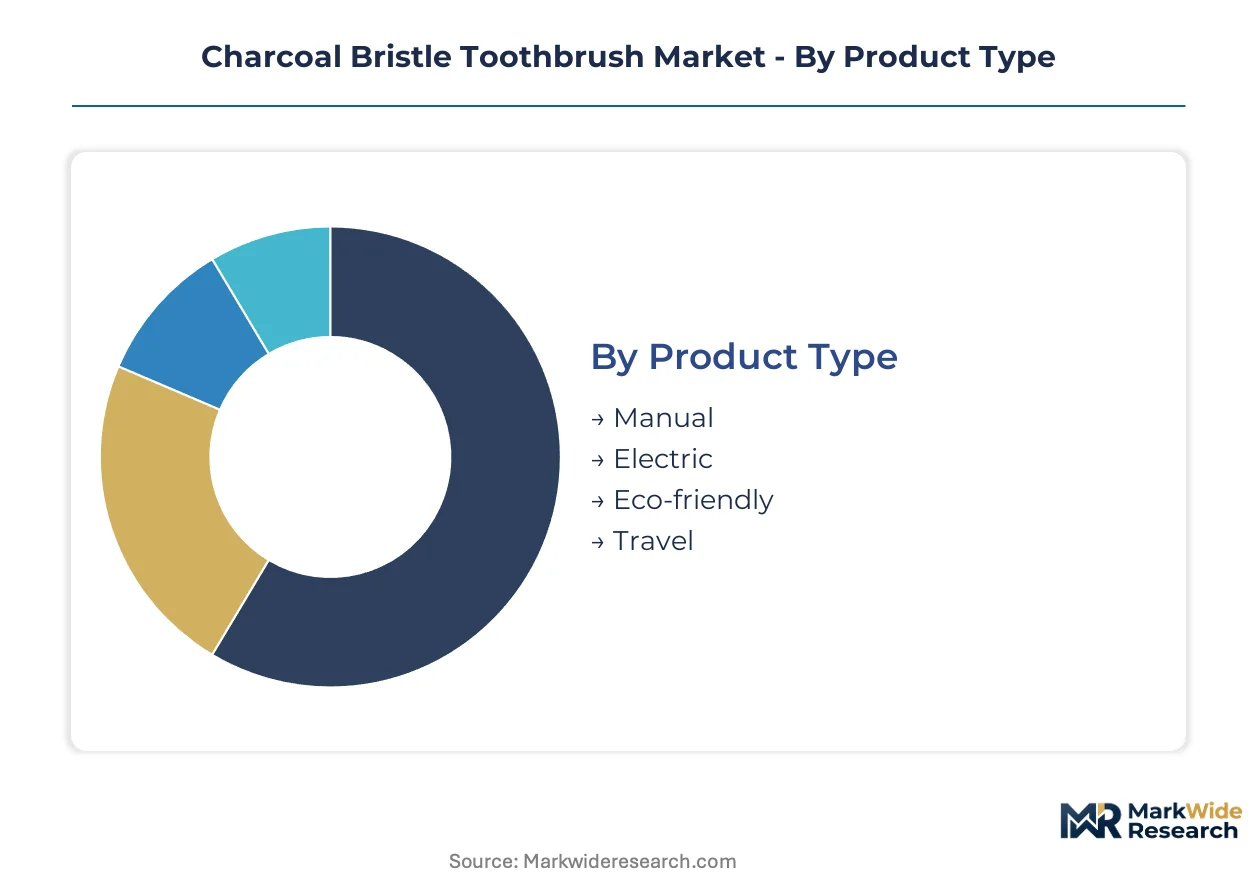
Charcoal bristle toothbrush segmentation reveals divergent upgrade cycles across product architectures. Manual variants drive replacement frequency through low price points, while electric configurations monetize recurring head purchases. Material compliance tiers now determine market access rather than mere positioning.
Product Type:
Replacement-head economics reshape profitability across mechanical configurations, with upgrade cycles varying from weeks to years depending on power integration.
- Manual:Nylon-6 or bamboo-fiber bristle matrices with activated carbon infusion target mass-market accessibility. German dm-drogerie markt and Rossmann chains allocate premium shelf space to these SKUs, though margin compression from petrochemical feedstock volatility constrains smaller manufacturers.
- Electric:Connected toothbrush ecosystems embed charcoal bristle options within replacement-head revenue models. Koninklijke Philips N.V. anchors this segment through smart-platform integration that captures recurring purchases unavailable to manual competitors.
- Eco-friendly:Biodegradable handle materials certified under France's AGEC law and EU Green Deal packaging directives.
- Travel:Compact formats targeting urban professional mobility patterns and subscription-driven direct-to-consumer channels.
Volume placements concentrate in Manual; the faster expansion belongs to Electric.
Customer Type:
Demographic targeting aligns bristle stiffness and handle ergonomics with oral care regimen maturity and retailer procurement standards.
- Adults:Wellness-focused millennials drive SKU expansion through cosmetic whitening and antimicrobial positioning claims. REACH-compliant bristle binders and pyrolysis-derived activated carbon command price premiums in this segment.
- Children:Softer bristle matrices with safety-compliant handle dimensions.
- Seniors:Ergonomic grip designs and gentler charcoal dispersion for sensitive gum tissue.
- Discount Retail:Price-competitive nylon-6 variants without biodegradable certification, constrained by ISO 20126 durability testing overhead.
Adult segments dominate absolute volume; Seniors show the steepest expansion trajectory as aging populations prioritize specialized oral hygiene.
Material:
Raw material sourcing now determines regulatory compliance pathways across jurisdictions with divergent chemical restrictions.
- Bamboo:Pyrolysis at 600–900°C yields activated carbon for bristle infusion while satisfying plastic-reduction procurement mandates. German retailers enforce this standard for premium positioning, decentralizing production from petrochemical supply chains.
- Plastic:Conventional nylon-6 matrices retain impulse-purchase dominance in emerging market supermarkets despite margin pressure from feedstock price volatility.
- Recycled:Post-consumer resin handles meeting EU Green Deal circularity requirements.
- Biodegradable:Multi-jurisdictional certification holders gain first-mover advantage as extended producer responsibility frameworks proliferate.
Plastic retains the largest installed base; Bamboo gains share fastest under retailer sustainability mandates.
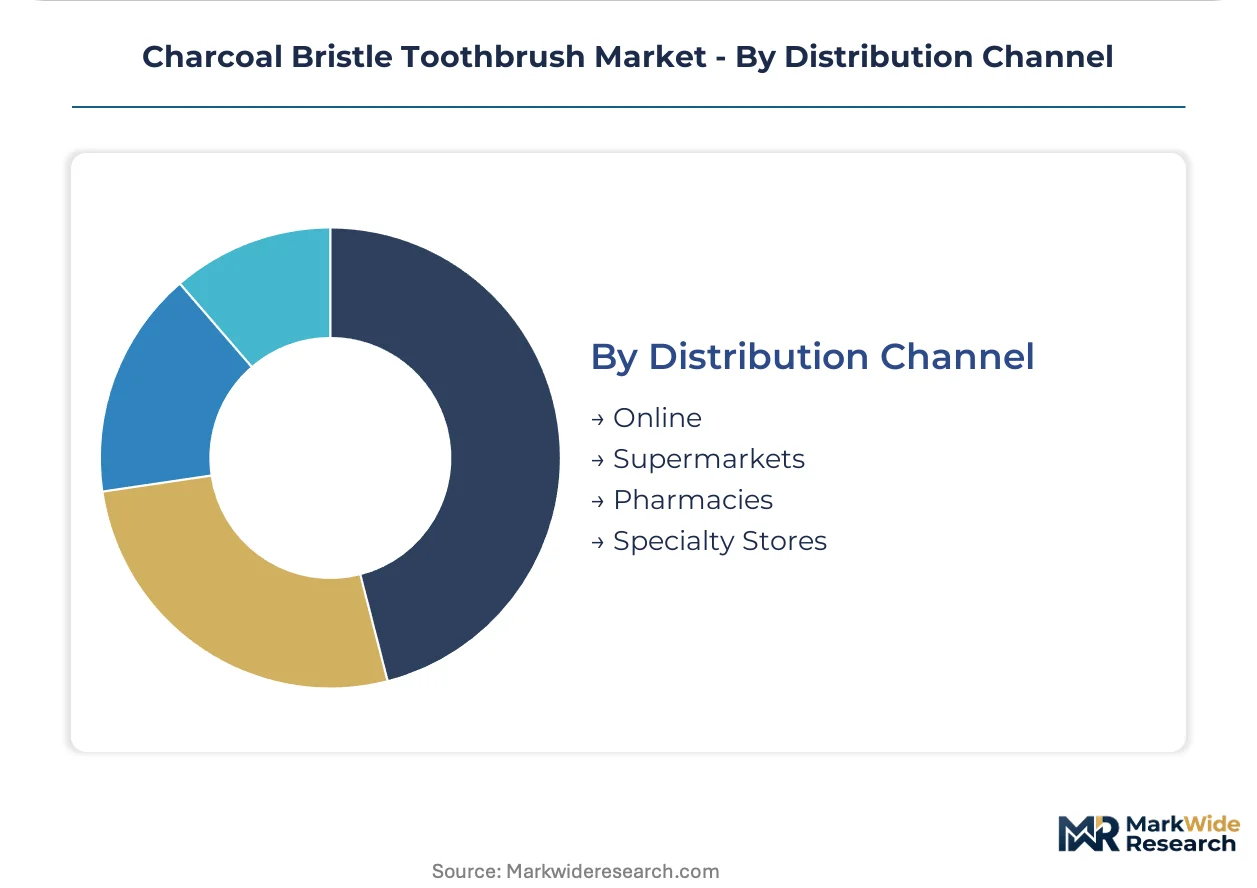
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition economics through divergent slotting fee structures.
- Online:Subscription-driven models bypass supermarket slotting fees while capturing recurring purchase behavior. Direct-to-consumer platforms concentrate urban professional demand with personalized replacement-head scheduling.
- Supermarkets:Impulse-purchase dominance in emerging markets persists for unbranded and conventional SKUs without charcoal positioning.
- Pharmacies:Clinical credibility endorsements for antimicrobial claim substantiation.
- Specialty Stores:Curated wellness retail environments with biodegradable certification requirements.
Supermarkets move the highest unit volumes; Online channels climb the fastest on recurring revenue model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's special economic zone incentives concentrate contract manufacturing capacity for charcoal-infused oral care products serving Asia-Pacific export markets. Regional demand patterns diverge sharply between mature regulatory environments with extended producer responsibility frameworks and emerging markets where conventional nylon-6 variants retain price-driven volume dominance.
United States
Wellness-focused millennials in urban coastal metros drive subscription-driven charcoal toothbrush adoption through direct-to-consumer platforms. FDA bristle safety standards and cosmetic claim substantiation requirements create compliance overhead that favors enterprises with dedicated regulatory infrastructure. Brooklyn and Austin anchor specialty retail curation where biodegradable certification commands shelf placement premiums.
Germany
dm-drogerie markt and Rossmann chains concentrate European demand through premium shelf space allocation for REACH-compliant charcoal dental SKUs. ECHA chemical restrictions on bristle binders force reformulation investments that fragment registration strategies across member states. Hamburg's logistics cluster supports pyrolysis-capable supplier networks serving plastic-reduction procurement mandates.
China
Domestic manufacturing scale advantages position Yangtze River Delta producers as export anchors for activated carbon infusion technologies. NMPA antimicrobial additive thresholds and GB standards impose strict domestic production limits that complicate multinational supply chain planning. Shenzhen's SEZ contract manufacturers serve both branded OEM relationships and private-label supermarket contracts.
Japan
Ergonomic design sophistication and aging-population oral hygiene prioritization create specialized demand for gentle charcoal dispersion variants. METI industrial standards and PMDA cosmetic classification frameworks govern product registration pathways. Osaka-Kobe manufacturing clusters integrate precision bristle-matrix extrusion with traditional personal care brand heritage.
India
Price-sensitive mass-market accessibility constraints limit premium charcoal SKU penetration despite urban professional wellness trend adoption. BIS quality certification requirements and CDSCO cosmetic regulation create multi-layer compliance for imported and domestically manufactured products. Mumbai and Bangalore anchor e-commerce subscription growth bypassing traditional supermarket distribution economics.
Charcoal Bristle Toothbrush Market Competitive Environment
European producers anchor the regulatory-compliant tier; Asian specialists hold manufacturing scale advantages in pyrolysis-derived activated carbon supply. Market structure tilts toward consolidated multinational presence in premium electric replacement-head segments, with fragmented mid-tier competition in manual bamboo variants. Three archetypes dominate: diversified consumer health conglomerates with global regulatory infrastructure, dedicated oral care specialists with sustainability certification depth, and contract manufacturers serving private-label supermarket channels. Competitive moves concentrate on biodegradable material transitions and connected electric ecosystem integration.
Among diversified consumer health conglomerates, Colgate-Palmolive Company and Unilever exemplify archetypes leveraging multi-market registration infrastructure to sustain REACH-compliant product pipelines without SKU fragmentation. Koninklijke Philips N.V. occupies a distinct position embedding charcoal bristle options within replacement-head recurring revenue models. These three anchors represent divergent strategic vectors: chemical compliance scale, sustainability-forward brand architecture, and smart-platform hardware integration.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| Colgate-Palmolive Company |
| Morihata International Ltd |
| Dental Expert |
| Wowe Lifestyle |
| Unilever |
| Koninklijke Philips N.V. |
| Johnson & Johnson Services Inc. |
| Sunstar Group |
| Others |
Value Chain & Pricing Dynamics
Captive pyrolysis operations among German and Chinese manufacturers anchor both supply security and premium pricing power, as in-house activated carbon production insulates margins from coconut shell feedstock volatility while commanding shelf placement premiums at sustainability-focused retailers.
Pricing Analysis
Short lead-time premiums separate subscription-driven replacement-head models from spot-market manual variants, with Philips and Colgate-Palmolive capturing recurring revenue through connected electric ecosystems. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and material compliance, with REACH-compliant bamboo variants commanding the widest spreads. Cost compression in nylon-6 manual tiers is intensifying because petrochemical feedstock hedging demands scale unavailable to mid-tier competitors. Discount retail channels exhibit the highest price sensitivity, while specialty wellness retailers accept premiums for biodegradable certification.
Supply Chain Analysis
EU Green Deal packaging certifications and France's AGEC biodegradability standards gate supplier access to premium European retail channels, fragmenting procurement eligibility across jurisdictions. Pyrolysis capacity concentrates in China, Germany, and Vietnam, with Shenzhen SEZ contract manufacturers and Hamburg logistics clusters serving distinct regulatory zones. Activated carbon feedstocks draw from coconut shell plantations in Indonesia and bamboo forests in China's Fujian province. Single-source vulnerability runs through European machinery suppliers for specialized bristle-matrix extrusion equipment. Distribution runs through dm-drogerie markt and Rossmann chains in Germany for premium positioning, with online subscription platforms capturing urban professional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over pyrolysis-derived activated carbon supply determines margin sustainability and regulatory compliance speed.
For Market Incumbents: Cement multi-jurisdictional registration infrastructure to sustain REACH-compliant product pipelines without SKU fragmentation, while acquiring bamboo pyrolysis capabilities to preempt feedstock cost volatility. The threat of ECHA chemical restriction evolution demands continuous reformulation investment; backward integration into activated carbon production secures supply continuity and pricing power against spot-market dependent competitors. For New Entrants and Emerging Players: Specialty wellness retailers with biodegradable certification mandates represent the most penetrable channel archetype, as dm-drogerie markt and Rossmann chains actively displace conventional plastic-handle SKUs from premium shelf allocations. Target senior oral hygiene segments in Japan and Germany where ergonomic design sophistication commands price premiums unavailable in mass-market tiers. A direct-to-consumer subscription model with personalized replacement-head scheduling bypasses supermarket slotting fees while capturing recurring purchase behavior. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified consumer health conglomerates seeking sustainability-forward brand architecture, with standalone certification depth commanding premium multiples. Long-term viability hinges on pyrolysis capacity scalability and connected electric ecosystem integration over a multi-year horizon. The signal to watch is retailer procurement mandate acceleration, particularly EU Green Deal packaging directive enforcement timelines that compress development windows for biodegradable alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Capacity | In-house activated carbon production insulates margins from coconut shell feedstock volatility at Indonesian suppliers. |
| REACH-Compliant Bristle Binder Reformulation | ECHA chemical restrictions on European imports force reformulation investments that fragment registration strategies across member states. |
| Connected Electric Ecosystem Integration | Replacement-head recurring revenue models within Philips smart platforms capture purchase behavior unavailable to manual competitors. |
| Biodegradable Certification Investment | France's AGEC law and EU Green Deal directives create first-mover advantages for multi-jurisdictional certification holders. |
| Direct-to-Consumer Subscription Launch | Online channels bypass dm-drogerie markt slotting fees while capturing recurring urban professional demand with personalized scheduling. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with brand managers at oral care multinationals, category buyers at German drugstore chains, pyrolysis equipment suppliers in Shenzhen, and regulatory affairs leads navigating REACH compliance. Bottom-up demand modeling triangulated against top-down market sizing from customs export records and retailer procurement database analysis.
Data-stream reconciliation across shipment manifests, retail audit data, and manufacturing capacity disclosures enabled segmentation modeling by product architecture, material compliance tier, and distribution channel across the analysis window. CAGRs derived from replacement frequency differentials between manual and electric configurations, cross-referenced with retailer shelf space allocation trends and subscription platform growth trajectories. Forecast inputs incorporated ISO 20126 durability testing adoption rates and biodegradability certification timeline assumptions.
Caveats apply where ECHA enforcement intensity or EU Green Deal packaging directive acceleration could materially shift the outlook for synthetic bristle matrix viability. Forecasts reflect assumptions regarding retailer procurement mandate timelines and pyrolysis capacity expansion rates. A model refresh is warranted upon material change in biodegradability certification approval velocities or connected electric toothbrush platform adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Disposable Shower Caps Market
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Electric Foot Callus Remover Market
Personal Grooming Products
Global Massage Guns Market
Personal Grooming Products
Gel Socks Market
Personal Grooming Products
Shoe Insert Market
Personal Grooming Products
Global Mobile Barber Shop Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
Global Aligner Sheet Market
Personal Grooming Products
Antibacterial Soap Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market
Personal Grooming Products
Electrical Neck Warmer Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
Shaving Market