
 Multi-Touch Attribution Market | 2026-2036
Multi-Touch Attribution Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Touch Attribution Market Foresight
Buyer concentration across enterprise e-commerce and retail media networks is rebalancing as mid-market direct-to-consumer brands fragment into thousands of new platform users. Triple Whale leverages product specialization for Shopify-native merchants. Northbeam anchors technology leadership in incrementality measurement for paid social channels. Dreamdata sustains R&D intensity around B2B revenue attribution pipelines.
Multi-touch attribution assigns fractional credit across multiple customer touchpoints using probabilistic models, deterministic matching, or algorithmic weighting against conversion paths; its primary commercial purpose is to replace last-click bias with distributed signal clarity for media mix optimization. Data-driven attribution competes for margin pools among enterprises with sufficient conversion volume to train statistical models, while cloud-based deployment leads adoption velocity by eliminating infrastructure latency for real-time pipeline ingestion. Rule-based attribution occupies a mature position among smaller advertisers prioritizing transparent, auditable logic over black-box sophistication.
GDPR in Europe, state privacy statutes in the United States, and emerging sector-specific guidance from the FTC collectively constrain cross-site tracking and probabilistic identifier usage, which elevates demand for first-party data infrastructure and consent-aware measurement architecture. ISO standards around data quality management provide additional compliance scaffolding for attribution vendors serving regulated finance and healthcare-adjacent clients. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized or federated attribution infrastructure delivers durable competitive advantage.
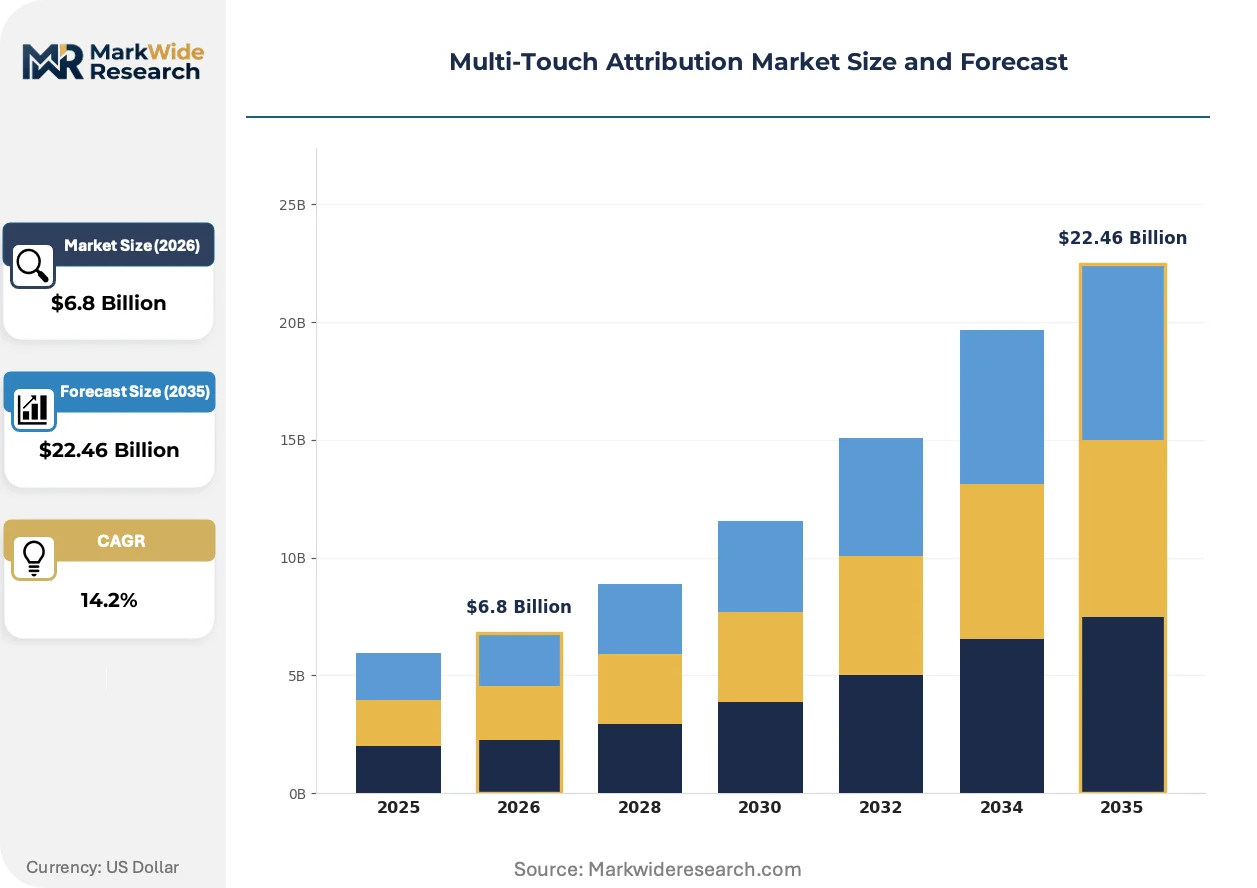
Market Dynamics
Privacy regulations and the deprecation of third-party cookies are forcing attribution vendors to rebuild measurement infrastructure around first-party data graphs and probabilistic modeling techniques that do not rely on persistent cross-site identifiers.
Growth Catalysts
- Retail media networks:E-commerce platforms are deploying proprietary attribution tools to capture closed-loop measurement budgets from consumer packaged goods advertisers seeking granular path-to-purchase visibility.
- GDPR enforcement:Consent-aware measurement architecture is elevating demand for server-side tracking and clean room implementations that preserve analytical utility while satisfying European data protection requirements.
- Algorithmic weighting:Machine learning-based attribution models are penetrating mid-market advertiser segments previously priced out of data-driven measurement capabilities.
Market Restraints
- Identifier fragmentation:Apple's App Tracking Transparency framework and Google's Privacy Sandbox are fragmenting addressable audiences across iOS and Android ecosystems, degrading cross-platform path reconstruction accuracy.
- Implementation cost concentration:Enterprise-grade attribution deployments require substantial data engineering resources, concentrating advanced capabilities among advertisers with dedicated marketing technology operations.
- Probabilistic matching degradation:Browser-level privacy protections are eroding fingerprinting techniques that attribution platforms rely on for device graph construction in cookie-constrained environments.
Strategic Opportunities
- B2B revenue attribution:Long sales cycle enterprises are adopting account-based measurement pipelines that connect marketing touchpoints to CRM opportunity stages and closed-won revenue.
- Clean room infrastructure:Privacy-enhancing computation environments are enabling advertiser-publisher data collaboration without raw data sharing, opening new partnership models for walled garden measurement.
- CTV attribution standardization:Connected television platforms are developing impression-to-outcome measurement protocols that bridge linear and digital video investment planning.
Industry Challenges
- Data engineering talent scarcity:Attribution platform vendors face acute competition for machine learning engineers capable of building privacy-preserving identity resolution systems at scale.
- Legacy system integration friction:Enterprise marketing stacks built on last-click measurement require substantial reconfiguration to ingest multi-touch signals into existing BI and planning workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Touch Attribution Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
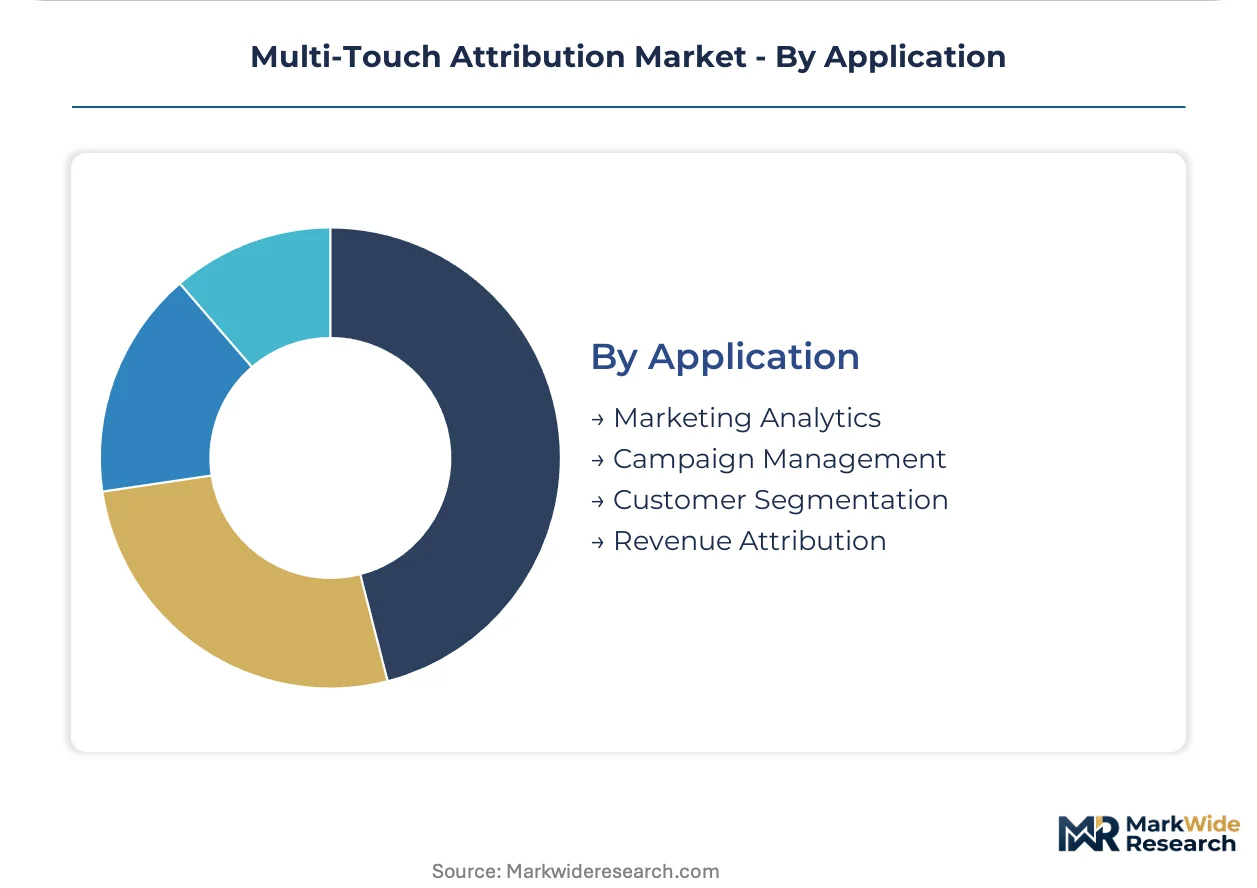
| Segmentation | Technology: Data-Driven Attribution, Rule-Based Attribution, Algorithmic Attribution, Single-Touch Attribution End User: E-Commerce, Retail, Media, Finance Deployment: Cloud-Based, On-Premises, Hybrid Solution, Managed Services Application: Marketing Analytics, Campaign Management, Customer Segmentation, Revenue Attribution |
| Companies Covered | Dreamdata, Northbeam, SegmentStream, Polar Analytics, Triple Whale, HockeyStack, Ruler Analytics, AdBeacon, Rockerbox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Touch Attribution Market Shifts & Advancements
Measurement methodology is pivoting from deterministic identity matching toward privacy-preserving probabilistic techniques that infer attribution relationships without persistent user-level tracking.
Server-side tracking infrastructure is converging with consent management platforms to enable real-time data routing decisions based on jurisdiction-specific privacy preferences. Mid-market direct-to-consumer brands are adopting these combined stacks fastest as they lack resources to maintain separate compliance and measurement engineering teams. This convergence is compressing vendor selection cycles as buyers prioritize unified solutions over best-of-breed point products.
The FTC's emerging sector-specific guidance on dark patterns and deceptive data practices is tightening disclosure requirements for consumer-facing tracking consent flows. Attribution vendors must now engineer user interface components that satisfy both conversion optimization goals and regulatory transparency standards. Healthcare-adjacent and financial services advertisers in the United States are most affected, accelerating procurement of ISO-certified measurement infrastructure.
Buyer concentration among enterprise e-commerce platforms is fragmenting as direct-to-consumer brands disperse spending across specialized attribution tools rather than consolidating on incumbent marketing clouds. Self-serve onboarding and transparent pricing models are displacing traditional sales-led enterprise procurement for platforms serving sub-$50 million revenue advertisers. This shift is most visible in North American and Western European markets where Shopify-native merchants represent the fastest-growing attribution software customer segment.
Multi-Touch Attribution Market Segmentation
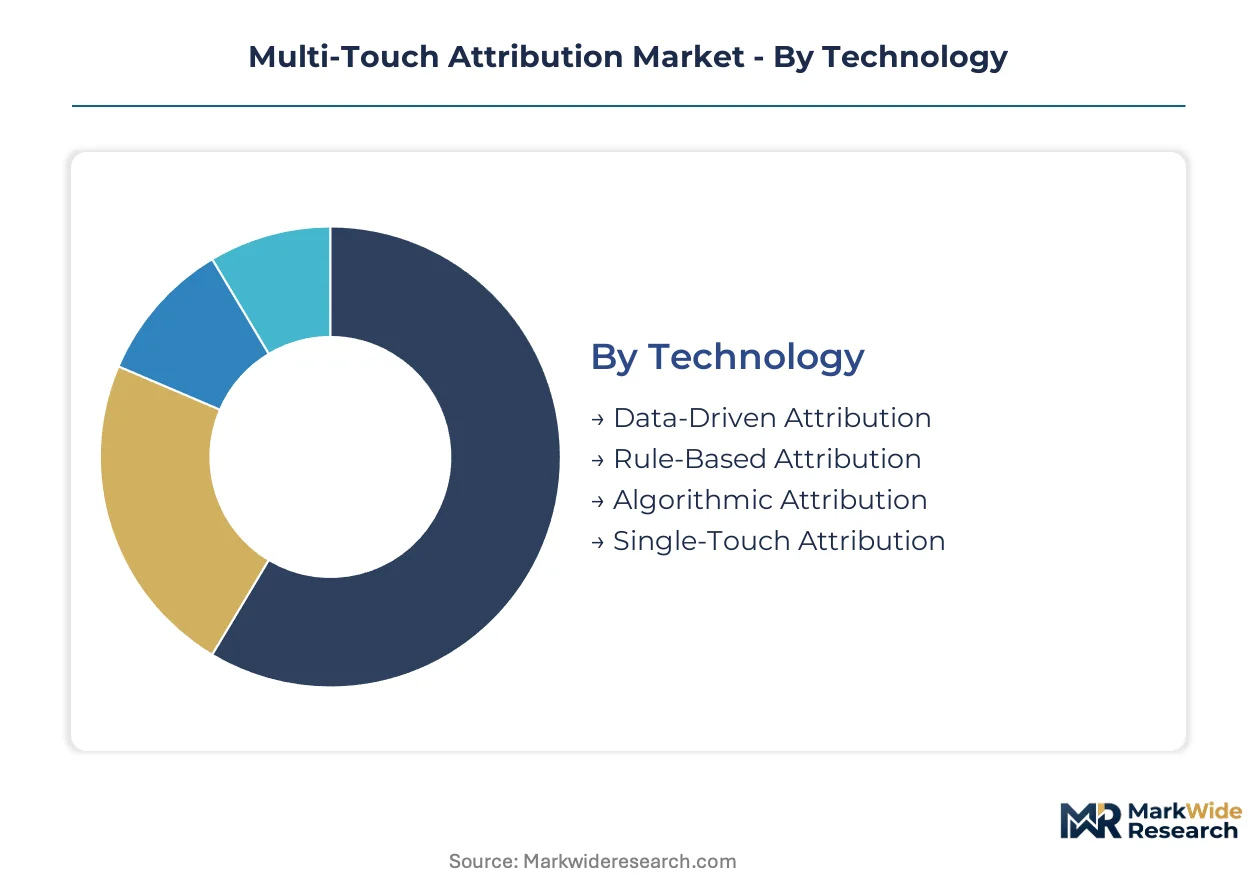
Segmentation in multi-touch attribution reveals how buyer sophistication, data maturity, and regulatory exposure determine technology selection. Understanding these divides enables vendors to align product roadmaps with distinct implementation capabilities and compliance requirements across customer tiers.
Technology:
Buyers in this category separate by statistical sophistication and conversion volume thresholds available for model training.
- Data-Driven Attribution:Machine learning models ingest conversion path data to calculate dynamic credit allocation based on actual observed patterns. Enterprise advertisers in the United States with high transaction volumes deploy these systems to replace heuristic assumptions with statistical inference, though implementation demands dedicated data science resources.
- Algorithmic Attribution:Proprietary weighting engines apply vendor-specific logic to distribute credit across touchpoints without requiring client-side model training. Mid-market direct-to-consumer brands in Western Europe adopt these solutions fastest as GDPR constraints elevate demand for consent-aware measurement without internal ML engineering.
- Rule-Based Attribution:Predefined logic such as linear, time-decay, or position-based models offer transparent, auditable credit distribution.
- Single-Touch Attribution:Last-click or first-click models persist among smaller advertisers prioritizing implementation simplicity over path complexity.
Volume sits with Rule-Based Attribution; growth tilts toward Algorithmic Attribution.
End User:
Vertical selection tracks privacy sensitivity, sales cycle length, and media mix complexity rather than company size alone.
- E-Commerce:High-velocity transaction environments generate rich path-to-purchase data ideal for multi-touch modeling. Shopify-native merchants across North America and Western Europe represent the fastest-expanding customer segment as self-serve platforms democratize access previously restricted to enterprise marketing clouds.
- Finance:Regulated institutions face heightened scrutiny from the FTC and state-level privacy statutes, elevating demand for ISO-certified measurement infrastructure with audit trails. Banks and insurers in the United States prioritize server-side tracking architectures that satisfy compliance without sacrificing analytical utility.
- Retail:Brick-and-click operators blend online attribution with offline outcome validation through loyalty program linkage.
- Media:Publishers and broadcasters seek impression-to-outcome measurement for inventory pricing and advertiser reporting.
Deployment concentration favors E-Commerce; steepest expansion trajectory belongs to Finance.
Deployment:
Infrastructure choices reflect data sovereignty requirements, latency tolerance, and engineering resource availability.
- Cloud-Based:SaaS delivery eliminates infrastructure latency for real-time pipeline ingestion and scales elastically with conversion volume. This mode captures the majority of new platform adoption as mid-market buyers prioritize speed-to-insight over customization depth.
- Hybrid Solution:Split architectures process sensitive identity data on-premises while pushing aggregated analytics to cloud environments. German and French enterprises under GDPR and national implementation laws favor this approach to maintain data residency without sacrificing computational scale.
- On-Premises:Fully captive infrastructure serves defense contractors and government-adjacent entities with air-gapped security requirements.
- Managed Services:Vendor-operated deployments address talent scarcity by outsourcing data engineering and model maintenance.
Adoption clusters in Cloud-Based; Hybrid Solution gains share fastest among regulated verticals.
Application:
Use case prioritization correlates with organizational maturity in connecting marketing signals to business outcomes.
- Revenue Attribution:Closed-loop measurement connects marketing touchpoints to CRM opportunity stages and booked revenue, essential for B2B enterprises with extended sales cycles. Long-cycle technology vendors in the United States invest heavily here to defend media mix decisions against finance department scrutiny.
- Marketing Analytics:Exploratory path analysis and cohort behavior modeling support strategic planning without immediate operational integration. This application dominates initial platform adoption as teams build data literacy before advancing to automated optimization.
- Campaign Management:Real-time budget reallocation based on attributed performance requires API connectivity to media buying platforms.
- Customer Segmentation:Attribution-informed audience building enables lookalike expansion and retention targeting.
Investment intensity concentrates in Revenue Attribution; platform entry most commonly begins with Marketing Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where enterprise marketing technology spending and retail media network expansion create the most substantial near-term opportunity. European markets follow under GDPR compliance pressure. Asia-Pacific adoption accelerates through e-commerce platform growth.
United States
Enterprise advertisers in the United States deploy data-driven attribution models to defend media mix decisions against finance department scrutiny. The FTC's emerging sector-specific guidance on dark patterns tightens disclosure requirements for consumer-facing tracking consent flows. Technology vendors cluster in San Francisco and New York, where marketing technology operations concentrate.
Germany
German enterprises under GDPR and national implementation laws favor hybrid deployment architectures to maintain data residency without sacrificing computational scale. The country's national data protection regulator enforces consent-aware measurement architecture with particular rigor. Frankfurt and Munich host the densest concentration of attribution engineering talent serving regulated finance and industrial clients.
United Kingdom
UK-based direct-to-consumer brands adopt self-serve attribution platforms fastest as Shopify-native merchants represent the fastest-growing customer segment. The Information Commissioner's Office enforces transparency standards for consumer-facing tracking consent flows. London anchors technology development for B2B revenue attribution pipelines serving long sales cycle enterprises.
France
French enterprises prioritize server-side tracking architectures that satisfy CNIL requirements without sacrificing analytical utility. National implementation laws of GDPR elevate demand for clean room implementations that preserve measurement utility while satisfying data protection requirements. Paris hosts specialized vendors serving luxury and fashion advertisers with complex path-to-purchase visibility requirements.
Japan
Japanese advertisers adopt algorithmic attribution solutions as machine learning-based models penetrate mid-market segments previously priced out of data-driven measurement. METI guidance shapes privacy-preserving computation standards for advertiser-publisher data collaboration. Tokyo concentrates vendor development for CTV attribution protocols bridging linear and digital video investment planning.
Multi-Touch Attribution Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue product specialization for platform-native merchants. The vendor base separates into three maturity tiers: incumbent marketing clouds with bundled attribution modules, independent platforms with vertical specialization, and self-serve tools democratizing access for sub-$50 million revenue advertisers. Dominant competitive moves include strategic partnerships with e-commerce platforms and portfolio diversification into clean room infrastructure.
Within the independent platform tier, Dreamdata and Northbeam exemplify divergent specialization strategies. Dreamdata occupies a position among B2B revenue attribution specialists, while Northbeam anchors technology leadership in incrementality measurement for paid social channels. Triple Whale represents the self-serve platform archetype targeting Shopify-native merchants with transparent pricing models displacing traditional sales-led procurement.
| Leading Market Players |
|---|
| Dreamdata |
| Northbeam |
| SegmentStream |
| Polar Analytics |
| Triple Whale |
| HockeyStack |
| Ruler Analytics |
| AdBeacon |
| Rockerbox |
| Others |
Supply & Pricing Matrix
Data engineering labor costs cascade through attribution platform pricing tiers, with San Francisco and New York talent premiums compressing margins for cloud-native vendors while elevating subscription rates for enterprise deployments requiring dedicated ML engineering resources.
Pricing Analysis
Volume concentrates in self-serve algorithmic tiers targeting sub-fifty-million-revenue advertisers, while margin pools accrue to data-driven enterprise implementations demanding client-side model training. Price differentiation hinges on ISO certification status and server-side tracking architecture depth. Pricing pressure stems from mid-market fragmentation as transparent SaaS models displace sales-led procurement. Shopify-native merchants exhibit highest price sensitivity; regulated finance and healthcare-adjacent buyers demonstrate lowest elasticity due to compliance-driven procurement mandates.
Supply Chain Analysis
ISO certification and GDPR consent-architecture compliance gate vendor qualification for regulated verticals, elevating engineering talent scarcity into a structural supply constraint. Engineering talent concentrates in the United States, Germany, and the United Kingdom. Platform infrastructure draws from cloud hyperscaler compute, first-party data graph tooling, and consent management platform integrations. Single-source vulnerability sits with Apple-Google identifier fragmentation degrading cross-platform path reconstruction. Distribution runs through direct self-serve onboarding for mid-market segments and consultative enterprise sales for regulated institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
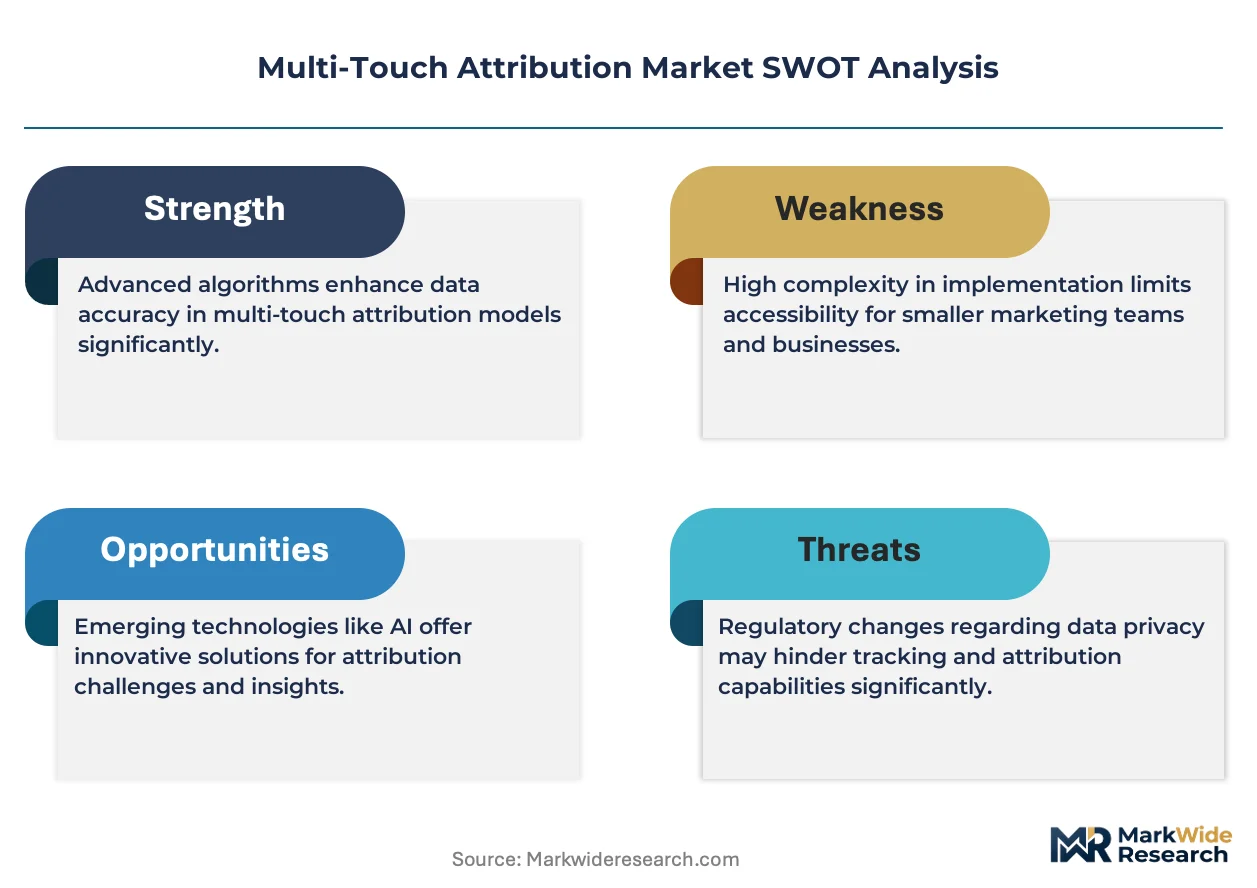
GDPR enforcement and state-level privacy statutes in the United States have transformed compliance infrastructure into a durable barrier-to-entry moat, advantaging vendors with pre-built consent-aware measurement architecture over point-solution entrants lacking regulatory scaffolding.
For Market Incumbents: Acquire clean room infrastructure capabilities to defend against emerging privacy-enhancing computation specialists. Consolidate server-side tracking talent pools in Frankfurt and Munich to preempt German data residency requirements. Channel control through Shopify partnership exclusivity represents the critical defensive lever against self-serve platform fragmentation.
For New Entrants and Emerging Players: Mid-market B2B revenue attribution pipelines in the United Kingdom present the most penetrable white-space target, with long sales cycle technology vendors underserved by incumbent marketing clouds. France's luxury and fashion advertiser segment offers secondary entry velocity given complex path-to-purchase visibility requirements. A vertical-specialist go-to-market positioning around CRM-integrated opportunity stage tracking outperforms horizontal platform competition.
For Investors and Strategic Acquirers: Distressed-cycle entries favor algorithmic attribution specialists with pre-trained consent-aware models in Western European markets facing acute GDPR enforcement escalation. Long-term viability across the analysis window hinges on first-party data graph infrastructure ownership rather than probabilistic matching dependencies. The signal to watch is FTC sector-specific guidance expansion beyond healthcare and finance into adjacent regulated verticals.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean Room Infrastructure Acquisition | Enables walled garden measurement partnerships without raw data sharing under GDPR constraints. |
| Server-Side Tracking Platform Integration | Consolidates consent management and measurement routing for real-time privacy compliance. |
| B2B Revenue Attribution Pipeline Development | Connects marketing touchpoints to CRM opportunity stages for long-cycle enterprise defense. |
| ISO Certification Investment | Qualifies vendors for regulated finance and healthcare-adjacent procurement in the United States. |
| Shopify-Native Self-Serve Expansion | Captures fastest-growing North American and Western European direct-to-consumer merchant segment. |
Research Methodology
Independent corroboration across attribution platform engineering leads, enterprise marketing technology procurement officers, and privacy compliance directors underwrites the qualitative findings in this study. Primary interviews with CTOs at mid-market direct-to-consumer brands, data protection officers at German financial institutions, and integration specialists at Shopify app ecosystem partners combined with secondary validation from SEC filings of marketing technology vendors, GDPR enforcement action databases maintained by European data protection authorities, and cloud hyperscaler partnership disclosure announcements. Bottom-up platform adoption estimates and top-down enterprise marketing technology spending benchmarks were triangulated to establish segmentation splits.
Rate-of-change decomposition across deployment models, end-user verticals, and technology sophistication tiers anchored the forecast framework. Segmentation dimensions modeled include statistical methodology tier, organizational revenue scale, regulatory exposure cluster, and regional adoption pattern. CAGRs were derived from elasticity-adjusted spending trajectories calibrated against historical platform penetration curves. Industry-specific forecast inputs incorporated retail media network budget expansion rates and B2B sales cycle length compression indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Apple-Google identifier policy divergence and FTC enforcement intensity escalation. Model outputs reflect assumptions around consent architecture adoption velocity and cloud infrastructure cost curves. A model refresh is warranted upon material change in Privacy Sandbox implementation timelines or sector-specific FTC guidance issuance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Brazil Geospatial Analytics Market
Analytics
Data Analytics in Telecom Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Europe Emotion Analytics Market
Analytics
North America Mobile Analytics Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
App Analytics Tools Market
Analytics
Social Business Intelligence Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Global AI Video Analytics Market
Analytics
Content Intelligence Market
Analytics
Customer Identity Graph Drift Monitoring Market
Analytics
Global User and Entity Behavior Analytics Market
Analytics
SME Big Data Market
Analytics
Global Telco Data Monetization Market
Analytics
United Kingdom Business Intelligence Market