
 North America Mobile Analytics Market | 2026-2036
North America Mobile Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mobile Analytics Market Insights
Enterprise software distribution is narrowing as platform vendors consolidate indirect sales through cloud marketplaces. Adobe Inc. leverages its creative cloud install base to cross-sell analytics modules. Microsoft anchors enterprise accounts through Azure-embedded mobile intelligence tools. Alphabet Inc. competes on real-time attribution depth across its advertising ecosystem.
North America mobile analytics encompasses software systems that capture, process, and visualize behavioral telemetry from iOS and Android endpoints using SDK instrumentation with event throughput exceeding 50,000 events per second. These systems enable retail, finance, and healthcare organizations to optimize user journeys, reduce churn, and personalize engagement at scale. Cloud deployment now leads the deployment category as latency-sensitive workloads migrate from on-premises data centers. Predictive analytics within the solution category is expanding fastest among large enterprises seeking anticipatory rather than retrospective intelligence. Reporting tools remain the mature margin pool where incumbent vendors extract recurring revenue from risk-averse buyers.
The FCC and state-level attorneys general in California and New York are enforcing stricter mobile data collection disclosures, compelling SDK providers to implement granular opt-in flows. HIPAA boundaries for healthcare apps and CCPA/CPRA compliance costs are reshaping vendor R&D priorities toward privacy-preserving architectures. Stakeholders must weigh consent friction against measurement fidelity when configuring event capture strategies.
Market Dynamics
The FCC's evolving data privacy frameworks are pressuring mobile analytics vendors to retool consent architectures, creating a structural pivot toward privacy-preserving telemetry collection across retail, finance, and healthcare deployments.
Growth Catalysts
- CPRA Compliance Investment:California's attorney general enforcement of granular opt-in flows is forcing retailers to upgrade analytics stacks, expanding vendor addressable spend across the San Francisco Bay Area tech cluster.
- Cloud Latency Migration:Finance and healthcare organizations are shifting latency-sensitive workloads from on-premises data centers to cloud deployments, accelerating SDK instrumentation refresh cycles.
- Predictive Analytics Demand:Large enterprises in the United States are prioritizing anticipatory intelligence over retrospective reporting, pulling predictive module adoption ahead of replacement timelines.
Market Restraints
- Consent Friction Costs:HIPAA boundaries for healthcare apps and CCPA/CPRA compliance requirements are inflating vendor R&D spend on privacy-preserving architectures without immediate revenue offset.
- SDK Provider Concentration:Telemetry capture infrastructure depends on a narrow base of specialized SDK vendors, creating single-point-of-failure risk in event pipeline reliability.
- Event Throughput Limitations:Real-time processing above 50,000 events per second demands specialized infrastructure that mid-market buyers cannot self-provision, capping addressable segments.
Strategic Opportunities
- Underpenetrated Healthcare Vertical:HIPAA-compliant mobile analytics remains nascent in United States patient engagement apps, creating first-mover advantage for privacy-certified entrants.
- Azure-Embedded Distribution:Cloud marketplace consolidation enables analytics modules to ride Microsoft enterprise account expansion without direct sales investment.
- Cross-Platform Attribution Convergence:iOS and Android telemetry unification with web analytics is collapsing measurement silos for retailers running omnichannel conversion optimization.
Industry Challenges
- Specialized Talent Scarcity:Privacy engineering and real-time event pipeline architecture expertise concentrates in California's San Francisco Bay Area, inflating compensation costs for distributed vendors.
- Legacy System Integration:Mainframe-era data warehouses in United States financial institutions resist API-native telemetry ingestion, extending implementation timelines and eroding project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mobile Analytics Market |
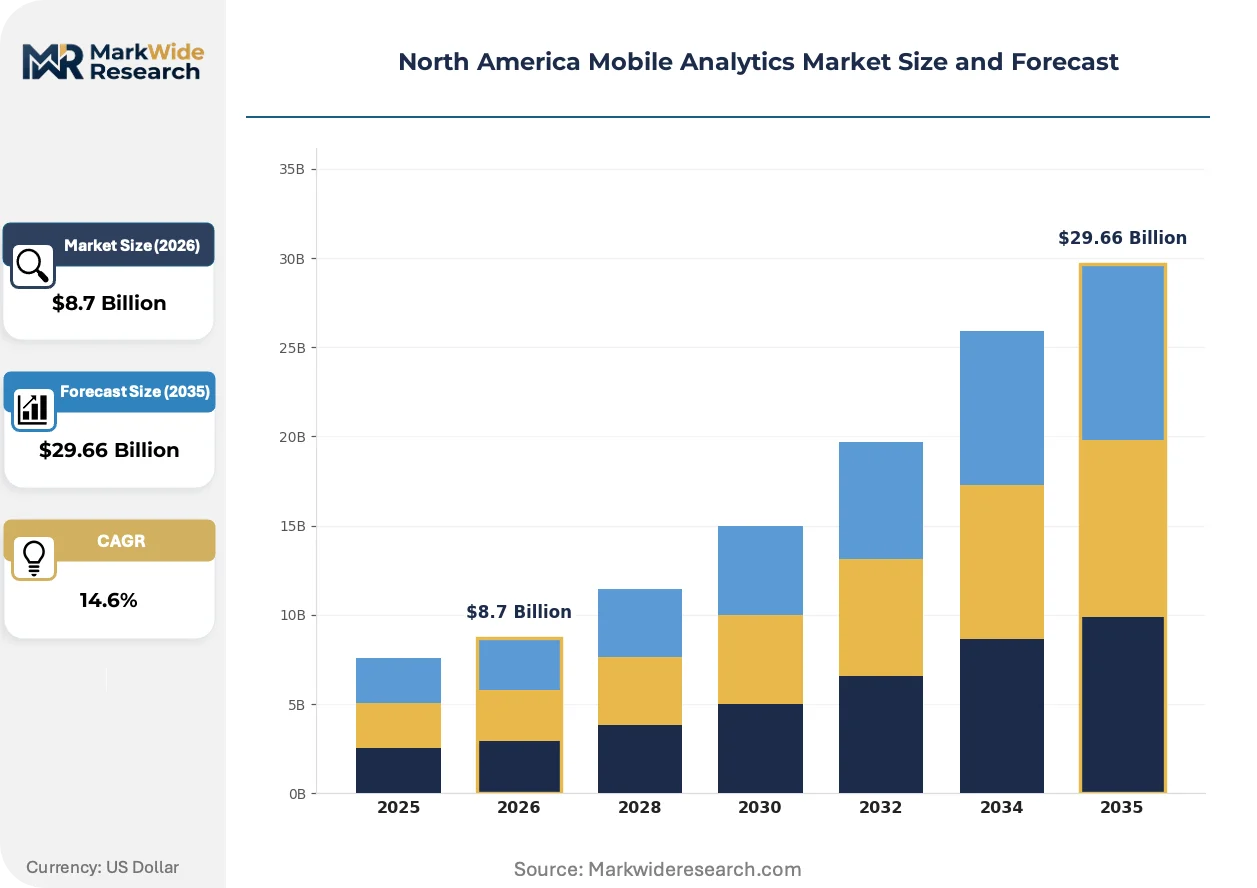
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, SaaS Application: Retail, Healthcare, Finance, Travel End User: Small Enterprises, Medium Enterprises, Large Enterprises, Startups Solution: Data Visualization, Predictive Analytics, Reporting Tools, Performance Metrics |
| Companies Covered | AppsFlyer Ltd., Mixpanel, Adobe Inc., Oracle, Microsoft, Alphabet Inc., Branch Metrics, Inc., Salesforce, Amplitude, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mobile Analytics Market Trends and Innovations
Telemetry processing architectures are undergoing fundamental compression as batch-oriented systems give way to stream-native pipelines, reshaping vendor R&D priorities and buyer procurement criteria across North America.
Stream-native event processing is collapsing the latency gap between data capture and actionable insight. Retailers in the United States are adopting sub-second funnel visualization to intercept cart abandonment in real time. This compression is eliminating the competitive advantage previously held by vendors with overnight batch reporting capabilities.
California's attorney general enforcement of CCPA/CPRA is mandating granular opt-in flows before SDK initialization. Healthcare app publishers face overlapping HIPAA disclosure requirements that extend consent collection into clinical workflow contexts. Vendors serving United States healthcare verticals are responding with modular consent architectures that segment telemetry capture by data sensitivity tier.
Buyer procurement of mobile analytics is consolidating through cloud marketplace channels rather than direct vendor negotiation. Enterprise software distribution is narrowing as platform vendors capture indirect sales volume. This channel shift is most visible in Azure-embedded deployments across Microsoft-anchored enterprise accounts in the United States, where procurement teams prefer consolidated billing over point-solution contracting.
North America Mobile Analytics Market Segmentation
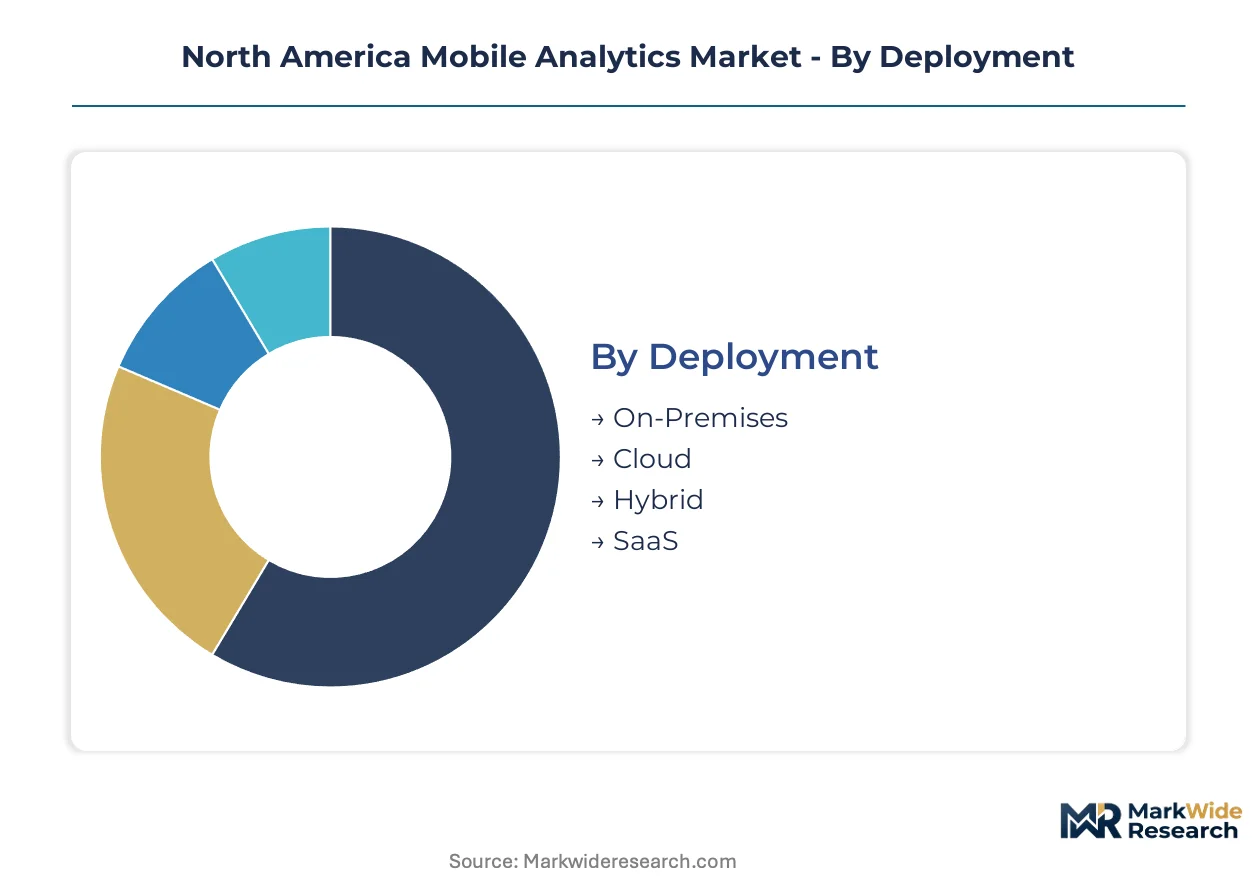
Segmentation in North America mobile analytics reveals divergent procurement rhythms across deployment modes, vertical applications, and enterprise scale tiers. Understanding these cycle-time differentials enables vendors to align sales capacity with replacement windows and expansion triggers.
Deployment:
Cloud deployments refresh on 18-24 month cycles as vendors push continuous feature releases, while on-premises installations persist across 5-7 year amortization schedules.
- Cloud:Fully managed infrastructure with auto-scaling event pipelines eliminates capital expenditure for telemetry ingestion. Demand concentrates among California's San Francisco Bay Area retailers optimizing in-app conversion funnels through sub-second funnel visualization.
- SaaS:Pre-configured analytics modules with standardized SDK instrumentation reduce implementation timelines from months to weeks. United States healthcare organizations favor this model to minimize HIPAA compliance engineering overhead.
- On-Premises:Dedicated hardware clusters within buyer data centers retain full data sovereignty. Legacy financial institutions in the United States maintain these deployments to satisfy internal audit requirements.
- Hybrid:Split architectures process sensitive events locally while pushing anonymized aggregates to cloud visualization layers. This configuration addresses CCPA/CPRA data residency concerns without sacrificing computational elasticity.
On-Premises dominates installed base. Cloud is where expansion concentrates.
Application:
Retail applications command the highest per-seat pricing due to real-time attribution requirements, while healthcare deployments carry the longest sales cycles due to privacy certification hurdles.
- Retail:Cart abandonment interception and personalized push orchestration drive SDK instrumentation density. United States merchants running omnichannel operations demand unified iOS and Android telemetry with web analytics convergence.
- Healthcare:Patient engagement apps require HIPAA-compliant event capture with clinical workflow-embedded consent flows. California's attorney general enforcement of granular opt-in mandates is reshaping vendor R&D priorities toward modular consent architectures.
- Finance:Real-time fraud detection and transaction pattern analysis push event throughput requirements above 50,000 events per second. Mainframe-era data warehouses in United States institutions resist API-native ingestion, extending implementation timelines.
- Travel:Booking funnel optimization and loyalty program personalization rely on cross-platform attribution. Mid-market buyers in this vertical lack infrastructure to self-provision specialized real-time processing capabilities.
Retail captures the margin premium. Healthcare is climbing the fastest as privacy-certified entrants establish first-mover positions.
End User:
Large enterprises consolidate vendor relationships through multi-year master service agreements, while startups represent high-churn, price-sensitive demand with minimal switching costs.
- Large Enterprises:Centralized procurement teams prioritize predictive analytics modules over retrospective reporting. Microsoft-anchored accounts prefer Azure-embedded tools to consolidate billing and reduce vendor management overhead.
- Medium Enterprises:Growing event volumes strain self-managed infrastructure, creating migration pressure toward cloud deployments. Finance and healthcare organizations in this tier face the steepest compliance cost inflation.
- Small Enterprises:Limited technical staffing drives preference for fully managed SaaS with pre-built dashboards. California's San Francisco Bay Area tech cluster contains disproportionate concentration of venture-backed startups in this segment.
- Startups:Minimal data engineering resources rely on free-tier SDKs with volume-limited event ingestion. High failure rates produce unpredictable revenue continuity for analytics vendors.
Large Enterprises dominate vendor revenue concentration. Startups is where platform vendors seed future expansion through freemium conversion funnels.
Solution:
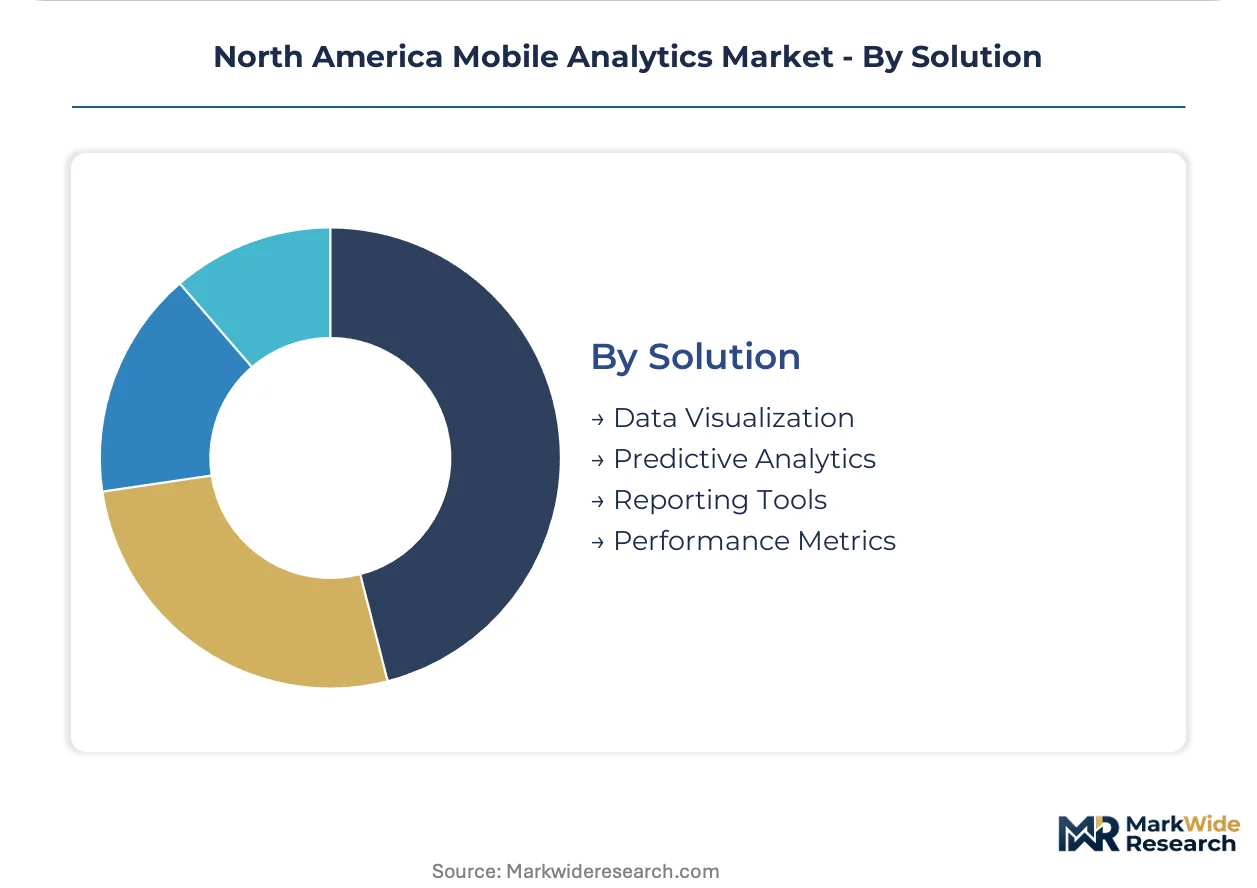
Reporting tools extract recurring revenue from risk-averse buyers with minimal feature churn, while predictive analytics modules command implementation fees and ongoing consulting engagement.
- Predictive Analytics:Machine learning models anticipate churn and conversion propensity before behavioral signals manifest. Large enterprises in the United States prioritize this anticipatory intelligence over retrospective dashboards.
- Reporting Tools:Standardized dashboards with scheduled distribution satisfy compliance and executive review requirements. Mature margin pool where incumbent vendors defend position through entrenched workflow integration.
- Data Visualization:Interactive exploration interfaces enable ad-hoc analysis without SQL expertise. Retail analysts leverage these tools to identify micro-segment behavioral anomalies.
- Performance Metrics:Pre-defined KPI tracking for app store optimization and user acquisition cost monitoring. Mobile game publishers and e-commerce operators depend on these benchmarks for campaign pacing decisions.
Reporting Tools dominates recurring revenue stability. Predictive Analytics is gaining share fastest as enterprises reallocate budget from descriptive to anticipatory intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CPRA enforcement and FCC data privacy frameworks are accelerating vendor investment in consent architectures across North American jurisdictions. Retailers and healthcare organizations face divergent compliance cost structures depending on state-level regulatory intensity. The analysis examines three national markets where deployment patterns reflect distinct policy environments and industrial clustering.
United States
Retailers operating omnichannel conversion funnels drive the highest per-seat pricing for real-time attribution modules. FCC disclosure mandates and California's attorney general enforcement of granular opt-in flows compel SDK providers to retool consent architectures. The San Francisco Bay Area tech cluster concentrates predictive analytics demand among venture-backed startups and large enterprises migrating latency-sensitive workloads to cloud deployments.
Canada
Healthcare app publishers prioritize HIPAA-compliant event capture architectures to serve cross-border patient engagement use cases. Health Canada and the Office of the Privacy Commissioner coordinate enforcement of mobile data collection disclosures that parallel FCC frameworks. Toronto's financial services corridor anchors demand for real-time fraud detection exceeding 50,000 events per second among banking institutions.
Mexico
Mid-market retailers adopt SaaS analytics modules to minimize implementation timelines and technical staffing requirements. The country's national data protection authority enforces consent collection standards that lag California's CPRA stringency, reducing compliance engineering overhead. Mexico City Metro concentrates fintech and e-commerce operators seeking cart abandonment interception capabilities without self-provisioned infrastructure investment.
North America Mobile Analytics Market Competitive Landscape
On the supply side, the industry is consolidating around platform vendors capturing indirect sales through cloud marketplaces. Adobe, Microsoft, and Alphabet anchor enterprise accounts through creative cloud install bases, Azure-embedded distribution, and advertising ecosystem integration respectively. Three strategic archetypes dominate: predictive module specialists commanding implementation fees, reporting tool incumbents defending recurring revenue through workflow entrenchment, and cross-platform attribution vendors collapsing iOS-Android-web measurement silos. Competitive moves concentrate on M&A to acquire privacy engineering talent and strategic partnerships to embed analytics within cloud marketplace channels.
Within the platform-anchored tier, Adobe Inc., Microsoft, and Alphabet Inc. occupy positions that exemplify distinct distribution strategies. Adobe leverages creative cloud install bases to cross-sell analytics modules through existing enterprise relationships. Microsoft anchors procurement consolidation through Azure-embedded tools that reduce vendor management overhead for centralized IT teams. Alphabet competes on real-time attribution depth across its advertising ecosystem, capturing measurement spend from retailers optimizing omnichannel conversion funnels. These three entities represent the dominant competitive anchors reshaping vendor addressable spend across the North American market.
| Leading Market Players |
|---|
| AppsFlyer Ltd. |
| Mixpanel |
| Adobe Inc. |
| Oracle |
| Microsoft |
| Alphabet Inc. |
| Branch Metrics, Inc. |
| Salesforce |
| Amplitude, Inc. |
| Others |
Pricing and Supply Chain Analysis
The Port of Los Angeles-Long Beach freight corridor absorbs container cost volatility that compresses margins for SDK vendors concentrated in California's San Francisco Bay Area, forcing price differentiation between cloud-native and on-premises deployment tiers while supply chain bottlenecks in semiconductor fabrication extend procurement timelines for telemetry processing hardware.
Pricing Analysis
Certification level creates the primary spread between HIPAA-compliant healthcare modules and standard retail analytics tiers. Subscription-based SaaS pricing dominates, with premium differentiation anchored in privacy-preserving architecture investments and real-time event throughput capacity. Pricing pressure intensifies as mid-market buyers migrate toward consolidated Azure-embedded procurement, eroding standalone vendor margins. Startups exhibit highest price sensitivity, while large enterprises absorbing multi-year master service agreements demonstrate lowest elasticity.
Supply Chain Analysis
Upstream semiconductor fabrication rests on Taiwan, South Korea, and United States foundry capacity for telemetry processing chipsets. Cloud infrastructure hardware draws from specialized server component suppliers, while SDK instrumentation depends on narrow-base telemetry capture vendors. Single-source vulnerability concentrates in advanced node semiconductor supply, exposing real-time pipeline vendors to fabrication allocation constraints. Distribution runs through hyperscaler cloud marketplaces rather than direct vendor negotiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America mobile analytics is recovering from a cyclical trough as FCC enforcement of granular consent architectures forces replacement spending across healthcare and retail verticals, compressing procurement timelines from historical five-year amortization schedules.
For Market Incumbents: Insulate recurring revenue streams by embedding reporting tools deeper into clinical workflow integrations for HIPAA-compliant healthcare deployments. Consolidate channel control through exclusive Azure marketplace listings to preempt procurement consolidation. Counter emerging predictive module specialists by accelerating R&D spend on anticipatory intelligence capabilities.
For New Entrants and Emerging Players: Pursue the underpenetrated HIPAA-certified healthcare vertical where incumbent workflow entrenchment remains weakest. Target medium enterprises in United States finance facing mainframe integration friction as the most penetrable segment. Lead with freemium SDK tier conversion funnels seeded through California's venture-backed startup cluster.
For Investors and Strategic Acquirers: CPRA enforcement and FCC data privacy framework evolution reshapes the acquisition landscape toward privacy engineering talent scarcity. Long-term viability favors platform-anchored vendors with cloud marketplace distribution lock-in over standalone point solutions. Monitor California attorney general consent enforcement intensity as the signal indicating replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Privacy Architecture Certification | HIPAA-compliant SDK modules capture healthcare replacement spending ahead of incumbent retooling. |
| Cloud Marketplace Embedding | Azure-integrated distribution rides Microsoft enterprise account expansion without direct sales investment. |
| Predictive Module Development | Anticipatory intelligence capabilities displace retrospective reporting in large enterprise procurement. |
| Cross-Platform Attribution Convergence | Unified iOS-Android-web telemetry collapses measurement silos for omnichannel retailers. |
| Stream-Native Pipeline Migration | Sub-second funnel visualization intercepts cart abandonment before batch-oriented competitors respond. |
Research Methodology
A spread of perspectives from mobile analytics product managers, healthcare compliance officers, retail digital transformation leads, and cloud procurement specialists converged on the working assumptions driving this analysis. Primary interviews with SDK vendors and enterprise IT architects combined with secondary validation against SEC filings, hyperscaler capex disclosures, and App Annie mobile intelligence data. Bottom-up telemetry volume estimates and top-down enterprise software spend allocation were triangulated to constrain projection variance.
Demand-supply balance across deployment models, vertical applications, and enterprise scale tiers anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include cloud versus on-premises infrastructure, retail versus healthcare versus finance end-use, and predictive versus descriptive solution categories. CAGRs derived from replacement cycle compression analysis and compliance-driven procurement acceleration. Forecast inputs incorporated FCC regulatory enforcement timelines and California CPRA implementation intensity.
Sensitivities concentrate around FCC consent architecture mandate timing and healthcare HIPAA boundary interpretation shifts. Forecasts reflect assumptions on cloud migration velocity and mid-market buyer infrastructure self-provisioning limitations. Cross-checking against hyperscaler earnings call commentary on analytics attach rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Spend Analytics Software Market
Analytics
Weather Data Services Market
Analytics
Network Traffic Analytics Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Global Development Analytics Tools Market
Analytics
Latin America Big Data Analytics Market
Analytics
Greece ICT Market
Analytics
South Korea Contact Center Analytics Market
Analytics
North America Speech Analytics Market
Analytics
TV Analytics Solutions Market
Analytics
Sweden ICT Market
Analytics
Global in-Store Analytics Market
Analytics
Global Enterprise Performance Management Market
Analytics
Global Wi-Fi Analytics Market
Analytics
Customer Identity Graph Drift Monitoring Market
Analytics
Embedded Analytics Market