
 Data Analytics in Telecom Market | 2026-2036
Data Analytics in Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Data Analytics in Telecom Market Insights
Cloud infrastructure buildouts across North American hyperscale providers is realigning how telecom carriers procure analytics capabilities. Cisco Systems leverages its networking hardware footprint to embed analytics directly at the network edge. SAP SE anchors enterprise-grade data pipelines that integrate billing systems with real-time usage analytics.
Data analytics in telecom encompasses the collection, processing, and interpretation of subscriber, network, and operational data using statistical models and machine learning algorithms to optimize service delivery and revenue generation. These systems process petabyte-scale streaming data from cell towers, core networks, and customer touchpoints to enable automated decision-making with sub-second latency. Network Optimization applications command the largest share of deployment spending as carriers prioritize quality-of-service metrics during 5G densification. IoT Analytics represents the fastest-expanding technology segment, driven by connected device proliferation in smart city and industrial verticals.
The Federal Communications Commission shapes data governance requirements for US carriers handling consumer location and usage records. The EU AI Act imposes risk-classification frameworks on automated network management decisions, while GDPR mandates strict anonymization protocols for subscriber behavioral analytics. Stakeholders must weigh compliance investments against the latency penalties of privacy-preserving computation methods.
Market Dynamics
The convergence of 5G network densification and edge computing deployment is restructuring how telecom carriers architect analytics infrastructure, forcing wholesale reconfiguration of data processing topology from centralized clouds toward distributed intelligence nodes.
Growth Catalysts
- EU AI Act risk-classification frameworks:European carriers are accelerating investment in explainable machine learning pipelines to satisfy automated decision-making audit requirements, creating procurement pull for governance-embedded analytics platforms.
- Smart city IoT device proliferation:Municipal deployments of connected traffic, energy, and environmental sensors across India and Germany are generating petabyte-scale data streams that demand real-time telecom analytics processing.
- Privacy-preserving computation methods:Federated learning and differential privacy techniques enable subscriber behavioral analysis without raw data centralization, resolving GDPR anonymization mandates while preserving analytical utility.
Market Restraints
- Specialized data science talent scarcity:Shortages of engineers proficient in both telecommunications network architecture and machine learning operations constrain deployment velocity for advanced analytics programs.
- GPU and specialized silicon supply concentration:Dependence on Taiwan and South Korea for AI accelerator chips creates procurement bottlenecks and cost volatility for on-premise analytics infrastructure buildouts.
- Latency penalties of homomorphic encryption:Computational overhead from privacy-preserving cryptographic methods degrades real-time network optimization performance, limiting deployment scope for sensitive data workloads.
Strategic Opportunities
- Open RAN intelligent controller integration:Disaggregated radio access network architectures create insertion points for third-party analytics applications at the network edge, bypassing incumbent vendor lock-in.
- Industrial vertical predictive maintenance:Manufacturing and logistics sectors in the United States are contracting private 5G networks with embedded analytics for equipment failure prediction, opening high-margin service revenue streams.
- India's Production Linked Incentive scheme:Domestic manufacturing incentives for telecom equipment are attracting analytics software vendors to establish local development centers, reducing deployment friction for Indian carriers.
Industry Challenges
- Multi-vendor data pipeline integration:Carriers operating heterogeneous equipment from multiple suppliers face schema incompatibility and telemetry format fragmentation when consolidating analytics across network layers.
- Model drift in dynamic radio environments:Machine learning models trained on stable 4G traffic patterns degrade in accuracy as 5G millimeter-wave propagation characteristics introduce non-stationary signal behaviors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Analytics in Telecom Market |
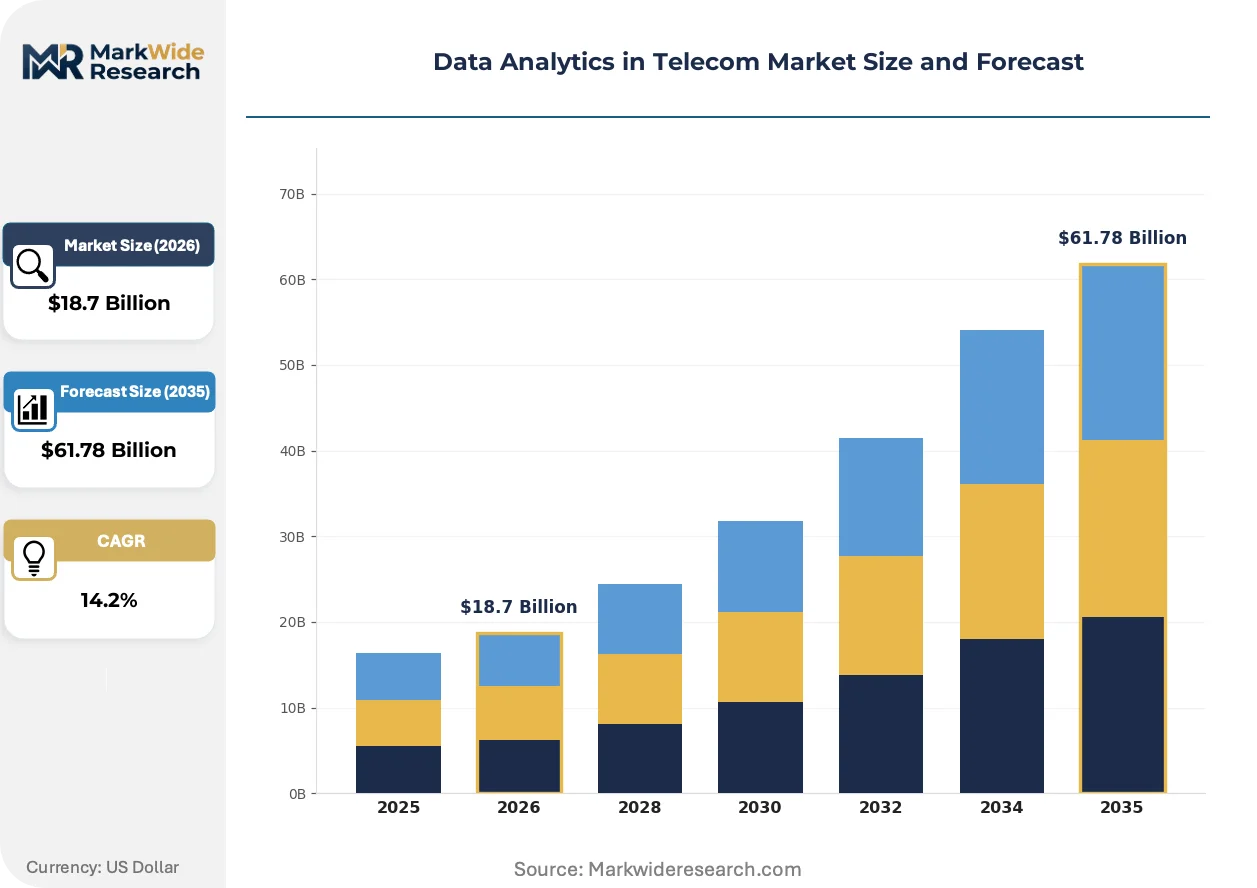
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Customer Experience Management, Network Optimization, Fraud Detection, Predictive Maintenance End User: Telecom Operators, Enterprises, Government Agencies, System Integrators Technology: Machine Learning, Big Data, Cloud Computing, IoT Analytics Service Type: Consulting, Managed Services, Software as a Service, Platform as a Service |
| Companies Covered | Cisco Systems, IBM Corporation, Oracle Corporation, SAP SE, Accenture, Microsoft Corporation, Huawei Technologies, Dell Technologies, Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Analytics in Telecom Market Trends and Innovations
Artificial intelligence is migrating from cloud data centers toward network edge nodes, compressing decision latency while complicating model governance across distributed infrastructure footprints.
Edge-native analytics software is modularizing network intelligence deployment, allowing carriers to slot machine learning inference engines into cell site routers and baseband units without forklift hardware upgrades. German operators are piloting containerized analytics microservices at 5G aggregation points to support industrial automation use cases. This architecture is modularizing vendor relationships, decoupling analytics procurement from radio hardware refresh cycles and enabling best-of-breed component selection.
The EU AI Act's risk-tiered compliance obligations are mandating human oversight interfaces for automated network management systems, forcing analytics vendors to retrofit explanation layers onto black-box optimization algorithms. Carriers operating cross-border infrastructure must maintain auditable decision trails for load-balancing and handoff algorithms. Equipment suppliers are responding by embedding model interpretability dashboards directly into network management platforms, prioritizing European deployment roadmaps to capture regulatory-driven replacement demand.
Enterprise buyers are unbundling analytics capabilities from bundled managed service contracts, preferring to license standalone network intelligence platforms and integrate them with existing business intelligence stacks. This disintermediation pressures traditional telecom vendors who historically packaged analytics as a value-add to connectivity services. The shift is most pronounced among Fortune 500 manufacturers in the United States deploying private 5G networks, where IT procurement teams demand API-accessible analytics rather than operator-managed reports.
Data Analytics in Telecom Market Segmentation
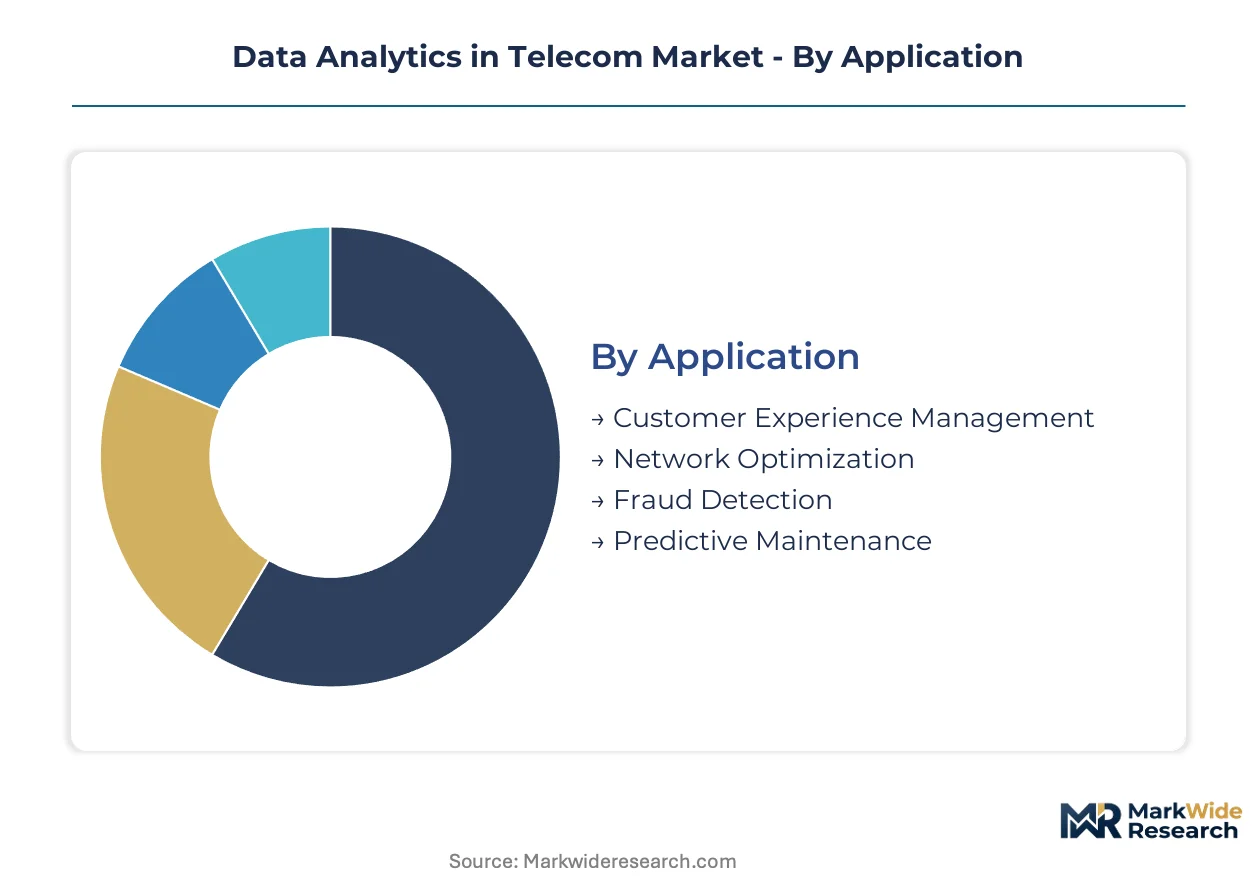
Telecom analytics deployments fragment across multiple technical and commercial axes, each commanding distinct procurement patterns and integration architectures. Understanding these segment boundaries clarifies where infrastructure investments concentrate and which capability layers drive pricing differentiation.
Application:
Technical specification of the analytics workload determines latency requirements, data sovereignty constraints, and integration complexity with legacy network management systems.
- Customer Experience Management:Real-time sentiment analysis and subscriber journey mapping platforms process call detail records, app usage telemetry, and support interaction logs to predict churn propensity. German carriers prioritize these investments to satisfy EU AI Act audit requirements for automated retention offers.
- Network Optimization:Millimeter-wave propagation modeling and dynamic spectrum allocation algorithms minimize handoff failures during 5G densification. United States carriers dominate procurement here as FCC coverage mandates intensify quality-of-service scrutiny.
- Fraud Detection:Anomaly detection systems flag SIM cloning, international revenue share fraud, and subscription identity theft through call pattern deviation analysis.
- Predictive Maintenance:Equipment failure forecasting for base stations and core network elements reduces mean-time-to-repair through vibration, thermal, and power consumption telemetry.
Network Optimization leads on scale; Customer Experience Management leads on momentum.
End User:
Procurement authority and technical sophistication vary sharply across buyer categories, shaping contract structures from perpetual licenses to consumption-based SaaS.
- Telecom Operators:Tier-1 carriers with petabyte-scale data estates deploy hybrid cloud architectures balancing on-premise inference latency with elastic training capacity. Indian operators accelerate spending under TRAI quality-of-service regulations and PLI scheme infrastructure incentives.
- Enterprises:Manufacturing and logistics firms contracting private 5G networks demand edge-native analytics with direct API integration into existing ERP and MES systems.
- Government Agencies:National security and emergency services deployments emphasize sovereign data residency and certified encryption for location intelligence.
- System Integrators:Multi-vendor consolidation specialists aggregate telemetry from heterogeneous equipment suppliers into unified analytics pipelines.
Telecom Operators anchor procurement volume; Enterprises expand most quickly.
Technology:
Computational approach dictates hardware requirements, model governance overhead, and talent acquisition strategies.
- Machine Learning:Supervised and reinforcement learning pipelines optimize radio resource allocation, with German operators piloting explainable architectures for EU AI Act compliance.
- Big Data:Distributed processing frameworks handle subscriber-scale record ingestion, with United States hyperscalers dominating managed cluster provisioning.
- Cloud Computing:Elastic infrastructure abstracts analytics deployment from physical data center constraints, accelerating procurement for mid-tier carriers.
- IoT Analytics:Sensor fusion and time-series forecasting for connected device fleets, climbing fastest as smart city deployments multiply across India and Germany.
Big Data commands installed base; IoT Analytics gains share fastest.
Service Type:
Delivery model selection reflects internal capability maturity and capital allocation preferences between OpEx and CapEx.
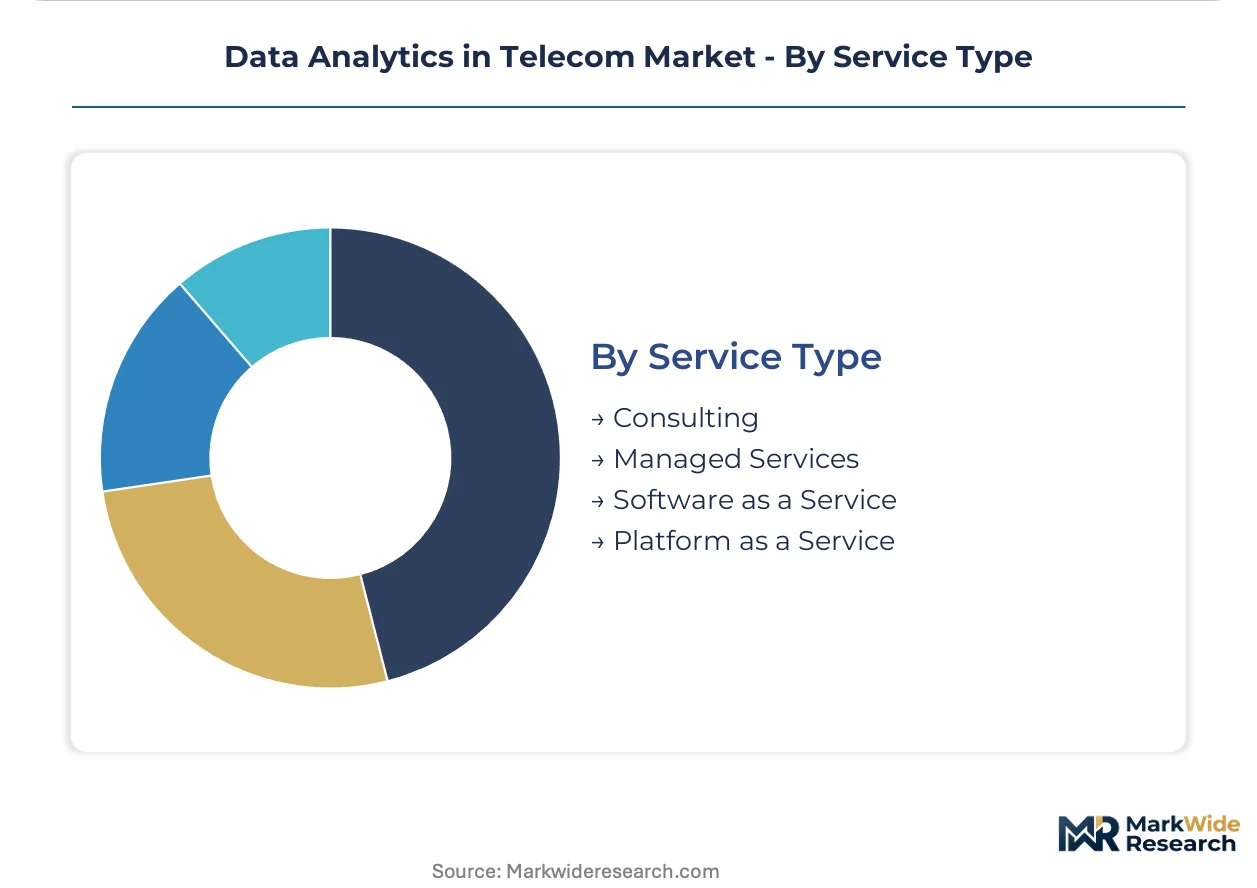
- Consulting:Strategy and implementation services for analytics transformation programs, concentrated among legacy operators modernizing from siloed BI systems.
- Managed Services:Outsourced platform operation and model maintenance, preferred by carriers addressing data science talent scarcity through vendor specialization.
- Software as a Service:Pre-configured analytics applications with standardized KPI dashboards, expanding through low-code customization interfaces.
- Platform as a Service:Development environments for carrier-specific model training, climbing fastest as Open RAN disaggregation enables third-party algorithm deployment at network edge.
Managed Services dominate current spending; Platform as a Service shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting analytics infrastructure investment toward jurisdictions with clearer AI governance frameworks, as carriers weigh compliance certainty against deployment velocity. The United States, Germany, and India concentrate procurement activity, each offering distinct risk-reward profiles for platform vendors.
United States
FCC coverage mandates and private 5G network deployments by Fortune 500 manufacturers drive demand for edge-native analytics. The Commission's data governance requirements for consumer location records shape platform architecture decisions. Greater Boston and the Pacific Northwest host clusters of analytics software development for telecom applications.
Germany
Industrial automation use cases and smart city sensor networks generate petabyte-scale processing requirements. The EU AI Act's risk-classification frameworks and GDPR anonymization mandates accelerate spending on explainable machine learning pipelines. The Ruhr industrial corridor and Bavaria's manufacturing belt concentrate pilot deployments of predictive maintenance analytics.
India
TRAI quality-of-service regulations and 5G core modernization programs expand carrier procurement budgets. The Production Linked Incentive scheme for domestic telecom equipment manufacturing attracts analytics vendors to establish local development centers. Maharashtra and Karnataka's technology corridors anchor software engineering capacity for the sector.
United Kingdom
Open RAN disaggregation initiatives and enterprise private network contracts create insertion points for third-party analytics applications. The Information Commissioner's Office enforces GDPR-aligned subscriber data protections. London's financial services cluster drives demand for fraud detection and real-time billing analytics integration.
South Korea
AI accelerator chip supply concentration and hyperscale cloud infrastructure investments position the country as a hardware procurement hub. The Ministry of Science and ICT promotes national AI competitiveness through R&D subsidies. Seoul's metropolitan area concentrates systems integration expertise for analytics platform deployment.
Data Analytics in Telecom Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-native specialization and API-first delivery models. The vendor base stratifies across three tiers: networking hardware incumbents embedding analytics at infrastructure layers, enterprise software houses anchoring billing-integration pipelines, and cloud hyperscalers abstracting elastic compute for mid-tier carriers. Strategic moves concentrate on M&A for data science talent acquisition and strategic partnerships with Open RAN disaggregation consortia.
Among networking-anchored vendors, Cisco Systems and Ericsson exemplify the hardware-embedded analytics archetype, leveraging radio access network footprints to deploy intelligence at cell site aggregation points. SAP SE occupies a position within the enterprise software tier, anchoring data pipelines that unify operational and customer-facing systems. IBM Corporation represents the services-integrated model, combining platform technology with consulting capacity for carrier transformation programs.
| Leading Market Players |
|---|
| Cisco Systems |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Accenture |
| Microsoft Corporation |
| Huawei Technologies |
| Dell Technologies |
| Ericsson |
| Others |
Pricing and Supply Chain Analysis
Edge-native analytics software modularization is compressing hardware refresh cycles while concentrating procurement leverage among carriers with multi-vendor Open RAN deployments. This shift simultaneously reduces CapEx barriers for mid-tier operators and amplifies pricing power for software vendors with containerized inference engines.
Pricing Analysis
Direct-to-carrier enterprise licensing commands the dominant channel margin layer, bypassing traditional systems integrator markups. Pricing stratifies across premium explainable-AI tiers for EU AI Act compliance, standard subscription bundles for network optimization, and economy SaaS tiers for IoT analytics entry points. Cost compression in the standard tier is intensifying because hyperscale cloud providers are absorbing infrastructure overhead. Mid-tier Indian carriers exhibit the highest price sensitivity due to TRAI-mandated quality-of-service investments draining discretionary budgets.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for GPU and AI accelerator silicon, constraining on-premise analytics infrastructure buildouts. The supply chain draws from United States hyperscalers for elastic cloud capacity, German industrial automation firms for edge hardware, and Indian software development centers for analytics engineering talent. Tariff exposure on semiconductor imports threatens deployment timelines for carriers pursuing sovereign data residency. Distribution runs through direct vendor-carrier relationships and systems integrator consolidation for multi-vendor telemetry aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through privacy-preserving computation premiums as GDPR and EU AI Act compliance costs get passed through to carrier buyers.
For Market Incumbents: Extend explainable machine learning capabilities into network management platforms to capture EU AI Act-driven replacement demand. Anchor data pipeline integration with SAP and Oracle billing systems to deepen switching costs. Address emerging entrant pressure from API-first analytics startups by embedding governance dashboards directly into existing carrier workflows. For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for audit-ready analytics platforms targeting industrial automation use cases. Private 5G network deployments by Fortune 500 manufacturers in the United States represent the most penetrable white space. Pursue a platform-as-a-service go-to-market angle with low-code customization interfaces to bypass incumbent managed service bundling. For Investors and Strategic Acquirers: Valuations sit cheapest among edge-native software specialists with Open RAN controller integration capabilities. The five-to-ten year viability story rests on 5G densification sustaining analytics infrastructure refresh cycles. Watch for TRAI enforcement actions in India as an inflection signal for quality-of-service regulation spreading to other emerging markets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies billing systems with real-time usage analytics for German carriers facing GDPR audits. |
| Acquisition of Specialist Firm | Addresses data science talent scarcity constraining machine learning operations deployment velocity. |
| Geographic Expansion | Establishes local development centers in India under PLI scheme incentives for telecom equipment. |
| Strategic Partnership | Creates insertion points for third-party analytics at Open RAN intelligent controllers bypassing vendor lock-in. |
| Product Launch | Deploys containerized microservices at 5G aggregation points for industrial automation in Bavaria. |
Research Methodology
Direct dialogue with network operations executives, data science leads at tier-1 carriers, Open RAN consortium technical directors, and TRAI regulatory officers grounded the qualitative assessment. Secondary validation drew from FCC coverage mandate filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and TRAI quality-of-service enforcement records. Bottom-up carrier spending estimates and top-down vendor revenue analysis were triangulated to anchor market sizing.
Bottom-up modeling segmented deployments by application workload, end-user procurement authority, computational approach, and delivery model across the analysis window. CAGRs were derived from carrier infrastructure budget trajectories, 5G densification timelines, and regulatory compliance investment schedules. The forecast framework incorporated Open RAN disaggregation pace, privacy-preserving computation adoption curves, and industrial vertical private network contract velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under GPU supply disruption scenarios or EU AI Act enforcement acceleration. The analysis assumes sustained carrier differentiation pressure from streaming video quality metrics and IoT device density requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global User and Entity Behavior Analytics Market
Analytics
Social Business Intelligence Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
Japan Geospatial Analytics Market
Analytics
Emotion Analytics Market
Analytics
India Contact Center Analytics Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Network Analytics Services Market
Analytics
Content Analytics and Discovery Software Market
Analytics
Contact Center Analytics Market
Analytics
Middle East Geospatial Analytics Market
Analytics
Europe Mobile Analytics Market
Analytics
Europe Big Data and Business Analytics Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Asia-Pacific Crowd Analytics Market
Analytics
UAE Geospatial Analytics Market