
 Global AI Video Analytics Market | 2026-2036
Global AI Video Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI Video Analytics Market Foresight
Edge silicon is recalibrating total cost of ownership for AI video analytics deployments, displacing centralized GPU clusters with on-device inference engines. Robert Bosch GmbH leverages its sensor manufacturing depth to anchor hardware-software bundles in European security markets. Cisco Systems, Inc. competes through network-integrated video platforms that extend enterprise IT infrastructure into physical security domains. Genetec Inc. specializes in open-architecture video management systems that navigate multi-vendor interoperability requirements across government and transportation verticals.
AI video analytics encompasses computer vision algorithms that process streaming video to detect objects, classify behaviors, and generate actionable metadata without continuous human monitoring, typically operating at latencies below 150 milliseconds for real-time alerting. The technology serves industrial and commercial purposes ranging from automated perimeter security to queue management and anomaly detection in critical infrastructure. Cloud-based deployment leads in new contract value among mid-sized enterprises seeking elastic compute for seasonal surveillance loads, while edge computing represents the fastest-expanding architecture as municipalities deploy battery-backed street-level inference nodes. Behavior analysis solutions command premium pricing in retail analytics, whereas license plate recognition has matured into a commoditized function bundled within broader platform subscriptions.
The EU AI Act imposes conformity assessments on biometric identification systems, restricting real-time facial recognition in public spaces and redirecting vendor R&D toward pseudonymized crowd analytics. FDA guidelines for AI-enabled medical monitoring devices and China's GB standards for intelligent video surveillance collectively shape product roadmaps across export-oriented manufacturers. NHTSA protocols for driver behavior cameras in commercial fleets add another compliance layer for transportation sector suppliers. Stakeholders must monitor divergence between permissive and restrictive regulatory blocs when allocating localization engineering resources across product lines.
Market Dynamics
Edge inference silicon is compressing latency requirements below 50 milliseconds for real-time threat detection, forcing a wholesale rearchitecture of video analytics stacks away from centralized cloud processing toward distributed compute nodes.
Growth Catalysts
- EU AI Act biometric restrictions:Pseudonymized crowd analytics systems gain regulatory preference over facial recognition, redirecting R&D investment toward privacy-preserving computer vision architectures.
- Smart city infrastructure mandates:Singapore's lamp-post-as-a-sensor deployments demonstrate scalable urban surveillance models that municipalities across Germany and Japan are replicating.
- Battery-backed edge nodes:Solar-powered inference hardware enables street-level deployment without grid connectivity, opening rural and remote perimeter security applications previously uneconomical.
Market Restraints
- GPU memory cost volatility:High-bandwidth memory shortages constrain on-device model complexity, limiting transformer-based architectures to cloud-only deployments.
- Foundry concentration in Taiwan:Advanced node semiconductor fabrication for AI accelerators rests with a single geography, exposing supply continuity to geopolitical friction.
- Interoperability protocol fragmentation:ONVIF, PSIA, and proprietary SDKs force redundant integration engineering, inflating deployment costs for multi-vendor environments.
Strategic Opportunities
- India smart city expansion:The country's urban infrastructure investment pipeline under its Smart Cities Mission creates demand for traffic management and public safety analytics without legacy system baggage.
- FDA medical monitoring pathways:AI-enabled patient fall detection and ICU monitoring devices open clinical video analytics as a regulated vertical with premium pricing power.
- 5G network slicing:Guaranteed bandwidth slices for video backhaul enable cloud-reliant analytics in locations previously requiring full edge autonomy.
Industry Challenges
- Embedded systems ML engineering scarcity:Talent capable of optimizing neural networks for ARM Cortex and RISC-V inference engines commands compensation premiums that mid-sized vendors struggle to match.
- EU conformity assessment timelines:Notified body backlogs for AI Act high-risk system certification extend product launch windows by 12-18 months.
- Retrofit integration complexity:Analog camera estates in industrial facilities require encoder middleware that degrades analytics accuracy, forcing rip-and-replace capex decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI Video Analytics Market |
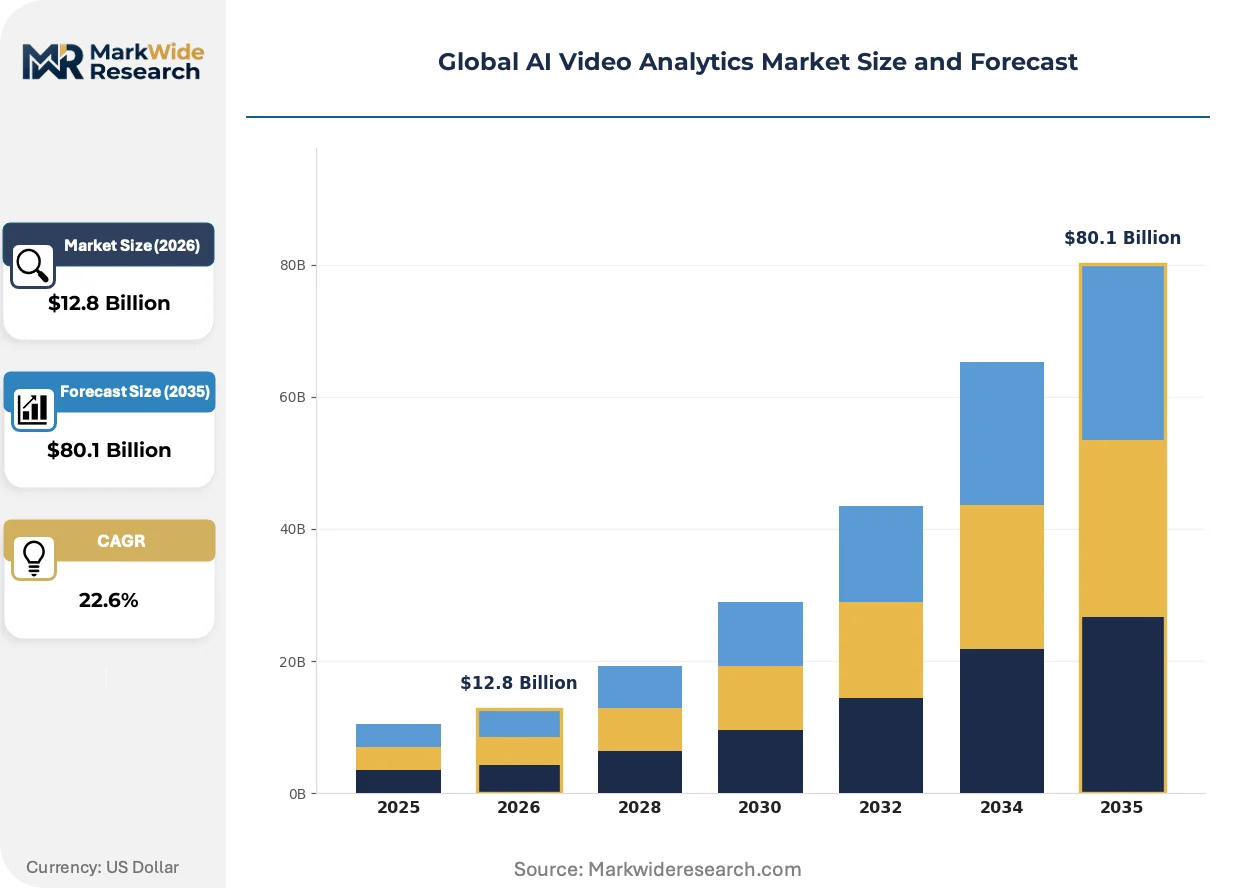
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $80.1 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution: Object Recognition, Behavior Analysis, Facial Recognition, License Plate Recognition, Crowd Analytics Use Case: Security Surveillance, Traffic Monitoring, Retail Analytics, Public Safety, Smart Cities End User Industry Vertical: Transportation, Government Offices, Educational Institutions, Hospitality, Manufacturing |
| Companies Covered | Robert Bosch GmbH, Cisco Systems, Inc., Motorola Solutions, Inc., AllGoVision Technologies Pvt. Ltd, Irisity AB, Honeywell International Inc., Axis Communications AB, Genetec Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI Video Analytics Market Shifts & Advancements
Transformer architectures are migrating from natural language processing into computer vision, enabling context-aware behavior prediction that rule-based systems cannot replicate. This shift demands new hardware-software co-design approaches.
Neural architecture search is absorbing engineering resources from manual model tuning, automating the optimization of detection networks for specific camera angles and lighting conditions. Retail loss prevention teams at large-format stores deploy these auto-generated models within weeks rather than quarters. The compression of model development cycles is absorbing margin from traditional computer vision consultancies.
China's GB standards for intelligent video surveillance mandate domestic encryption protocols and data residency, fragmenting product architectures for export-oriented manufacturers. Vendors serving both European and Chinese markets now maintain parallel firmware branches with divergent feature sets. The compliance burden falls heaviest on mid-tier suppliers lacking dedicated localization engineering teams.
Buyers in critical infrastructure verticals now require source code escrow and algorithmic audit rights before contract execution, shifting procurement from pure software licensing toward transparency-guaranteed partnerships. Water utilities and nuclear facilities in France and Canada pioneered these terms, which spread to transportation authorities. This contractual evolution rewards vendors with established security clearance frameworks and documented model training provenance.
Global AI Video Analytics Market Segmentation
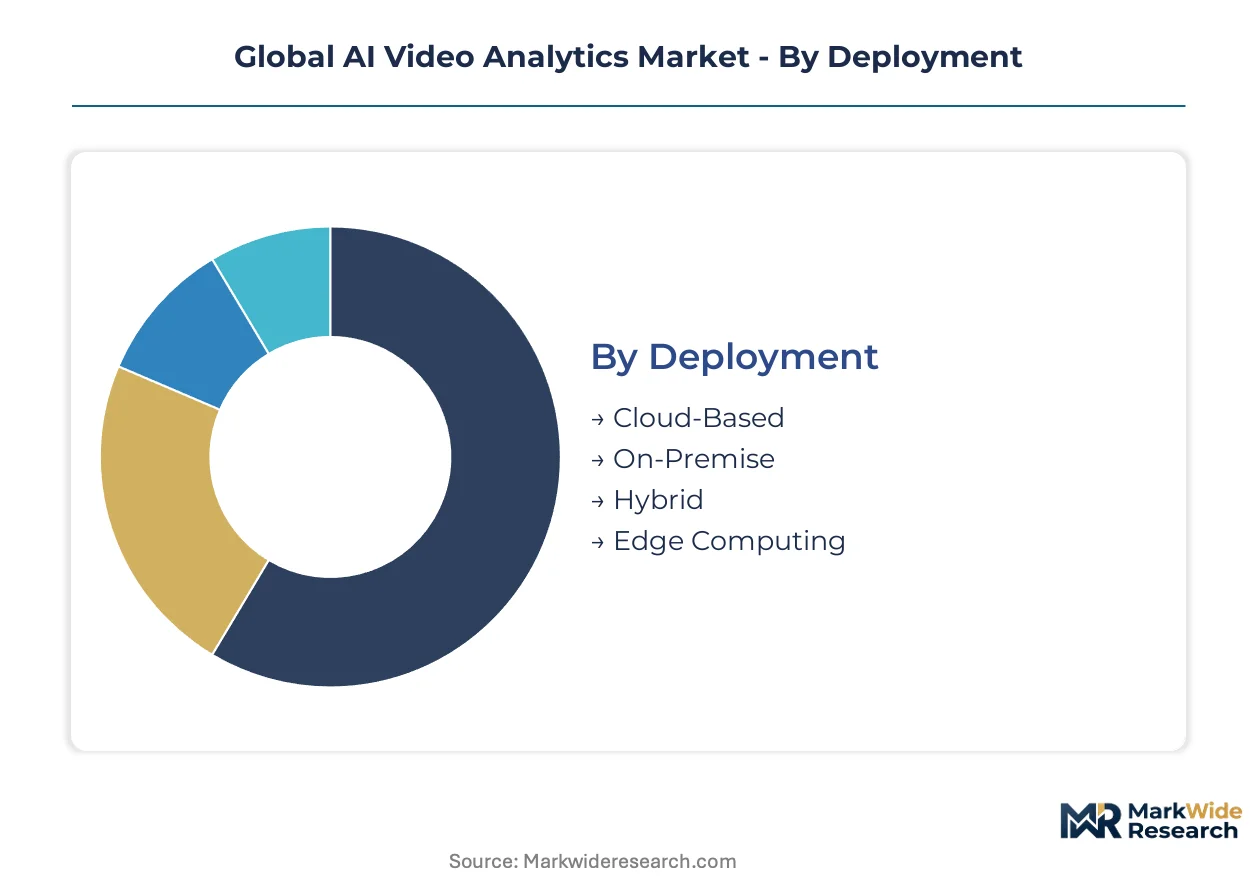
Deployment architecture and solution specialization determine procurement patterns across AI video analytics. Buyers prioritize latency requirements, data sovereignty constraints, and integration complexity when selecting segment combinations.
Deployment:
Standardization decreases from cloud toward edge, with customization intensity inversely tracking infrastructure control depth.
- Cloud-Based:Elastic compute pools handle burst surveillance workloads for seasonal retail peaks and event-driven security. Mid-sized enterprises in Germany and Japan favor this model for its elimination of on-site server maintenance. Demand concentrates among organizations lacking dedicated IT security staff.
- Edge Computing:On-device inference engines process video streams at sub-50 millisecond latencies for real-time threat response. Singapore's lamp-post-as-a-sensor deployments and rural perimeter security in Australia drive hardware orders for solar-powered, battery-backed nodes. GPU memory constraints limit model complexity.
- On-Premise:Air-gapped installations serve nuclear facilities and defense sites with classified video data. French and Canadian critical infrastructure operators mandate source code escrow for these deployments.
- Hybrid:Tiered processing routes metadata to cloud while retaining sensitive frames locally. Healthcare systems in the US use this architecture for HIPAA-compliant patient monitoring with remote diagnostic access.
Leading the category by volume: Cloud-Based. Expanding most quickly: Edge Computing.
Solution:
Functional maturity separates commodity modules from premium-priced behavioral intelligence layers.
- Behavior Analysis:Context-aware prediction engines detect anomalies in crowd flow and individual movement patterns that rule-based systems miss. Large-format retail chains in the US deploy auto-generated models for loss prevention, compressing development cycles from quarters to weeks. Transformer architectures demand new hardware-software co-design approaches.
- Object Recognition:Real-time classification of vehicles, weapons, and abandoned items underpins automated perimeter alerts. Traffic management authorities in India integrate these capabilities into Smart Cities Mission infrastructure without legacy encoder middleware.
- Facial Recognition:EU AI Act restrictions on biometric identification in public spaces redirect R&D toward consent-based access control. Conformity assessment backlogs extend product launches.
- License Plate Recognition:Mature optical character recognition functions now bundle into broader platform subscriptions rather than commanding standalone pricing. Parking enforcement and toll collection remain primary applications.
- Crowd Analytics:Pseudonymized density mapping and flow optimization gain regulatory preference over identifiable tracking. Stadium operators and transit hubs in Singapore deploy these systems for capacity management.
Highest margin concentration: Behavior Analysis. Steepest volume growth: Crowd Analytics.
Use Case:
Application urgency determines acceptable latency thresholds and corresponding infrastructure investment.
- Public Safety:Real-time alerting for active threats and emergency response coordination commands premium system integration. Urban deployments in Germany replicate Singapore's sensor-lamp-post models with EU AI Act-compliant pseudonymization.
- Smart Cities:Integrated traffic, environmental, and security sensor networks require open-architecture platforms navigating ONVIF and proprietary SDK fragmentation. Battery-backed edge nodes enable grid-independent rural coverage.
- Security Surveillance:Perimeter monitoring for critical infrastructure demands sub-50 millisecond inference for automated response triggering. Water utilities and nuclear facilities in France pioneered algorithmic audit rights in procurement contracts.
- Traffic Monitoring:Automated incident detection and signal optimization absorb municipal budgets across India's urban infrastructure pipeline. 5G network slicing now enables cloud-reliant analytics in previously edge-only locations.
- Retail Analytics:Queue management and customer flow analysis drive mid-market enterprise adoption of cloud-based seasonal scaling. Neural architecture search automates model tuning for specific store layouts.
Deployment value leader: Public Safety. Fastest policy tailwind: Smart Cities.
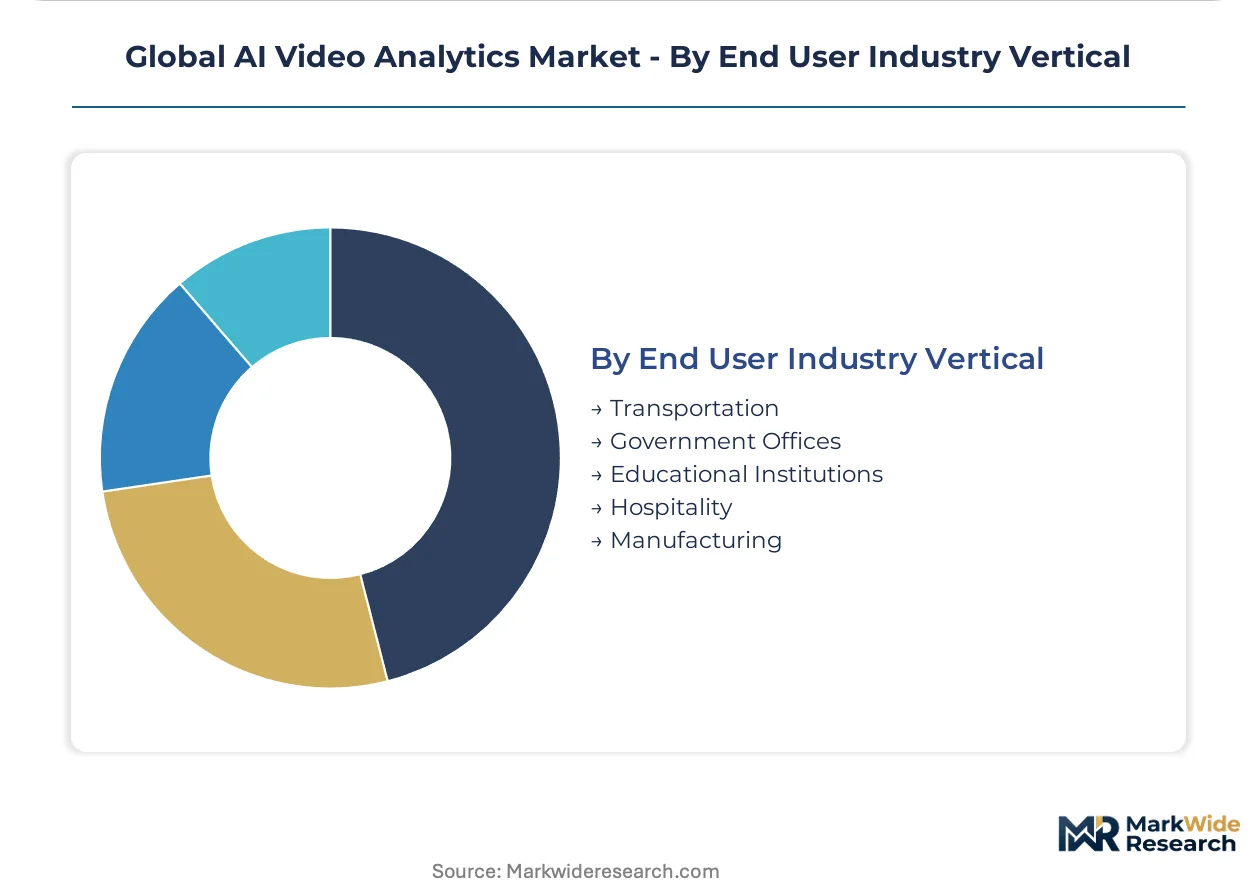
End User Industry Vertical:
Regulatory exposure and integration legacy shape procurement sophistication across verticals.
- Government Offices:Security clearance frameworks and documented model training provenance dominate vendor selection. EU conformity assessments for high-risk biometric systems extend procurement cycles.
- Transportation:NHTSA protocols for commercial fleet driver behavior cameras add compliance layers. Airports and rail operators require multi-vendor interoperability across legacy and new sensor estates.
- Manufacturing:Analog camera retrofit complexity forces rip-and-replace decisions where encoder middleware degrades analytics accuracy. Industrial facilities prioritize on-premise deployment for intellectual property protection.
- Educational Institutions:Campus safety mandates drive demand with constrained capital budgets favoring cloud-based subscription models. Privacy concerns limit facial recognition adoption.
- Hospitality:Guest experience optimization and loss prevention balance against brand reputation risks from visible surveillance. Casino operators lead in behavior analysis deployment for fraud detection.
Contract value concentration: Government Offices. Procurement velocity: Transportation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public safety procurement and smart city infrastructure investments concentrate demand across five distinct national markets, each shaped by divergent regulatory postures toward biometric surveillance and edge computing deployment.
United States
Federal transportation mandates and healthcare monitoring applications drive adoption, with NHTSA protocols governing commercial fleet driver behavior cameras and FDA pathways enabling AI-enabled patient fall detection devices. Cloud-based elastic compute serves mid-sized enterprises lacking dedicated IT security staff. Critical infrastructure operators in Texas and California pioneered algorithmic audit rights and source code escrow requirements in procurement contracts.
Germany
Industrial manufacturing facilities and municipal traffic authorities anchor demand, with EU AI Act conformity assessments redirecting vendor R&D toward pseudonymized crowd analytics over facial recognition. Smart city deployments replicate Singapore's sensor-lamp-post models with privacy-preserving architectures. The country's national data protection regulator enforces strict biometric processing limitations in public spaces.
Singapore
Lamp-post-as-a-sensor deployments demonstrate scalable urban surveillance models that municipalities across Asia-Pacific are replicating. Battery-backed edge nodes enable grid-independent rural coverage for perimeter security applications. The national smart city program concentrates procurement authority within the Land Transport Authority and Housing Development Board.
India
The Smart Cities Mission urban infrastructure investment pipeline creates demand for traffic management and public safety analytics without legacy system baggage. 5G network slicing now enables cloud-reliant analytics in locations previously requiring full edge autonomy. Municipal corporations in Maharashtra and Karnataka lead procurement for integrated traffic and security sensor networks.
China
GB standards for intelligent video surveillance mandate domestic encryption protocols and data residency, fragmenting product architectures for export-oriented manufacturers. Domestic demand concentrates in urban public safety and transportation verticals. Manufacturers serving both European and Chinese markets maintain parallel firmware branches with divergent feature sets.
Global AI Video Analytics Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to bridge hardware-software integration gaps and navigate multi-vendor interoperability requirements. The vendor base organizes into three tiers: diversified technology conglomerates with sensor manufacturing depth, network infrastructure specialists extending enterprise IT into physical security, and pure-play software vendors with open-architecture video management systems. Hardware-software bundling and cross-licensing agreements represent the primary competitive moves, with conformity assessment capabilities emerging as a differentiation factor for EU market access.
Within the diversified industrial tier, Robert Bosch GmbH and Honeywell International Inc. occupy positions anchored by sensor manufacturing heritage and security clearance frameworks. Among network-integrated platform providers, Cisco Systems, Inc. exemplifies the IT infrastructure extension archetype. Specialized software vendors include Genetec Inc., which represents the open-architecture interoperability camp navigating ONVIF and proprietary SDK fragmentation. These three archetypes collectively shape procurement patterns across government, transportation, and critical infrastructure verticals.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Cisco Systems, Inc. |
| Motorola Solutions, Inc. |
| AllGoVision Technologies Pvt. Ltd |
| Irisity AB |
| Honeywell International Inc. |
| Axis Communications AB |
| Genetec Inc. |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Embedded systems ML engineering talent concentration in Taiwan and South Korea feeds labor-cost differentials that separate premium-tier edge inference hardware from economy-tier cloud analytics subscriptions. The scarcity of engineers capable of optimizing neural networks for ARM Cortex and RISC-V inference engines commands compensation premiums that mid-sized vendors struggle to match, compressing margins in the standard tier while compliant incumbents defend pricing power.
Pricing Analysis
Volume concentrates in cloud-based subscription tiers while margins accrue to edge computing deployments with sub-50 millisecond latency guarantees. Pricing stratifies across premium certified tiers with EU AI Act conformity assessments, standard bundled platform offerings, and economy-tier license plate recognition modules commoditized into broader subscriptions. Cost compression in the economy tier stems from GPU memory shortages constraining on-device model complexity. Mid-sized enterprises lacking dedicated IT security staff exhibit highest price sensitivity, whereas French and Canadian critical infrastructure operators prioritize algorithmic audit rights over unit cost.
Supply Chain Analysis
Reverse-logistics flows for edge inference hardware refurbishment and remanufacturing center on Taiwan, South Korea, and the United States as primary collection and redistribution nodes. Advanced node semiconductor fabrication for AI accelerators rests with Taiwan, creating single-source vulnerability for foundry-dependent vendors. High-bandwidth memory and specialized image sensors constitute critical input dependencies. Distribution runs through authorized security integrators and direct enterprise IT procurement channels, with cloud-based analytics bypassing hardware logistics entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global AI Video Analytics Market operates as a cost-of-compliance story where EU AI Act conformity assessment backlogs create 12-18 month certification delays that function as barrier-to-entry moats for notified body relationships and documented model training provenance.
For Market Incumbents: Deepen open-architecture video management capabilities to navigate ONVIF and proprietary SDK fragmentation that inflates deployment costs for multi-vendor environments. Invest in dedicated localization engineering teams to maintain parallel firmware branches for GB standards compliance in China versus EU AI Act architectures. Certification investment represents the critical defensive lever against mid-tier suppliers lacking conformity assessment capabilities.
For New Entrants and Emerging Players: Transformer-based behavior prediction engines offer technology-first wedge positioning against rule-based incumbents in retail loss prevention and crowd analytics verticals. India's Smart Cities Mission urban infrastructure pipeline presents the most penetrable geography without legacy encoder middleware baggage. A channel partnership with established security integrators accelerates procurement access against direct enterprise sales requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with open-architecture software vendors possessing notified body relationships and algorithmic audit rights frameworks given EU AI Act enforcement acceleration. Long-term viability across the analysis window favors vendors with security clearance frameworks and documented model training provenance. Monitor notified body backlog clearance rates and EU member state biometric enforcement divergence as early inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment Investment | Notified body relationships compress product launch windows against 12-18 month competitor delays. |
| Edge Inference Hardware-Software Co-Design | Sub-50 millisecond latency guarantees command premium pricing in perimeter security applications. |
| Parallel Firmware Localization for GB Standards | Domestic encryption protocol compliance unlocks Chinese public safety procurement access. |
| Strategic Partnership with 5G Network Operators | Guaranteed bandwidth slices enable cloud-reliant analytics in previously edge-only locations. |
| Acquisition of Neural Architecture Search Specialist | Automated model tuning compresses retail loss prevention deployment cycles from quarters to weeks. |
Research Methodology
Independent corroboration across CTOs at mid-sized enterprises, IT procurement officers at German and Japanese organizations, platform engineers specializing in edge inference optimization, and integration specialists navigating ONVIF protocol fragmentation underwrites the qualitative findings. Secondary validation draws from SEC filings of diversified technology conglomerates, hyperscaler capex disclosures for cloud infrastructure expansion, EU AI Act implementation guidance documents, and FDA medical device submission databases. Bottom-up demand modeling across deployment architectures and solution specializations triangulates against top-down market sizing from technology vendor revenue disclosures.
Comparable-period anchoring to historical cloud infrastructure investment cycles and smart city procurement waves establishes the forecast framework baseline across the projection horizon. Segmentation dimensions modeled include deployment architecture elasticity, solution functional maturity, use case latency requirements, and end-user regulatory exposure. CAGRs derive from installed base expansion rates and replacement cycle compression in edge computing. Industry-specific inputs incorporate GPU memory cost volatility trajectories and notified body certification throughput estimates.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan foundry operations, abrupt EU AI Act enforcement divergence across member states, and breakthrough transformer architecture efficiency gains that displace current hardware-software co-design assumptions. Practitioners should monitor high-bandwidth memory supply contract renegotiations and EU notified body capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Active Data Warehousing Market
Analytics
Data Mining Tools Market
Analytics
Global Mobile BI Market
Analytics
Text Analytics Market
Analytics
Global Data Fusion Market
Analytics
APAC Data Wrangling Market
Analytics
Europe Emotion Analytics Market
Analytics
Asia-Pacific Edge Analytics Market
Analytics
Europe Network and Location Analytics Market
Analytics
Procurement Analytics Market
Analytics
Big Data Analytics in BFSI Market
Analytics
Global Customer Analytics Market
Analytics
Learning Analytics Solution Market
Analytics
Human Resource Analytics Market
Analytics
Global E-Commerce Analytics Software Market
Analytics
Predictive and Prescriptive Analytics Market