
 App Analytics Tools Market | 2026-2036
App Analytics Tools Market Size, Share, and Industry Trends Forecast 2026-2036
App Analytics Tools Market Outlook
Enterprise buyer concentration is pivoting toward mid-market mobile publishers that previously relied on free-tier dashboards. AppsFlyer leverages its fraud-prevention stack to anchor enterprise accounts across gaming and fintech verticals. Mixpanel sustains R&D intensity in cohort-based visualization, competing for product teams that prioritize behavioral pathing over vanity metrics. Amplitude differentiates through warehouse-native architecture, positioning its platform for organizations with existing cloud data infrastructure.
App analytics tools comprise software platforms that capture, process, and visualize user interaction data across mobile and web applications through SDK instrumentation, event tagging, and session recording protocols. These systems enable product managers, marketers, and developers to measure retention funnels, attribution paths, and revenue events with granularity down to individual user journeys. Cloud-based deployment leads in absolute revenue as enterprises favor elastic compute for peak traffic periods, while in-app analytics represents the fastest-expanding product category as publishers demand real-time feature performance feedback. User behavior analytics commands premium pricing due to technical complexity in probabilistic identity resolution and cross-device stitching.
FCC guidelines on consumer data transparency and GDPR consent frameworks constrain how analytics vendors collect persistent identifiers, forcing SDK redesigns toward aggregated measurement models. India's TRAI data localization expectations and Brazil's LGPD alignment pressure vendors to region-segment data storage or risk exclusion from public-sector procurement. Stakeholders must evaluate whether their current stack architecture accommodates jurisdiction-specific data residency without fragmenting cross-border reporting fidelity.
Market Dynamics
Privacy-preserving measurement architectures are forcing analytics vendors to rebuild SDKs around aggregated attribution models, compressing addressable data fidelity while elevating demand for probabilistic identity resolution.
Growth Catalysts
- India's smartphone proliferation:Domestic app publishers scale analytics spending to capture 750 million mobile-first consumers. Product teams prioritize cohort-based retention tools over vanity dashboards.
- GDPR consent frameworks:European enforcement of granular opt-in requirements accelerates investment in privacy-compliant measurement stacks. Vendors redesign data pipelines to serve aggregated insights without persistent identifiers.
- Real-time feature experimentation:Mobile gaming studios drive platform subscriptions by demanding sub-second performance feedback loops. In-app analytics adoption outpaces batch-processed alternatives.
Market Restraints
- Cloud compute cost volatility:Elastic infrastructure pricing squeezes mid-market publisher margins during traffic spikes. Peak-load provisioning consumes disproportionate budget share.
- Identifier deprecation:Apple's ATT framework and Google's Privacy Sandbox erode deterministic attribution accuracy. Cross-platform measurement fidelity degrades without device-level tracking.
- Data residency fragmentation:India's TRAI localization mandates and Brazil's LGPD alignment force region-segmented storage architectures. Cross-border reporting consistency suffers under jurisdiction-specific silos.
Strategic Opportunities
- Warehouse-native architectures:Organizations with existing Snowflake or BigQuery infrastructure seek analytics platforms that query directly against cloud data lakes. Elimination of data duplication reduces total cost of ownership.
- Fraud-prevention bundling:Ad fraud detection capabilities anchor enterprise retention in high-CPM verticals. Gaming and fintech publishers pay premium pricing for integrated verification stacks.
- Behavioral pathing specialization:Product teams prioritize journey visualization tools that map probabilistic user flows across fragmented touchpoints. Technical complexity supports pricing power in this segment.
Industry Challenges
- Probabilistic identity resolution talent scarcity:Data science teams struggle to hire engineers skilled in cross-device stitching algorithms. Compensation inflation concentrates expertise at top-tier vendors.
- Legacy SDK integration friction:Enterprises maintaining decade-old application codebases face protracted instrumentation timelines. Parallel tracking systems operate during multi-quarter migration windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | App Analytics Tools Market |
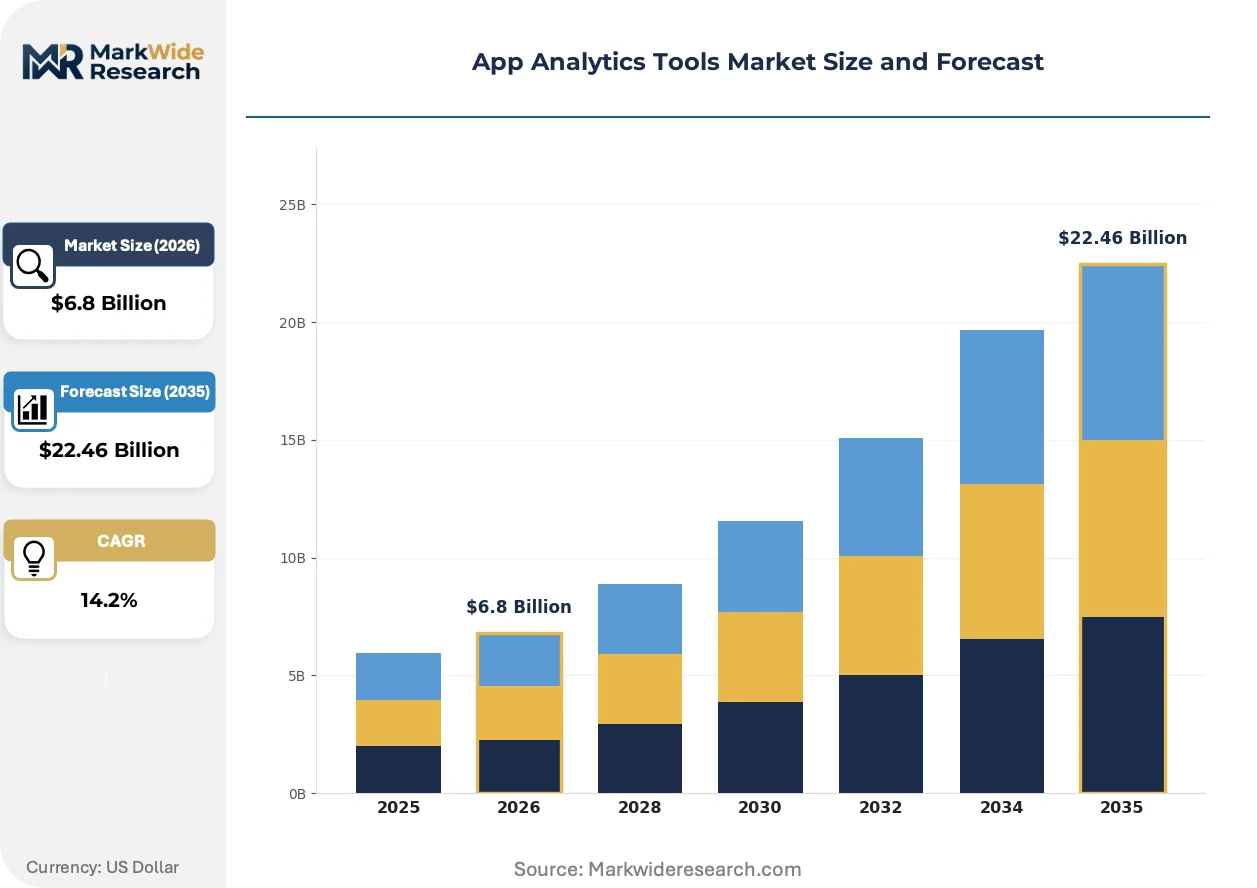
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Analytics, Web Analytics, In-App Analytics, User Behavior Analytics Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Retail, Entertainment, Finance, Healthcare Customer Type: Small Businesses, Enterprises, Startups, Developers |
| Companies Covered | AppsFlyer, Amplitude, Mixpanel, Google Analytics for Firebase, Adjust, Sensor Tower, UXCam, App Radar, Singular, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
App Analytics Tools Market Strategic Shifts
Measurement methodologies are fragmenting across privacy-compliant alternatives as deterministic tracking erodes, compressing attribution windows while expanding demand for contextual and cohort-based inference techniques.
Edge-based event processing is converging with on-device machine learning to enable real-time anomaly detection without raw data egress. Mobile publishers with stringent latency requirements adopt localized inference engines that surface aggregated behavioral signals. This architecture compresses time-to-insight from minutes to milliseconds while satisfying data minimization principles.
GDPR's enforcement arm in Ireland and Germany has intensified scrutiny of analytics vendors' lawful basis documentation for persistent identifier collection. Vendors face operational friction from mandatory Data Protection Impact Assessments prior to SDK deployment. Gaming studios with European user bases are most affected, accelerating migration toward consent-agnostic measurement models.
Mid-market publishers are consolidating vendor relationships around platforms offering bundled attribution, product analytics, and experimentation tooling. Standalone point solutions face displacement as procurement teams prioritize integration depth over feature specialization. This concentration is most visible in India's domestic app economy, where capital efficiency pressures favor consolidated stacks.
App Analytics Tools Market Segmentation
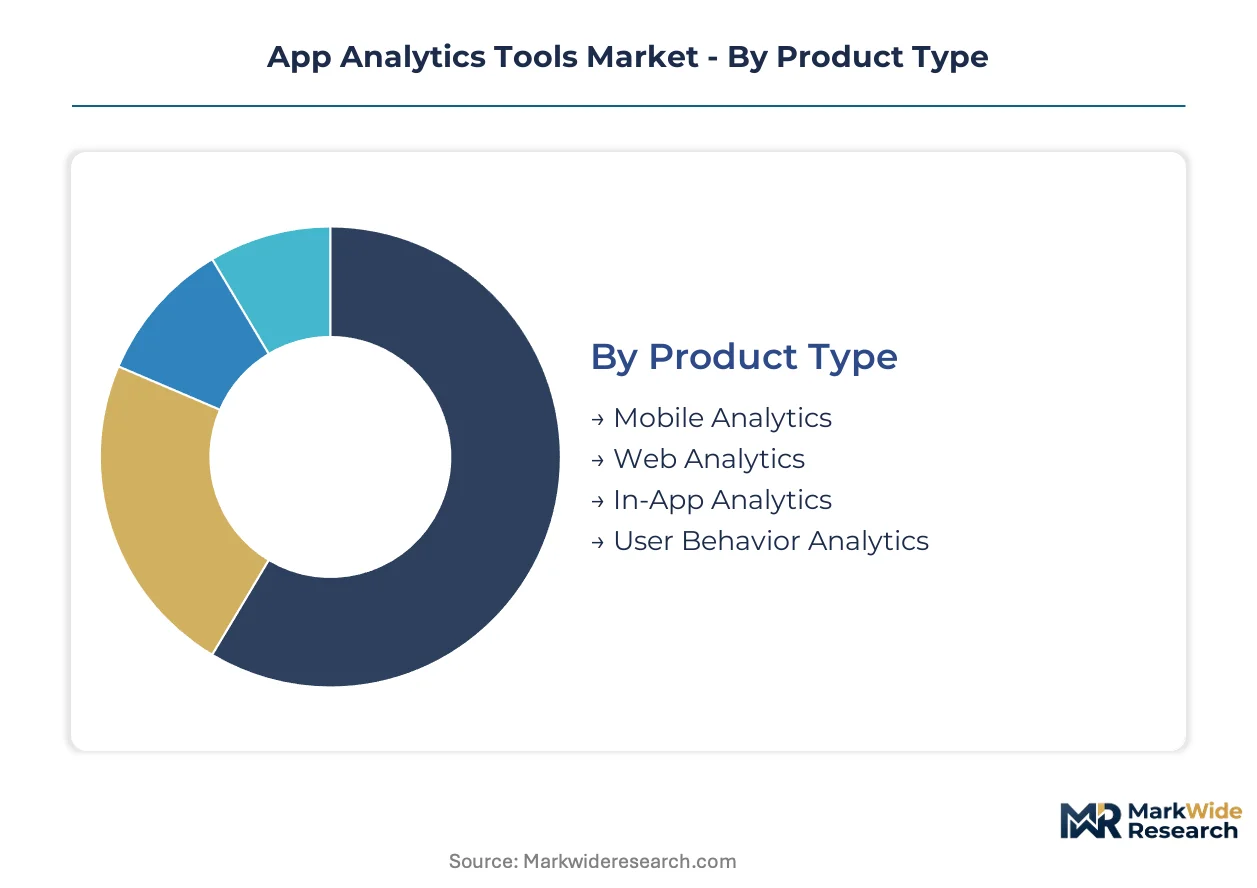
App analytics tools segment across multiple dimensions that determine integration complexity, data sovereignty requirements, and pricing architecture. Product teams select platforms based on whether they need standalone dashboards or embedded measurement systems feeding warehouse infrastructure.
Product Type:
Standalone analytics suites demand dedicated engineering resources for SDK instrumentation and maintenance, while embedded modules integrate within broader marketing or product stacks with lighter configuration overhead.
- Mobile Analytics:SDK-based measurement captures session duration, screen flows, and crash reports across iOS and Android environments. Gaming studios in India deploy these tools to optimize retention for 750 million smartphone users. Volume placements concentrate in mobile-first publishers; the faster expansion belongs to in-app analytics.
- In-App Analytics:Real-time event streaming enables sub-second feature performance feedback without external data egress. Publishers with stringent latency requirements favor localized inference engines that surface aggregated behavioral signals. Gaming verticals pay premium pricing for millisecond-level experimentation loops.
- Web Analytics:JavaScript tag-based measurement tracks page journeys, conversion funnels, and referrer attribution across browser environments.
- User Behavior Analytics:Probabilistic pathing maps fragmented user journeys across touchpoints with technical complexity supporting pricing power.
Mobile analytics holds the largest installed base; in-app analytics climbs the fastest as real-time experimentation demands intensify.
Deployment:
Cost tier separation distinguishes elastic consumption models from fixed-capital infrastructure commitments, with mid-market publishers particularly sensitive to traffic-spike provisioning economics.
- Cloud-Based:Elastic compute architectures scale automatically during traffic surges, though peak-load pricing squeezes publisher margins. Enterprises favor this model for seasonal campaign spikes. Finance and retail verticals dominate consumption.
- SaaS:Subscription pricing bundles maintenance, updates, and support into predictable operational expenditures. Startups and small businesses prioritize this model for capital efficiency. The segment gains share fastest among capital-constrained publishers.
- On-Premises:Dedicated hardware deployments satisfy stringent data residency mandates from India's TRAI and Brazil's LGPD.
- Hybrid:Split architectures process sensitive data locally while feeding anonymized aggregates to cloud analytics engines.
Cloud-based deployments command the greatest revenue volume; SaaS offerings expand most quickly among mid-market customer bases.
End User:
Application maturity and regulatory exposure shape vertical adoption patterns, with fraud-sensitive and privacy-regulated sectors driving premium platform selection.
- Entertainment:Mobile gaming studios demand granular retention metrics and real-time A/B testing infrastructure. GDPR consent frameworks in Ireland and Germany accelerate migration toward aggregated measurement models. This vertical anchors enterprise subscription growth.
- Finance:Fraud-prevention requirements and high-CPM customer acquisition costs justify premium pricing for integrated verification stacks. Fintech publishers prioritize bundled attribution and ad fraud detection capabilities.
- Retail:E-commerce applications track cart abandonment, purchase funnels, and lifetime value calculations.
- Healthcare:HIPAA compliance constraints limit data collection architectures to de-identified and aggregated measurement protocols.
Entertainment verticals generate the highest platform engagement; finance applications steepen fastest on fraud-prevention bundling demand.
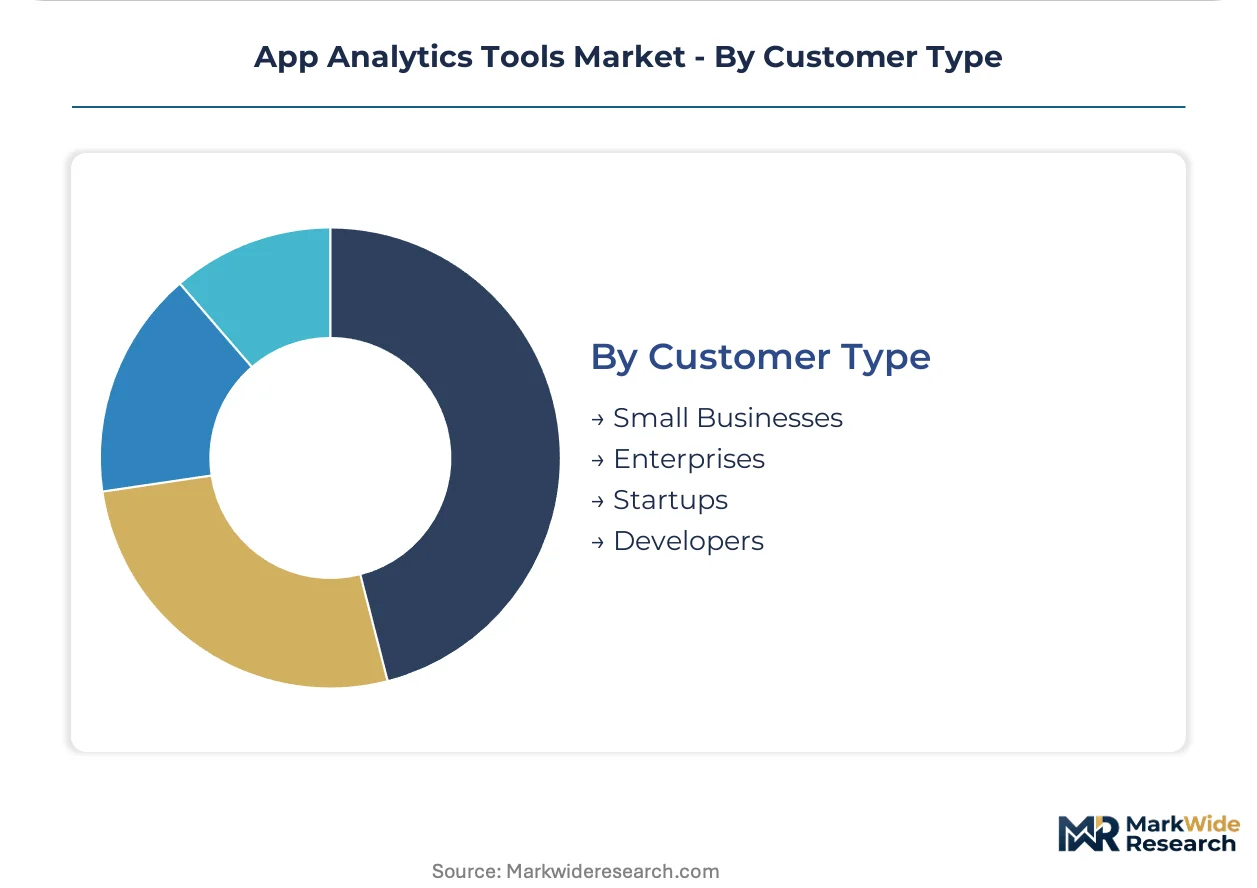
Customer Type:
Organizational scale determines whether buyers prioritize feature depth, integration flexibility, or self-service accessibility in procurement decisions.
- Enterprises:Existing Snowflake or BigQuery infrastructure drives demand for warehouse-native architectures that query directly against cloud data lakes. Procurement teams consolidate vendor relationships around bundled attribution, product analytics, and experimentation tooling.
- Developers:Technical users favor platforms with robust API access, raw data export capabilities, and customizable event schemas. This segment expands most quickly as engineering-led product teams gain analytics procurement authority.
- Small Businesses:Free-tier and low-cost dashboards satisfy basic vanity metrics without cohort-based retention analysis.
- Startups:Capital efficiency pressures favor consolidated stacks over standalone point solutions.
Enterprise accounts represent the deepest revenue concentration; developer-led procurement gains share fastest as technical teams control stack decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand acceleration as domestic app publishers scale analytics spending to capture smartphone-first consumers. Germany and Ireland anchor European regulatory enforcement. Brazil and the United States shape compliance architectures across the Americas.
United States
Mobile gaming studios and fintech publishers drive enterprise subscription growth for fraud-prevention bundled platforms. FCC guidelines on consumer data transparency constrain SDK designs toward aggregated measurement models. San Francisco Bay Area clusters anchor venture-backed analytics startups targeting mid-market consolidation.
Germany
GDPR enforcement from Hamburg and Munich regulators intensifies scrutiny of lawful basis documentation for persistent identifiers. Data Protection Impact Assessments now precede SDK deployments for gaming studios with European user bases. Berlin's product analytics ecosystem migrates toward consent-agnostic measurement architectures.
India
Domestic app publishers scale analytics spending to compete for 750 million mobile-first consumers across tier-2 and tier-3 cities. TRAI data localization expectations pressure vendors toward region-segmented storage or public-sector procurement exclusion. Bengaluru and Hyderabad clusters concentrate engineering talent for cohort-based retention tool development.
Brazil
LGPD alignment pressures analytics vendors to implement jurisdiction-specific data residency without fragmenting cross-border reporting fidelity. Local app publishers prioritize bundled attribution and experimentation tooling for capital efficiency. São Paulo anchors Latin American headquarters for warehouse-native platform providers.
Ireland
GDPR's lead supervisory authority intensifies operational friction for analytics vendors serving gaming verticals with European exposure. Consent framework enforcement accelerates investment in privacy-compliant measurement stacks. Dublin's cloud infrastructure clusters support region-segmented data lake architectures for mid-market publishers.
App Analytics Tools Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue warehouse-native specialization and fraud-prevention bundling. The vendor base stratifies across three maturity tiers: incumbents with decade-long SDK integration histories, mid-scale challengers competing on real-time experimentation velocity, and cloud-native entrants exploiting elastic infrastructure economics. Two dominant competitive moves reshape positioning: M&A activity consolidates standalone point solutions into bundled stacks, and strategic partnerships with cloud data warehouse providers accelerate warehouse-native adoption.
Within the attribution-specialist tier, AppsFlyer and Adjust exemplify platforms competing for fraud-sensitive verticals through integrated verification architectures. Amplitude occupies a position among warehouse-native providers targeting enterprises with existing Snowflake or BigQuery infrastructure. These three anchors represent divergent strategic bets: fraud-prevention bundling versus direct data lake querying versus behavioral pathing visualization.
| Leading Market Players |
|---|
| AppsFlyer |
| Amplitude |
| Mixpanel |
| Google Analytics for Firebase |
| Adjust |
| Sensor Tower |
| UXCam |
| App Radar |
| Singular |
| Others |
Value Chain & Pricing Dynamics
Aggregated attribution SDK architectures are compressing data fidelity while elevating engineering costs, simultaneously concentrating pricing power among vendors with probabilistic identity resolution capabilities and fragmenting procurement options for mid-market publishers. This technical transition forces buyers toward bundled stacks that amortize implementation complexity across multiple measurement functions.
Pricing Analysis
Volume placements concentrate in SaaS-tiered subscription models serving mobile-first publishers, while margin capture clusters in premium user behavior analytics tiers demanding cross-device stitching expertise. Price differentiation rests on latency performance and consent-agnostic measurement depth. Pricing pressure intensifies in the mid-market as elastic cloud compute costs during traffic spikes erode budget flexibility. Gaming studios prove least price-sensitive for real-time experimentation tooling; small app publishers exhibit highest sensitivity to per-event pricing increments.
Supply Chain Analysis
Regional distribution centers for SDK delivery and edge-processing infrastructure concentrate in the United States, Ireland, and India to satisfy data residency mandates. Raw material dependencies center on cloud compute capacity from hyperscalers, specialized data science talent pools, and open-source machine learning frameworks. Supply chain risk concentrates in single-source vulnerability for probabilistic identity resolution engineering expertise. Distribution runs through direct enterprise sales teams and cloud marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where scarce probabilistic identity resolution talent props pricing power for technical specialists. Capacity bottlenecks in cross-device stitching engineering prevent rapid competitive replication.
For Market Incumbents: Acquire specialized behavioral pathing engineering teams to deepen technical moats against warehouse-native challengers. Consolidate standalone point solutions into bundled attribution-analytics-experimentation stacks before mid-market procurement teams complete vendor rationalization. Prioritize fraud-prevention capability integration to anchor high-CPM verticals. For New Entrants and Emerging Players: Capture tier-2 and tier-3 city app publishers in India through localized cohort-based retention tooling priced below enterprise tiers. Target developer-led procurement authority with API-first architectures and raw data export capabilities. Pursue geographic expansion through TRAI-compliant data residency architectures. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by cloud data warehouse providers seeking native analytics capabilities. Long-term viability favors platforms with warehouse-native architectures that eliminate data duplication costs. Monitor Apple's ATT framework evolution and Google's Privacy Sandbox deployment as inflection signals for attribution-model disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Amplitude's warehouse-native querying against Snowflake infrastructure reduces total cost of ownership. |
| Acquisition of Specialist Firm | Fraud-detection capabilities anchor enterprise retention in gaming and fintech verticals. |
| Geographic Expansion | Region-segmented storage architectures satisfy India's TRAI localization mandates. |
| Product Launch | Edge-based event processing with on-device ML enables sub-second experimentation loops. |
| Strategic Partnership | Cloud data warehouse alliances accelerate warehouse-native adoption among enterprise buyers. |
Study Parameters
Independent corroboration across product analytics executives, mobile marketing leads, SDK engineering directors, and privacy compliance officers underwrites the qualitative findings. Primary interviews with CTOs at gaming studios and fintech publishers combined with secondary validation from SEC filings, App Annie/Sensor Tower mobile intelligence, hyperscaler capex disclosures, and GDPR enforcement documentation. Bottom-up sizing of SDK deployment volumes triangulates against top-down platform revenue estimates.
Comparable-period anchoring to historical mobile analytics adoption curves shaped the projection methodology across the analysis window. Segmentation dimensions modeled include deployment architecture, organization scale, vertical application, integration complexity, and regional regulatory cluster. CAGRs derive from elasticity-adjusted pricing trajectories and smartphone penetration saturation curves. Forecast inputs incorporate India's TRAI localization timeline and identifier deprecation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to probabilistic identity resolution talent availability and ATT framework evolution. Outputs reflect documented assumptions around consent framework enforcement intensity and cloud compute cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
IT Operation Analytics (ITOA) Market
Analytics
Sentiment Analytics Market
Analytics
North America Mobile Analytics Market
Analytics
Middle East Geospatial Analytics Market
Analytics
UK Video Analytics Market
Analytics
Cyprus ICT Market
Analytics
Germany Geospatial Analytics Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Human Resource Analytics Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
TV Analytics Solutions Market
Analytics
Cloud Performance Management Market
Analytics
APAC Retail Analytics Market
Analytics
Customer Data Platform Market
Analytics
India Geospatial Analytics Market
Analytics
Investigative Analytics Market