
 Global Big Data Analytics in Telecom Market | 2026-2036
Global Big Data Analytics in Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Global Big Data Analytics in Telecom Market Foresight
A widening capability gap between hyperscale cloud infrastructure and legacy on-premises data warehousing is reorganizing competitive dynamics across the telecom analytics landscape. Microsoft leverages its Azure cloud ecosystem to anchor large-scale network optimization deployments for tier-one carriers. Cisco Systems competes through specialized edge analytics hardware that sustains low-latency processing at cell tower sites. IBM differentiates via consulting-led implementations that navigate complex hybrid environments combining private data centers with public cloud bursts.
Big data analytics in telecom encompasses the collection, processing, and algorithmic analysis of petabyte-scale network traffic, subscriber usage patterns, and operational telemetry to generate actionable intelligence for service providers. These systems typically employ distributed computing frameworks such as Apache Spark and Kafka streams to process call detail records, signaling data, and IoT device metrics in near real-time, enabling automated capacity planning and fraud detection. Cloud-based deployment now leads solution delivery as mobile operators abandon capital-heavy on-premises installations, while network optimization commands the largest solution offering margin pool due to its direct impact on capital expenditure efficiency. Customer analytics represents the fastest-expanding solution segment as operators weaponize subscriber behavior data against aggressive virtual network operator competition.
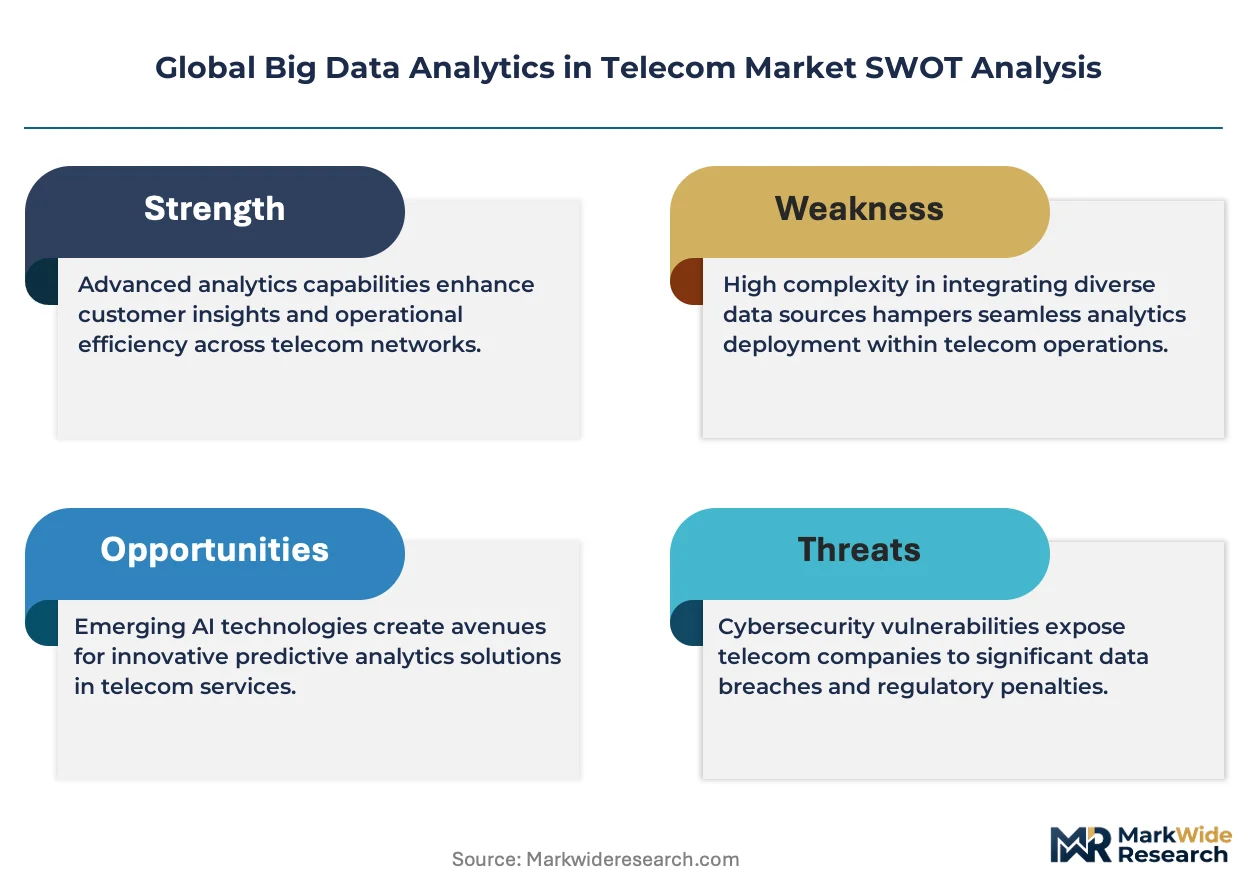
The FCC in the United States enforces data privacy and net neutrality provisions that constrain how carriers monetize subscriber analytics, while the EU AI Act imposes algorithmic transparency requirements on automated churn prediction and credit-scoring models deployed by European operators. India's TRAI mandates quality-of-service reporting that directly stimulates demand for real-time service quality monitoring dashboards among domestic carriers. Stakeholders must monitor evolving cross-border data localization rules that threaten the economics of centralized cloud analytics architectures serving multinational operator groups.
Market Dynamics
The migration from proprietary data warehouses to cloud-native analytics stacks is compressing deployment timelines from months to weeks while forcing carriers to retrain entire IT organizations on distributed computing paradigms.
Growth Catalysts
- EU AI Act compliance mandates:European operators must deploy algorithmic audit trails for automated credit-scoring and churn prediction systems, creating immediate procurement demand for explainable analytics platforms.
- India's NDCP implementation:TRAI-mandated quality-of-service reporting requires domestic carriers to invest in real-time network telemetry dashboards, accelerating edge analytics deployment across the subcontinent.
- Apache Spark streaming architectures:Petabyte-scale call detail record processing now operates at sub-second latency, enabling dynamic spectrum allocation that reduces capital expenditure on physical infrastructure expansion.
Market Restraints
- Cross-border data localization statutes:Multinational operator groups face fragmented sovereignty requirements that fragment cloud analytics economics and force redundant regional infrastructure builds.
- Specialized data engineering talent scarcity:Distributed systems expertise concentrates in Silicon Valley, Bangalore, and Tel Aviv, creating wage inflation that constrains mid-tier carrier adoption.
- Legacy mainframe integration debt:Decades-old billing and provisioning systems resist API-based connectivity, requiring expensive middleware layers that erode cloud migration return-on-investment calculations.
Strategic Opportunities
- Brazilian ANVISA-aligned health-telecom convergence:Remote patient monitoring partnerships between carriers and hospital networks create new revenue streams for IoT analytics in Latin America's largest market.
- 5G network slicing monetization:Guaranteed latency tiers for autonomous vehicle telemetry and industrial automation require predictive capacity algorithms that command premium pricing.
- Saudi SFDA medical device connectivity mandates:Regulatory requirements for continuous monitoring of implanted devices stimulate demand for ultra-reliable low-latency analytics pipelines.
Industry Challenges
- Real-time feature engineering expertise gap:Carriers struggle to hire data scientists capable of productionizing streaming machine learning models that adapt to network topology changes without manual retraining.
- Hybrid cloud orchestration complexity:Bursting analytics workloads between private data centers and public clouds requires sophisticated Kubernetes management that exceeds current telecommunications IT capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Big Data Analytics in Telecom Market |
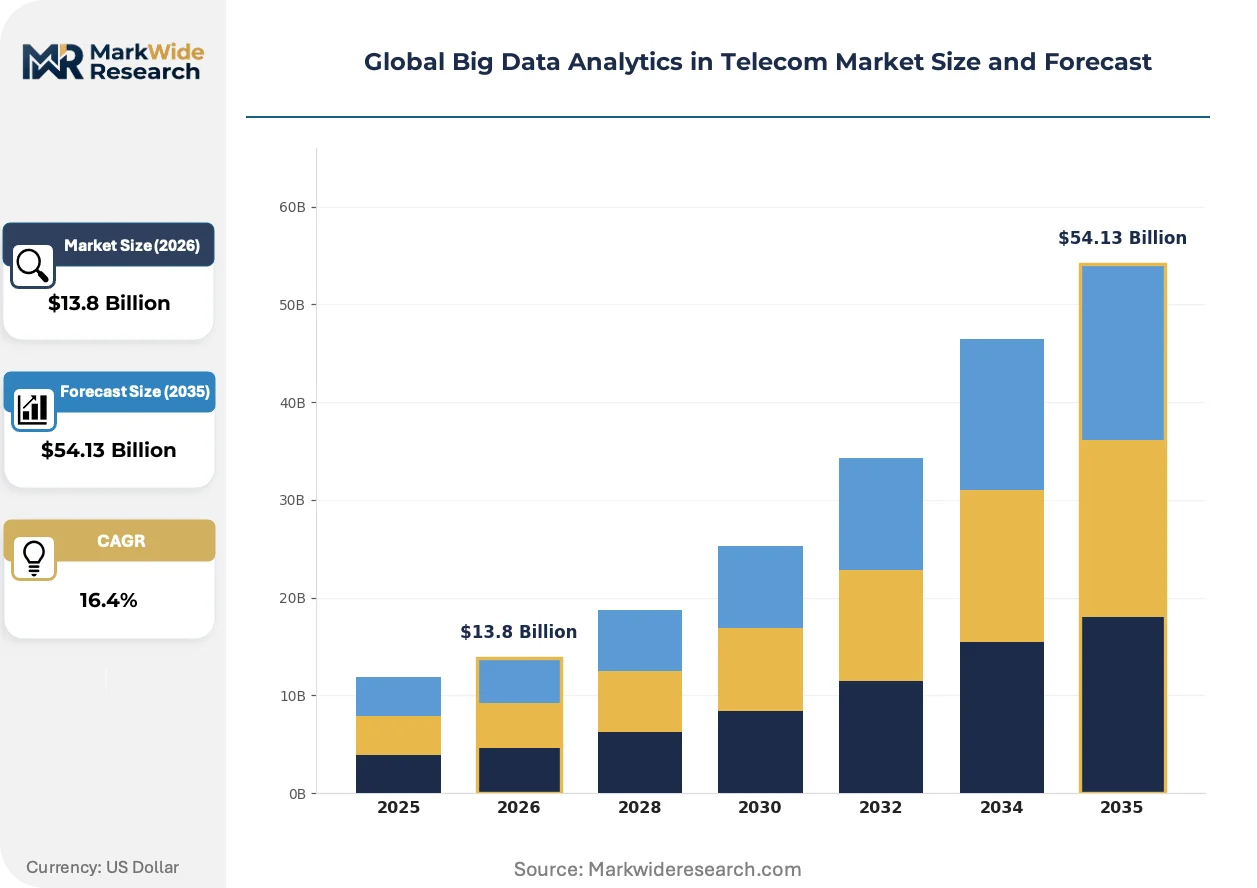
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $54.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution Offering: Customer Analytics, Fraud Detection, Network Optimization, Predictive Maintenance, Churn Management Use Case: Subscriber Behavior Analysis, Revenue Assurance, Capacity Planning, Service Quality Monitoring, Campaign Management End User: Mobile Network Operators, Internet Service Providers, Managed Service Providers, Virtual Network Operators |
| Companies Covered | Microsoft, Cisco Systems, Accenture, SAP, Dell EMC, IBM, Oracle, Intel, Amazon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Big Data Analytics in Telecom Market Shifts & Advancements
Telecom analytics infrastructure is bifurcating between hyperscale cloud deployments and specialized edge hardware, with each path demanding distinct engineering competencies and vendor relationships.
Federated learning architectures are fragmenting model training across distributed cell tower processors rather than centralizing subscriber data in regional cloud data centers. European operators under GDPR pressure adopt this approach most aggressively, trading model accuracy gains for regulatory risk reduction. The technique compresses backhaul bandwidth requirements while complicating version control across thousands of edge nodes.
The EU AI Act's algorithmic transparency requirements force carriers to document decision pathways for automated service termination and credit limit adjustments. German operators now maintain dedicated model governance teams that interface with both technical and legal functions. This regulatory friction slows deployment velocity but creates competitive differentiation for vendors offering built-in audit capabilities.
Subscription-based analytics procurement displaces perpetual license purchases as carriers prefer operational expenditure treatment for cloud-native tools. Tier-one operators in the United States negotiate consumption-based contracts with Microsoft Azure and Amazon Web Services that scale with subscriber growth. This shift compresses upfront vendor revenue recognition while extending customer lifetime value calculations across multi-year engagements.
Global Big Data Analytics in Telecom Market Segmentation
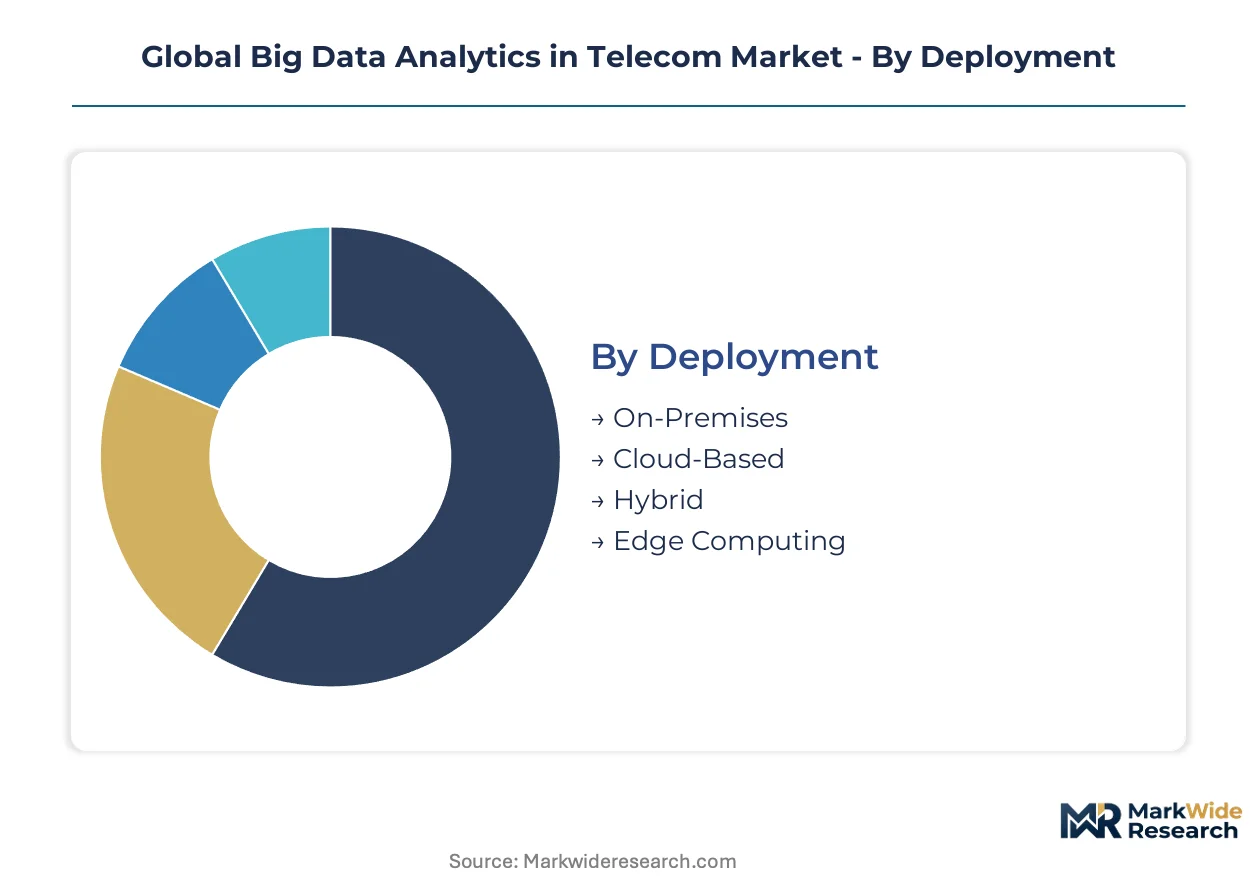
Telecom analytics procurement channels diverge sharply by deployment complexity and regulatory exposure. Carriers route cloud-native solutions through hyperscale marketplaces while reserving direct vendor relationships for edge hardware and hybrid orchestration layers.
Deployment:
Channel economics split between capital-intensive hardware procurement and consumption-based cloud subscriptions, with procurement teams negotiating distinct commercial terms for each pathway.
- Cloud-Based:Consumption models through AWS, Azure, and Google Cloud dominate tier-one carrier procurement, with TRAI-mandated dashboards in India accelerating multi-year commitments. Indian operators under NDCP pressure favor this route for rapid network telemetry deployment without data center construction.
- Edge Computing:Low-latency processing at cell tower sites requires specialized hardware partnerships with Cisco and Nokia, with 5G network slicing creating dedicated procurement verticals for autonomous vehicle and industrial automation use cases.
- Hybrid:Bursting architectures split sensitive subscriber data across private facilities and public cloud, demanding Kubernetes management capabilities that carriers acquire through systems integrator relationships.
- On-Premises:Legacy data warehouse retention persists among operators with strict data localization requirements in Russia and China, though maintenance costs erode competitive positioning.
By volume, Cloud-Based leads. By growth pace, Edge Computing is ahead.
Solution Offering:
Margin concentration follows capital expenditure impact, with network-facing solutions commanding premium pricing against customer-facing analytics competing on operational efficiency.
- Network Optimization:Spectrum allocation algorithms and dynamic capacity planning directly reduce infrastructure spend, with EU operators under AI Act pressure documenting automated decision pathways for regulatory audit trails.
- Customer Analytics:Subscriber behavior modeling targets virtual network operator competition through personalized pricing, with GDPR-constrained European carriers adopting federated learning to limit centralized data exposure.
- Churn Management:Predictive scoring for contract renewal risk integrates call center workflows and retention offer orchestration.
- Fraud Detection:Real-time signaling analysis flags SIM cloning and international revenue share fraud before billing completion.
- Predictive Maintenance:Base station equipment failure forecasting extends hardware lifecycles and reduces truck-roll dispatch costs.
Network Optimization captures the largest margin pool. Customer Analytics expands most quickly.
Use Case:
Implementation maturity varies by data pipeline readiness, with real-time applications requiring streaming infrastructure investments that batch-oriented use cases avoid.
- Service Quality Monitoring:TRAI-mandated quality-of-service dashboards in India drive immediate procurement, with sub-second latency requirements pushing processing toward edge architectures.
- Subscriber Behavior Analysis:Usage pattern clustering enables micro-segmentation for tariff design, with Brazilian operators leveraging this for health-telecom convergence partnerships under ANVISA guidelines.
- Revenue Assurance:Leakage detection across interconnect billing and roaming settlements protects margin in low-growth markets.
- Capacity Planning:Traffic forecasting models inform spectrum auction bidding and cell site densification timing.
- Campaign Management:Offer personalization engines integrate with CRM systems for contextual upsell triggers.
Service Quality Monitoring dominates current spend. Subscriber Behavior Analysis shows the steepest expansion trajectory.
End User:
Procurement sophistication scales with subscriber base and IT organizational maturity, creating tiered vendor engagement models from self-service platforms to embedded consulting teams.
- Mobile Network Operators:Tier-one carriers deploy full-stack analytics across network and customer domains, with Saudi operators responding to SFDA medical device connectivity mandates through ultra-reliable pipeline investments.
- Internet Service Providers:Fixed-line broadband providers prioritize churn prediction and congestion management for residential and enterprise segments.
- Virtual Network Operators:MVNOs without network infrastructure rely entirely on host operator data feeds and third-party customer analytics subscriptions.
- Managed Service Providers:MSPs aggregate analytics across multiple carrier clients, creating multi-tenant platforms with standardized reporting templates.
Mobile Network Operators anchor procurement volume. Virtual Network Operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom analytics consumption patterns diverge sharply across geographies. European operators prioritize algorithmic compliance infrastructure under regulatory pressure. Indian carriers emphasize rapid deployment of network telemetry dashboards. US tier-one providers concentrate on hybrid cloud orchestration capabilities.
United States
FCC net neutrality provisions and data privacy constraints shape how American carriers monetize subscriber analytics. Tier-one operators negotiate consumption-based contracts with hyperscale cloud providers. Seattle-based Microsoft anchors large-scale network optimization deployments through its Azure ecosystem.
Germany
EU AI Act mandates force German operators to maintain dedicated model governance teams for automated decision documentation. Algorithmic audit trail requirements create immediate procurement demand for explainable analytics platforms. Munich and Frankfurt clusters concentrate compliance-focused vendor relationships.
India
TRAI-mandated quality-of-service reporting under the National Digital Communications Policy accelerates real-time dashboard deployment. Domestic carriers favor cloud-based routes to avoid data center construction delays. Bangalore hosts concentrated data engineering talent pools serving regional operator demand.
Brazil
ANVISA-aligned health-telecom convergence creates new revenue streams for IoT analytics through remote patient monitoring partnerships. Carriers leverage subscriber behavior analysis for hospital network collaborations. São Paulo anchors Latin America's largest market for analytics-driven healthcare connectivity.
Saudi Arabia
SFDA medical device connectivity mandates stimulate demand for ultra-reliable low-latency analytics pipelines. Operators invest in predictive capacity algorithms for guaranteed latency tiers. Riyadh-based carriers respond with specialized edge infrastructure for continuous monitoring applications.
Global Big Data Analytics in Telecom Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in telecom analytics supply. Hyperscale cloud providers anchor consumption-based procurement through marketplace ecosystems. Edge hardware specialists sustain low-latency processing partnerships with infrastructure vendors. Consulting-led systems integrators navigate hybrid environments combining legacy and cloud-native stacks. Dominant competitive moves include strategic cloud marketplace alliances and edge computing capacity expansion.
Within the integrated cloud tier, Microsoft exemplifies hyperscale platform dominance through Azure-anchored carrier relationships. Cisco Systems occupies a position among edge hardware specialists with cell tower site processing capabilities. IBM sits within the consulting-led implementation archetype, serving complex hybrid deployments across multinational operator groups.
| Leading Market Players |
|---|
| Microsoft |
| Cisco Systems |
| Accenture |
| SAP |
| Dell EMC |
| IBM |
| Oracle |
| Intel |
| Amazon |
| Others |
Supply & Pricing Matrix
Cloud-native analytics stacks displacing legacy on-premises data warehousing simultaneously shift supply geography toward hyperscale cloud regions and compress pricing power for traditional hardware vendors. This substitution dynamic rewards carriers with consumption-based flexibility while eroding margin structures for perpetual-license software providers.
Pricing Analysis
Long-term consumption contracts with hyperscale cloud providers dominate tier-one carrier procurement, with AWS, Azure, and Google Cloud anchoring multi-year commitments. Three-tier pricing structure across premium, standard, and economy levels separates dedicated infrastructure from shared compute and burst capacity options. Pricing pressure stems from aggressive virtual network operator competition forcing operational efficiency mandates on host carriers. Mid-tier operators exhibit highest price sensitivity, while tier-one carriers prioritize capability breadth over unit cost.
Supply Chain Analysis
Inventory cycles for specialized edge hardware stretch twelve to eighteen months, constraining rapid deployment of low-latency cell tower analytics. Supply concentrates in the United States, Taiwan, and Ireland for cloud infrastructure, with India and Germany hosting concentrated data engineering talent pools. GPU and specialized AI accelerator dependencies create single-source vulnerability through NVIDIA's dominant position. Distribution runs through direct vendor relationships for edge hardware and hyperscale marketplaces for cloud-native solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's expansion is fundamentally constrained by scarce distributed systems expertise, with carriers competing for Apache Spark and Kubernetes specialists concentrated in Bangalore, Tel Aviv, and Silicon Valley clusters.
For Market Incumbents: Shield existing carrier relationships through embedded consulting teams that navigate hybrid cloud complexity, while acquiring specialist firms in edge analytics to counter Cisco's cell tower hardware dominance. Invest in EU AI Act compliance tooling to capture algorithmic audit trail procurement from European operators. For New Entrants and Emerging Players: GDPR-aligned federated learning certification fast-tracks unlock immediate access to European operators under algorithmic transparency pressure. Target Brazilian health-telecom convergence partnerships under ANVISA guidelines, where remote patient monitoring creates greenfield IoT analytics demand. Lead with consumption-based pricing to bypass incumbent perpetual-license lock-in. For Investors and Strategic Acquirers: The market sits at a cloud-migration acceleration phase that favors platforms with hybrid orchestration capabilities over pure-play cloud tools. Viability over the coming decade hinges on Kubernetes-native talent retention and edge-to-cloud workflow integration. Monitor TRAI enforcement intensity in India as inflection indicator for real-time dashboard demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Partnership | Cisco and Nokia hardware alliances enable sub-second latency for 5G network slicing applications. |
| Cloud Marketplace Integration | Azure and AWS marketplace presence accelerates procurement velocity for tier-one carrier IT organizations. |
| Regulatory Compliance Tooling | Built-in EU AI Act audit capabilities differentiate vendors serving German operator governance teams. |
| Federated Learning Deployment | GDPR-compliant model training at cell tower sites reduces backhaul costs for European carriers. |
| Talent Acquisition in India | Bangalore engineering hubs address Spark streaming expertise scarcity constraining mid-tier adoption. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs at tier-one mobile operators, data engineering leads at Indian carriers under NDCP pressure, procurement officers at European operators facing EU AI Act mandates, and edge infrastructure specialists at Cisco and Nokia. Secondary validation drew from TRAI quality-of-service reports, FCC net neutrality filings, hyperscaler capex disclosures, and EU regulatory implementation guidance. Bottom-up deployment estimates triangulated against top-down market sizing across cloud, edge, hybrid, and on-premises deployment pathways.
Across the analysis window, the forecasting framework modeled deployment mode, solution offering type, end-user sophistication tier, and geographic regulatory cluster as primary segmentation dimensions. CAGRs derived from trajectory analysis of historical cloud migration velocity and projected 5G network slicing deployment curves. Industry-specific inputs included Apache Spark adoption rates among Indian operators and EU AI Act compliance spending patterns among German carriers.
Decision-makers should treat outputs as directional under assumptions of sustained cloud migration momentum and stable cross-border data localization policy; material deviation in hyperscale pricing or regulatory enforcement intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Weather Data Services Market
Analytics
Workforce Analytics Market
Analytics
Big Data in Automotive Market
Analytics
United States Geospatial Analytics Market
Analytics
Application Analytics Market
Analytics
Personal Analytics Market
Analytics
Global Analytics Market
Analytics
Israel ICT Market
Analytics
Global Data Analysis Software Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
Europe Edge Analytics Market
Analytics
Human Resource Analytics Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Europe Crowd Analytics Market
Analytics
Business Intelligence (BI) Market
Analytics
Big Data Analytics in Manufacturing Market